
 US Terracotta Cladding Market | 2026-2036
US Terracotta Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
US Terracotta Cladding Market Intelligence
A preference for custom-glaze finishes and large-format panels is bifurcating the market between bespoke architectural solutions and standardized systems. Boston Valley Terracotta specializes in complex, custom projects for institutional and cultural buildings. In contrast, Terreal North America leverages its manufacturing scale to supply large-volume commercial developments. Shildan differentiates its offerings by providing complete engineered rainscreen systems.
US terracotta cladding refers to fired clay panels, typically extruded, that form the outer layer of a ventilated rainscreen facade. These systems manage moisture and improve thermal performance for the building envelope. New construction within the commercial and institutional end-user segments drives the majority of volume. Renovation and retrofitting applications represent the fastest-growing installation type as owners upgrade building exteriors for efficiency.
Product performance is governed by ASTM International standards, while local building codes in states like California and Florida dictate seismic and wind-load resistance. OSHA regulations further shape installation practices by mandating specific site safety protocols for facade work. Supplier selection will increasingly hinge on providing system-level warranties and verified performance data tailored to specific US climate zones.
Market Dynamics
The US terracotta cladding market is shaped by the convergence of stringent state-level energy codes and architectural demand for sustainable, yet aesthetically unique building envelopes. This dynamic pushes manufacturers to balance performance compliance with design flexibility.
Growth Catalysts
- Building Energy Codes:Stricter thermal performance mandates in states like California and New York are driving specification of ventilated rainscreen facades, a primary application for terracotta cladding.
- Institutional Construction:Universities, museums, and public buildings are specifying terracotta for its longevity, low maintenance, and ability to create a signature architectural identity, sustaining demand for custom products.
- Manufacturing Advances:Improved extrusion and firing techniques enable the production of larger format panels and complex three-dimensional shapes, expanding the material's design potential for architects.
Market Restraints
- High Upfront Cost:The total installed cost for a terracotta rainscreen system, including specialized labor and substructure, is significantly higher than for materials like metal panels or EIFS.
- Long Lead Times:Custom glaze development and production, particularly for materials sourced from European factories, can create long project lead times, conflicting with compressed construction schedules in the US.
- Structural Weight:The inherent weight of terracotta panels requires more robust and costly structural engineering for the building frame and support systems compared to lighter cladding materials.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in mid-rise commercial and mixed-use projects in growing metropolitan areas across the Southeast and Texas, beyond the established high-rise markets.
- Building Retrofit:The renovation segment offers a major growth avenue as building owners reclad aging office towers to improve energy efficiency and modernize aesthetics to attract tenants.
- Federal Incentives:Provisions within the Inflation Reduction Act (IRA) supporting deep energy retrofits for commercial buildings could create a strong tailwind for high-performance facade systems like terracotta rainscreens.
Industry Challenges
- Skilled Labor Scarcity:A shortage of trained and certified installers specializing in terracotta rainscreen systems can lead to installation errors, project delays, and increased liability for contractors.
- Code Compliance Complexity:Navigating the patchwork of state and local building codes, particularly disparate wind-load and seismic requirements in Florida and California, complicates system design and testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Terracotta Cladding Market |
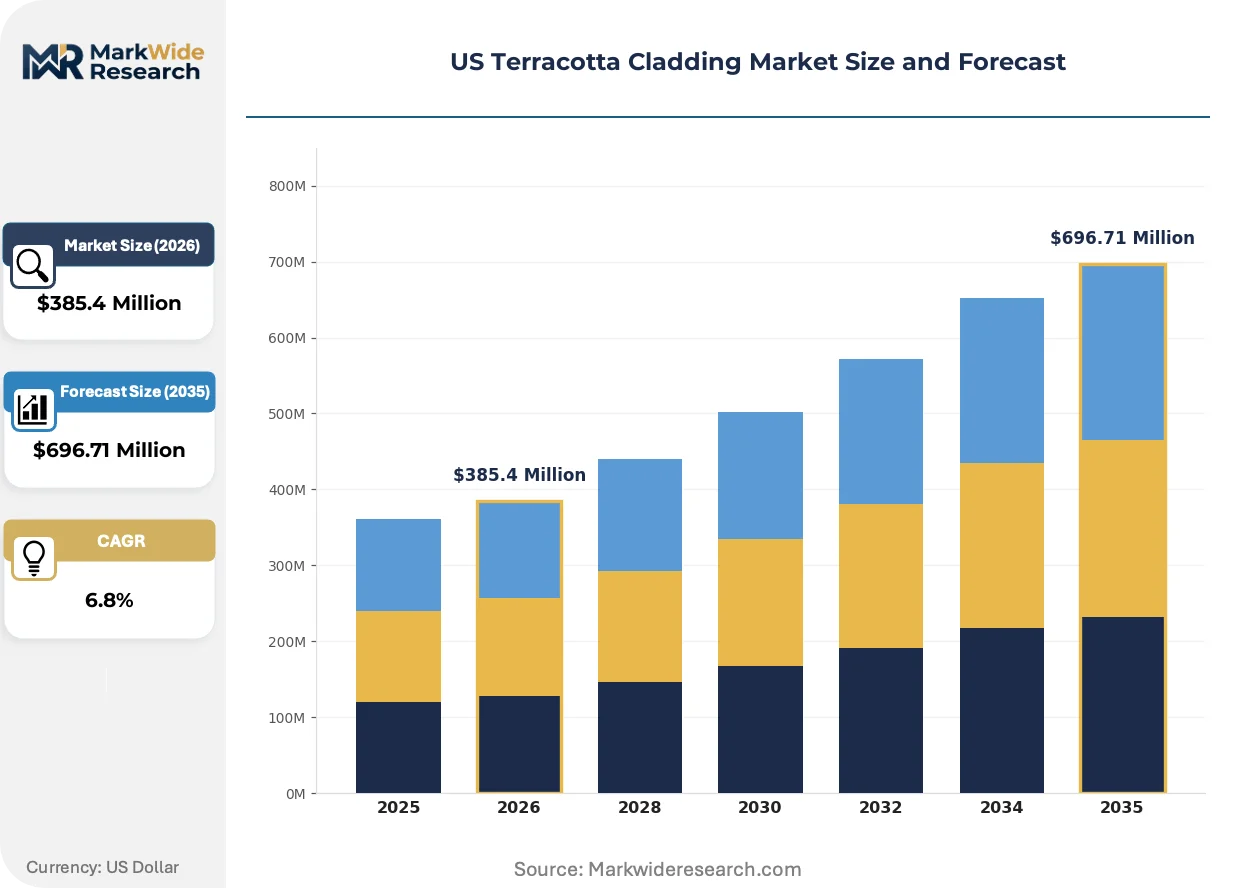
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Unglazed, Natural, Extruded Installation Type: New Construction, Renovation, Retrofitting, Restoration End User: Residential, Commercial, Industrial, Institutional Thickness: Thin, Standard, Thick, Custom |
| Companies Covered | Boston Valley Terracotta, Pace Representatives, Terreal North America, Palagio USA, Shildan, M.F. Murray Companies, Cladding Corp, Avenere Cladding, Hunter Douglas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Terracotta Cladding Market Strategic Shifts & Innovations
Advancements in manufacturing technology and evolving project delivery models are reshaping market expectations. The focus is shifting from individual components to integrated, performance-guaranteed facade systems, altering supplier-architect collaboration.
Digital glazing and 3D modeling allow for unprecedented customization in color, texture, and shape. High-end architectural firms are rapidly adopting these tools for signature institutional and cultural buildings. This capability is bifurcating the market between bespoke, project-specific solutions and standardized systems for mass commercial application.
Stricter state-level enforcement of ASTM performance standards for building envelopes is becoming a critical factor. This shift requires suppliers to validate entire rainscreen assemblies for water penetration and air leakage, not just individual panels. The high-rise commercial sector is most affected, demanding system-level warranties to de-risk complex facade projects.
Architects and general contractors are increasingly specifying fully engineered, single-source rainscreen systems. This model displaces the traditional multi-vendor approach, where components were sourced separately, favoring suppliers who provide integrated engineering support. This preference is most pronounced in large commercial developments in cities like Boston and Seattle seeking streamlined procurement.
US Terracotta Cladding Market Segmentation
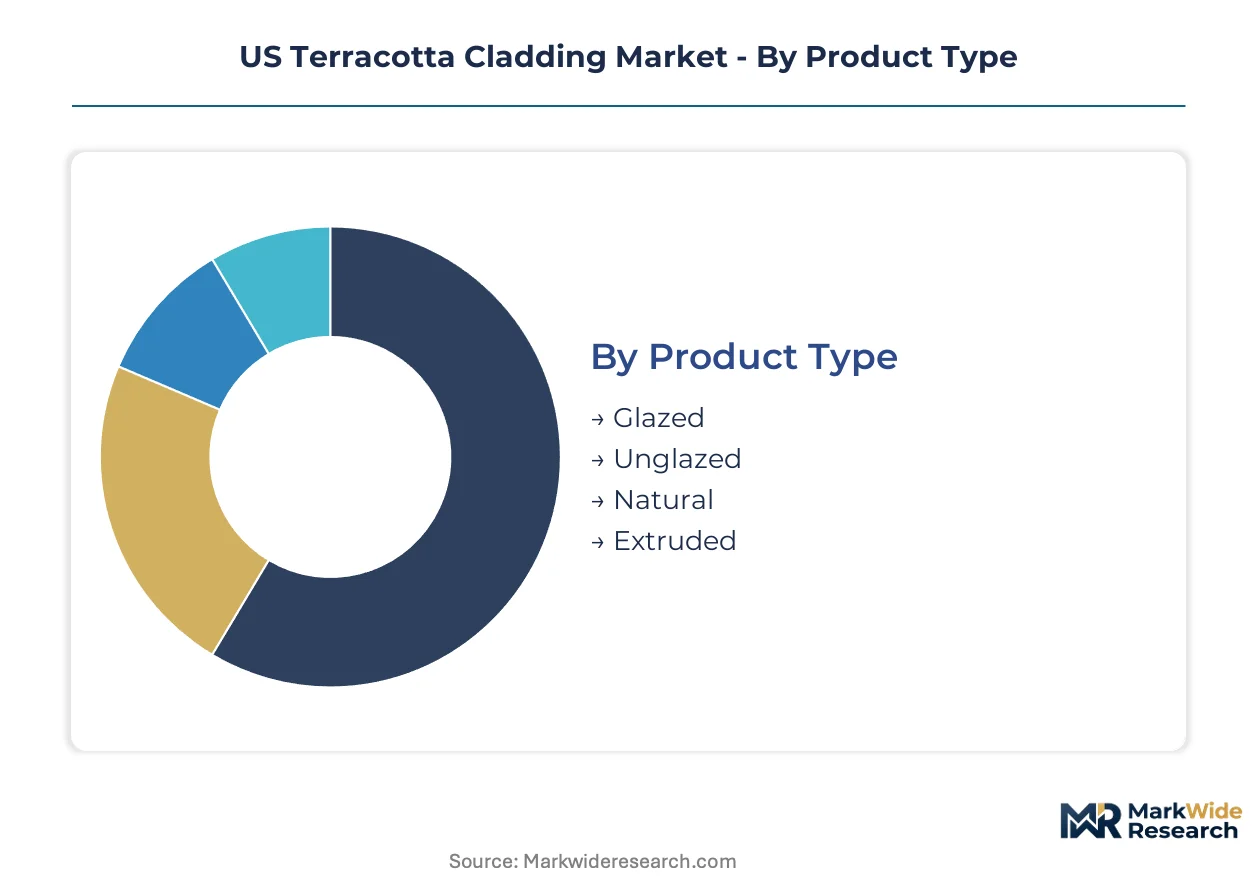
The US terracotta cladding market exhibits distinct segmentation based on product characteristics, installation methods, end-user applications, and material specifications. Understanding these categories helps to delineate demand patterns and identify specific growth opportunities within the national construction landscape.
Product Type:
Product type differentiation in US terracotta cladding is increasingly influenced by ASTM performance standards and evolving state-level energy codes.
- Glazed:These panels feature a ceramic coating applied before firing, offering a wide range of colors and finishes. Demand concentrates in institutional and cultural buildings in metropolitan areas like New York City, driven by aesthetic customization and signature architectural identity.
- Extruded:Produced by forcing clay through a die, these panels offer consistent shapes and often form part of standardized rainscreen systems. High-volume commercial developments in cities such as Chicago frequently specify extruded terracotta for its cost-efficiency and reliable performance.
- Unglazed:These panels retain the natural color and texture of the fired clay, providing an earthy aesthetic. Architects often select unglazed options for projects seeking a more traditional or muted facade appearance.
- Natural:Similar to unglazed, natural terracotta emphasizes the inherent variations and organic qualities of the clay body. This type finds application in bespoke architectural designs where material authenticity is paramount.
Established volume favors Extruded systems; emerging adoption favors Glazed finishes.
Installation Type:
Installation type segmentation reflects the diverse project applications, ranging from preserving historic facades to constructing modern high-performance envelopes.
- New Construction:This segment involves the installation of terracotta cladding on newly erected buildings. Commercial and institutional sectors represent the primary volume drivers, particularly for high-rise projects in urban centers seeking durable and energy-efficient facades.
- Renovation:Renovation projects involve upgrading existing building exteriors with new terracotta cladding. This segment experiences significant growth as owners modernize aesthetics and improve energy efficiency to meet evolving state-level energy codes and attract tenants.
- Retrofitting:Retrofitting focuses on enhancing the performance of an existing building facade, often to improve thermal insulation or moisture management. This application is expanding due to federal incentives like the Inflation Reduction Act supporting deep energy retrofits.
- Restoration:Restoration involves carefully replicating or repairing historic terracotta facades to preserve architectural heritage. Specialized firms undertake these projects, often for landmark buildings or cultural institutions.
Demand for New Construction continues to drive market volume, while Renovation demonstrates significant growth potential.
End User:
End-user segmentation reflects the varying scale and aesthetic requirements of building projects across different sectors.
- Commercial:This segment includes office buildings, retail centers, and hospitality projects. Commercial developers specify terracotta for its longevity, low maintenance, and ability to create a distinctive brand image, especially in competitive urban markets.
- Institutional:Universities, museums, and government buildings constitute this segment. Institutional clients prioritize terracotta for its durability, sustainable attributes, and capacity to create iconic, long-lasting architectural statements.
- Residential:Terracotta cladding finds application in high-end multi-family residential buildings and custom homes. Owners seek its aesthetic appeal and thermal performance benefits.
- Industrial:While less common, some industrial facilities utilize terracotta for administrative buildings or specific architectural features. This segment often prioritizes durability and low maintenance.
The Commercial segment accounts for the largest share, with Institutional projects requiring specialized, long-lifecycle solutions.
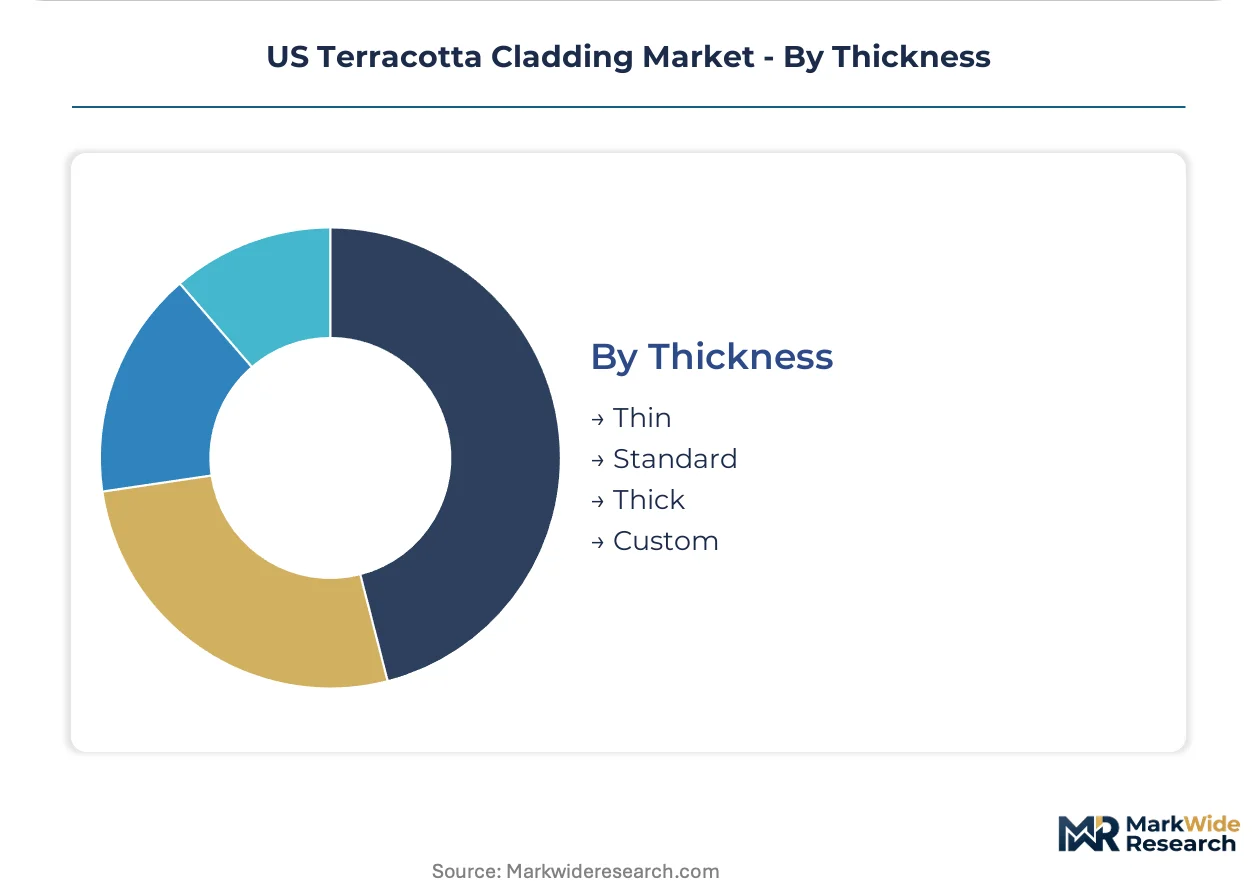
Thickness:
Thickness segmentation addresses both structural performance needs and specific aesthetic design requirements for facade systems.
- Standard:These panels represent the most common thickness, offering a balance of structural integrity and material cost. They are widely used across commercial and institutional projects for general facade applications.
- Custom:Custom thickness panels are manufactured to specific project requirements, often for unique architectural designs or to meet particular wind-load and seismic resistance standards in states like California and Florida.
- Thin:Thinner panels reduce overall facade weight, potentially lowering structural requirements for the building frame. They are increasingly considered for renovation projects where existing structural capacity is a concern.
- Thick:Thicker panels offer enhanced durability and can contribute to a more robust facade system. They are often specified for projects requiring superior impact resistance or a more pronounced aesthetic depth.
Material specification often balances the cost-effectiveness of Standard panels with the enhanced performance or aesthetic demands of Custom solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US terracotta cladding market exhibits supply-side concentration due to specialized manufacturing processes for both bespoke and standardized systems. This concentration drives regional demand patterns, particularly in urban centers with stringent building codes. Local market dynamics influence material specification and project delivery across various states.
New York City Metro
New York City's metropolitan area drives significant demand for custom-glaze terracotta cladding in high-rise commercial and institutional projects. Stricter thermal performance mandates in New York state necessitate advanced facade systems. Iconic cultural buildings and new commercial towers across Manhattan and Brooklyn frequently specify bespoke terracotta for its aesthetic and performance attributes.
California
California's construction market requires terracotta cladding for both seismic resistance and energy efficiency upgrades. Local building codes in California dictate stringent seismic and wind-load resistance standards for all facade materials. Major urban centers like San Francisco and Los Angeles see strong demand for high-performance terracotta in renovation and new construction projects.
Florida
Florida's building sector emphasizes robust cladding solutions due to its vulnerability to extreme weather events. Local building codes in Florida dictate specific wind-load resistance requirements for exterior materials. Coastal cities such as Miami and Tampa prioritize resilient terracotta systems for new developments and retrofits, enhancing building envelope integrity.
Chicago
Chicago's commercial construction market utilizes terracotta cladding for high-volume developments, favoring standardized extruded systems. Illinois state-level energy codes influence material selection, promoting efficient building envelopes. The city's extensive commercial district frequently specifies terracotta for its cost-efficiency and reliable performance in large-scale architectural applications.
Southeast
The Southeast region, encompassing growing metropolitan areas like Atlanta and Charlotte, presents significant opportunities for mid-rise commercial and mixed-use terracotta projects. Emerging state-level energy codes in states such as Georgia and North Carolina are increasing demand for high-performance facades. These cities are experiencing rapid expansion, driving specification for durable and aesthetically pleasing cladding solutions.
US Terracotta Cladding Market Key Industry Players
Concentration sits with specialized manufacturers offering bespoke solutions, alongside large-scale producers supplying standardized systems. The US terracotta cladding market exhibits a tiered structure, segmenting between high-end architectural providers and volume commercial suppliers. Key strategic archetypes include custom fabrication specialists, integrated system providers, and large-scale panel manufacturers. Competitive moves focus on geographic expansion into underserved regions and deepening vertical integration to offer system-level warranties.
Specialists in complex, custom projects include Boston Valley Terracotta, which caters to institutional and cultural buildings with unique design requirements for signature architectural identity. Terreal North America, a large-scale manufacturer, exemplifies the volume commercial segment, leveraging its manufacturing scale to supply standardized systems for extensive developments. Shildan further differentiates its offerings by providing complete engineered rainscreen systems, integrating multiple components into a single, performance-guaranteed solution. These companies represent distinct approaches to market engagement, from highly customized production to comprehensive, integrated system delivery.
| Leading Market Players |
|---|
| Boston Valley Terracotta |
| Pace Representatives |
| Terreal North America |
| Palagio USA |
| Shildan |
| M.F. Murray Companies |
| Cladding Corp |
| Avenere Cladding |
| Hunter Douglas |
| Others |
Cost & Logistics Intelligence
The increasing preference for high-performance rainscreen systems as a building envelope solution simultaneously reshapes the supply geography towards specialized manufacturers and elevates pricing economics for integrated offerings.
Pricing Analysis
ASTM performance standards dictate the pricing tier structure for US terracotta cladding, influencing system design and material specification. Project-based pricing dominates for custom architectural solutions, while standardized extruded systems often follow transactional models. Price differentiation stems from the level of customization for glazes and panel shapes, alongside the certification level for wind-load and seismic resistance. Pricing pressure stems from the higher upfront installation costs compared to alternative cladding materials. Commercial developers exhibit higher price sensitivity for volume projects, whereas institutional clients prioritize long-term value over initial cost.
Supply Chain Analysis
Just-in-time inventory strategies are challenging for bespoke terracotta, leading to strategic stockpiles of raw clay and glazes for custom orders. Supply concentrates significantly in European factories for specialized glazes and complex forms, while US manufacturers often focus on standardized extruded panels. The supply chain draws from raw clay, specialized pigments for glazes, and engineered substructure components. Long lead times for custom European products represent a structural risk, impacting project schedules. Distribution runs through a network of manufacturer representatives and specialized facade contractors directly to project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US terracotta cladding market presents a high-growth disruption, driven by stringent state-level energy codes and advancements in digital glazing technology.
For Market Incumbents: Shield market share by deepening vertical integration into engineered rainscreen systems, offering comprehensive system-level warranties to de-risk complex projects. Invest in advanced manufacturing capabilities for larger format panels and unique 3D shapes to counter the cost advantage of alternative cladding materials. Focus R&D on developing faster-curing glazes to reduce lead times for custom orders.
For New Entrants and Emerging Players: Anchor in underserved geographic markets, particularly mid-rise commercial and mixed-use projects in the Southeast and Texas. Target the renovation segment by offering standardized, easy-to-install rainscreen systems that improve energy efficiency. A go-to-market angle emphasizing rapid delivery and simplified installation for high-volume commercial applications will penetrate the market effectively.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors vertically integrated specialists offering performance-guaranteed facade solutions. Long-term viability remains strong over the next decade due to ongoing energy efficiency mandates and architectural demand for durable aesthetics. Acquire companies with robust engineering capabilities and established supply chains for custom glazing. Increased federal incentives for deep energy retrofits is a specific signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Manufacturing Capacity | Increases ability to meet growing demand for both standardized and custom terracotta panels. |
| Deepen Vertical Integration | Enhances control over product quality and enables comprehensive system-level warranties for complex facades. |
| Invest in Advanced Glazing R&D | Unlocks new aesthetic possibilities and reduces lead times for bespoke architectural solutions. |
| Pursue System-Level Certification | Validates entire rainscreen assemblies, addressing critical performance requirements for high-rise commercial projects. |
| Target Geographic Expansion | Captures opportunities in rapidly growing metropolitan areas beyond established high-rise markets. |
Research Approach
A spread of perspectives from architects, general contractors, facade consultants, and building owners converged on the working assumptions for the US terracotta cladding market. This approach combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data sources included ASTM standards, state-specific building codes, construction industry reports, and manufacturer specifications. Bottom-up data collection was triangulated with top-down market sizing to ensure accuracy.
The analytical framework modeled market dynamics across the analysis window, segmenting by product type, installation method, end-user application, thickness, and regional market. Compound annual growth rates were derived from historical trend analysis and projected growth drivers, including evolving energy codes and construction activity. Industry-specific forecast inputs included commercial construction starts and the rate of building energy code updates.
Decision-makers should treat outputs as directional under assumptions of continued economic stability and consistent regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect these documented assumptions. Revision becomes warranted when significant shifts in construction spending or unexpected changes in material costs cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Vitrified Tiles Market