
 Fiber Cement Rainscreen Panels Market | 2026-2036
Fiber Cement Rainscreen Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Cement Rainscreen Panels Market Analysis
Skilled facade installer availability is collapsing across mature construction markets, forcing manufacturers to engineer lighter panel formats and clip-based attachment systems that reduce labor hours. James Hardie Industries plc leverages its North American distribution density to sustain contractor loyalty through certified training programs. Etex Group anchors European supply through vertically integrated fiber cement production, while Nichiha Corporation dominates Japanese commercial specifications with proprietary coating technologies.
Fiber cement rainscreen panels are composite building envelopes manufactured from Portland cement, cellulose fibers, and mineral fillers, typically formed through Hatschek process layering and autoclave curing to achieve densities of 1,400–1,600 kg/m³ and fire resistance ratings up to A2-s1,d0. These panels serve primarily as ventilated exterior cladding systems that manage moisture, thermal bridging, and atmospheric protection in multi-story structures. Flat panels occupy the largest volume share due to standardized procurement in commercial towers, while insulated panels represent the fastest-growing configuration as building codes tighten envelope performance minimums. Ventilated facades command premium positioning among installation methods, though modular systems are gaining share in prefabricated construction workflows.
The EU Green Deal and national transpositions through Germany's Building Energy Act shape product certification requirements across European projects, while the EPA's NESHAP standards govern fiber cement manufacturing emissions in the United States. ASTM E84 and EN 13501-1 fire performance classifications function as gatekeeping thresholds for commercial insurance and code compliance in both markets. Stakeholders must monitor evolving carbon accounting rules for embodied emissions in facade materials, as these metrics are becoming decisive in public procurement scoring and institutional investor screening.
Market Dynamics
Retrofit mandates across Germany, the United Kingdom, and the northeastern United States are compressing specification timelines and forcing manufacturers to pre-certify panel systems against evolving thermal performance thresholds. Installer scarcity is simultaneously pushing product design toward lighter formats and mechanical fastening simplification.
Growth Catalysts
- Germany's Building Energy Act:Mandatory efficiency upgrades for commercial building envelopes are accelerating specification of ventilated fiber cement systems in multi-tenant office and healthcare facilities.
- Prefabricated construction workflows:Modular building manufacturers are integrating rainscreen panels into factory-built envelope assemblies, reducing on-site labor exposure.
- Cellulose fiber sourcing:Sustainable pulp supply chains from Nordic forestry operations are enabling carbon-negative claims in institutional procurement scoring.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production concentrates in China and Turkey, exposing margins to natural gas and carbon border adjustment fluctuations.
- Aluminum composite panel substitution:Lower-cost metal facades retain share in speculative commercial development where energy code enforcement remains inconsistent.
- Autoclave capacity concentration:Curing infrastructure clusters in Belgium and Poland create geographic supply risk for just-in-time project delivery.
Strategic Opportunities
- United Kingdom retrofit corridors:Urban densification zones in Manchester and Birmingham present concentrated demand for overcladding solutions on 1960s concrete frame stock.
- Photovoltaic integration:Building-integrated solar manufacturers are co-developing mounting systems for fiber cement substrates, opening rooftop and facade energy generation applications.
- EU Taxonomy alignment:Technical screening criteria for sustainable construction are creating preferential financing terms for certified rainscreen specifications in institutional portfolios.
Industry Challenges
- Facade installer certification gaps:Trade apprenticeship programs in France and the Netherlands have not scaled to match retrofit program velocity, forcing manufacturers to absorb training costs.
- Multi-jurisdictional fire testing:ASTM E84 and EN 13501-1 divergence requires duplicate certification expenditure for transatlantic project participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Cement Rainscreen Panels Market |
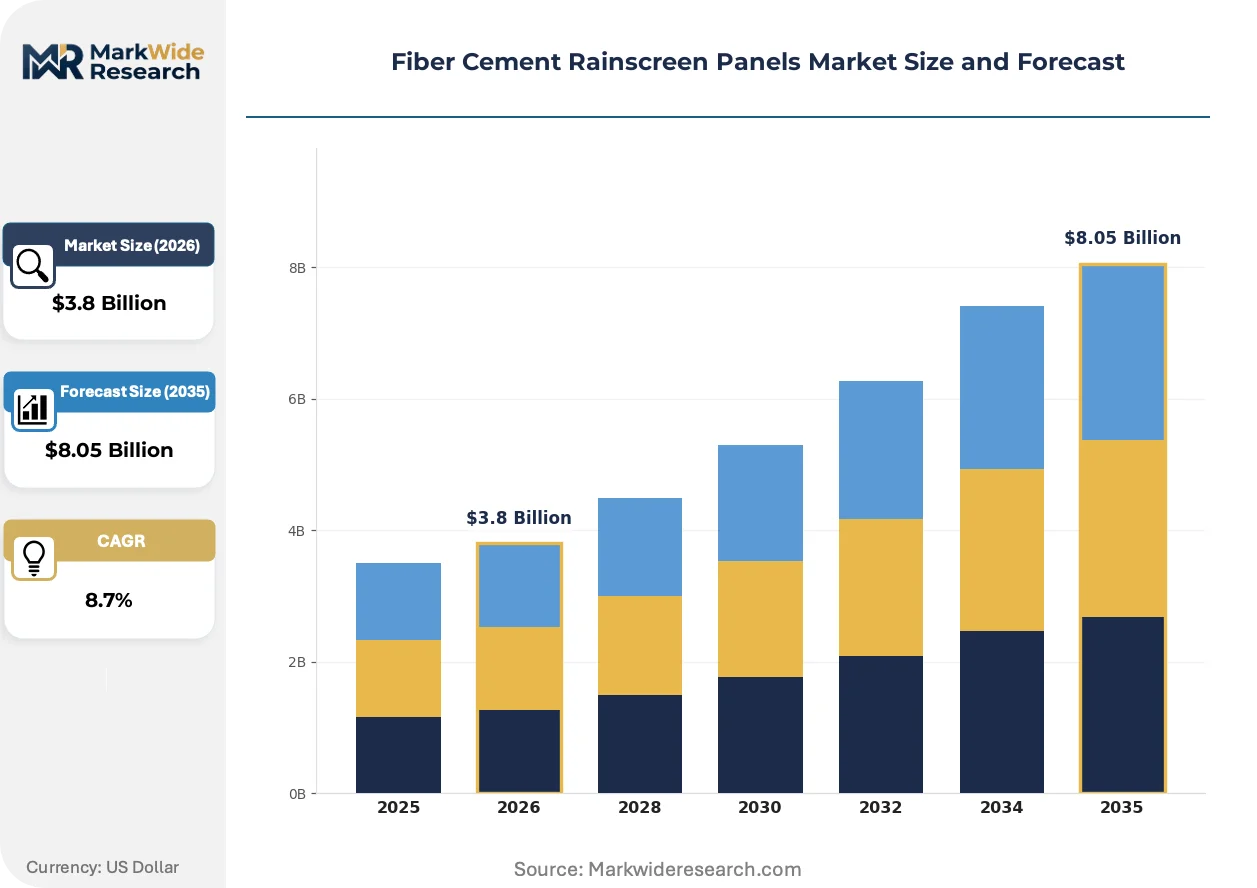
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panels, Textured Panels, Decorative Panels, Insulated Panels End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Educational Institutions Installation Method: Direct Attachment, Ventilated Facades, Curtain Walls, Modular Systems Application: Exterior Cladding, Interior Partitions, Fire-Resistant Walls, Atmospheric Protection |
| Companies Covered | James Hardie Industries plc, Saint-Gobain, Etex Group, Nichiha Corporation, Cembrit, Allura, Hume Cemboard Industries, Everest Industries, Equitone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Cement Rainscreen Panels Market Emerging Trajectories
Product engineering and regulatory compliance are converging to redefine competitive advantage in facade specification. Manufacturers are racing to embed performance verification into panel systems before procurement gates harden.
Prefinished fiber cement panels with factory-applied hydrophobic coatings are supplanting site-painted alternatives in commercial tower specifications. General contractors in London and Frankfurt are mandating these systems to eliminate scaffolding duration and weather-dependent scheduling risk. The shift is compressing traditional paint subcontractor roles and transferring finish warranty liability upstream to panel manufacturers.
REACH restrictions on crystalline silica exposure are forcing reformulation of fiber cement mixing processes across European production facilities. Manufacturers are investing in wet-cutting automation and closed-loop dust capture to maintain workforce access and avoid operational shutdowns. German and Austrian plants are furthest along in compliance conversion, creating temporary supply allocation advantages for domestic project bidding.
Design-build procurement is consolidating specification authority into fewer hands across Nordic commercial construction. Engineering firms in Copenhagen and Stockholm are pre-approving rainscreen systems for multi-project deployment, reducing architect-led material substitution. The concentration is favoring manufacturers with documented whole-life carbon data and BIM object libraries over specification-grade generalists.
Fiber Cement Rainscreen Panels Market Segmentation
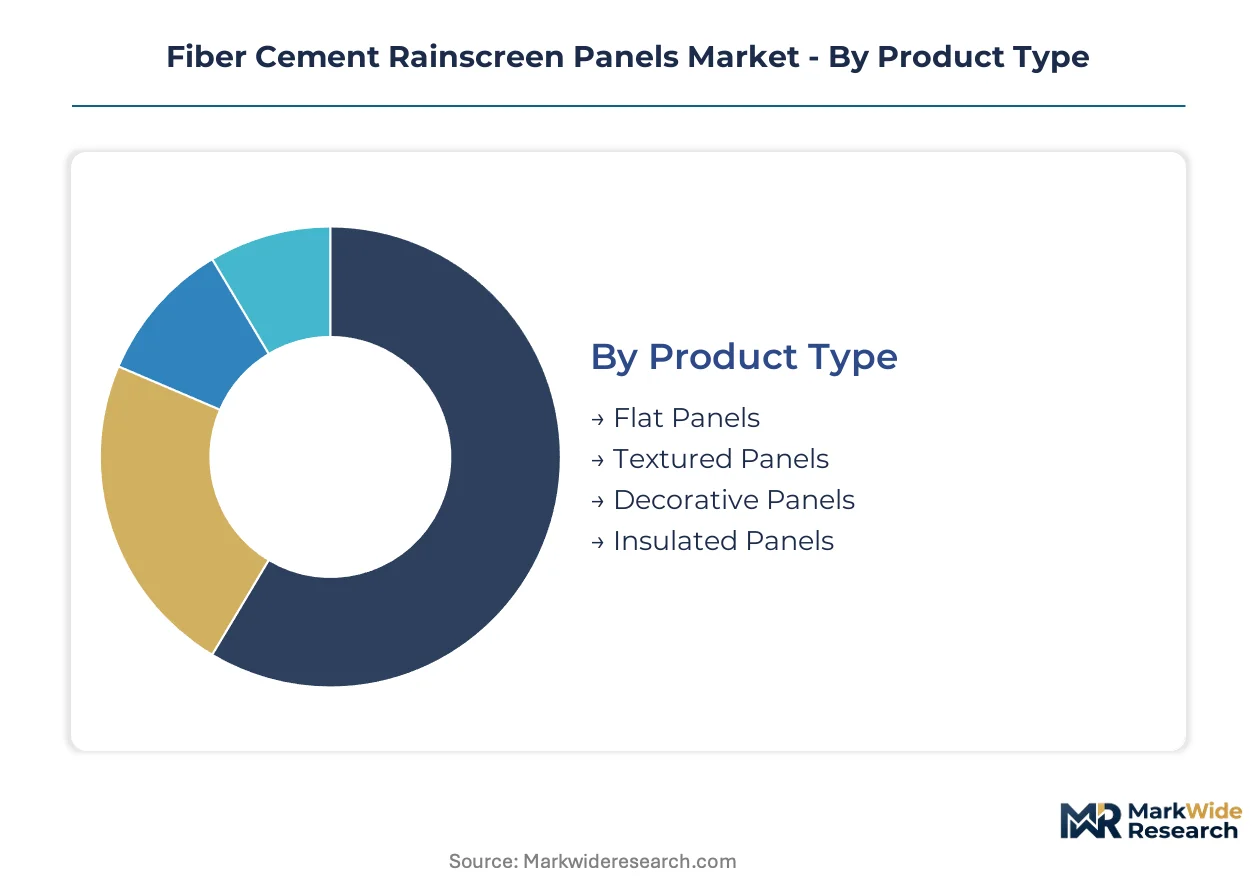
Segmentation in fiber cement rainscreen panels reveals how regulatory pressure and installation economics reshape procurement patterns. Product formats, end-user priorities, and mounting systems each carry distinct compliance burdens and labor cost profiles that determine competitive positioning.
Product Type:
ASTM E84 and EN 13501-1 fire ratings create divergent certification pathways across product formats, with surface finish and core density determining test outcomes.
- Flat Panels:Standardized rectangular boards with uniform thickness dominate commercial tower procurement due to predictable structural calculations and rapid quantity surveying. German and UK retrofit corridors concentrate specification for overcladding 1960s concrete frame stock where flat geometries simplify weatherproofing interfaces.
- Insulated Panels:Composite assemblies bonding fiber cement facing to rigid thermal insulation achieve A2-s1,d0 ratings while meeting Germany's Building Energy Act envelope performance minimums. Prefabricated construction workflows in Denmark and Sweden integrate these units into factory-built envelope assemblies, reducing on-site labor exposure and compressing project schedules.
- Textured Panels:Embossed surface treatments mimicking timber grain or masonry provide aesthetic differentiation for institutional facades requiring visual warmth without combustible materials.
- Decorative Panels:Custom-patterned or pigmented finishes serve signature architectural statements where design-build procurement consolidates specification authority into engineering-led selection.
Flat panels handle the majority of throughput; insulated panels are expanding most quickly on share as thermal codes tighten.
End User:
Customer type determines warranty duration, maintenance liability, and the sophistication of whole-life carbon accounting applied to material selection.
- Commercial Buildings:Multi-tenant offices and healthcare facilities drive ventilated facade specification to satisfy Germany's Building Energy Act mandatory efficiency upgrades. Institutional investors screen facade materials against EU Taxonomy technical screening criteria, creating preferential financing terms for certified rainscreen assemblies in Copenhagen and Stockholm portfolios.
- Residential Buildings:Single-family and multi-family construction favor direct-attachment systems where installer scarcity pushes product design toward lighter formats and mechanical fastening simplification. Nordic forestry-based cellulose fiber sourcing enables carbon-negative claims in Swedish and Finnish housing association procurement.
- Educational Institutions:Public sector procurement scoring weights embodied emissions metrics, favoring manufacturers with documented environmental product declarations.
- Industrial Facilities:Chemical resistance and impact durability priorities dominate specification for manufacturing plant envelopes.
Commercial buildings anchor volume demand; educational institutions are climbing the fastest on specification sophistication.
Installation Method:
Labor availability and scaffolding economics drive method selection, with clip-based systems reducing skilled installer hours per square meter.
- Ventilated Facades:Cavity-based rainscreen systems manage moisture and thermal bridging through pressure-equalized air gaps, commanding premium positioning in German and UK commercial retrofits. REACH restrictions on crystalline silica exposure favor factory-finished panels that eliminate on-site cutting and dust generation.
- Modular Systems:Pre-engineered panel-and-frame units integrate into offsite manufacturing workflows, addressing installer certification gaps in France and the Netherlands. Engineering firms in Stockholm and Copenhagen pre-approve these systems for multi-project deployment.
- Direct Attachment:Simplified mechanical fastening suits residential and light commercial applications where labor cost sensitivity outweighs performance optimization.
- Curtain Walls:Structural glazing interfaces with fiber cement infill panels serve high-rise commercial towers requiring large-format cladding without combustible core materials.
Ventilated facades dominate value capture; modular systems are gaining share fastest as prefabrication scales.
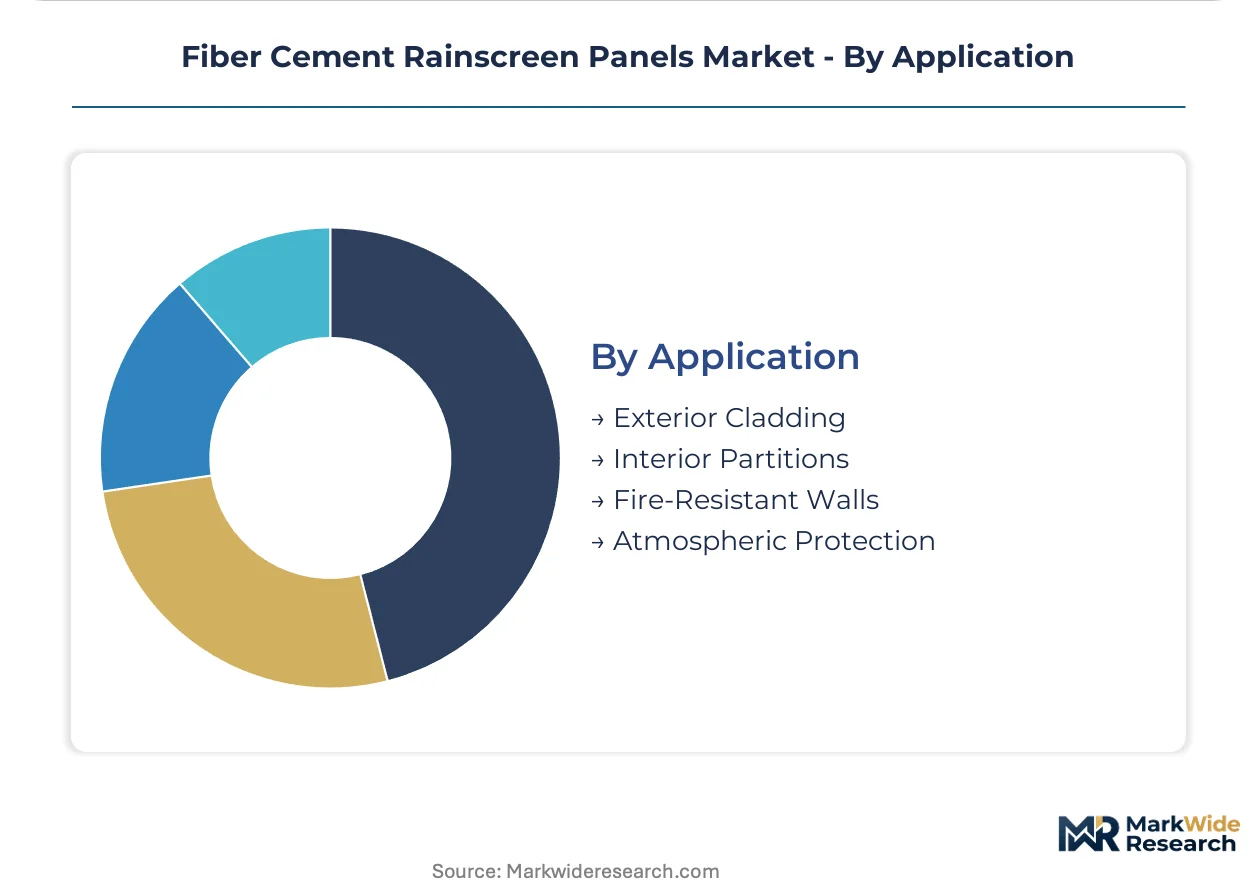
Application:
Functional performance requirements determine panel density, coating chemistry, and edge-sealing specifications.
- Exterior Cladding:Primary weatherproofing function demands hydrophobic factory coatings and autoclave-cured densities of 1,400–1,600 kg/m³ to resist freeze-thaw cycling. London and Frankfurt general contractors mandate prefinished systems to eliminate scaffolding duration and weather-dependent scheduling risk.
- Fire-Resistant Walls:Non-combustible core requirements in high-occupancy buildings drive A2-s1,d0 certification as a gatekeeping threshold for commercial insurance compliance.
- Interior Partitions:Moisture-resistant fiber cement serves wet-area lining in healthcare and institutional settings where humidity cycling degrades gypsum alternatives.
- Atmospheric Protection:Specialized coatings resist industrial pollutant deposition in manufacturing zones and coastal salt exposure.
Exterior cladding commands the largest installed base; fire-resistant walls show the steepest specification trajectory as code enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's NESHAP standards govern manufacturing emissions in the United States, while Germany's Building Energy Act and the EU Green Deal shape certification requirements across European projects. National efficiency mandates and retrofit programs are compressing specification timelines in mature construction markets.
Germany
Commercial building developers accelerate ventilated facade specifications to meet EnEV thermal efficiency standards. The Building Energy Act mandates envelope upgrades for multi-tenant offices and healthcare facilities. Retrofit corridors in Berlin and Hamburg concentrate demand for overcladding solutions on post-war concrete frame stock.
United Kingdom
Urban densification zones in Manchester and Birmingham present concentrated demand for facade renovation on 1960s building stock. The country's net-zero building targets align with EU Green Deal transpositions for embodied carbon accounting. London general contractors mandate prefinished panel systems to eliminate scaffolding duration and weather-dependent scheduling risk.
United States
Northeastern commercial developers specify rainscreen systems to satisfy stringent state-level energy codes. EPA NESHAP standards limit fiber cement manufacturing emissions from clinker-intensive production. Retrofit-intensive corridors across New York and Boston drive specification of lighter panel formats addressing installer scarcity.
Japan
Commercial tower specifications favor proprietary coating technologies for atmospheric protection in coastal and industrial zones. METI efficiency standards govern building envelope performance in high-occupancy structures. Tokyo and Osaka engineering firms pre-approve rainscreen systems for multi-project deployment in design-build procurement.
Sweden
Prefabricated construction workflows in Stockholm and Copenhagen integrate insulated panels into factory-built envelope assemblies. Nordic forestry-based cellulose fiber sourcing enables carbon-negative claims in institutional procurement scoring. Danish modular manufacturers are gaining share as prefabrication scales across Scandinavian commercial construction.
Fiber Cement Rainscreen Panels Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the fiber cement rainscreen panels market. The upper tier commands specification authority through captive raw material supply and certified distribution networks, while mid-scale fabricators compete on retrofit project velocity and regional code expertise. Two strategic archetypes dominate: vertically integrated producers with autoclave curing infrastructure, and coating specialists leveraging proprietary surface technologies. Competitive moves concentrate on capacity expansion in low-carbon clinker regions and strategic partnerships with modular construction manufacturers.
Within the integrated producer tier, James Hardie Industries plc and Etex Group exemplify divergent geographic anchoring strategies. James Hardie leverages North American distribution density to sustain contractor loyalty through certified training programs. Etex Group anchors European supply through captive fiber cement production capacity clustered in Belgium and Poland. Nichiha Corporation occupies a position as the coating-technology specialist, dominating Japanese commercial specifications through proprietary surface engineering. These three represent the spectrum from scale-driven manufacturing to technology-differentiated positioning.
| Leading Market Players |
|---|
| James Hardie Industries plc |
| Saint-Gobain |
| Etex Group |
| Nichiha Corporation |
| Cembrit |
| Allura |
| Hume Cemboard Industries |
| Everest Industries |
| Equitone |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between European facade contractors and autoclave operators in Belgium and Poland lock in cellulose fiber supply access while stabilizing panel price visibility against Portland cement volatility. These contracts bundle factory-finished panel procurement with certified installer training, transferring warranty liability upstream to manufacturers and compressing paint subcontractor margins.
Pricing Analysis
Project-based contracting dominates commercial tower procurement, with three-tier pricing structure across premium, standard, and economy levels separating A2-s1,d0 certified systems from direct-attachment residential formats. Price differentiation rests on fire certification grade and factory-applied hydrophobic coating chemistry. Cost compression in standard-grade panels is intensifying because REACH compliance investments concentrate in German and Austrian plants. Speculative commercial developers exhibit highest price sensitivity; institutional investors with EU Taxonomy mandates show lowest.
Supply Chain Analysis
China and Turkey anchor clinker production for Portland cement feedstock, while Belgium and Poland concentrate autoclave curing infrastructure. Raw material sourcing draws from Nordic forestry operations for cellulose pulp and Turkish natural gas-dependent kilns for cement. Single-source vulnerability in autoclave capacity creates geographic supply risk for just-in-time project delivery. Distribution runs through certified contractor networks and design-build engineering firms in Copenhagen, Stockholm, and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where BIM object libraries and whole-life carbon data interoperability determine specification authority. Manufacturers embedding performance verification into digital procurement workflows capture multi-project deployment commitments from engineering-led design-build consortia.
For Market Incumbents: Secure autoclave capacity expansion in low-carbon clinker regions to defend margin position against Portland cement price volatility. Invest in wet-cutting automation and closed-loop dust capture to maintain workforce access under tightening REACH crystalline silica restrictions. Backward integration into Nordic forestry pulp supply secures carbon-negative claims for institutional procurement scoring. For New Entrants and Emerging Players: Anchor in United Kingdom retrofit corridors—Manchester and Birmingham present concentrated demand for overcladding 1960s concrete frame stock with fragmented incumbent presence. Target modular system partnerships with offsite manufacturers addressing installer certification gaps in France and the Netherlands. Lead with photovoltaic integration co-development for building-integrated solar mounting systems. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated producers with captive fiber cement capacity and documented environmental product declarations. Long-term viability hinges on EU Taxonomy alignment creating preferential financing terms for certified rainscreen specifications. Watch for carbon border adjustment mechanism implementation as the inflection signal reshaping competitive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Belgian and Polish curing infrastructure investments reduce just-in-time delivery risk for German retrofit corridors. |
| Backward Integration into Pulp Supply | Nordic forestry captive sourcing enables carbon-negative claims in Copenhagen and Stockholm institutional portfolios. |
| Prefinished Panel Certification | Factory-applied hydrophobic coating investments eliminate on-site cutting dust under REACH crystalline silica restrictions. |
| BIM Object Library Development | Digital specification assets capture engineering-led design-build procurement consolidation in Nordic commercial construction. |
| Photovoltaic Integration Partnership | Co-developed mounting systems for fiber cement substrates open rooftop and facade energy generation applications. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with facade contractors, engineering firm specification leads, and autoclave plant operations managers; and secondary validation through customs trade data, SEC filings of listed building materials producers, EU ETS carbon price registries, and national building energy code transposition documents. Bottom-up project pipeline assessment across German, UK, and US retrofit corridors triangulated against top-down manufacturer capacity disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product format, installation method, end-user category, and regional regulatory cluster. CAGRs were derived from segment-level growth rate blending anchored to building code enforcement timelines and retrofit program funding velocity. Key inputs included cellulose fiber pulp pricing indices, Portland cement clinker production cost curves, and installer certification program scaling rates.
Underlying assumptions cover sustained enforcement of Germany's Building Energy Act and EU Green Deal building renovation targets, with deviation risk concentrated in carbon border adjustment implementation timing and natural gas price volatility affecting clinker production economics. Recalibration cycles align with material shifts in national efficiency mandate transpositions and prefabricated construction workflow adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Precast Concrete Manufacturing Market