
 Global Fire-Rated Medium Density Fiberboard Market | 2026-2036
Global Fire-Rated Medium Density Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire-Rated Medium Density Fiberboard Market Foresight
Commercial construction contractors are collapsing the historical dominance of residential furniture manufacturers as the primary volume buyers of fire-rated MDF, as stringent fire codes in high-rise and public buildings redirect procurement toward certified building materials. West Fraser Timber Co. Ltd. leverages its integrated fiber supply and North American mill network to anchor large-scale project deliveries. Sonae Arauco Portugal S.A. differentiates through European manufacturing scale and CE-marked product breadth. Dongwha Enterprise Co. Ltd. competes aggressively across Asia-Pacific infrastructure tenders with cost-optimized, chemically treated board lines.
Fire-rated medium density fiberboard is an engineered wood panel manufactured from refined wood fibers bonded with resin and fortified with mineral additives or intumescent chemicals to achieve Class A or Class B flame-spread ratings under ASTM E84 or EN 13501-1 protocols, serving primarily as a structural or decorative substrate where building codes mandate fire resistance. Moisture resistant MDF and high-density fire-rated MDF command the widest specification ranges in commercial interiors, with moisture-resistant grades capturing margin pools in healthcare and hospitality retrofits where humidity and fire standards overlap. Chemical treatment and mineral additive integration represent the fastest-growing technology lanes, as manufacturers shift away from surface-applied intumescent coatings toward embedded flame retardancy that survives machining and edge exposure.
The EU Construction Products Regulation, the U.S. International Building Code adopted by jurisdictions nationwide, and China's GB 8624 building material fire classification standard collectively elevate compliance costs while restricting market access for uncertified imports. ASTM E84 and EN 13501-1 testing protocols directly determine product eligibility for specification in commercial and institutional projects across their respective jurisdictions. Stakeholders must monitor evolving harmonization between regional fire-test methods and the pace of green-building certification integration, as LEED and BREEAM criteria increasingly intersect with flame-retardant material selection protocols.
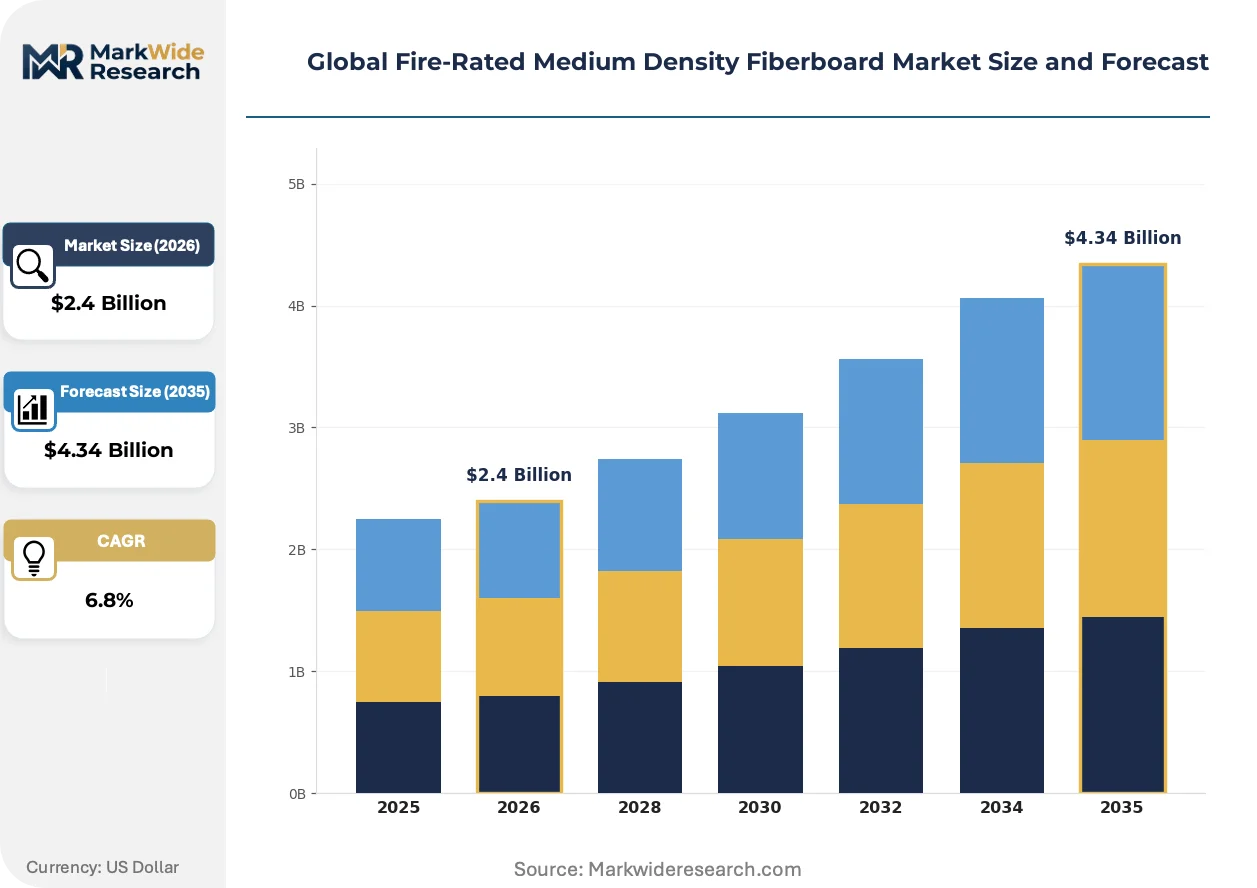
Market Dynamics
The fire-rated MDF market pivots on embedded flame-retardant chemistry displacing surface-applied intumescent coatings, as commercial contractors demand machinable boards that retain fire ratings after edge cutting and routing.
Growth Catalysts
- EU Construction Products Regulation:Mandates CE-marked fire performance declarations for structural substrates, forcing specification upgrades across German, French, and British high-rise retrofits.
- Urban densification clusters:Chinese municipal governments in Shanghai, Shenzhen, and Chengdu accelerate fire-code enforcement for mixed-use towers, concentrating demand for Class A-rated panels.
- Mineral additive integration:Embedded ammonium polyphosphate and magnesium hydroxide systems now achieve ASTM E84 Class A ratings without compromising board density or screw-holding strength.
Market Restraints
- Urea-formaldehyde resin volatility:Petrochemical feedstock price swings compress margins for manufacturers lacking backward integration into resin production.
- North American fiber supply concentration:Western Canadian sawmill residues dominate global pulp supply, exposing converters to rail-shipment bottlenecks and provincial timber-harvest quotas.
- Cross-laminated timber substitution:Mass-timber structural systems in Scandinavian and Pacific Northwest commercial projects bypass MDF for primary fire-rated assemblies.
Strategic Opportunities
- India's Smart Cities Mission:Metro rail stations and government hospital expansions in Mumbai, Delhi, and Bangalore lack domestic fire-rated panel capacity, creating import windows for certified producers.
- Healthcare humidity-fire overlap:Moisture-resistant fire-rated grades penetrate operating theaters and pharmaceutical cleanrooms where steam sterilization and flame codes intersect.
- Green-building certification convergence:LEED v4.1 and BREEAM credits for low-emitting materials now overlap with fire-safety procurement checklists, bundling specification criteria.
Industry Challenges
- ASTM E84 30-minute tunnel testing backlog:Certification queues at Underwriters Laboratories and Intertek facilities extend project timelines by 8-14 weeks.
- Intumescent chemist scarcity:Formulation expertise for halogen-free, low-smoke systems concentrates among retiring specialists at German and Japanese additive suppliers.
- Legacy CNC machining incompatibility:Embedded mineral fillers accelerate tool wear, forcing fabricators to retool with diamond-coated cutters or absorb higher maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire-Rated Medium Density Fiberboard Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fire-Rated MDF, Moisture Resistant MDF, High-Density Fire-Rated MDF, Flame Retardant MDF Technology: Thermal Insulation, Chemical Treatment, Intumescent Coating, Mineral Additive Integration Application: Wall Paneling, Ceiling Tiles, Furniture Manufacturing, Partition Systems, Decorative Elements End User: Construction Contractors, Furniture Manufacturers, Interior Designers, Real Estate Developers |
| Companies Covered | West Fraser Timber Co. Ltd., Sonae Arauco Portugal S.A., Georgia-Pacific Wood Products LLC, Dongwha Enterprise Co. Ltd., Swiss Krono Group AG, Weyerhaeuser Company, Duratex S.A., Pfleiderer Group SE, Celulosa Arauco y Constitución S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire-Rated Medium Density Fiberboard Market Shifts & Advancements
Fire-rated MDF innovation clusters around chemistry integration, regulatory harmonization pressures, and contractor procurement rationalization. Three vectors dominate competitive differentiation.
Embedded intumescent systems is fragmenting the supplier landscape by enabling smaller regional mills to achieve Class A ratings without licensing proprietary surface-coating technologies. Hospital and hospitality contractors in Texas, Florida, and California specify these boards for corridor wainscoting and elevator lobbies where field-cut edges remain exposed. The technology compresses minimum efficient scale for fire-rated production, allowing mid-capacity European and Southeast Asian plants to contest specifications previously reserved for integrated North American producers.
REACH restrictions on halogenated flame retardants are forcing reformulation cycles across EU-facing supply chains, with ECHA's 2023-2024 substance evaluation dossiers targeting legacy brominated additives used in construction panels. German and Polish manufacturers accelerate ammonium polyphosphate and expandable graphite transitions to maintain CE-marking validity. The regulatory pressure concentrates most acutely on white-goods and commercial-furniture exporters who dual-source construction-grade and decorative fire-rated lines.
General contractors now bundle fire-rated substrate procurement under single-source national agreements, displacing fragmented regional distributor relationships. Turner Construction, Clark Construction, and similar tier-one firms in the United States negotiate direct mill contracts for multi-project panel volumes. The consolidation concentrates specification influence among procurement teams in Chicago, Houston, and Atlanta, compressing margins for independent stocking distributors who previously captured value through technical specification support.
Global Fire-Rated Medium Density Fiberboard Market Segmentation
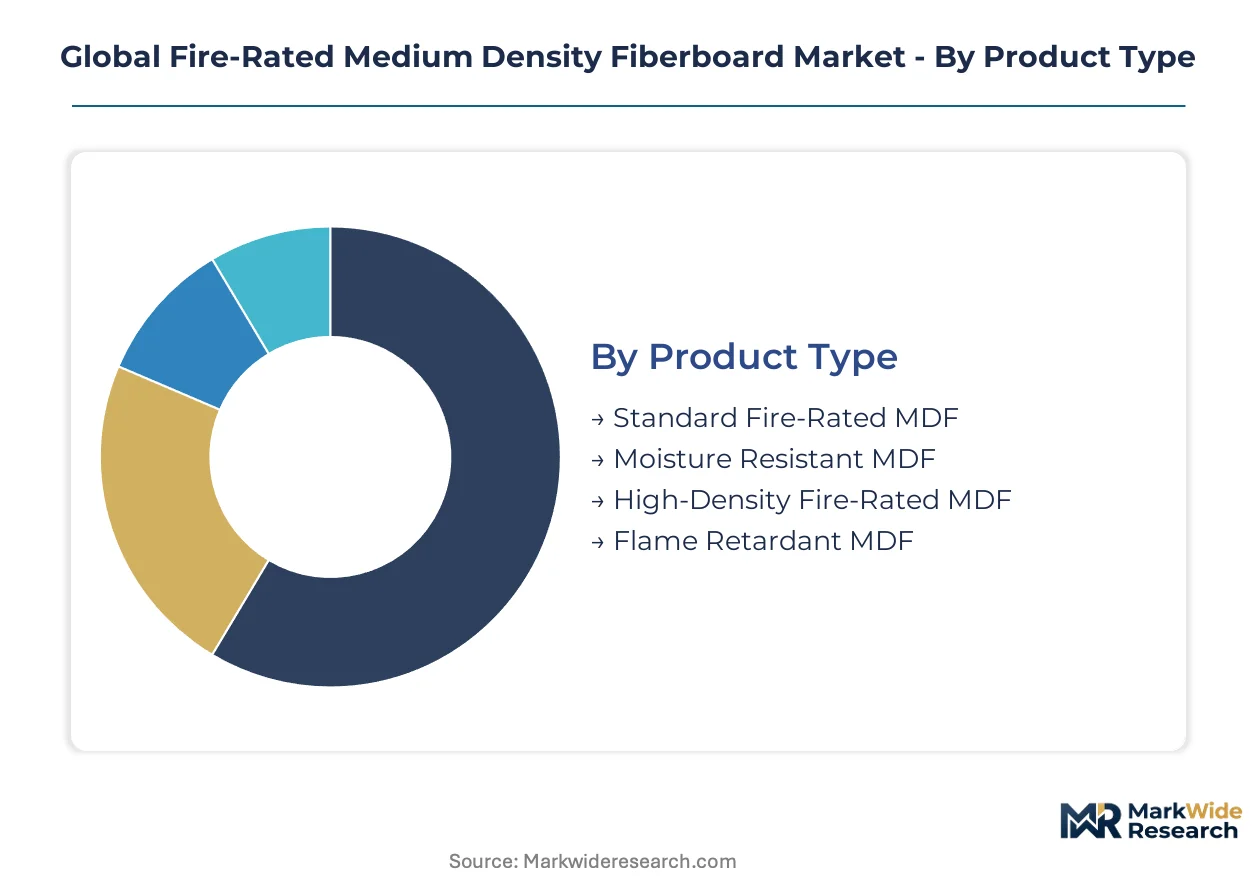
Segmentation in fire-rated MDF reveals how margin pools migrate toward specification-grade products where certification complexity creates pricing power. Contractors and procurement teams filter procurement through product performance, chemistry integration, and end-use compliance requirements.
Product Type:
Margin concentration sits with boards that solve dual-performance problems—fire resistance combined with humidity tolerance or structural density.
- Moisture Resistant MDF:Manufactured with hydrophobic resin systems and wax emulsions that prevent swelling while maintaining Class B or Class A flame-spread ratings. Healthcare retrofits in Florida, Texas, and California specify these boards for operating theater wall assemblies where steam sterilization and NFPA 101 life-safety codes overlap.
- High-Density Fire-Rated MDF:Pressed to 800-1000 kg/m³ with elevated resin content and mineral loading that improves screw-holding strength for structural applications. German and British high-rise contractors specify these panels for elevator shaft enclosures and exit corridor substrates where IBC and EN 13501-1 requirements mandate both fire integrity and mechanical robustness.
- Standard Fire-Rated MDF:Baseline panels with surface-applied intumescent treatments or embedded ammonium polyphosphate systems achieving minimum code compliance.
- Flame Retardant MDF:Boards engineered with halogen-free additive packages targeting specific smoke-density limits for transit infrastructure and tunnel applications.
The dominant share belongs to moisture-resistant grades, while high-density fire-rated MDF is closing the gap fastest.
Technology:
Technology selection determines capital intensity and regulatory durability across manufacturing footprints.
- Mineral Additive Integration:Magnesium hydroxide and aluminum trihydrate particles distributed throughout the fiber mat during formation, creating embedded flame retardancy that survives machining without edge-rating degradation. Chinese manufacturers in Shandong and Jiangsu provinces deploy this chemistry for domestic GB 8624 Class A compliance and export CE marking.
- Chemical Treatment:Resin systems modified with phosphorus-nitrogen compounds that catalyze char formation under pyrolysis. European mills favor this approach for REACH-compliant formulations avoiding legacy brominated additives targeted by ECHA substance evaluation.
- Thermal Insulation:Low-density core structures that delay heat transmission through mass reduction rather than active chemistry.
- Intumescent Coating:Surface-applied systems that expand under heat exposure, increasingly displaced by embedded alternatives due to field-durability concerns.
Chemical treatment commands the largest installed base, though mineral additive integration is expanding most quickly.
Application:
Application segmentation tracks where fire-code enforcement tightens fastest and where aesthetic requirements resist substitution to non-combustible materials.
- Wall Paneling:Vertical surface substrates for corridors, lobbies, and tenant improvement spaces where ASTM E84 Class A ratings meet design flexibility demands. US commercial contractors in Atlanta, Houston, and Chicago specify these for multi-project national agreements.
- Partition Systems:Demountable and fixed wall assemblies in open-plan offices and healthcare facilities requiring both fire-resistance ratings and acoustic performance.
- Ceiling Tiles:Suspended grid systems where fire-rated MDF provides concealed plenum barriers and decorative finish surfaces.
- Furniture Manufacturing:Casegoods and millwork for hospitality and institutional settings where NFPA 260 upholstery standards intersect with substrate flame-spread requirements.
- Decorative Elements:Routed columns, wainscoting, and architectural features where machined edge exposure demands embedded rather than surface fire protection.
Wall paneling retains the largest specification volume, while partition systems are gaining share fastest.
End User:
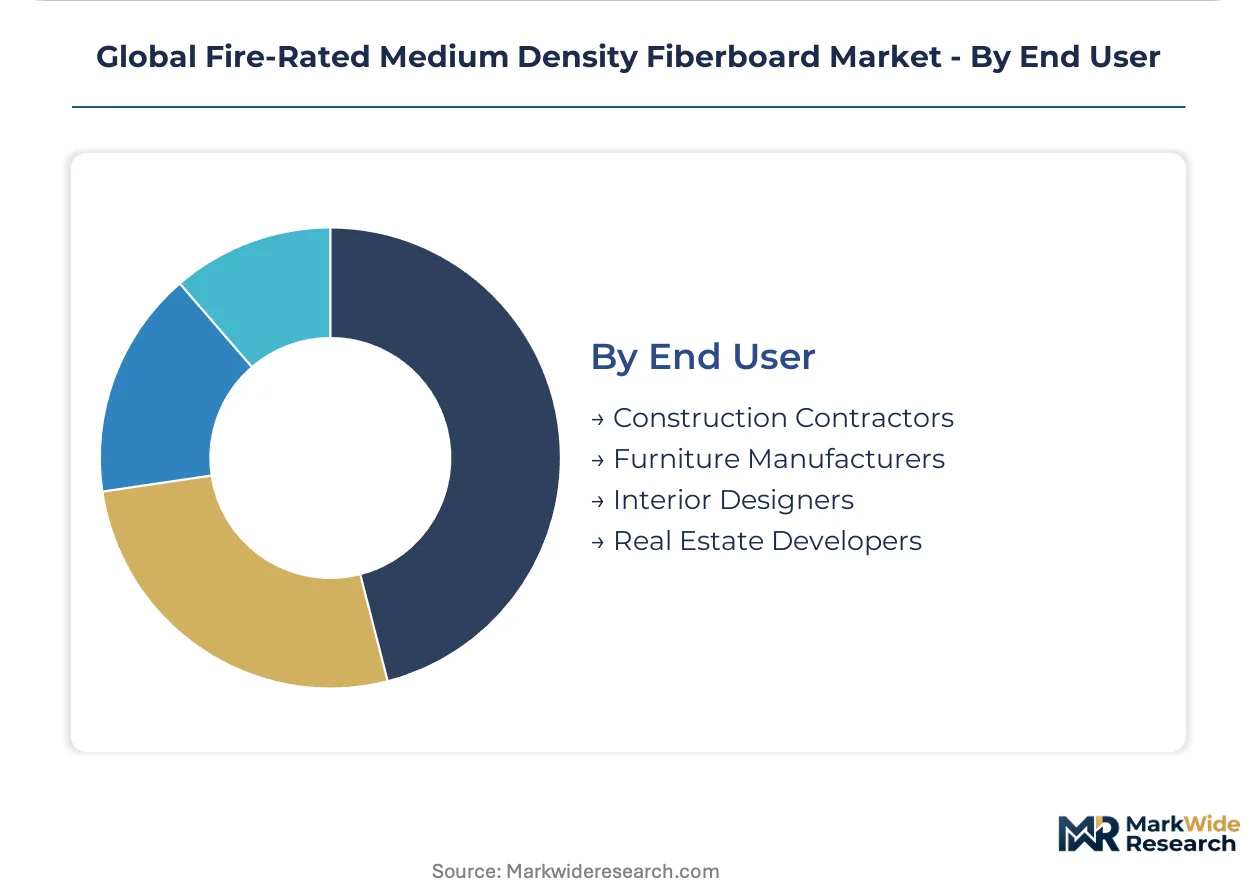
End-user structure reflects a power shift from fragmented furniture producers to consolidated construction procurement.
- Construction Contractors:General contractors and specialty interior firms negotiating direct mill contracts for certified panel volumes across multi-project portfolios. Turner Construction and Clark Construction bundle fire-rated substrate procurement under single-source agreements that displace regional distributor relationships.
- Real Estate Developers:Asset owners in Shanghai, Shenzhen, and Mumbai specifying Class A-rated materials for mixed-use towers and Smart Cities infrastructure where municipal fire-code enforcement accelerates.
- Furniture Manufacturers:Residential and commercial producers facing margin compression as certification costs rise and construction contractors capture volume premiums.
- Interior Designers:Specification influencers routing selections through procurement teams rather than independent material sourcing.
Construction contractors hold the dominant procurement position, while real estate developers are consolidating influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors in the United States, China, and Germany command the dominant procurement positions for certified fire-rated panels, with municipal retrofit mandates and high-rise densification programs concentrating demand in specific urban corridors.
United States
General contractors in Atlanta, Houston, and Chicago negotiate direct mill contracts for multi-project national agreements covering corridor wainscoting and elevator lobby assemblies. The International Building Code adopted by jurisdictions nationwide mandates ASTM E84 Class A flame-spread ratings for high-rise interior substrates. UL and Intertek certification facilities face testing backlogs that extend project timelines by 8-14 weeks.
China
Municipal governments in Shanghai, Shenzhen, and Chengdu accelerate fire-code enforcement for mixed-use towers, concentrating demand for GB 8624 Class A-rated panels. The country's national building material fire classification standard elevates compliance costs while restricting market access for uncertified imports. Manufacturers in Shandong and Jiangsu provinces deploy mineral additive integration for domestic compliance and export CE marking.
Germany
High-rise contractors specify EN 13501-1 certified panels for elevator shaft enclosures and exit corridor substrates where mechanical robustness requirements intersect with flame-spread protocols. The EU Construction Products Regulation mandates CE-marked fire performance declarations for structural substrates. ECHA substance evaluation dossiers target legacy brominated additives, forcing ammonium polyphosphate transitions among German and Polish manufacturers.
India
Metro rail stations and government hospital expansions in Mumbai, Delhi, and Bangalore lack domestic fire-rated panel capacity, creating import windows for certified producers. The Smart Cities Mission drives specification of Class A-rated materials for public infrastructure where municipal fire-code enforcement accelerates. Real estate developers in these metros increasingly bundle substrate procurement under single-source agreements.
United Kingdom
High-rise retrofit programs following Grenfell Tower regulatory reforms redirect procurement toward certified building materials with traceable fire performance declarations. British adoption of EN 13501-1 protocols determines product eligibility for commercial and institutional projects. Contractors in London and Birmingham specify moisture-resistant fire-rated grades for healthcare and hospitality projects where humidity and fire standards overlap.
Global Fire-Rated Medium Density Fiberboard Market Competitive Landscape
Player mix skews toward integrated timber conglomerates with captive fiber supply and North American or European manufacturing footprints. The competitive structure concentrates around three strategic archetypes: vertically integrated pulp-to-panel producers controlling resin and fiber inputs; regional specialists leveraging CE-marking proximity for EU public-sector tenders; and Asia-Pacific cost-optimized fabricators competing on chemically treated board lines. Dominant competitive moves include backward integration into resin production to offset petrochemical feedstock volatility, and direct mill contracts with tier-one general contractors that displace fragmented regional distributor relationships.
Within the integrated timber conglomerate tier, West Fraser Timber Co. Ltd. and Weyerhaeuser Company exemplify North American players with mill network scale, while Sonae Arauco Portugal S.A. occupies a position representing European manufacturing breadth with CE-marked product lines. Dongwha Enterprise Co. Ltd. sits within the Asia-Pacific competitive vector, anchoring cost-optimized production for regional infrastructure tenders. Pfleiderer Group SE and Swiss Krono Group AG represent continental European specialists navigating REACH-compliant reformulation cycles, with Celulosa Arauco y Constitución S.A. and Duratex S.A. exemplifying Latin American integrated producers. Georgia-Pacific Wood Products LLC occupies a position among US-based building materials conglomerates with project-delivery scale.
| Leading Market Players |
|---|
| West Fraser Timber Co. Ltd. |
| Sonae Arauco Portugal S.A. |
| Georgia-Pacific Wood Products LLC |
| Dongwha Enterprise Co. Ltd. |
| Swiss Krono Group AG |
| Weyerhaeuser Company |
| Duratex S.A. |
| Pfleiderer Group SE |
| Celulosa Arauco y Constitución S.A. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between North American general contractors and integrated fiberboard producers lock in multi-year supply access while fixing resin and fiber input costs against petrochemical index volatility. These agreements concentrate pricing power among vertically integrated mills with captive pulp supply, squeezing regional converters dependent on spot resin markets.
Pricing Analysis
Cost-plus contracts with methanol and urea-formaldehyde resin indexation dominate procurement between tier-one contractors and integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Class A panels from domestic-grade Class B alternatives and uncertified commodity board. Cost compression in standard-grade lines is intensifying because Western Canadian fiber supply constraints and rail bottlenecks elevate delivered raw material costs. Furniture manufacturers exhibit highest price sensitivity, while hospital and hospitality contractors absorbing specification premiums for moisture-resistant certified grades show lowest elasticity.
Supply Chain Analysis
Western Canada and the southeastern United States anchor global fiber supply through sawmill residue concentration and plantation pine harvesting. Production draws from ammonium polyphosphate additives sourced from German and Chinese chemical suppliers, plus wax emulsions and formaldehyde resins tied to petrochemical feedstocks. Single-source vulnerability concentrates in rail-shipment corridors through British Columbia and Alberta, where provincial harvest quotas and weather disruptions cascade to North American converter operations. Distribution runs through mill-direct national agreements with tier-one contractors, displacing fragmented regional stocking distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire-rated MDF procurement is consolidating under platform-style national contracting, where interoperability between CE-marked and ASTM-certified product lines determines supplier stickiness across multi-jurisdictional project portfolios.
For Market Incumbents: Compound specification influence through captive resin production and direct mill contracts with Turner Construction and Clark Construction that bypass distributor intermediaries. Cross-laminated timber substitution in Scandinavian and Pacific Northwest commercial projects threatens medium-density fiberboard volumes for structural fire-rated assemblies. Backward integration into formaldehyde and methanol production offsets petrochemical feedstock volatility compressing converter margins. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Poland and Portugal opens EU public-sector tender access without legacy brominated additive reformulation burdens. India's Smart Cities Mission metro rail stations and government hospital expansions in Mumbai and Delhi present the most penetrable white-space, given absent domestic fire-rated panel capacity. Lead with moisture-resistant Class A grades targeting healthcare humidity-fire overlap specifications where incumbent coverage remains thin. For Investors and Strategic Acquirers: Regional CE-marked specialists with embedded intumescent chemistry capabilities and sub-scale European mill networks represent the optimal acquisition target archetype. Long-term viability hinges on REACH-compliant additive transitions and green-building certification bundling as specification criteria converge. Watch for ECHA substance evaluation dossier finalizations on legacy brominated flame retardants as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive formaldehyde supply shields margins from methanol index swings at German and Polish mills. |
| CE Marking Fast-Track Investment | Notified body partnerships in Portugal accelerate EU Construction Products Regulation compliance for Asian exporters. |
| Direct Mill Contracting with Tier-One Contractors | National agreements with Turner Construction and Clark Construction displace regional distributor value capture. |
| Moisture-Resistant Grade Capacity Addition | Florida and Texas healthcare retrofits demand overlapping humidity tolerance and NFPA 101 flame-spread compliance. |
| REACH-Compliant Additive Transition | Ammonium polyphosphate and expandable graphite substitutions preserve CE-marking validity against ECHA evaluation dossiers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fire-rated MDF procurement directors at tier-one general contractors, plant managers at integrated North American and European mills, and specification influencers at healthcare and hospitality design firms; and secondary validation through customs trade databases, SEC 10-K filings of listed timber conglomerates, ASTM and EN testing protocol documentation, and ECHA substance evaluation registers. Bottom-up volume triangulation across product-grade manufacturing capacities converged with top-down construction spending allocation models.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product performance tier, chemistry integration technology, end-use application intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand functions tied to high-rise construction permit data and retrofit mandate enforcement schedules. Forecast inputs incorporated mineral additive integration adoption curves and green-building certification intersection rates with fire-safety procurement checklists.
Underlying assumptions cover sustained enforcement of EU Construction Products Regulation, GB 8624, and International Building Code adoption across US jurisdictions, with deviation risk concentrated in municipal fire-code harmonization delays and petrochemical feedstock price discontinuities. Recalibration cycles align with material shifts in ECHA regulatory timelines and tier-one contractor procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Vinyl Windows Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Indonesia Cement Market