
 Reinforced Ultrafine Mill Market | 2026-2036
Reinforced Ultrafine Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforced Ultrafine Mill Market Analytics
Aftermarket service revenue for spare grinding media and classifier components is reshaping margin distribution across the reinforced ultrafine mill value chain. Hosokawa Micron Powder Systems leverages its North American service network to capture recurring revenue from installed vertical mill bases. NETZSCH Grinding & Dispersing anchors its competitive position through deep specialization in wet milling technology for pigments and coatings. Shandong Alpa Powder Technology dominates domestic supply of air classifier systems serving China's battery materials sector.
Reinforced ultrafine mills employ high-strength alloy grinding elements and precision-engineered classifier rotors to achieve particle sizes below 10 microns in continuous duty cycles, serving mineral processing and advanced materials synthesis where liberation efficiency and surface area control determine downstream process economics. Wet milling technology leads unit shipments for battery cathode precursor production, while dry milling configurations sustain higher margins in cement and mining applications where thermal sensitivity is less critical. Nano-milling capacity remains concentrated among custom-engineered large-scale installations serving pharmaceutical and electronics-grade ceramic demand.
EPA emissions standards for particulate matter constrain dry milling system designs in US industrial installations, while REACH compliance in Europe shapes material selection for grinding chamber linings and classifier coatings. China's MEE enforces dust concentration limits that accelerate replacement cycles for legacy equipment in cement and mining operations. Stakeholders must monitor evolving battery material specifications and corresponding particle size distribution requirements as cathode chemistry transitions reshape equipment selection criteria.
Market Dynamics
The reinforced ultrafine mill sector is experiencing structural pressure from battery cathode precursor specifications tightening particle size distribution tolerances below 5 microns, forcing equipment retrofits across existing installed bases.
Growth Catalysts
- GB Standard 4915-2013 Revisions:China's MEE dust emission limits for cement and mining operations are accelerating replacement demand for legacy dry milling systems that cannot meet 10 mg/m³ stack concentration ceilings.
- Lithium Iron Phosphate Expansion:Wet milling configurations for LFP cathode production are pulling capacity additions in Jiangsu and Sichuan provinces where battery material integrators are consolidating supply chains.
- Rhine Chemical Corridor Investment:Germany's specialty chemical processors along Ludwigshafen-Basel are expanding nano-milling capacity for pigment and coating applications requiring sub-micron particle engineering.
Market Restraints
- High-Chromium Alloy Supply Concentration:Grinding media production depends on South African ferrochrome and Chinese casting capacity, exposing mill operators to alloy price volatility and logistics bottlenecks.
- EPA PM2.5 Compliance Costs:US installations face capital-intensive baghouse and scrubber retrofits to meet National Ambient Air Quality Standards, extending project payback periods for dry milling upgrades.
- Technical Floor at 500 Nanometers:Conventional bead mill architectures hit particle size limits for pharmaceutical active ingredient applications, ceding share to jet milling and precipitation technologies.
Strategic Opportunities
- Solid-State Battery Material Processing:Sulfide electrolyte synthesis requires contamination-free ultrafine grinding, creating specification gaps that specialized ceramic-lined mill suppliers can fill.
- India PLI Scheme for ACC Batteries:Production-linked incentives for advanced chemistry cell manufacturing are attracting grinding equipment vendors to Gujarat and Tamil Nadu industrial corridors.
- Predictive Maintenance Integration:Vibration monitoring and classifier rotor wear sensing via IoT sensors is digitizing service revenue models for installed vertical mill fleets.
Industry Challenges
- Classifier Rotor Balancing Expertise:Precision-engineered high-speed rotors operating above 15,000 RPM require specialized technicians that OEMs and third-party service providers struggle to recruit and retain.
- Legacy DCS Integration Complexity:Brownfield cement and mining sites operate proprietary distributed control systems that resist seamless connectivity with modern mill automation platforms, delaying digital upgrade timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforced Ultrafine Mill Market |
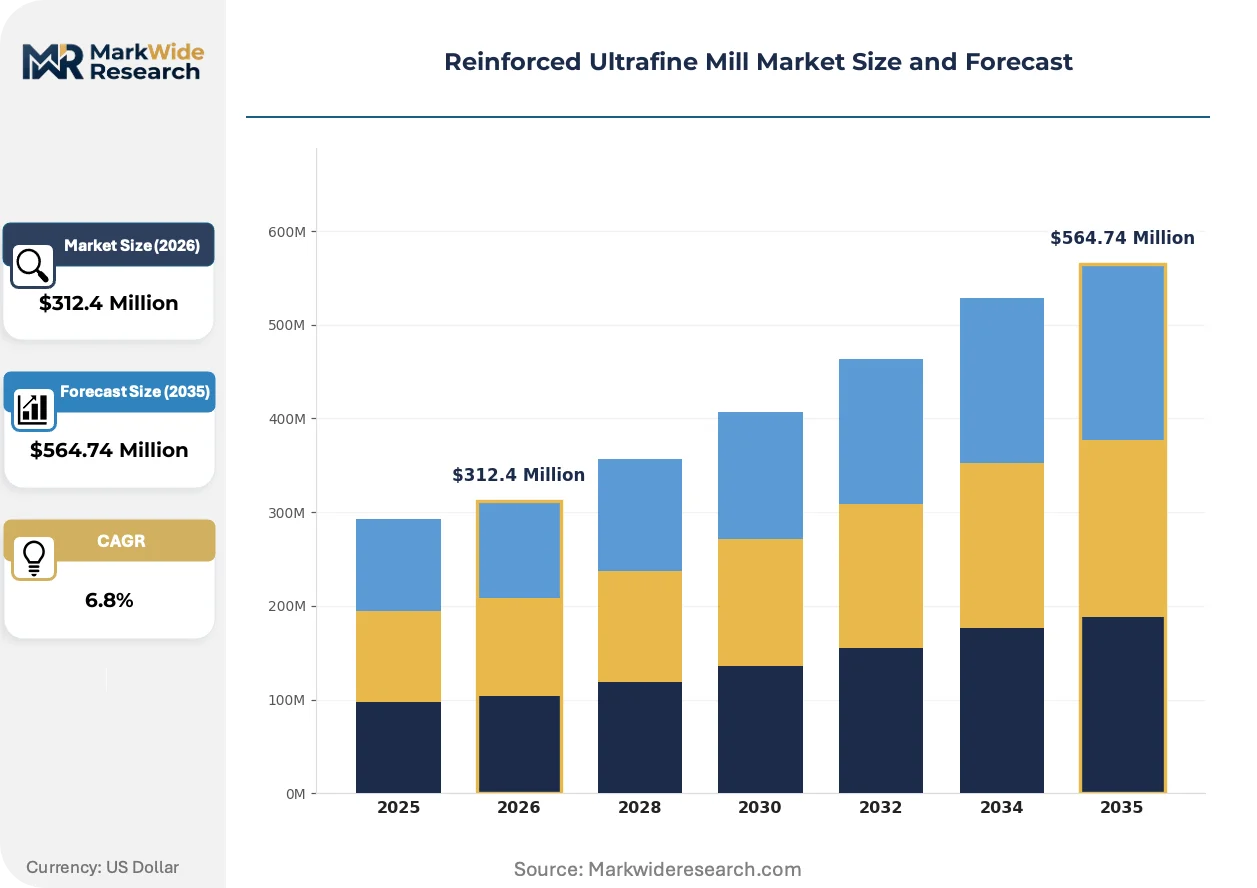
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Mills, Horizontal Mills, Ring Mills, Air Classifiers End User: Cement Industry, Mining Sector, Chemicals Manufacturing, Metal Processing Technology: Wet Milling, Dry Milling, Nano-Milling, Cryogenic Grinding Capacity: Small Scale, Medium Scale, Large Scale, Custom Capacity |
| Companies Covered | Hosokawa Micron Powder Systems, NETZSCH Grinding & Dispersing, Shandong Alpa Powder Technology Co., Ltd., Guilin Hongcheng Mining Equipment Manufacture Co., Ltd., Hosokawa Alpine, FLSmidth, Metso Outotec, CITIC Heavy Industries, Kurimoto Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforced Ultrafine Mill Market Evolving Landscape
Equipment intelligence and emissions compliance are converging to redefine competitive differentiation, with suppliers racing to embed real-time particle size analytics and remote diagnostics into standard mill configurations.
Advanced process control software is digitizing operator intervention in continuous grinding circuits. Battery material producers in South Korea and Japan are deploying machine learning algorithms to stabilize classifier cut points within 0.5 micron variance. This capability is compressing yield loss and reducing off-spec batches that previously required reprocessing.
REACH Annex XVII restrictions on chromium VI compounds are forcing grinding chamber lining material transitions across EU chemical processing installations. Equipment vendors are qualifying alumina ceramic and silicon carbide alternatives that eliminate hexavalent chromium exposure risks. German pigment manufacturers along the Lower Rhine are piloting these linings in high-throughput wet milling trains ahead of 2026 compliance deadlines.
Service unbundling is fragmenting traditional mill procurement patterns. Mining operators in Western Australia and Chile are separating capital equipment purchases from multi-year maintenance and grinding media supply contracts. This shift is pressuring OEM margin structures while creating openings for specialized consumables suppliers and independent service integrators to capture recurring revenue streams previously captive to original equipment vendors.
Reinforced Ultrafine Mill Market Segmentation
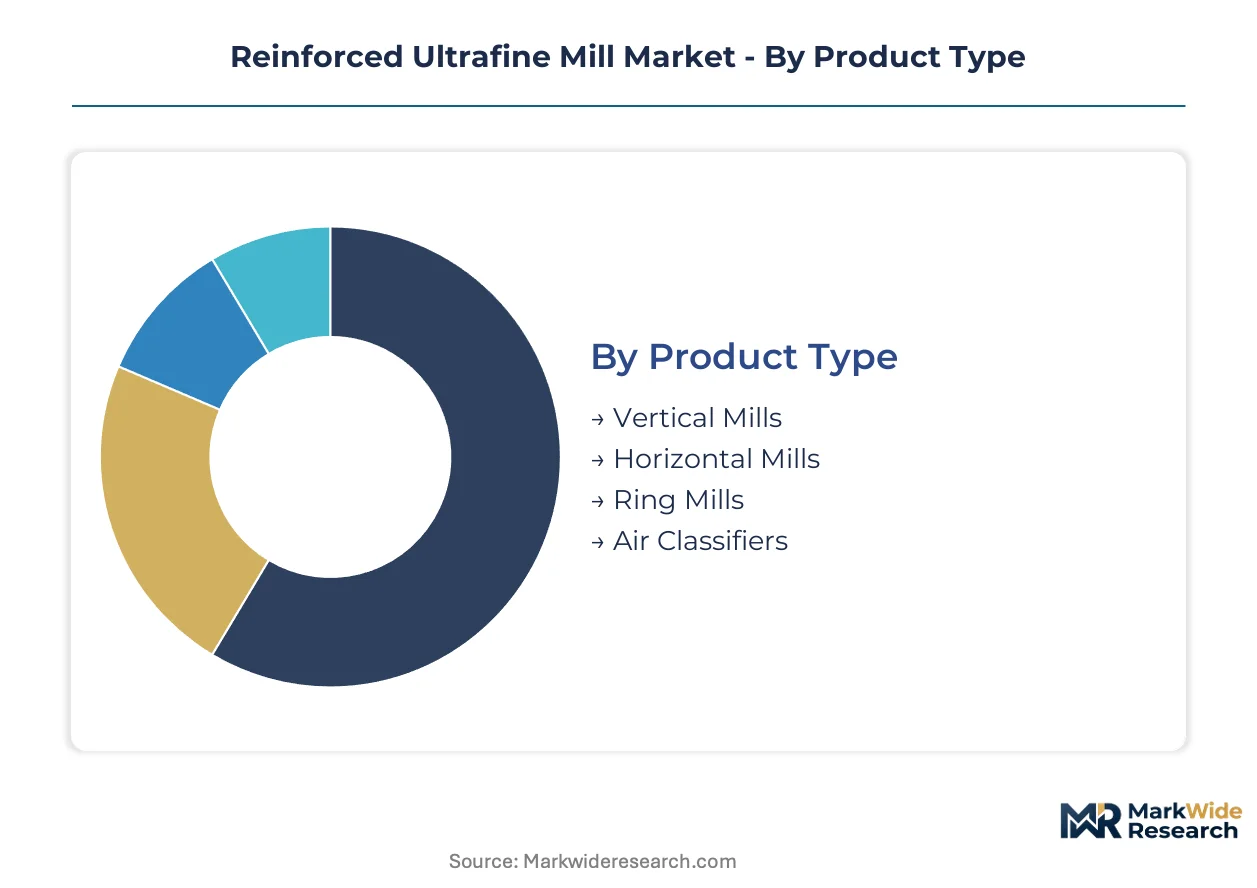
Segmentation in reinforced ultrafine milling reveals how equipment specifications diverge across duty cycles and material systems. Product architecture, processing technology, and scale requirements each create distinct procurement criteria that reshape supplier positioning and aftermarket economics.
Product Type:
Mature vertical mill designs dominate installed bases across heavy industry, while emerging horizontal configurations are gaining traction in continuous chemical processing applications.
- Vertical Mills:High-strength alloy grinding elements arranged in a vertical spindle configuration achieve particle sizes below 10 microns in continuous duty cycles. Mining operators in Australia are expanding vertical mill capacity for mineral liberation as ore grades decline and liberation efficiency demands intensify.
- Horizontal Mills:Horizontal chamber orientation enables superior heat dissipation and media retention in high-throughput wet milling trains. Battery material integrators in Jiangsu province are consolidating supply chains around horizontal configurations for lithium iron phosphate cathode precursor production.
- Ring Mills:Annular grinding zone geometry suits intermediate particle size reduction with lower specific energy consumption.
- Air Classifiers:Precision-engineered classifier rotors operating above 15,000 RPM separate fine fractions for downstream surface area control.
Vertical mills handle the majority of throughput; horizontal mills are expanding most quickly on share as battery material specifications tighten.
End User:
Cost tier differentiation separates commodity mineral processing from high-value advanced materials synthesis, with margin structures varying by thermal sensitivity and contamination tolerance.
- Cement Industry:Dry milling configurations sustain higher margins where thermal sensitivity is less critical and stack emission compliance drives replacement cycles. China's MEE dust concentration limits are accelerating replacement demand for legacy equipment that cannot meet 10 mg/m³ ceilings.
- Mining Sector:Mineral liberation efficiency determines downstream process economics in copper, gold, and rare earth extraction. Western Australian operators are separating capital equipment purchases from multi-year grinding media supply contracts, fragmenting traditional procurement patterns.
- Chemicals Manufacturing:REACH Annex XVII restrictions on chromium VI compounds are forcing grinding chamber lining material transitions across EU chemical processing installations.
- Metal Processing:Precision particle engineering serves powder metallurgy and additive manufacturing feedstock preparation.
Cement applications anchor volume demand; chemicals manufacturing shows the steepest expansion trajectory as nano-milling capacity expands along Germany's Rhine corridor.
Technology:
Volume concentration in wet milling for battery materials contrasts with margin concentration in dry systems for mining and cement, while nano-milling remains custom-engineered at limited scale.
- Wet Milling:Slurry-based processing with bead or ball media achieves sub-micron particle sizes in continuous circulation loops. South Korean and Japanese battery material producers are deploying machine learning algorithms to stabilize classifier cut points within 0.5 micron variance.
- Dry Milling:Air-swept operation eliminates thermal degradation risks in heat-sensitive materials while demanding intensive emission control. EPA PM2.5 compliance costs are extending project payback periods for dry milling upgrades in US installations.
- Nano-Milling:Specialized ceramic-lined configurations achieve particle sizes below 100 nanometers for pharmaceutical and electronics-grade applications.
- Cryogenic Grinding:Liquid nitrogen or carbon dioxide cooling enables brittle fracture of elastomers and temperature-sensitive polymers.
Wet milling leads unit shipments; nano-milling commands the highest value per installed kilowatt.
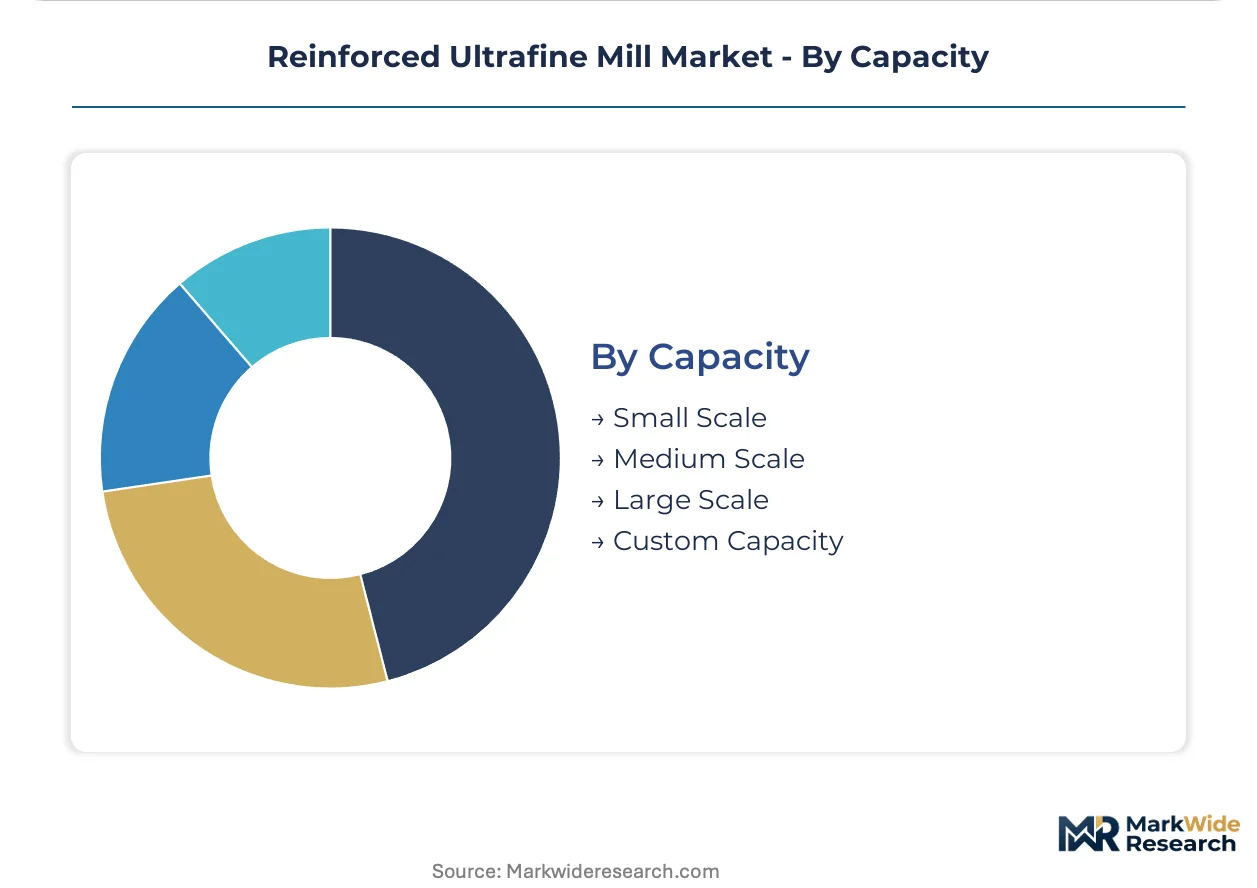
Capacity:
Customer type segmentation separates standardized offerings from engineered solutions, with service unbundling creating new revenue models across the scale spectrum.
- Large Scale:Integrated grinding-classifier trains exceeding 500 kW motor rating serve centralized mineral processing and cement clinker grinding. Brownfield cement sites operate proprietary distributed control systems that resist seamless connectivity with modern mill automation platforms.
- Custom Capacity:Application-specific engineering addresses contamination-free requirements for solid-state battery sulfide electrolyte synthesis. Specialized ceramic-lined mill suppliers are filling specification gaps in emerging battery chemistry transitions.
- Medium Scale:Modular skid-mounted systems enable rapid deployment in greenfield chemical processing installations.
- Small Scale:Pilot and R&D configurations support process development and quality control sampling.
Large scale installations absorb the majority of capital expenditure; custom capacity solutions are climbing the fastest as battery material specifications evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Mining operators in Australia absorb premium equipment costs for liberation efficiency gains, while cement producers in emerging markets prioritize capital discipline over performance specifications.
China
Battery material integrators in Jiangsu and Sichuan provinces are consolidating supply chains around wet milling capacity for lithium iron phosphate production. The Ministry of Ecology and Environment enforces GB Standard 4915-2013 revisions that accelerate replacement of legacy dry milling systems unable to meet 10 mg/m³ dust concentration ceilings. Shandong Alpa Powder Technology anchors domestic air classifier supply serving the battery materials sector.
Germany
Specialty chemical processors along the Ludwigshafen-Basel corridor are expanding nano-milling capacity for pigment and coating applications requiring sub-micron particle engineering. REACH Annex XVII restrictions on chromium VI compounds are forcing grinding chamber lining material transitions across EU chemical processing installations. The Lower Rhine region pilots alumina ceramic and silicon carbide alternatives ahead of 2026 compliance deadlines.
United States
EPA emissions standards for particulate matter constrain dry milling system designs in industrial installations, with National Ambient Air Quality Standards driving capital-intensive baghouse and scrubber retrofits. Hosokawa Micron Powder Systems leverages its North American service network to capture recurring revenue from installed vertical mill bases. Mining operations in the Mountain West extend project payback periods for dry milling upgrades.
Australia
Mining operators in Western Australia are expanding ultrafine grinding capacity for mineral liberation as ore grades decline and liberation efficiency demands intensify. Procurement patterns fragment as operators separate capital equipment purchases from multi-year grinding media supply contracts. The Pilbara region concentrates demand for high-throughput vertical mill configurations serving iron ore and rare earth extraction.
India
Production-linked incentives for advanced chemistry cell manufacturing under the PLI scheme are attracting grinding equipment vendors to Gujarat and Tamil Nadu industrial corridors. The Bureau of Indian Standards shapes equipment specifications for domestic battery material production. Chemical processing clusters in Maharashtra and Gujarat pilot modular skid-mounted systems for rapid greenfield deployment.
Reinforced Ultrafine Mill Market Competitive Landscape
Capability concentration sits with specialized grinding technology developers; scale advantage sits with diversified heavy machinery conglomerates. The vendor base separates into three tiers: precision-engineered specialists serving battery and pharmaceutical specifications, diversified mining equipment suppliers leveraging installed base relationships, and regional fabricators competing on delivered cost. Dominant competitive moves include service unbundling to capture recurring revenue and ceramic lining material transitions to meet REACH compliance.
Among Japanese precision equipment specialists, Kurimoto Ltd. and Hosokawa Micron Powder Systems exemplify the capability-driven tier where vertical mill specialization supports aftermarket service models. German technology developers including NETZSCH Grinding & Dispersing and Hosokawa Alpine occupy positions anchored in wet milling expertise for pigments and coatings. Chinese fabricators such as Shandong Alpa Powder Technology Co., Ltd. and Guilin Hongcheng Mining Equipment Manufacture Co., Ltd. represent scale-oriented regional supply serving domestic battery material demand.
| Leading Market Players |
|---|
| Hosokawa Micron Powder Systems |
| NETZSCH Grinding & Dispersing |
| Shandong Alpa Powder Technology Co., Ltd. |
| Guilin Hongcheng Mining Equipment Manufacture Co., Ltd. |
| Hosokawa Alpine |
| FLSmidth |
| Metso Outotec |
| CITIC Heavy Industries |
| Kurimoto Ltd. |
| Others |
Value Network & Pricing Analysis
South African ferrochrome concentration for high-chromium grinding media anchors upstream cost volatility, pushing margin pools downstream toward aftermarket service contracts and consumables supply. Battery material integrators in Jiangsu province now unbundle capital equipment from multi-year grinding media agreements, fragmenting traditional OEM pricing power.
Pricing Analysis
Aftermarket service revenue from spare classifier rotors and grinding media supply drives lifetime value capture across installed vertical mill bases. Three-tier pricing structure across premium ceramic-lined configurations, standard alloy systems, and economy fabricated mills separates procurement tiers by contamination tolerance and duty cycle intensity. Cost compression in standard alloy segments is intensifying because Chinese fabricators compete on delivered cost for domestic battery material demand. Cement producers in emerging markets exhibit highest price sensitivity, while pharmaceutical and solid-state battery material processors absorb premium pricing for contamination-free nano-milling capacity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for large-scale grinding-classifier trains, straining working capital for regional fabricators. Grinding media production draws from South African ferrochrome, Chinese casting capacity, and German precision-engineered ceramic alternatives. Supply chain risk centers on single-source vulnerability for high-purity alumina ceramic linings qualified under REACH Annex XVII. Distribution runs through OEM direct sales for large installations, independent service integrators for aftermarket capture, and regional distributors for modular skid-mounted systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward battery material integrators consolidating supply chains in Jiangsu and Sichuan, fragmenting traditional equipment vendor pricing leverage.
For Market Incumbents: Pre-empt service unbundling by capturing grinding media supply contracts before independent consumables suppliers establish footholds in Western Australian mining corridors. Deepen backward integration into high-chromium alloy casting capacity to offset South African ferrochrome price volatility threatening margin stability. For New Entrants and Emerging Players: Pursue modular skid-mounted wet milling configurations for India's PLI-backed ACC battery corridors in Gujarat and Tamil Nadu, where domestic fabrication cost advantages outweigh established vendor relationships. Lead with predictive maintenance integration as a differentiated service layer for brownfield cement sites struggling with legacy DCS integration complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across custom-engineered nano-milling capacity serving pharmaceutical and solid-state battery applications, favoring specialized ceramic-lined mill suppliers over diversified heavy machinery conglomerates. Target acquisition candidates with qualified contamination-free processing credentials and established relationships with sulfide electrolyte developers. Watch for battery cathode chemistry transitions requiring sub-500 nanometer particle specifications as the inflection signal for premium capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Lining Material Transition | REACH Annex XVII compliance deadlines in 2026 force alumina and silicon carbide qualification across EU chemical processing installations. |
| Predictive Maintenance Integration | IoT-enabled vibration monitoring digitizes service revenue for installed vertical mill fleets in Australian mining operations. |
| Backward Integration into Grinding Media | South African ferrochrome volatility drives OEM captive supply strategies for high-chromium alloy production. |
| Modular Skid-Mounted System Deployment | Rapid greenfield installation capability captures India's PLI scheme capacity additions in Gujarat and Tamil Nadu. |
| Solid-State Battery Material Qualification | Contamination-free sulfide electrolyte processing creates specification gaps for specialized ceramic-lined mill suppliers. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this reinforced ultrafine mill analysis. Primary fieldwork combined with trade data from customs records, SEC filings from listed heavy machinery manufacturers, and MEE emission standard documentation enabled bottom-up and top-down triangulation across market sizing.
Scenario-bracketing around battery material specification tightening and REACH compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, processing technology, end-use industry, and regional production hub concentration. CAGRs derived from equipment shipment trajectories, capacity utilization rates, and replacement cycle analysis for legacy dry milling systems unable to meet 10 mg/m³ dust concentration ceilings.
Sensitivities concentrate around cathode chemistry transitions, ferrochrome price volatility, and emission standard enforcement intensity. Forecasts reflect documented assumptions regarding equipment lifecycles and technology substitution patterns. Macroeconomic contraction, regulatory timeline acceleration, or breakthrough jet milling adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Dynamic Compactor Market