
 Quarry Tiles Market | 2026-2036
Quarry Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Quarry Tiles Market Analysis
Specialty tile distributor networks is reconfiguring around regional logistics hubs and direct-to-contractor digital platforms. Mohawk Industries leverages its captive clay sourcing and kiln capacity across multiple states to sustain cost advantages in unglazed production. Metropolitan Ceramics competes through deep stock-keeping-unit breadth and rapid fulfillment for commercial renovation timelines. Emser Tile anchors its position via showroom-level specification support that locks architects into repeat commercial projects.
Quarry tiles are dense, vitreous ceramic units fired at temperatures exceeding 1,100 degrees Celsius, composed primarily of natural shale and flint clay with low water absorption rates below three percent. Their primary purpose is to provide durable, slip-resistant surfacing in high-traffic wet environments such as commercial kitchens, food processing plants, and institutional locker rooms. Unglazed quarry tiles dominate volume shipments due to their superior traction profile and lower unit cost in industrial food service settings. The commercial end-use segment captures the deepest margin pools, driven by specification-driven replacement cycles in hospitality and healthcare facilities. Custom sizing remains a niche but structurally important category, as institutional buyers with legacy dimensional requirements generate sticky, long-tail revenue streams that standard product lines cannot easily displace.
The U.S. EPA regulates kiln emissions and hazardous air pollutants under the National Emission Standards for Hazardous Air Pollutants for clay ceramics manufacturing, while OSHA mandates slip resistance thresholds in commercial food preparation zones that directly influence quarry tile texture specifications. The EU Green Deal and REACH chemical restrictions are beginning to shape export-oriented producers' formulation choices, particularly for glazes containing heavy metal pigments. Stakeholders must monitor how building code harmonization across state jurisdictions affects specification portability and whether emerging cold-pressed manufacturing techniques can satisfy both regulatory compliance and traditional performance benchmarks without premium pricing.
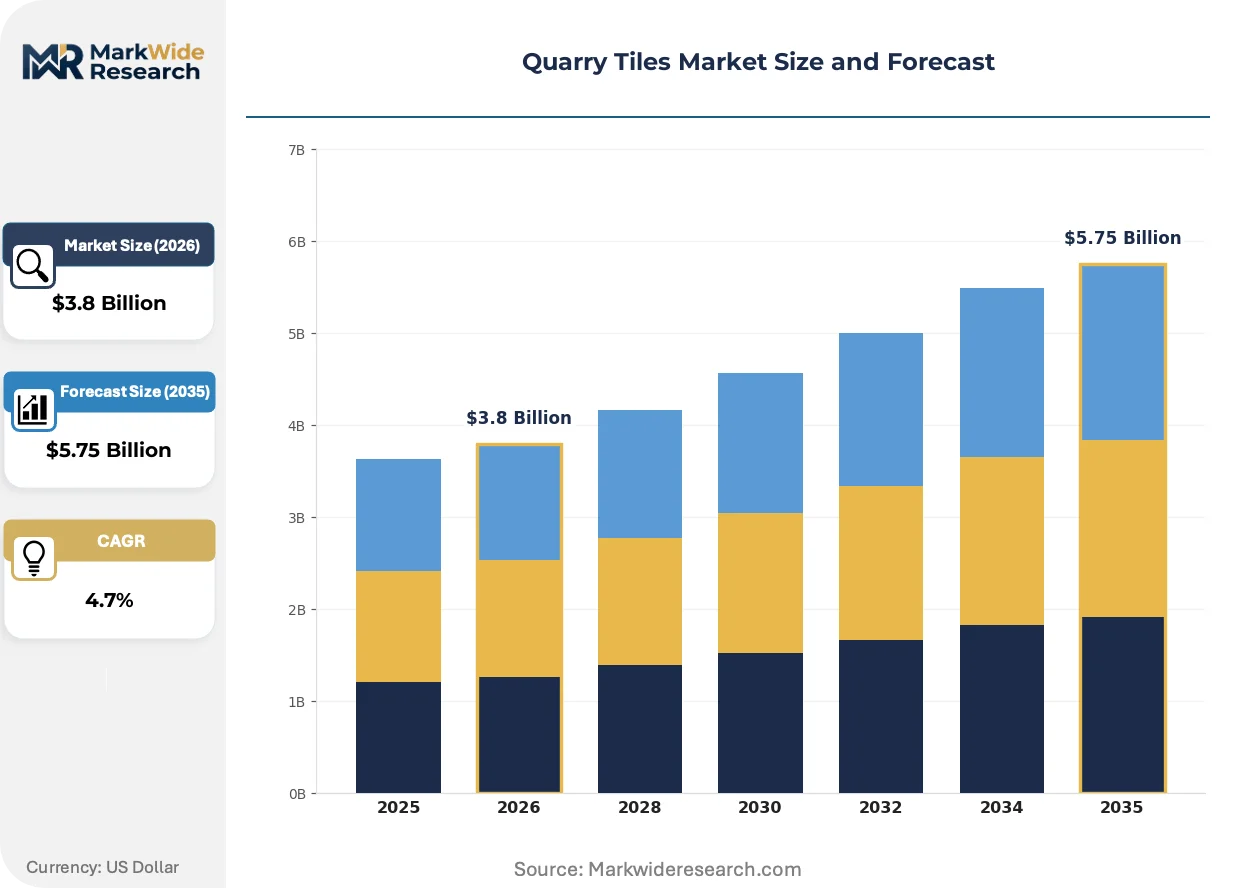
Market Dynamics
The quarry tiles market is being reshaped by tightening EPA volatile organic compound regulations for ceramic manufacturing, which are forcing reformulation investments across domestic production facilities and compressing margins for smaller kiln operators unable to absorb compliance costs.
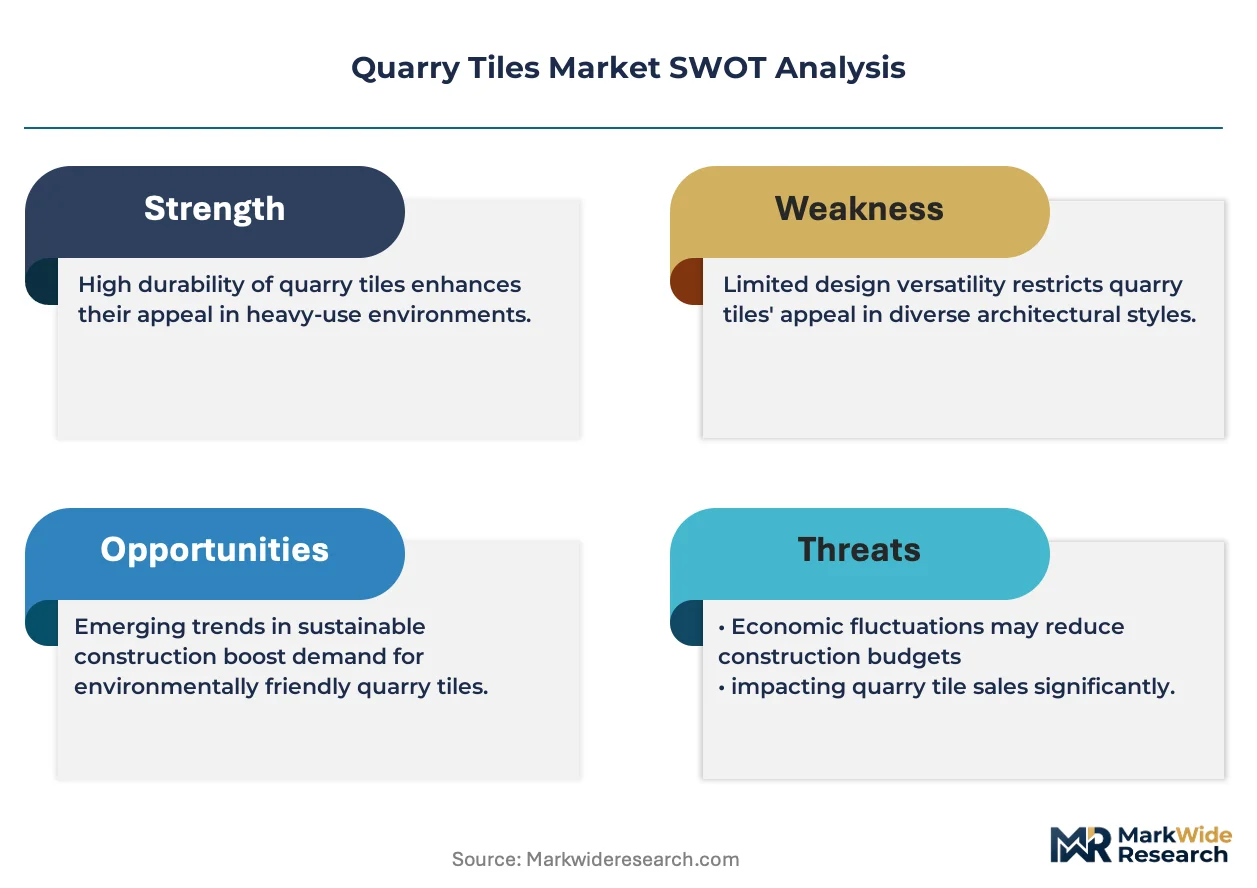
Growth Catalysts
- Commercial kitchen expansion:Hospitality chains in the American South are specifying quarry tile flooring for slip resistance and thermal durability in high-traffic food preparation zones.
- OSHA slip resistance mandates:Federal workplace safety thresholds for commercial food preparation zones directly drive specification of textured unglazed quarry tile surfaces.
- Shale and flint clay availability:Captive mineral reserves in multiple U.S. states sustain cost-competitive unglazed production against imported alternatives.
Market Restraints
- Natural gas price volatility:Kiln firing temperatures exceeding 1,100 degrees Celsius create exposure to energy input cost swings that erode production economics.
- Concentrated clay sourcing:Dependence on specific Appalachian shale deposits creates geographic supply risk if extraction permits face environmental review delays.
- Porcelain tile substitution:Thin-format porcelain with printed surface textures is capturing renovation specifications where traction requirements are less stringent.
Strategic Opportunities
- Healthcare facility renovation:Institutional locker rooms and physical therapy spaces represent underpenetrated specification channels for slip-resistant quarry tile surfacing.
- EU Green Deal alignment:REACH-compliant heavy-metal-free glaze formulations open export pathways to European food processing equipment manufacturers.
- Direct-to-contractor platforms:Digital procurement channels are compressing distributor markups and accelerating specification-to-delivery timelines for commercial renovation projects.
Industry Challenges
- Kiln operator skill scarcity:Firing unglazed quarry tile to vitreous density without warping requires experienced temperature curve management that retiring workforces possess.
- Legacy dimensional matching:Institutional buyers with decades-old installations demand custom sizing that disrupts standard production runs and inventory turns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quarry Tiles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unglazed, Glazed, Textured, Polished End Use: Residential, Commercial, Industrial, Outdoor Size: Small, Medium, Large, Custom Color: Red, Brown, Grey, Beige |
| Companies Covered | Shell, Mohawk Industries, Emser Tile, Polycor Inc., Florim Ceramiche S.p.A, Metropolitan Ceramics, Ceramica Saloni, Mosa, Casalgrande Padana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quarry Tiles Market Emerging Trajectories
Digital specification tools and cold-pressed manufacturing techniques are disrupting traditional quarry tile production economics, compressing lead times while testing whether new processes can match the performance benchmarks of conventionally fired ceramic.
Cold-pressed forming technology is migrating from experimental pilot lines to scaled production for specialty dimensional orders. Commercial renovation contractors with compressed project timelines are adopting these tiles for rapid fulfillment of legacy size requirements. The structural consequence is pressure on traditional kiln operators to justify firing cost premiums against lower-energy alternatives.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is intensifying monitoring of clay ceramics manufacturing facilities. Kiln operators face capital expenditure requirements for scrubber upgrades and continuous emissions monitoring systems. Smaller producers in shale-rich regions are consolidating or exiting rather than absorbing compliance infrastructure costs.
Architect specification behavior is fragmenting across digital and physical channels. Younger specifiers in commercial hospitality projects are bypassing traditional distributor showrooms for manufacturer-direct BIM object libraries. This channel compression is most visible in fast-casual restaurant construction clusters where speed-to-groundbreaking dictates procurement patterns.
Quarry Tiles Market Segmentation
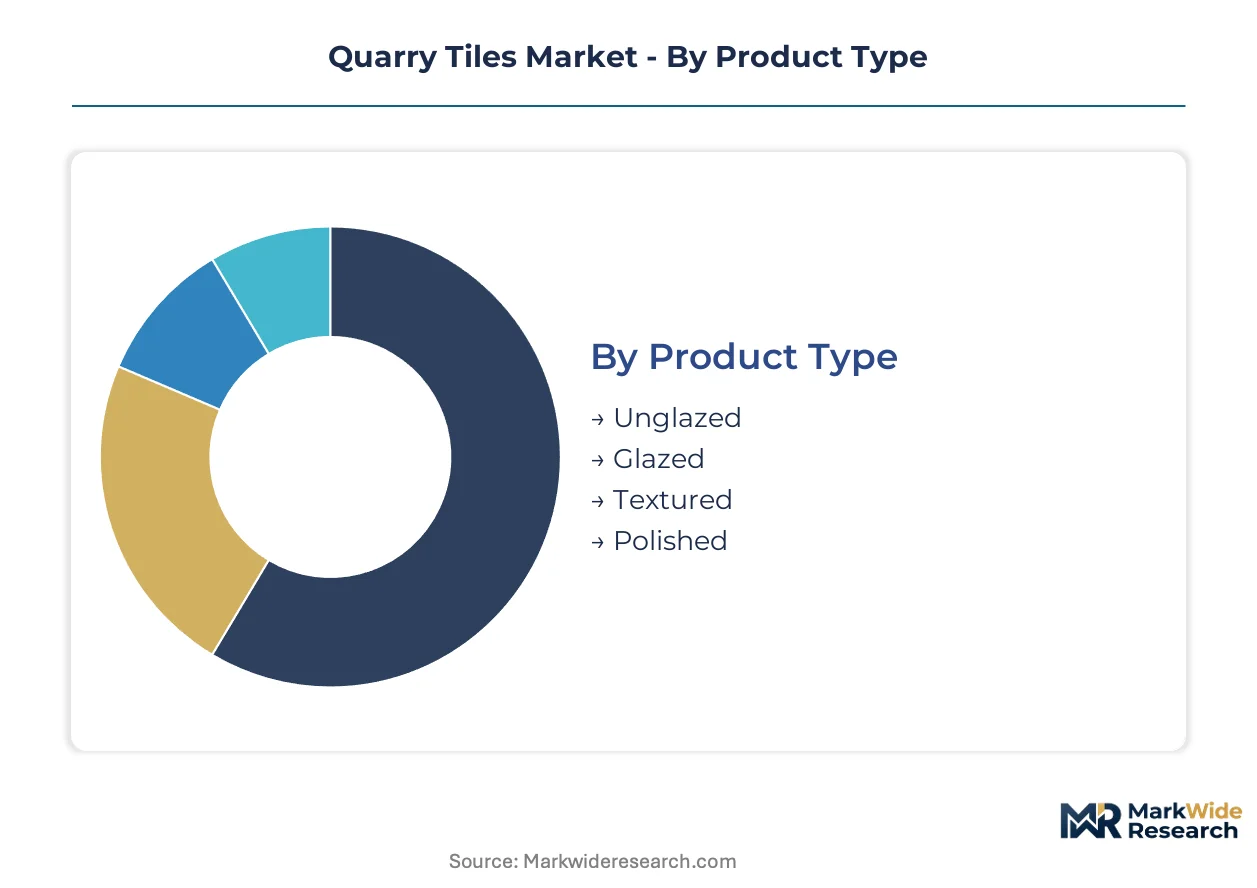
Quarry tile segmentation reveals starkly different replacement cycles across product categories. Unglazed commercial flooring turns over every 7-10 years under heavy thermal cycling, while residential installations persist 20+ years, creating divergent revenue recognition patterns for manufacturers.
Product Type:
Unglazed tiles rotate fastest through food service renovation cycles. Glazed and polished variants sit longer in specification pipelines due to architect review timelines.
- Unglazed:Dense vitreous ceramic fired above 1,100°C with natural shale and flint clay composition. Commercial kitchens in American South hospitality chains specify these for OSHA-mandated slip resistance and thermal shock durability under continuous griddle and fryer exposure. Replacement cycles compress where thermal cycling accelerates surface degradation.
- Glazed:Surface-coated variants with glass-forming mineral overlays that introduce color consistency but reduce traction coefficients. Demand concentrates in healthcare facility lobbies and retail front-of-house where aesthetic specification outweighs slip-critical performance requirements.
- Textured:Mechanical or chemical surface modification for enhanced coefficient of friction. Food processing plants specify these for USDA-inspected zones requiring drainage channel integration.
- Polished:Burnished surface finish achieved through diamond abrasion post-firing. Residential entryways and hospitality vestibules specify these where visual refinement supersedes traction needs.
Unglazed dominates installed base across commercial food service. Glazed is where expansion concentrates in healthcare renovation specifications.
End Use:
Cost tier stratification separates specification behavior. Industrial buyers prioritize unit economics and thermal performance. Commercial segments absorb premium pricing for code compliance.
- Commercial:Hospitality chains, healthcare systems, and institutional food service drive specification volume. OSHA slip resistance mandates and EPA emissions compliance create dual regulatory pressure that favors domestic unglazed supply. Margin pools deepen where replacement cycles align with franchise renovation schedules.
- Industrial:Food processing plants, beverage manufacturing, and pharmaceutical clean rooms demand chemical resistance and thermal shock performance. Shale-rich Appalachian sourcing sustains cost-competitive supply against imported porcelain alternatives.
- Residential:Mudrooms, patios, and basement applications specify quarry tile for moisture resistance. Volume trails commercial segments but generates stable replacement revenue in legacy housing stock.
- Outdoor:Pool decks, commercial walkways, and municipal plazas require freeze-thaw durability. Specifications concentrate in Sun Belt geographies with minimal frost penetration risk.
Industrial captures the deepest margin pools through specification-driven compliance requirements. Commercial is expanding most quickly via fast-casual restaurant construction clusters.
Size:
Volume concentration favors standard dimensions that optimize kiln packing efficiency. Custom sizing disrupts production economics but locks in sticky institutional relationships.
- Custom:Legacy dimensional requirements from decades-old institutional installations demand non-standard cutting and firing protocols. Physical therapy centers and correctional facilities generate long-tail revenue streams that resist commoditization.
- Large:8-inch and larger formats reduce grout line maintenance in commercial kitchen specifications. Cold-pressed manufacturing techniques are penetrating this segment for rapid fulfillment of compressed renovation timelines.
- Medium:6-inch nominal dimensions dominate standard commercial specification. Kiln operators optimize yield around these formats to minimize warping losses at vitreous firing temperatures.
- Small:4-inch and mosaic formats serve residential backsplash and accent applications. Volume is declining as large-format porcelain captures renovation specifications.
Medium formats dominate current shipment volume. Custom sizing is where manufacturer differentiation and pricing power concentrate.
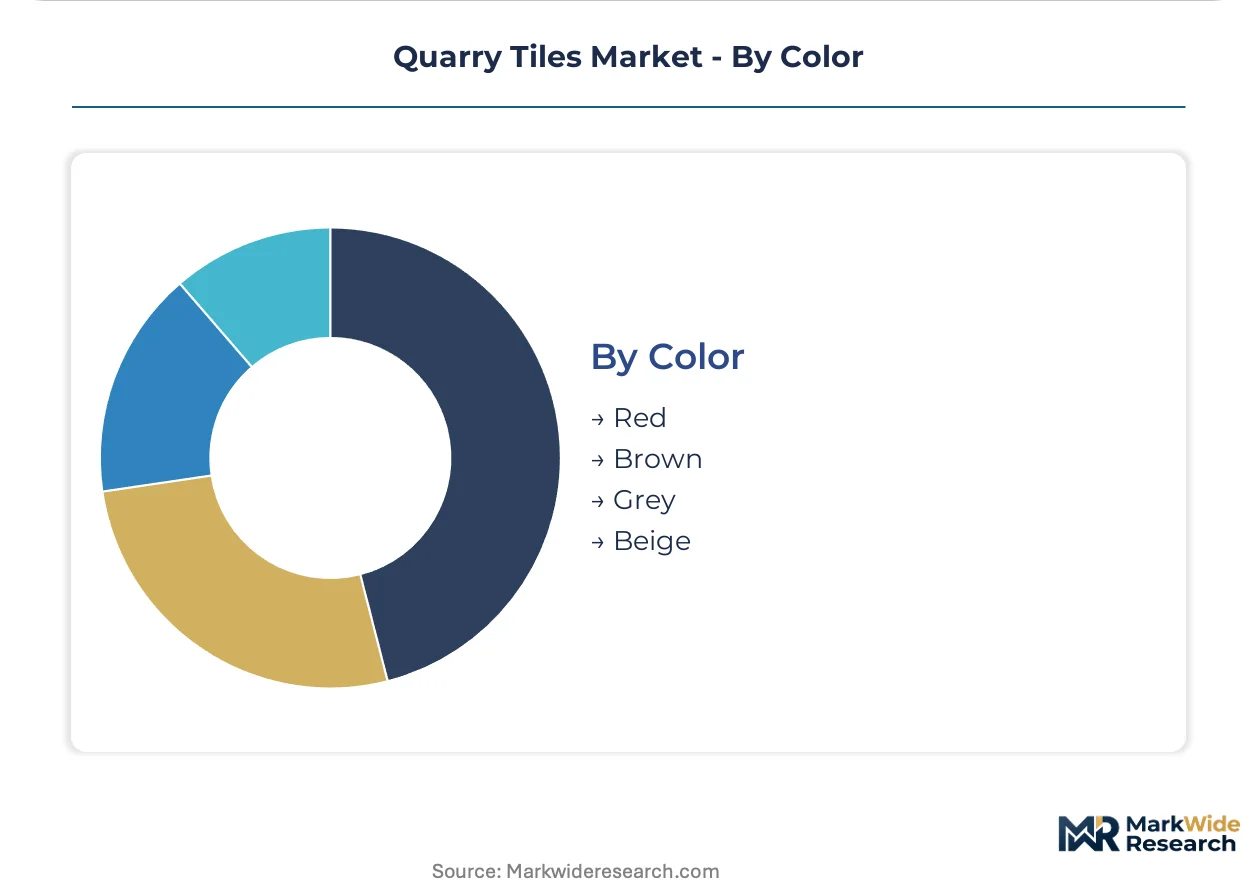
Color:
Supply concentration in natural clay deposits dictates color availability. Appalachian shale chemistry limits certain hue ranges without additive formulation.
- Red:Iron-rich shale deposits in Pennsylvania and Ohio yield natural red tones without pigment addition. Traditional pizza chain specifications favor this color for brand consistency across franchise locations.
- Brown:Manganese and iron oxide variations create earth-tone palettes. Fast-casual restaurant chains specify these for warm interior aesthetics.
- Grey:Reduced iron content and controlled oxidation produce neutral tones. Healthcare and institutional specifications favor grey for perceived cleanliness and stain concealment.
- Beige:Low-iron clay blends with calcium carbonate additions. Residential and hospitality applications specify these for brightness in limited natural light conditions.
Red holds the largest installed base from decades of food service specification. Grey is gaining share fastest in healthcare facility renovation palettes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Gulf Coast port infrastructure anchor American quarry tile distribution, moving dense ceramic units from Appalachian shale deposits to commercial construction clusters across the southern United States.
United States
Fast-casual restaurant construction in Texas and Florida drives specification volume for slip-resistant unglazed flooring. EPA National Emission Standards for Hazardous Air Pollutants enforcement is forcing kiln upgrades across Ohio and Pennsylvania production facilities. The Atlanta metropolitan area concentrates food service renovation activity where franchise operators demand rapid fulfillment timelines.
Germany
Industrial food processing equipment manufacturers specify REACH-compliant quarry tile surfacing for export-oriented production lines. The EU Green Deal chemical restrictions are eliminating heavy metal pigments from glaze formulations. The Ruhr Valley ceramic cluster is retooling cold-pressed manufacturing capabilities to serve compressed European renovation schedules.
China
Domestic hospitality construction in Guangdong and Jiangsu provinces absorbs medium-format unglazed shipments for commercial kitchen specifications. MEE emissions monitoring is tightening kiln operator compliance requirements across Shandong production zones. The Yangtze River Delta logistics hub is consolidating distributor networks around direct-to-contractor digital procurement platforms.
Italy
Luxury hospitality renovations in Tuscany and Lombardy specify polished quarry tile variants for vestibule and entryway applications. CE marking requirements for construction products are standardizing slip resistance certification across export-bound production. The Sassuolo ceramic district is maintaining specialized capacity for custom dimensional orders from institutional buyers.
Mexico
Maquiladora food processing plants in Nuevo León and Baja California demand thermal-shock-resistant flooring for USDA-inspected production zones. PROFEPA environmental enforcement is extending emissions monitoring to ceramic manufacturing facilities near Monterrey. The Mexico City metropolitan area is expanding commercial kitchen construction for domestic hospitality chains.
Quarry Tiles Market Vendor Landscape
On the supply side, the industry is consolidating around multi-state kiln operators with captive clay reserves and captive logistics networks. Regional distributors with deep stock-keeping-unit breadth compete against manufacturer-direct digital platforms for commercial renovation specifications. Two strategic archetypes dominate: vertically integrated producers with backward integration into Appalachian shale deposits, and specialty fabricators with rapid custom sizing capabilities. M&A activity is concentrating production assets among operators with scrubber-compliant facilities, while strategic partnerships between kiln operators and cold-pressed technology licensors are testing new process economics.
Within the integrated-producer tier, Mohawk Industries and Metropolitan Ceramics exemplify divergent competitive positions. Mohawk Industries leverages multi-state kiln capacity and captive mineral sourcing to sustain cost advantages in high-volume unglazed production. Metropolitan Ceramics occupies a position defined by stock-keeping-unit breadth and fulfillment velocity for compressed commercial renovation timelines. Emser Tile anchors the specification-support tier through architect-facing showroom networks that lock repeat commercial project involvement.
| Leading Market Players |
|---|
| Shell |
| Mohawk Industries |
| Emser Tile |
| Polycor Inc. |
| Florim Ceramiche S.p.A |
| Metropolitan Ceramics |
| Ceramica Saloni |
| Mosa |
| Casalgrande Padana |
| Others |
Supply Flow & Price Mechanics
The Mississippi River barge network and Gulf Coast port infrastructure anchor American quarry tile distribution, moving dense ceramic units from Appalachian shale deposits to commercial construction clusters across the southern United States. This freight corridor's cost dynamics concentrate supply-side power among multi-state kiln operators with captive mineral reserves, while downstream price differentiation separates specification-grade unglazed commercial flooring from commoditized residential alternatives.
Pricing Analysis
Volume-discount tiering structures separate franchise hospitality chains receiving pallet-rate contracts from independent contractors paying distributor markup. Three-tier pricing structure across premium specification-grade, standard commercial-grade, and economy residential-grade levels reflects certification grade and customization depth. Cost compression in economy tiers is intensifying because cold-pressed manufacturing alternatives erode firing cost premiums. Franchise hospitality buyers exhibit lowest price sensitivity due to specification lock-in, while residential renovators drive hardest bargain comparisons against porcelain substitutes.
Supply Chain Analysis
Extended payment terms from 60 to 90 days and supply-chain finance facilities have become standard procurement terms for commercial renovation contractors. Production concentrates in the United States, Germany, and China, drawing from Appalachian shale deposits, Ruhr Valley clay reserves, and Jiangsu province mineral beds. Raw material dependencies center on natural shale, flint clay, and natural gas for kiln firing. Single-source vulnerability concentrates in Pennsylvania and Ohio iron-rich shale deposits essential for natural red coloration. Distribution runs through regional logistics hubs and direct-to-contractor digital platforms competing for commercial specification volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity defines this market as digital procurement channels and cold-pressed manufacturing disrupt traditional kiln economics, creating niches for agile specialists alongside integrated volume producers.
For Market Incumbents: Insulate specification relationships through rapid custom sizing capabilities and architect-facing showroom networks that lock repeat commercial project involvement. Invest in scrubber-compliant kiln infrastructure before EPA enforcement intensifies consolidation pressure. Cold-pressed technology licensors represent emerging entrant threat requiring monitoring. For New Entrants and Emerging Players: Healthcare facility locker rooms and physical therapy spaces in the American South represent the most penetrable entry point for slip-resistant quarry tile surfacing currently served by legacy institutional suppliers. EU food processing equipment manufacturers seeking REACH-compliant heavy-metal-free glaze formulations present export white-space. Go-to-market through direct-to-contractor digital platforms bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multi-industry conglomerates with underinvested ceramic divisions lacking emissions compliance infrastructure. Long-term viability favors operators with backward integration into Appalachian shale deposits and scrubber-compliant kiln assets. Monitor EPA enforcement intensity as inflection indicator for accelerated consolidation timeline.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Manufacturing Scale-Up | Lower-energy production satisfies compressed commercial renovation timelines without premium pricing. |
| REACH-Compliant Glaze Reformulation | Heavy-metal-free formulations open EU food processing equipment export pathways. |
| Direct-to-Contractor Platform Launch | Digital procurement channels compress distributor markups and accelerate specification-to-delivery timelines. |
| Scrubber Upgrade Investment | EPA National Emission Standards compliance preserves operating permits against enforcement consolidation. |
| Custom Sizing Capability Expansion | Legacy dimensional matching locks sticky institutional relationships resisting commoditization. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with commercial kitchen specification architects, franchise facility directors, distributor procurement managers, and kiln operations engineers. Secondary validation drew from EPA emissions filings, OSHA workplace safety standards, hospitality construction permit databases, and ceramic trade association production surveys. Bottom-up shipment volume analysis triangulated against top-down construction spending allocation models.
Calibration against historical replacement cycle data and regulatory implementation timelines shaped projection methodology across the analysis window. Segmentation dimensions modeled include product type, end-use application, format size, and regional construction cluster. CAGRs derived from installed base turnover rates and new construction pipeline analysis, incorporating natural gas price volatility scenarios and cold-pressed technology penetration curves as industry-specific inputs.
Practitioners should monitor EPA enforcement intensity, natural gas price volatility, and cold-pressed manufacturing quality validation for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Decks Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Ceiling Tiles Market