
 Latin America Prefab Wood Buildings Market | 2026-2036
Latin America Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Prefab Wood Buildings Market Foresight
Buyer concentration among large-scale residential developers in Brazil and Chile is hardening as mid-sized construction firms consolidate procurement budgets toward fewer prefab suppliers. Green Magic Homes leverages its modular dome architecture to anchor demand in eco-tourism and vacation home segments across Costa Rica and Colombia. VMD sustains manufacturing scale through its Colombian production base, while E2E Chile specializes in seismic-resistant panelized systems for the Santiago metropolitan zone.
Latin America prefab wood buildings are factory-manufactured structural assemblies using engineered wood products, cross-laminated timber, or glulam frames, typically fabricated under controlled humidity conditions and transported to sites for rapid erection. These systems serve residential, commercial, and institutional clients seeking reduced construction timelines and lower on-site labor dependency. Modular homes dominate current volume flows due to standardized designs that compress project delivery schedules, while panelized structures capture expanding margin pools as architects specify custom envelope configurations. The pre-engineered construction method leads adoption in Chile and Peru where seismic engineering requirements elevate technical barriers.
Brazil's ABNT standards body and Chile's MINVU housing ministry both enforce structural performance certifications that shape product design and factory qualification requirements across the Andean and Southern Cone markets. Colombia's NSR-10 seismic code and Costa Rica's Colegio Federado de Ingenieros y Arquitectos review protocols further segment market access by compliance capability. Stakeholders must monitor evolving fire-resistance rating harmonization between national standards and ASTM/EN test methods before committing to cross-border manufacturing footprints.
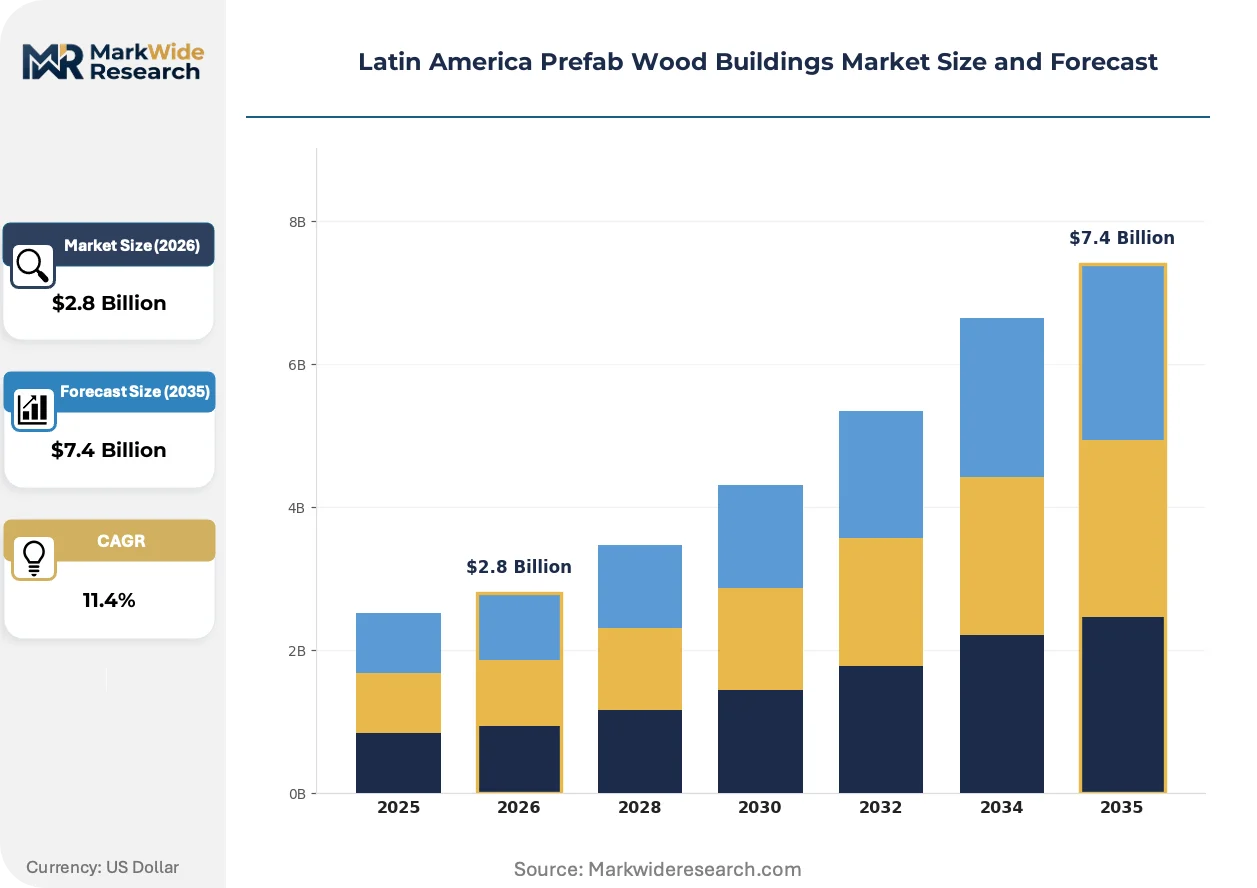
Market Dynamics
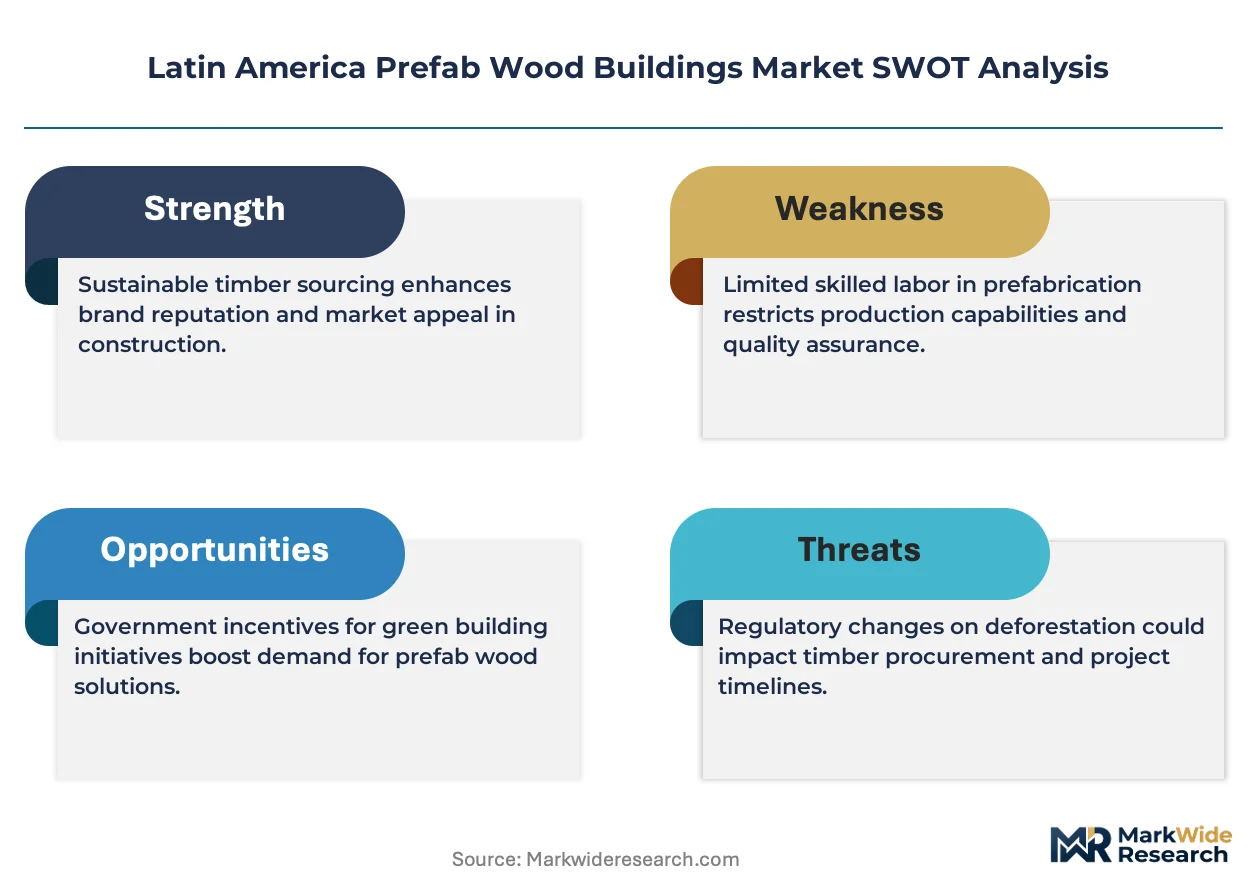
Seismic code harmonization across the Andean Ridge is compressing design cycles and forcing factory retooling investments that favor capitalized producers over craft-based competitors.
Growth Catalysts
- ABNT Fire-Safety Mandates:Brazil's tightened standards for engineered wood assemblies are disqualifying informal suppliers and consolidating procurement among certified fabricators serving São Paulo's affordable housing corridor.
- Cross-Laminated Timber:CLT panel production is displacing concrete block in mid-rise residential frames across Chile's Santiago metropolitan zone, cutting erection schedules by half.
- Eco-Tourism Developers:Costa Rica's vacation home segment is absorbing modular dome architectures for off-grid installations where conventional concrete delivery proves cost-prohibitive.
Market Restraints
- Glulam Beam Supply:Concentrated sourcing from southern Chilean mills creates vulnerability to pulp price volatility and export quota fluctuations.
- NSR-10 Compliance Costs:Colombia's seismic certification timeline adds four to six months to project planning, eroding prefab's schedule advantage versus conventional steel.
- Concrete Substitution:Ready-mix producers in Peru's coastal cities are pricing aggressively to defend share in the three-to-five-story residential band where wood competes directly.
Strategic Opportunities
- Colombia's Coffee Region:Earthquake reconstruction programs in Quindío and Risaralda are channeling housing subsidies toward panelized systems that local crews can assemble without heavy equipment.
- Digital Fabrication Convergence:CNC routing combined with BIM-to-factory data pipelines is enabling mass-customized envelope configurations that command premium pricing from architect-led projects.
- MINVU Performance Contracts:Chile's housing ministry is piloting outcome-based procurement models that reward suppliers for thermal efficiency and air-tightness guarantees rather than unit cost alone.
Industry Challenges
- Seismic Engineering Talent:Shortages of engineers qualified in timber lateral system design are throttling project throughput in Santiago and Bogotá.
- Factory Certification Backlogs:ABNT and MINVU audit queues are extending qualification timelines to fourteen months, freezing new entrants out of public housing tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Prefab Wood Buildings Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Structures, Log Cabins, Components End User: Residential, Commercial, Institutional, Recreational Construction Method: Pre-cut, Pre-engineered, Prefabricated, Hybrid Usage: Temporary Shelters, Permanent Residences, Vacation Homes, Eco-friendly Units |
| Companies Covered | Green Magic Homes, VMD, Modulbox, E2E Chile, Techno Fast, Easywood, All In Wall, Pampa Corporation, Casas Brazil, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Prefab Wood Buildings Market Shifts & Advancements
Factory automation and digital specification tools are compressing the traditional architect-contractor-fabricator chain into integrated design-build workflows.
Cross-laminated timber is integrating with robotic prefabrication lines to produce structural floor cassettes that ship with MEP rough-ins pre-installed. Chilean mid-rise developers are specifying these systems for twelve-story residential towers in Santiago's Ñuñoa district. The technology is integrating structural performance with installation speed, collapsing the traditional steel-concrete erection sequence that previously dominated this height band.
MINVU's updated thermal performance standards are mandating blower-door testing for all subsidized housing stock, forcing fabricators to invest in automated sealing stations and quality telemetry. The regulation is compressing the supplier base to factories with capital reserves for testing infrastructure. Panelized envelope specialists in Valparaíso are responding by certifying entire wall assemblies rather than component-level compliance, capturing specification preference from risk-averse project managers.
Large-scale residential developers in Brazil are consolidating vendor rosters from twelve to three approved fabricators per project, shifting procurement from unit-price bidding to multi-year framework agreements with volume commitments. The developer MRV Engenharia is piloting this model in São Paulo's outer ring municipalities, replacing competitive tender with partnered capacity reservation. This concentration is most visible in the affordable housing segment where scale economies outweigh design flexibility.
Latin America Prefab Wood Buildings Market Segmentation
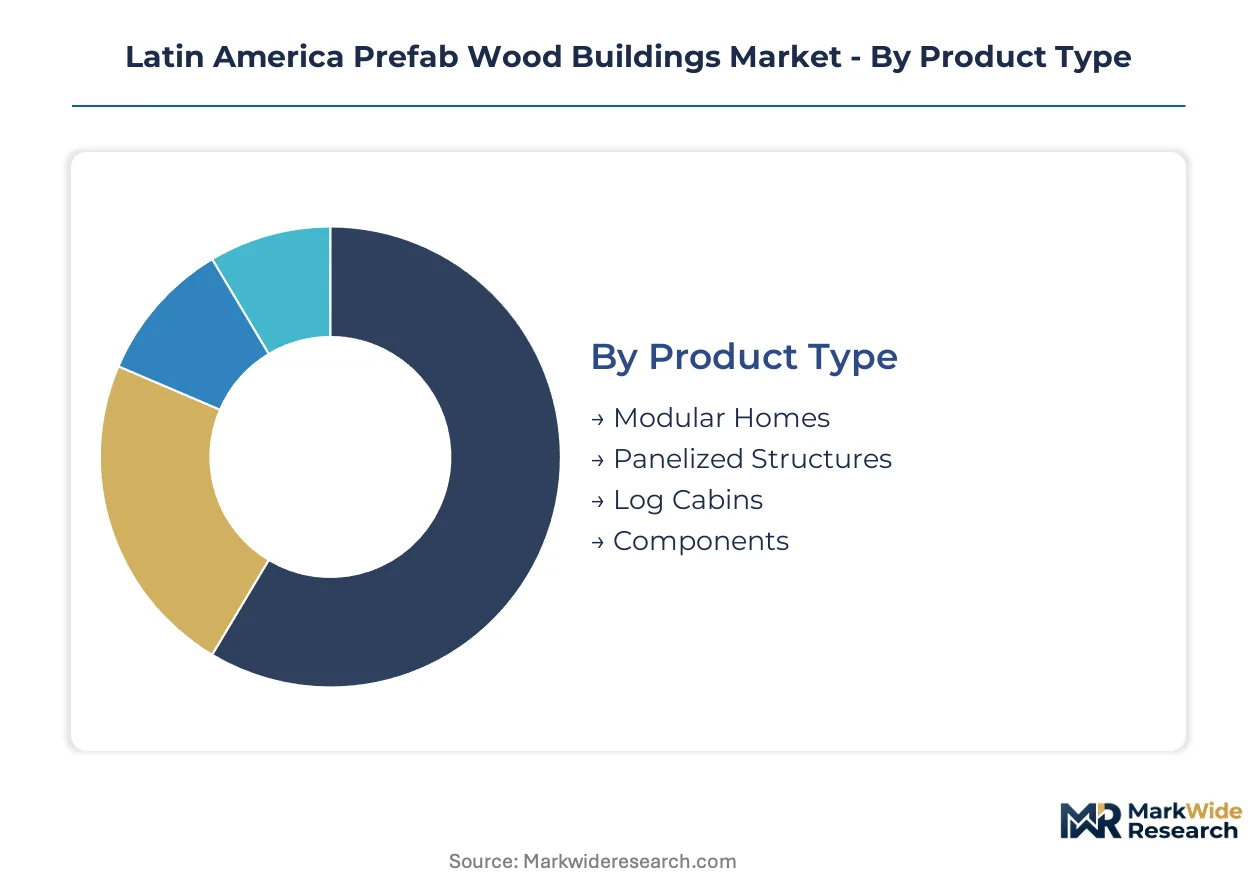
Prefab wood building markets fragment across construction methodology, end-use application, and structural system type. Each axis carries distinct certification requirements, margin profiles, and supply chain configurations that shape competitive positioning in Latin America's regulated environment.
Product Type:
Structural system architecture determines factory capital intensity, transportation logistics, and on-site assembly labor requirements across Brazilian and Chilean production corridors.
- Modular Homes:Three-dimensional volumetric units factory-finished with MEP rough-ins and interior fixtures. São Paulo's affordable housing developers favor these for standardized social housing blocks where speed-to-occupancy outweighs customization needs.
- Panelized Structures:Planar wall, floor, and roof assemblies shipped flat-packed for field erection. Colombia's Coffee Region reconstruction programs specify these for steep sites where crane access is limited and local crews assemble without heavy equipment.
- Log Cabins:Solid timber wall systems milled from native or imported softwoods. Costa Rica's eco-tourism operators deploy these for off-grid lodge installations where aesthetic authenticity commands premium pricing.
- Components:Individual engineered wood elements—glulam beams, CLT panels, I-joists—sold to conventional builders seeking partial prefabrication benefits.
Mature deployment sits with modular homes. Newer deployment is concentrated in panelized structures.
End User:
Customer archetypes diverge sharply in specification sophistication, procurement process length, and tolerance for design iteration cycles.
- Residential:Single-family and multi-family housing spanning subsidized social programs to luxury second homes. Brazil's MRV Engenharia and similar developers consolidate procurement into multi-year framework agreements with volume commitments.
- Commercial:Retail, office, and hospitality structures requiring fire-resistance ratings and accessibility compliance. Santiago's Ñuñoa district mid-rise towers demonstrate CLT commercial viability at twelve stories.
- Institutional:Schools, clinics, and government facilities with extended bid cycles and performance bonding requirements.
- Recreational:Camp facilities, sports pavilions, and event structures with seasonal demand patterns and lower durability specifications.
Volume concentration favors residential procurement. Margin expansion is strongest in commercial.
Construction Method:
Prefabrication depth ranges from material optimization to complete system integration, with seismic code compliance driving method selection in Chile and Colombia.
- Pre-cut:Dimensionally optimized lumber packages with CNC-cut joinery shipped to site for conventional stick-frame assembly. Peruvian coastal builders use these to defend against ready-mix concrete pricing aggression in the three-to-five-story band.
- Pre-engineered:Structural systems with stamped engineering calculations and hardware specifications for lateral load resistance. Chile's MINVU mandates these for all subsidized housing in seismic zones.
- Prefabricated:Factory-complete modules or panels with quality-controlled manufacturing and reduced on-site labor dependency.
- Hybrid:Mixed material systems combining engineered wood with steel moment frames or concrete cores for height and span performance.
Regulatory preference is hardening around pre-engineered methods. Hybrid systems are gaining share fastest in Santiago's densifying districts.
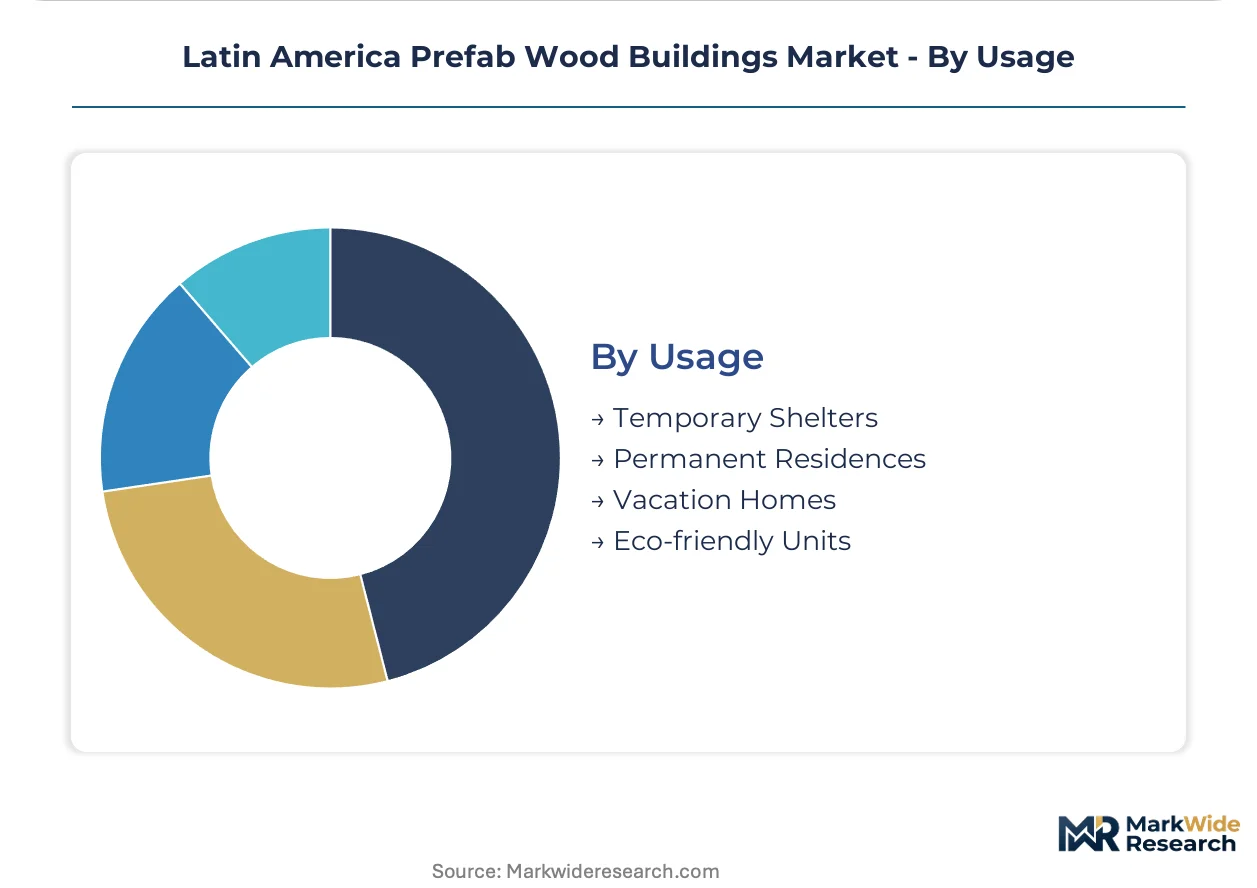
Usage:
Occupancy duration and environmental performance specifications create distinct product-positioning opportunities across climate zones and subsidy programs.
- Temporary Shelters:Rapid-deployment units for disaster response and construction workforce housing. Colombia's earthquake reconstruction channels subsidies toward panelized systems deployable without heavy equipment.
- Permanent Residences:Code-compliant dwellings meeting thermal, acoustic, and structural standards for full-time occupancy. Brazil's ABNT fire-safety mandates are disqualifying informal suppliers from this segment.
- Vacation Homes:Secondary dwellings prioritizing aesthetic distinction and rapid installation over operating cost optimization. Green Magic Homes' modular dome architecture anchors demand in Costa Rica and Colombia.
- Eco-friendly Units:Structures certified to passive house or equivalent standards with blower-door tested envelopes and renewable material sourcing.
Permanent residences dominate volume flows. Eco-friendly units represent the steepest expansion trajectory as MINVU thermal performance standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale residential developers in Brazil and Chile are consolidating procurement toward fewer certified fabricators, while Colombia and Peru navigate seismic compliance costs that compress prefab's schedule advantage against conventional materials.
Brazil
São Paulo state's construction corridor drives volume concentration as labor shortages and timber availability converge. ABNT tightened fire-safety standards for engineered wood assemblies, disqualifying informal suppliers from affordable housing tenders. MRV Engenharia pilots multi-year framework agreements with three approved fabricators per project in outer ring municipalities.
Chile
Santiago's Ñuñoa district anchors twelve-story CLT residential tower demand where seismic engineering requirements elevate technical barriers. MINVU mandates pre-engineered structural systems with stamped calculations for all subsidized housing in seismic zones. Valparaíso panelized envelope specialists certify entire wall assemblies to capture specification preference from risk-averse project managers.
Colombia
Quindío and Risaralda earthquake reconstruction programs channel housing subsidies toward panelized systems deployable without heavy equipment. NSR-10 seismic certification timelines add four to six months to project planning, eroding prefab's speed advantage versus conventional steel. VMD sustains manufacturing scale through its Colombian production base serving regional demand.
Peru
Coastal city developers face aggressive ready-mix concrete pricing defending share in the three-to-five-story residential band where wood competes directly. Pre-cut lumber packages with CNC-cut joinery help Peruvian builders defend position against concrete substitution. Lima metropolitan contractors favor hybrid approaches mixing engineered wood with concrete cores for height performance.
Costa Rica
Eco-tourism operators absorb modular dome architectures for off-grid lodge installations where conventional concrete delivery proves cost-prohibitive. Colegio Federado de Ingenieros y Arquitectos review protocols segment market access by compliance capability. Green Magic Homes leverages its modular dome architecture to anchor demand in vacation home segments across coastal provinces.
Latin America Prefab Wood Buildings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized niches in seismic-resistant engineering and eco-tourism aesthetics. The vendor base compresses toward capitalized fabricators with ABNT and MINVU certifications as audit queues extend qualification timelines to fourteen months. Three archetypes dominate: multi-regional scale players with integrated manufacturing, seismic engineering specialists serving Andean markets, and modular dome architects targeting premium vacation segments. Competitive moves center on factory automation investments and multi-year framework agreements with volume commitments from large developers.
Among Latin American fabricators, Green Magic Homes and E2E Chile exemplify divergent specialization strategies. Green Magic Homes occupies a position within the eco-tourism modular segment, its dome architecture representing an aesthetic-first approach to premium vacation housing. E2E Chile sits within the seismic engineering tier, its Santiago metropolitan focus exemplifying technical specialization for high-regulation Andean markets. VMD represents the manufacturing-scale archetype, its Colombian production base anchoring regional supply capacity. These three entities collectively illustrate how certification requirements and geographic concentration shape viable competitive positioning across the Latin American prefab wood buildings market.
| Leading Market Players |
|---|
| Green Magic Homes |
| VMD |
| Modulbox |
| E2E Chile |
| Techno Fast |
| Easywood |
| All In Wall |
| Pampa Corporation |
| Casas Brazil |
| Others |
Supply & Pricing Matrix
Captive sourcing of glulam beams from southern Chilean mills anchors supply positioning and pricing power for panelized system fabricators across the Andean Ridge. This backward integration into engineered wood feedstock buffers certified producers against pulp price volatility while informal competitors absorb margin compression from ABNT and MINVU audit backlogs.
Pricing Analysis
Volume concentrates in standardized modular homes for Brazil's affordable housing corridor, while margin expansion flows to architect-specified panelized envelopes with custom thermal performance guarantees. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates MINVU-validated fabricators from informal suppliers. Pricing pressure stems from ready-mix concrete producers in Peru's coastal cities defending share in the three-to-five-story residential band. Large-scale developers such as MRV Engenharia exhibit lowest price sensitivity through multi-year framework agreements, whereas mid-sized construction firms face acute cost pressure from extended certification timelines.
Supply Chain Analysis
Domestic-content mandates embedded in Colombia's NSR-10 seismic code and Chile's MINVU procurement rules are reshaping sourcing toward certified local fabrication. Supply concentrates in Brazil, Chile, and Colombia, with glulam beams, CLT panels, and engineered I-joists as critical inputs. Single-source vulnerability runs through concentrated southern Chilean mill capacity for structural timber feedstock. Distribution runs through developer-direct framework agreements and regional contractor networks serving seismic reconstruction programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America prefab wood buildings market is becoming a vertical-integration race, with upstream control over certified timber supply and downstream captive installation crews as the decisive levers separating capitalized incumbents from audit-frozen entrants.
For Market Incumbents: Anchor market position through backward integration into glulam beam production and automated sealing station investments that satisfy MINVU blower-door testing mandates. Defend against concrete substitution in Peru by certifying hybrid wood-concrete systems for height performance. Prioritize multi-year framework agreements with volume commitments from São Paulo's consolidated developer base to lock out emerging competitors facing fourteen-month ABNT audit queues. For New Entrants and Emerging Players: Capture white-space in Colombia's Coffee Region earthquake reconstruction programs where panelized systems deploy without heavy equipment and NSR-10 compliance timelines have frozen incumbent capacity. Target Costa Rica's eco-tourism modular dome segment where aesthetic differentiation commands premium positioning above commodity housing. Pursue digital fabrication convergence as the go-to-market angle, offering BIM-to-factory mass customization that architect-led projects specify for envelope performance guarantees. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multi-regional scale players seeking MINVU and ABNT certifications without fourteen-month audit delays. Long-term viability favors fabricators with captive timber supply and automated quality telemetry infrastructure. Watch MINVU's outcome-based procurement pilot expansion as the inflection signal shifting reward criteria from unit cost to thermal efficiency and air-tightness guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Wood Feedstock | Captive glulam beam supply buffers certified fabricators against Chilean mill export quota volatility. |
| Automated Sealing Station Deployment | MINVU blower-door testing mandates compress supplier base to capital-reserved factories with quality telemetry. |
| Multi-Year Framework Agreements | MRV Engenharia's partnered capacity reservation model replaces competitive tender in São Paulo's affordable housing corridor. |
| Digital Fabrication Convergence | CNC routing with BIM-to-factory pipelines enables mass-customized envelopes commanding architect-led premium pricing. |
| Hybrid System Certification | Wood-concrete hybrid validation defends position against Peruvian ready-mix concrete pricing aggression in mid-rise bands. |
Research Methodology
Document review covered ABNT and MINVU regulatory filings, seismic code harmonization protocols, and engineered wood product certification databases, complemented by interviews with plant managers at Colombian and Chilean fabrication facilities, procurement leads at Brazilian residential developers, and technical directors of panelized envelope specialists. Secondary validation drew from customs trade data on glulam beam flows, construction permit registries in São Paulo and Santiago metropolitan zones, and thermal performance testing records. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Cross-referencing historical procurement patterns with expert panel inputs on seismic code evolution shaped the analytical framework. Segmentation dimensions spanned construction methodology, end-use application, structural system type, and regional regulatory cluster. CAGRs were derived from regression analysis of certified factory capacity expansion against subsidized housing program allocations. Industry-specific forecast inputs incorporated ABNT audit queue durations and MINVU outcome-based procurement pilot scaling assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulp price volatility, seismic code harmonization delays, and concrete substitution pricing aggression in Peruvian coastal markets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Porcelain Tiles Market