
 Vinyl Windows Market | 2026-2036
Vinyl Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Windows Market Analysis
Big-box retail and pro-contractor channels are tilting toward consolidated purchasing agreements that favor volume suppliers. Andersen Corporation leverages its vertically integrated manufacturing network to sustain price competitiveness across regional markets. Pella Corporation anchors its position through specialized distribution partnerships with national homebuilders. Marvin Windows and Doors differentiates via custom-grade product lines that command premium positioning in the renovation segment.
Vinyl windows are thermoplastic fenestration systems fabricated from polyvinyl chloride (PVC) extrusions, typically incorporating multi-chamber hollow profiles with steel or aluminum reinforcement and dual-pane insulated glazing units. These assemblies deliver thermal insulation, air infiltration control, and structural weather resistance for residential and commercial building envelopes. Double-hung configurations dominate unit volume in North American residential applications due to familiarity among contractors and homeowners. Energy-efficient performance features represent the fastest-expanding specification tier, as code mandates and utility rebate programs tighten minimum U-factor and solar heat gain coefficient requirements. Impact-resistant glazing options command elevated margins in coastal hurricane zones, though volume penetration remains geographically concentrated.
ENERGY STAR specifications, International Energy Conservation Code adoption cycles, and state-level stretch codes in California and Massachusetts shape product certification requirements and manufacturing compliance costs. The EPA administers ENERGY STAR window criteria, while the IECC provides the baseline thermal performance framework adopted or amended by individual states. Stakeholders must monitor code adoption timelines and rebate program continuity to align capacity investments with demand pull from efficiency-driven replacement cycles.
Market Dynamics
Residential renovation cycles in cooling-dominated climates are compressing replacement intervals as ENERGY STAR thermal performance thresholds tighten, forcing manufacturers to retool extrusion lines for lower U-factor profiles.
Growth Catalysts
- Stretch code adoption:Massachusetts and California have enacted thermal performance mandates that exceed IECC baselines, accelerating specification upgrades among fenestration contractors.
- Utility rebate programs:Southern US electric cooperatives offer point-of-sale incentives for certified low-solar-heat-gain products, shortening payback periods for homeowners.
- Impact glazing integration:Multi-chamber vinyl frames now accommodate laminated glass assemblies, opening coastal hurricane zones previously served by aluminum systems.
Market Restraints
- PVC resin volatility:Feedstock costs for suspension-grade polyvinyl chloride fluctuate with ethylene and chlorine spot markets, compressing margin stability for extruders.
- Reinforcement supply concentration:Galvanized steel stiffeners and aluminum inserts depend on regional metal service centers with limited secondary sourcing.
- Aluminum substitution in commercial:Storefront and curtainwall specifications favor thermally broken aluminum for structural spans above vinyl frame limits.
Strategic Opportunities
- Passive house certification:PHIUS and PHI standards create premium positioning for triple-pane vinyl assemblies in high-performance residential construction.
- Online configurators:Direct-to-homeowner digital platforms bypass traditional distributor markups while capturing specification data for replacement demand forecasting.
- Tax credit alignment:The US Inflation Reduction Act residential clean energy credits subsidize qualified window replacements, amplifying pull-through from efficiency-motivated renovations.
Industry Challenges
- NFRC certification timelines:New product lines require extended laboratory testing for U-factor and SHGC ratings, delaying market entry against established SKUs.
- Installation labor scarcity:Skilled fenestration contractors capable of proper air-sealing and flashing integration remain concentrated in metropolitan construction corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Windows Market |
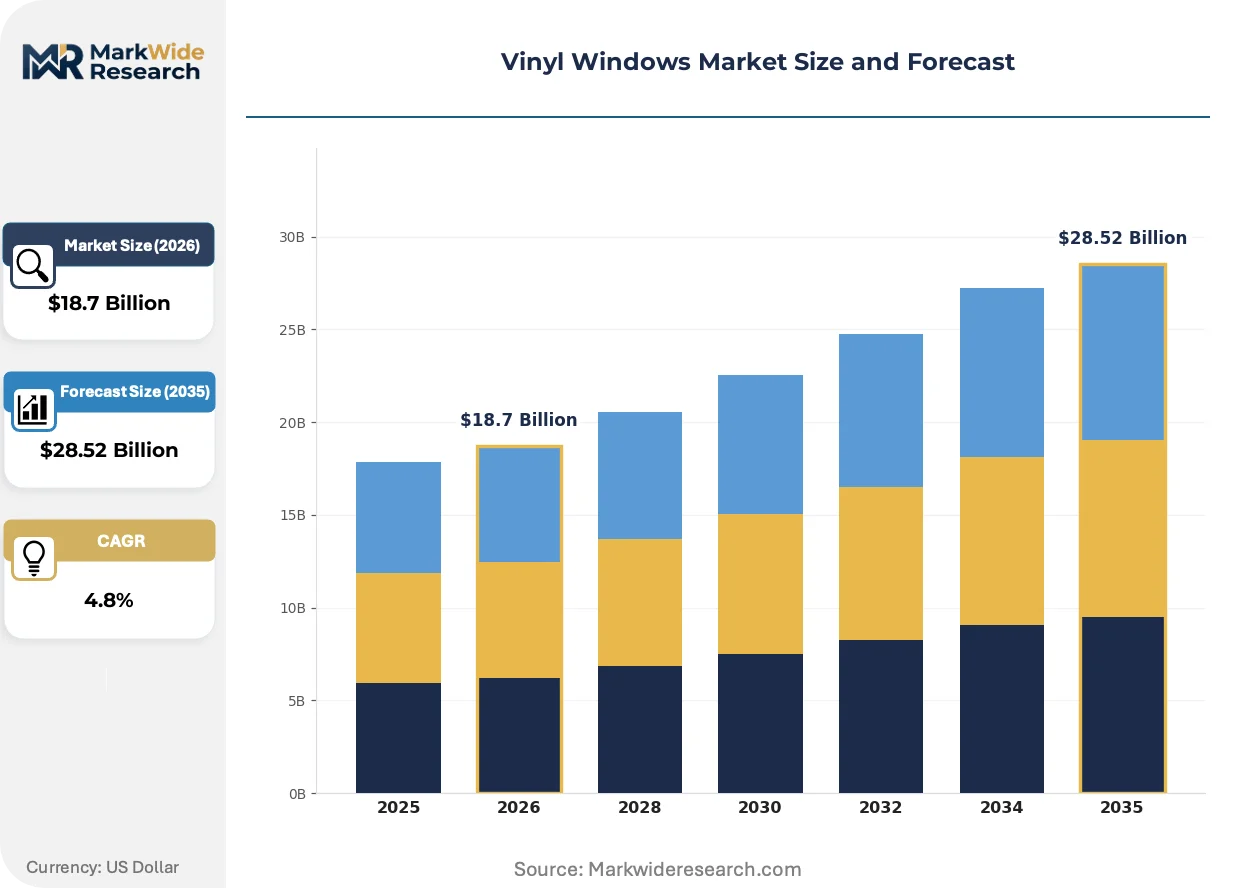
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Hung, Casement, Sliding, Picture End User: Residential, Commercial, New Construction, Renovation Frame Design: Vinyl-Clad, Non-Insulated, Insulated, Custom Performance Features: Energy-Efficient, Impact-Resistant, Soundproof, UV-Resistant |
| Companies Covered | Ply Gem Residential Solutions, JELD-WEN Inc., Andersen Corporation, Pella Corporation, Marvin Windows and Doors, Milgard Manufacturing LLC, MI Windows and Doors LLC, Alside Inc., Simonton Windows & Doors Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Windows Market Emerging Trajectories
Digital specification tools and advanced glazing technologies are compressing traditional product development cycles while reshaping how contractors and homeowners evaluate thermal performance trade-offs.
Co-extruded capstock technology is virtualizing surface durability expectations in the vinyl windows market. Capstock layers of acrylic or ASA resin over PVC substrates deliver color retention and impact resistance without painting. National homebuilders have adopted capstock-clad products for volume subdivisions, accepting modest cost premiums for reduced callback exposure. This layering approach is virtualizing the traditional separation between entry-level white vinyl and premium painted aluminum alternatives.
The EPA's revised ENERGY STAR Version 7.0 criteria tighten U-factor requirements for northern climate zones and lower SHGC thresholds for southern applications. Manufacturers serving multi-state distribution networks face SKU proliferation to meet divergent zone-specific certifications. The southern United States experiences the most acute specification pressure, where cooling-dominated load calculations now disqualify legacy double-pane configurations from rebate eligibility.
Big-box retail consolidation is altering contractor purchasing patterns. Pro-desk volume agreements at national home improvement chains now bundle windows with complementary building materials, capturing share from independent lumberyards. This channel migration concentrates specification influence among a handful of retail buyers who negotiate exclusive product lines. The southeastern United States displays the most pronounced shift, where cooling-season electricity costs drive rapid payback calculations for efficiency upgrades.
Vinyl Windows Market Segmentation
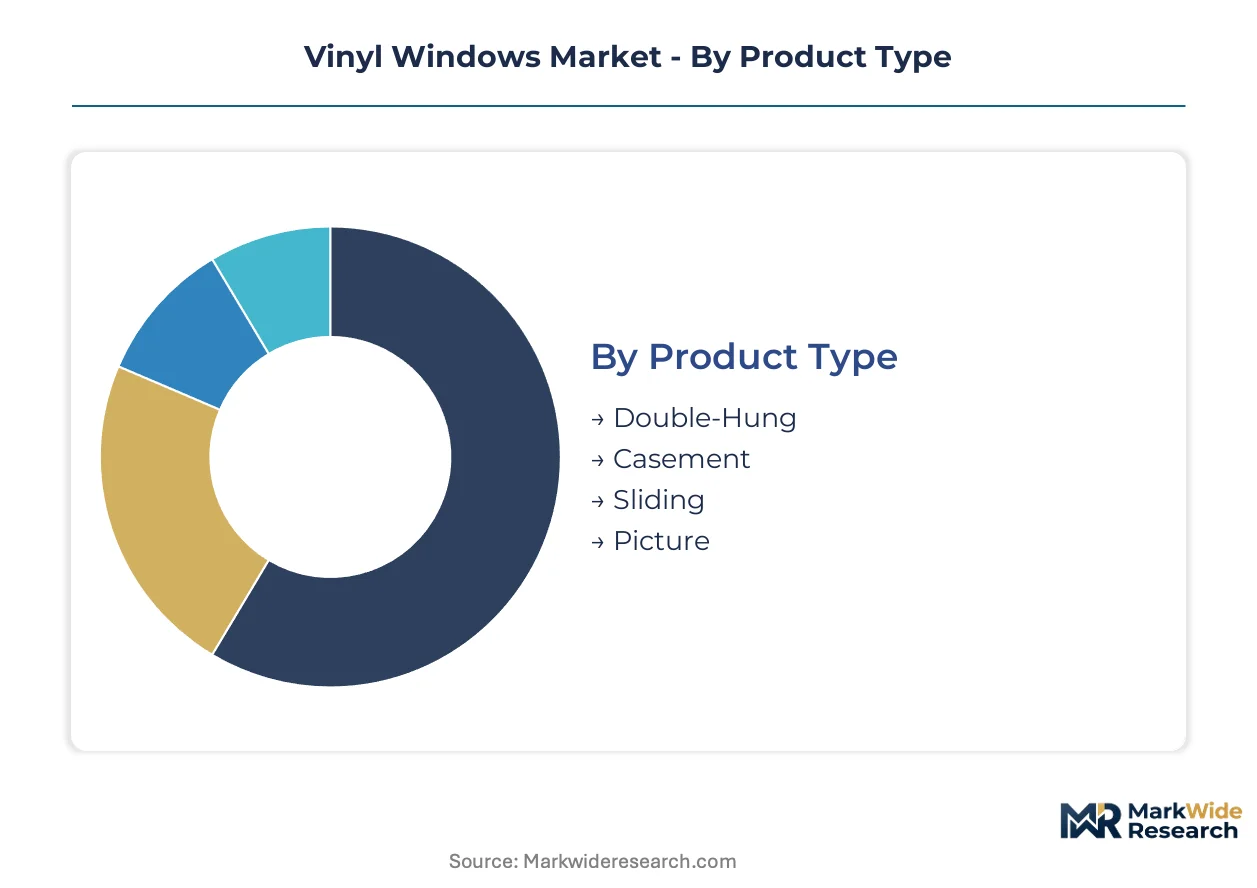
Segmentation in the vinyl windows market reflects divergent thermal performance mandates, installation labor constraints, and specification authority across residential and commercial channels. Understanding these divisions enables manufacturers to align extrusion capacity, glazing partnerships, and distribution investments with demand concentration points.
Product Type:
Double-hung configurations anchor contractor familiarity in replacement cycles, while specialized geometries address performance gaps in cooling-dominated climates.
- Double-Hung:Vertical sliding sashes with tilt-in cleaning functionality dominate North American residential renovation volume. Demand concentrates in the southern United States, where cooling-dominated climates amplify the value of low-SHGC glazing paired with familiar installation protocols.
- Casement:Hinged sashes with crank-operated opening deliver superior air-sealing compression against frames. Adoption climbs fastest in coastal hurricane zones, where impact-rated casement assemblies displace aluminum alternatives in wind-borne debris regions.
- Sliding:Horizontal operating sashes suit wide rough openings with limited vertical clearance. Commercial storefront retrofits favor this geometry for cost-efficient daylighting upgrades.
- Picture:Fixed non-operating frames maximize glazing area and thermal performance in passive house assemblies. High-performance residential construction drives specification in Massachusetts and California stretch code jurisdictions.
Established volume favors Double-Hung; emerging adoption favors Casement.
End User:
Specification authority splits between homeowner-driven replacement decisions and builder-controlled new construction procurement.
- Residential:Single-family and multifamily owners prioritize ENERGY STAR certification eligibility for utility rebate capture. The Inflation Reduction Act residential clean energy credits subsidize qualified replacements, amplifying pull-through from efficiency-motivated renovations across cooling-dominated southern states.
- Commercial:Storefront and curtainwall specifications favor thermally broken aluminum for structural spans above vinyl frame limits. Volume penetration remains constrained by building code structural requirements.
- New Construction:National homebuilders negotiate consolidated purchasing agreements that favor volume suppliers with vertically integrated manufacturing networks. Pro-desk volume agreements at national home improvement chains now bundle windows with complementary building materials.
- Renovation:Replacement cycles compress as thermal performance thresholds tighten, forcing manufacturers to retool extrusion lines for lower U-factor profiles. Skilled fenestration contractors capable of proper air-sealing remain concentrated in metropolitan construction corridors.
Procurement concentration favors New Construction; margin expansion favors Renovation.
Frame Design:
Chamber configuration and surface treatment differentiate cost tiers while compliance requirements drive specification upgrades.
- Vinyl-Clad:Co-extruded capstock layers of acrylic or ASA resin over PVC substrates deliver color retention without painting. National homebuilders have adopted capstock-clad products for volume subdivisions, accepting modest cost premiums for reduced callback exposure.
- Non-Insulated:Single-chamber hollow profiles serve price-sensitive replacement segments in mild climate zones. Regulatory pressure from IECC adoption cycles is displacing this tier in code-compliant jurisdictions.
- Insulated:Multi-chamber profiles with thermal breaks accommodate triple-pane glazing for PHIUS and PHI passive house certification. Massachusetts and California stretch codes accelerate specification upgrades among fenestration contractors.
- Custom:Specialized geometries and color matching serve high-end residential renovation and historic preservation. Marvin Windows and Doors anchors positioning through custom-grade product lines commanding premium positioning.
Volume scale favors Vinyl-Clad; specification intensity favors Insulated.
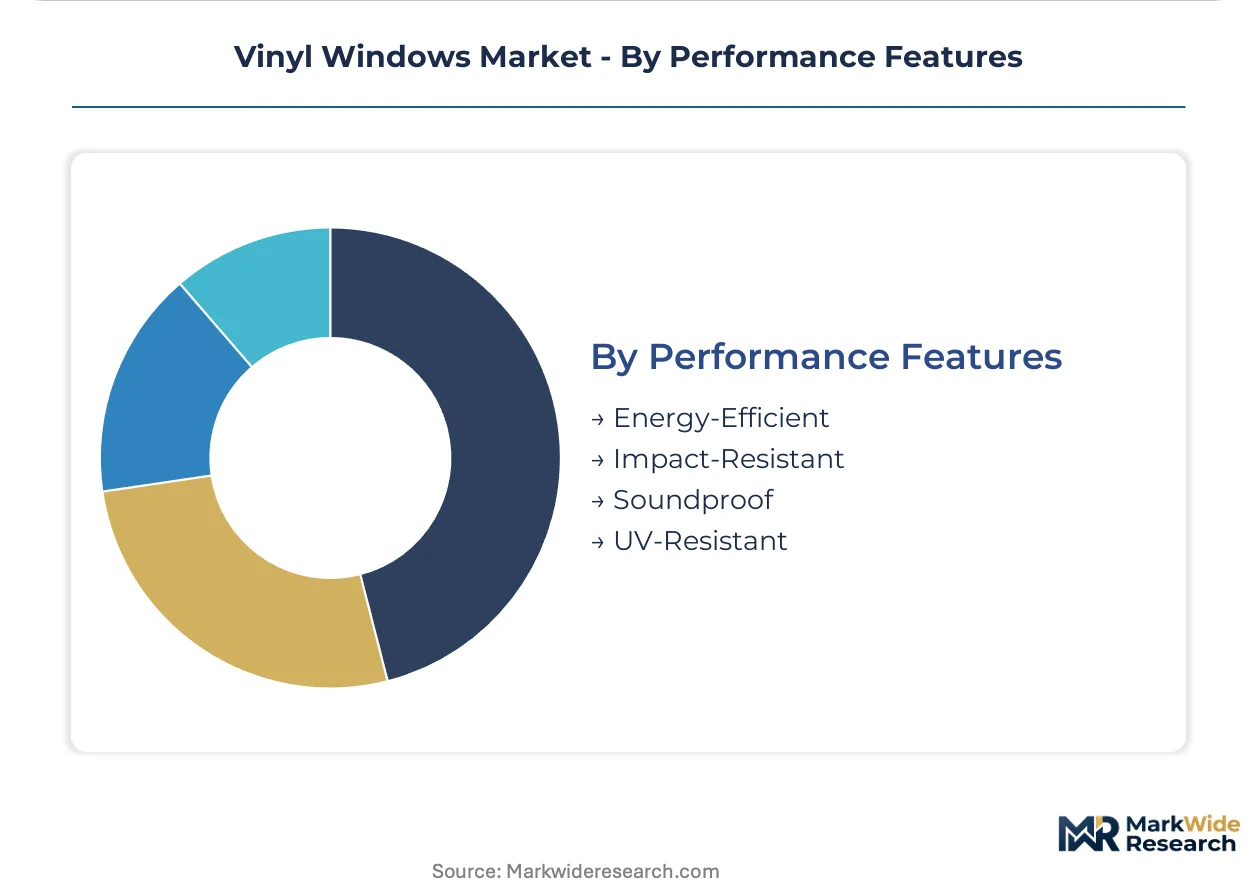
Performance Features:
Certification requirements and climate-specific load calculations reshape which performance bundles qualify for rebate programs.
- Energy-Efficient:Low-U-factor and optimized SHGC configurations meet ENERGY STAR Version 7.0 criteria. The southern United States experiences the most acute specification pressure, where cooling-dominated load calculations now disqualify legacy double-pane configurations from rebate eligibility.
- Impact-Resistant:Laminated glass assemblies within reinforced vinyl frames open coastal hurricane zones previously served by aluminum systems. Elevated margins accompany geographic concentration in wind-borne debris regions.
- Soundproof:Acoustic laminated interlayers and increased airspace target urban infill and airport-adjacent residential. Niche specification limits volume penetration.
- UV-Resistant:Specialized capstock formulations and glazing tints protect interior finishes in high-solar-exposure applications. Southwestern United States demand drives regional SKU proliferation.
Code compliance favors Energy-Efficient; margin elevation favors Impact-Resistant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands pricing power through ENERGY STAR rebate density, while Canada operates on thinner margins due to smaller-scale utility programs and cross-border logistics costs.
United States
Southern states drive replacement volume as cooling-dominated climates amplify efficiency payback calculations. The EPA administers Version 7.0 ENERGY STAR criteria that tighten U-factor and SHGC thresholds. The Southeast construction corridor from Atlanta to Charlotte concentrates fenestration contractor networks and big-box pro-desk purchasing agreements.
Canada
Cold-climate provinces prioritize low-U-factor configurations for heating load reduction. Natural Resources Canada maintains the EnerGuide and ENERGY STAR Canada programs with zone-specific performance requirements. The Greater Toronto Area anchors distribution networks serving Ontario's renovation market through regional building material wholesalers.
Germany
Passive house construction standards drive triple-pane specification in high-performance residential segments. The Federal Ministry for Economic Affairs and Energy oversees building energy efficiency regulations under the Energy Saving Ordinance. The Rhine-Ruhr metropolitan region hosts fabricators supplying PHIUS and PHI-certified assemblies for Central European export markets.
China
Rapid urbanization in cooling-dominated southern provinces expands demand for thermally efficient fenestration. The Ministry of Housing and Urban-Rural Development implements GB standards for building energy conservation. The Yangtze River Delta manufacturing cluster around Shanghai produces PVC extrusions and insulated glazing units for domestic and Southeast Asian markets.
Australia
Stringent National Construction Code thermal performance requirements accelerate specification upgrades in residential renovation. The Nationwide House Energy Rating Scheme mandates minimum star ratings that favor low-U-factor window systems. Melbourne and Sydney metropolitan areas concentrate installation contractor capacity for high-efficiency retrofits.
Vinyl Windows Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying extrusions, hardware, and sealed glazing units to branded assemblers. The market structures around three tiers: vertically integrated national brands with captive distribution, regional fabricators serving contractor networks, and private-label suppliers for big-box retail channels. Competitive moves concentrate on extrusion capacity expansion in southern US markets and digital specification tools that bypass traditional distributor markups.
Among North American fabricators, Andersen Corporation, Pella Corporation, and Marvin Windows and Doors occupy distinct positioning archetypes. Andersen exemplifies the vertically integrated platform model with captive supply chains sustaining price competitiveness. Pella represents the specialized distribution partnership approach anchoring relationships with national homebuilders. Marvin sits within the custom-grade premium tier, commanding positioning in renovation segments through specialized geometries and color-matched assemblies.
| Leading Market Players |
|---|
| Ply Gem Residential Solutions |
| JELD-WEN Inc. |
| Andersen Corporation |
| Pella Corporation |
| Marvin Windows and Doors |
| Milgard Manufacturing LLC |
| MI Windows and Doors LLC |
| Alside Inc. |
| Simonton Windows & Doors Inc. |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster around Shanghai anchors global PVC extrusion capacity, with volume concentration in this hub translating directly into pricing leverage for multi-chamber profile suppliers serving North American distributors. Downstream fabricators face margin compression when resin volatility coincides with reinforced steel stiffener shortages, forcing tiered procurement strategies that separate volume-contracted from spot-market exposure.
Pricing Analysis
Configured-to-order pricing for custom-grade vinyl assemblies commands spreads of 40-60 percent above standard double-hung SKUs, with color-matched capstock and specialized geometries driving differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects ENERGY STAR certification grade and volume scale, while PVC resin spot-market fluctuations are intensifying cost compression in the entry tier. National homebuilders exhibit lowest price sensitivity due to consolidated purchasing agreements, whereas independent renovation contractors face acute margin pressure from distributor markups.
Supply Chain Analysis
Export-control regimes on advanced glazing interlayers and low-emissivity coatings limit technology flows from German and Japanese specialty chemical suppliers to Chinese fabricators, constraining premium product availability. Geographic supply concentrates in China for PVC resin and extrusion equipment, the United States for galvanized steel reinforcement, and Germany for high-performance spacer systems. Feedstock costs for suspension-grade polyvinyl chloride rest on ethylene and chlorine spot markets, with single-source vulnerability in regional metal service centers for aluminum inserts. Distribution runs through big-box pro-desk volume agreements and independent lumberyard networks serving metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA's ENERGY STAR Version 7.0 criteria tightening constitutes a regulatory inflection that will compress replacement cycles and reward early compliance investment, positioning this market for sustained expansion through efficiency-driven renovation demand.
For Market Incumbents: Build certification moats around PHIUS and PHI passive house standards while retooling extrusion lines for triple-pane accommodation ahead of Massachusetts and California stretch code adoption. Consolidate distributor relationships through exclusive product lines at national home improvement chains, and anchor capacity expansion in the Southeast construction corridor from Atlanta to Charlotte to capture cooling-dominated climate volume. Aluminum substitution in commercial storefront applications represents the primary substitution threat requiring monitoring. For New Entrants and Emerging Players: Coastal hurricane zones from Florida to Texas represent the most penetrable entry point, where impact-rated vinyl casement assemblies are displacing aluminum alternatives and established brands lack specialized regional presence. Online configurators offering direct-to-homeowner specification bypass traditional distributor markups while capturing replacement demand forecasting data. Tax credit alignment under the Inflation Reduction Act provides immediate go-to-market leverage for efficiency-certified product positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because thermal performance mandates will progressively disqualify legacy configurations and concentrate share among certified manufacturers. Acquisition targets should emphasize regional fabricators with captive extrusion capacity and established contractor networks in cooling-dominated southern states. The signal to watch is utility rebate program continuity, as withdrawal of point-of-sale incentives would dampen efficiency-motivated replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Pane Capacity Expansion | Passive house certification requirements in Massachusetts and California stretch codes accelerate specification upgrades. |
| Co-Extruded Capstock Technology Investment | Acrylic or ASA resin layering over PVC substrates reduces callback exposure for national homebuilders. |
| Direct-to-Consumer Digital Platform Launch | Online configurators bypass distributor markups while capturing specification data for replacement demand forecasting. |
| Impact-Rated Product Line Development | Laminated glass assemblies within reinforced vinyl frames open coastal hurricane zones previously served by aluminum. |
| Utility Rebate Program Alignment | Southern US electric cooperative incentives shorten payback periods for certified low-solar-heat-gain configurations. |
Methodological Framework
A spread of perspectives from fenestration contractors, national homebuilder procurement directors, big-box retail buyers, PVC resin procurement managers, and ENERGY STAR certification specialists converged on the working assumptions underlying demand projections. Primary interviews with these stakeholders combined with secondary validation from EPA ENERGY STAR program documentation, International Energy Conservation Code adoption records, Natural Resources Canada EnerGuide databases, and US Census Bureau residential construction permits. Bottom-up unit volume estimates triangulated against top-down addressable market calculations.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by operating geometry, end-user channel splits between new construction and renovation, frame design tiering from non-insulated to triple-pane passive house configurations, and performance feature bundling. CAGRs derived from regression analysis against housing starts, renovation expenditure indices, and code adoption timelines. Industry-specific forecast inputs included ENERGY STAR Version 7.0 zone-specific U-factor and SHGC threshold changes, and southern US cooling-degree-day correlations with replacement cycle compression.
Macroeconomic conditions sit as an overlay; deviation in mortgage rate trajectories, residential construction labor availability, or PVC resin spot pricing would shift the trajectory. Forecasts reflect documented assumptions about stretch code adoption timelines and utility rebate program continuity. Material shifts in federal tax credit eligibility or International Energy Conservation Code amendment schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Pipe Hanger Market