
 North America Siding and Decking Market | 2026-2036
North America Siding and Decking Market Size, Share, and Industry Trends Forecast 2026-2036
North America Siding and Decking Market Analytics
Cellular PVC co-extrusion is tilting material preference toward moisture-resistant profiles across coastal and humid climate zones. Trex Company Inc. leverages recycled polyethylene feedstock to sustain cost advantages in composite deck boards. James Hardie Industries plc anchors fiber cement siding demand through specification relationships with national homebuilders. The AZEK Company differentiates via capped polymer technology that competes directly with traditional wood in appearance and workability.
Siding and decking encompasses exterior cladding and horizontal surface systems engineered from wood, vinyl, composite, or fiber cement substrates, typically installed via direct mount, fastening, clipping, or sealing methods with performance ratings for moisture resistance, UV stability, and structural load capacity. The primary purpose is weather protection and aesthetic finishing for residential, commercial, and institutional structures. Fiber cement occupies the premium renovation segment where fire ratings and dimensional stability justify higher installed costs. Composite materials represent the fastest-growing material type as capped co-extrusion technology narrows the price-performance gap with tropical hardwoods. Vinyl siding remains the volume leader in new residential construction, though margin pools have compressed toward commodity levels.
The EPA enforces TSCA Title VI formaldehyde emission limits that shape engineered wood product qualification, while the ICC governs structural performance standards through the International Residential Code adopted across US states and Canadian provinces. OSHA workplace exposure regulations additionally influence manufacturing plant locations and capital deployment decisions. Stakeholders must monitor evolving building code adoptions at the state and provincial level, where wildfire resistance criteria in California and British Columbia increasingly filter into specification requirements across the broader region.
Market Dynamics
Engineered material substitution is compressing traditional lumber's share across North American residential construction, driven by moisture-resistant composite formulations and EPA emission mandates that disqualify high-VOC alternatives from specification pools.
Growth Catalysts
- TSCA Title VI Compliance:The EPA's formaldehyde emission standards under TSCA Title VI are accelerating certification requirements for low-VOC engineered wood products, pushing builders toward compliant composite and fiber cement alternatives.
- Coastal Humidity Clusters:Moisture-resistant cellular PVC and capped polymer technologies are capturing specification share across southeastern United States residential markets where humidity degradation threatens traditional substrates.
- Wildfire Resistance Codes:California and British Columbia building code adoptions for fire-rated exterior cladding are expanding fiber cement and metal-composite hybrid demand across the broader North American region.
Market Restraints
- Petrochemical Feedstock Volatility:Recycled polyethylene and virgin PVC resin costs fluctuate with energy markets, compressing margin stability for composite decking manufacturers dependent on plastic feedstocks.
- Canadian Softwood Supply Concentration:British Columbia and Quebec lumber supply constraints from beetle infestation and harvest restrictions limit traditional wood siding availability, forcing price volatility absorption downstream.
- Tropical Hardwood Substitution Ceiling:Ipe and teak decking retains architect preference in ultra-premium coastal segments where natural grain authenticity resists full composite displacement despite price premiums.
Strategic Opportunities
- Mexico Residential Expansion:Underpenetrated middle-class housing construction in Mexico's northern industrial corridors presents white space for vinyl and fiber cement siding systems adapted to arid climate performance requirements.
- IRA Energy Efficiency Incentives:Inflation Reduction Act residential efficiency tax credits are creating specification pull for insulated siding products that improve building envelope thermal performance in US renovation markets.
- Digital-Physical Convergence:Building information modeling integration with manufacturer specification databases is virtualizing product selection workflows, enabling direct-to-architect marketing that bypasses traditional distributor gatekeeping.
Industry Challenges
- Co-Extrusion Technical Talent Scarcity:Capped composite manufacturing requires specialized polymer processing expertise that concentrates among a limited pool of engineers, constraining capacity expansion timelines for mid-tier producers.
- Multi-Jurisdiction Certification Complexity:ICC-ES evaluation report acquisition, CSA Group listings for Canada, and state-level environmental product declarations create compliance timeline friction for product line launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Siding and Decking Market |
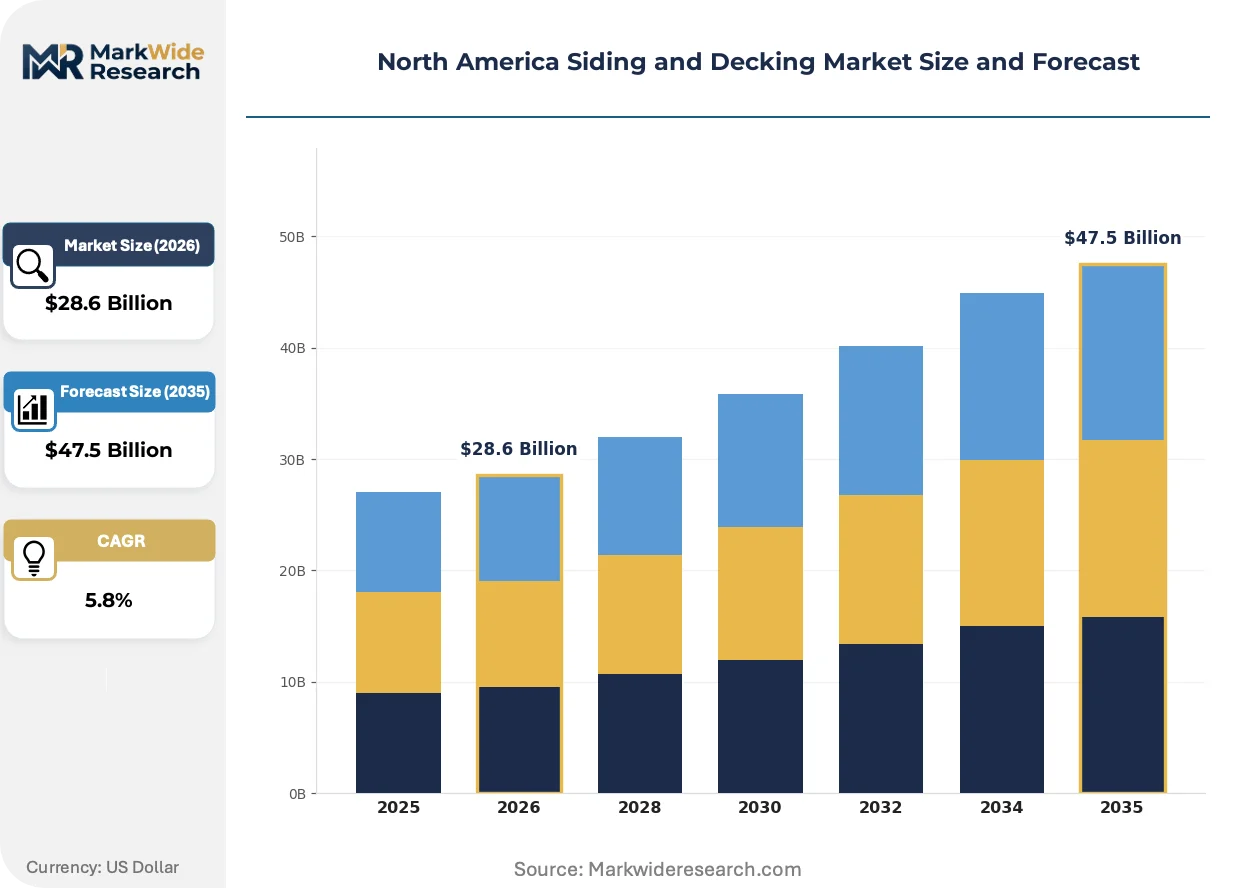
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Vinyl, Wood, Composite, Fiber Cement Installation Method: Direct Mount, Fastened, Clipped, Sealed Product Category: Siding Panels, Deck Boards, Trim, Railing End User: Residential, Commercial, Institutional, DIY |
| Companies Covered | Trex Company Inc., The AZEK Company, James Hardie Industries plc, Cornerstone Building Brands, Westlake Corporation, Louisiana Pacific Corporation, Fiberon, MoistureShield, Fortune Brands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Siding and Decking Market Evolving Landscape
Material science advances are collapsing the performance gap between synthetic substrates and natural wood aesthetics, while regulatory pressure on emissions and fire safety accelerates specification turnover across residential and light commercial construction.
Cellular PVC co-extrusion with acrylic capstock layers is virtualizing moisture resistance capabilities previously exclusive to tropical hardwoods. Custom homebuilders across Florida and Gulf Coast markets are specifying these profiles for pool decks and marina installations. The technology is compressing maintenance cost differentials that once justified premium natural material selection.
OSHA workplace exposure regulations are reshaping manufacturing plant capital deployment decisions across the United States. Composite and fiber cement producers face elevated compliance costs for silica dust containment and resin vapor recovery systems. Canadian provinces with stricter provincial occupational standards are seeing slower greenfield capacity approvals compared to US Southeast industrial corridors.
Architect specification behavior is rotating toward environmental product declaration transparency as a screening criterion. Large national homebuilders now require third-party verified lifecycle data for siding and decking materials in master specification templates. This shift is most visible across Pacific Northwest markets where municipal green building mandates cascade into private sector procurement protocols.
North America Siding and Decking Market Segmentation
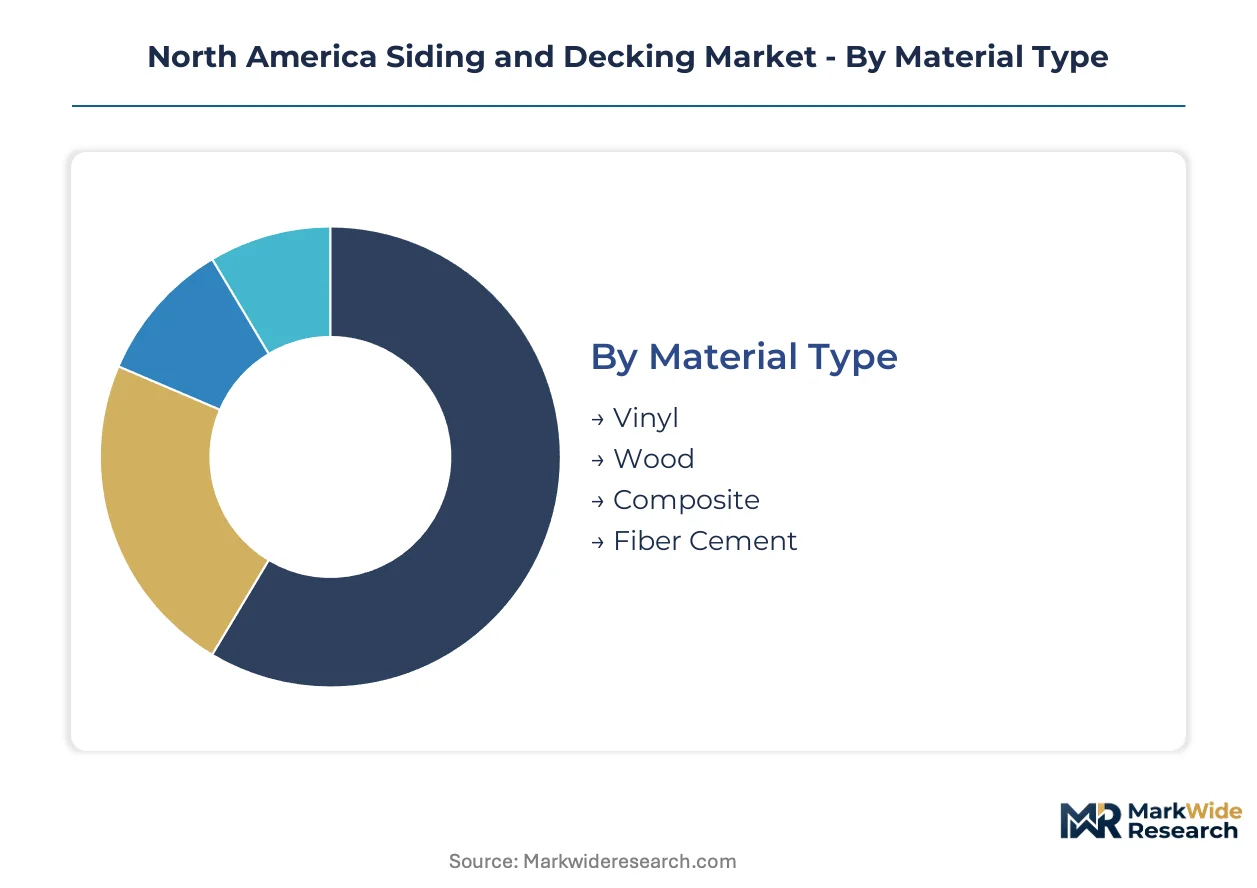
Material differentiation, installation complexity, and end-use durability requirements create distinct competitive arenas across the North America Siding and Decking Market. Each segment commands specialized manufacturing capabilities and regulatory compliance profiles that reshape procurement patterns.
Material Type:
Mature substrates dominate volume positions while engineered alternatives capture specification momentum in climate-stressed applications.
- Vinyl:Polyvinyl chloride resin extruded into hollow or solid profiles with UV-stabilized capstock layers. New residential construction in the southeastern United States absorbs the majority of volume, driven by cost efficiency and low maintenance requirements in high-humidity environments.
- Composite:Wood-plastic or capped polymer formulations combining recycled polyethylene with cellulose fiber or mineral fillers. Demand concentrates in coastal renovation markets where moisture resistance and dimensional stability justify premium positioning against tropical hardwoods.
- Wood:Traditional softwood and engineered lumber substrates including cedar, redwood, and pressure-treated pine. British Columbia and Pacific Northwest markets retain preference for natural grain aesthetics despite supply constraints from harvest restrictions.
- Fiber Cement:Portland cement, sand, and cellulose fiber composite pressed into planks or panels. California and British Columbia wildfire resistance codes are accelerating specification in fire-prone zones where Class A ratings are mandatory.
Vinyl retains volume leadership; composite holds the steepest expansion curve.
Installation Method:
Cost tier stratification separates labor-intensive traditional methods from premium systems demanding specialized contractor training.
- Direct Mount:Substrates affixed directly to structural sheathing or framing without intermediate furring strips. Residential renovation contractors favor this approach for speed and material economy in vinyl and fiber cement applications.
- Fastened:Mechanical attachment using nails, screws, or hidden fasteners with specified spacing patterns. Deck board installation across Florida and Gulf Coast markets depends on corrosion-resistant fastener specifications for salt-air durability.
- Clipped:Proprietary fastening systems engaging board edges or grooves to conceal hardware. Premium composite decking specifications increasingly mandate clip systems for clean surface aesthetics in high-end residential projects.
- Sealed:Adhesive or sealant-based attachment combined with mechanical backup for moisture barrier continuity. Institutional and commercial facades in hurricane-prone zones require sealed systems for wind-uplift resistance.
Fastened methods retain volume leadership; clipped systems gain share fastest in premium segments.
Product Category:
Application-specific performance requirements drive margin differentiation across cladding versus horizontal surface systems.
- Siding Panels:Vertical or horizontal cladding elements providing weather protection and aesthetic finishing. National homebuilder specification templates in the United States are standardizing insulated panel configurations for thermal envelope compliance.
- Deck Boards:Load-bearing horizontal surfaces for outdoor living spaces. Moisture-resistant cellular PVC and capped polymer formulations are displacing traditional lumber across southeastern United States pool deck and marina installations.
- Trim:Accent and finishing elements including corner boards, soffits, and fascia profiles. Color-matched trim systems command premium positioning in custom homebuilder specifications.
- Railing:Safety barrier systems for elevated decks and balconies. Code-compliant aluminum and composite railings are standardizing across multi-family residential construction.
Siding panels retain volume leadership; deck boards demonstrate the most rapid specification turnover.
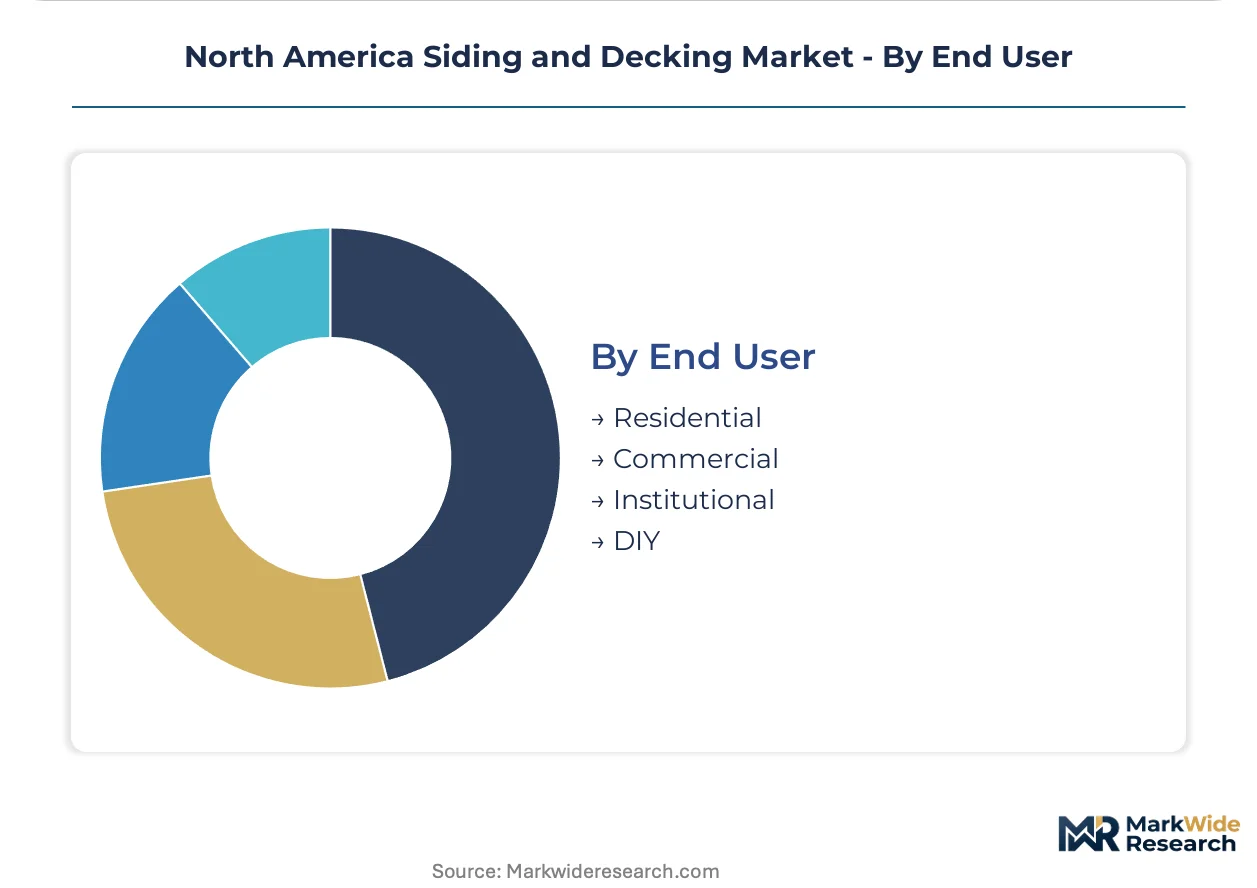
End User:
Customer type determines procurement channel, price sensitivity, and compliance documentation requirements.
- Residential:Single-family and multi-family construction absorbing engineered materials for durability and low maintenance. EPA TSCA Title VI emission standards are filtering composite and fiber cement into new construction specifications.
- Commercial:Light commercial, hospitality, and retail facades requiring fire-rated and high-impact-resistant systems. California Title 24 energy codes are pulling insulated siding into commercial renovation scopes.
- Institutional:Schools, healthcare, and government buildings with extended lifecycle and maintenance cost scrutiny. Environmental product declaration requirements are concentrating procurement among certified manufacturers.
- DIY:Homeowner-direct purchases through retail and pro-dealer channels. Big-box retailers in the United States are expanding composite decking assortments for weekend installation projects.
Residential retains volume leadership; institutional demonstrates the most stringent certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian softwood lumber flows southward to supply United States residential construction, while Mexican manufacturing corridors absorb vinyl and fiber cement systems for expanding middle-class housing. Cross-border trade patterns concentrate finished goods distribution near major population centers.
United States
Southeastern humidity-resistant composite formulations command premium positioning in Florida and Gulf Coast pool deck installations. EPA TSCA Title VI formaldehyde emission standards filter engineered wood products from specification pools. Atlanta and Charlotte distribution hubs channel cellular PVC and capped polymer inventory toward residential contractors.
Canada
British Columbia wildfire resistance codes accelerate fiber cement and metal-composite hybrid demand across fire-prone zones. Quebec and Ontario building code adoptions increasingly mirror California Title 24 energy efficiency requirements. Vancouver and Toronto specification markets drive environmental product declaration transparency among national homebuilders.
Mexico
Northern industrial corridors present underpenetrated white space for vinyl siding systems adapted to arid climate performance. Federal housing programs in Nuevo León and Jalisco prioritize durable exterior cladding for middle-class residential expansion. Monterrey manufacturing clusters absorb imported composite technologies for regional distribution.
California
Class A fire-rated exterior cladding mandates displace traditional wood substrates in wildland-urban interface zones. California Title 24 energy codes pull insulated siding into commercial renovation scopes. Los Angeles and San Francisco metropolitan specification markets require third-party verified lifecycle data for municipal green building compliance.
Texas
Houston and Dallas-Fort Worth residential construction absorbs engineered alternatives to pressure-treated lumber for humidity durability. State energy efficiency programs create specification pull for thermally performing building envelope systems. Gulf Coast marina and waterfront developments specify moisture-resistant cellular PVC for salt-air environments.
North America Siding and Decking Market Competitive Landscape
On the supply side, the industry is tiered between integrated building materials conglomerates and specialized engineered substrate fabricators. Large-scale producers leverage specification relationships with national homebuilders to secure volume positions, while mid-tier specialists concentrate on climate-specific formulations for coastal and fire-prone markets. Two dominant strategic archetypes emerge: recycled feedstock composite specialists and fiber cement fire-rating leaders. Competitive moves center on capacity expansion in southeastern United States industrial corridors and strategic partnerships with building information modeling platform providers.
Within the composite decking tier, Trex Company Inc. and The AZEK Company exemplify divergent feedstock strategies, with the former anchoring recycled polyethylene approaches and the latter representing capped polymer technology advancement. James Hardie Industries plc occupies a position exemplifying fiber cement specification dominance through national homebuilder relationships. These three entities collectively represent the primary competitive anchors shaping material substitution patterns across North American residential construction.
| Leading Market Players |
|---|
| Trex Company Inc. |
| The AZEK Company |
| James Hardie Industries plc |
| Cornerstone Building Brands |
| Westlake Corporation |
| Louisiana Pacific Corporation |
| Fiberon |
| MoistureShield |
| Fortune Brands |
| Others |
Value Network & Pricing Analysis
Undercapacity in Canadian softwood lumber mills is compressing traditional wood pricing power while elevating engineered substrate premiums across southeastern United States distribution channels. This utilization imbalance forces buyers toward composite and fiber cement alternatives, reshaping supplier negotiation leverage and inventory positioning strategies.
Pricing Analysis
Current-generation capped polymer decking commands substantial premiums over prior-generation uncapped composites and next-generation bio-based formulations. Three-tier pricing structure across premium, standard, and economy levels separates fire-rated fiber cement systems from vinyl commodity grades and pressure-treated lumber. Cost compression in vinyl siding intensifies because resin feedstock volatility erodes manufacturer margins. National homebuilders exhibit lowest price sensitivity for wildfire-rated cladding, while DIY retail channels absorb highest elasticity for standard deck boards.
Supply Chain Analysis
Extended payment terms from national homebuilder accounts are forcing working capital recalibration among mid-tier composite fabricators. Manufacturing concentrates in the United States, Canada, and Mexico, with resin compounding anchored in Gulf Coast petrochemical corridors. Raw material draws from recycled polyethylene streams, Portland cement, and cellulose fiber pulps. Single-source vulnerability concentrates in specialized acrylic capstock additives. Distribution runs through pro-dealer networks and big-box retail channels serving residential contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American residential construction is cycling through a post-pandemic normalization phase, with housing starts volatility creating demand lumpiness that rewards flexible capacity positioning.
For Market Incumbents: Insulate specification relationships by embedding building information modeling databases directly into architect workflows, countering distributor disintermediation threats. Deepen backward integration into recycled polyethylene collection networks to neutralize petrochemical cost volatility. Prioritize CSA Group and ICC-ES certification maintenance as regulatory compliance timelines lengthen. For New Entrants and Emerging Players: Establish a beachhead in Mexico's northern industrial corridors where federal housing programs prioritize durable exterior cladding for middle-class residential expansion. Target arid-climate vinyl siding formulations as the most penetrable white space, leveraging specification gaps left by US-centric incumbents. Pursue direct-to-architect digital marketing that bypasses traditional pro-dealer gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among building information modeling-integrated specification platforms that lock in multi-year architect relationships. Long-term viability over a five-to-ten year horizon favors manufacturers with captive recycled feedstock streams and fire-rating certification depth. Acquisition candidates should demonstrate installed base scale in California or British Columbia wildfire code jurisdictions. The signal to monitor is municipal green building mandate adoption velocity across Pacific Northwest metropolitan markets.| Strategic Initiative | Industry Significance |
|---|---|
| Building Information Modeling Integration | Virtual specification workflows embed AZEK and Trex products directly into architect design phases. |
| Recycled Feedstock Securement | Captive polyethylene sourcing insulates Trex from resin cost volatility affecting composite competitors. |
| Fire-Rating Certification Expansion | James Hardie's Class A rating penetration captures California Title 24 renovation specification pools. |
| Arid-Climate Formulation Development | Vinyl siding adaptations for Mexico's northern corridors unlock underpenetrated middle-class housing demand. |
| Environmental Product Declaration Investment | Third-party lifecycle transparency satisfies institutional procurement mandates in Vancouver and Toronto markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including national homebuilder procurement directors, regional contractor purchasing managers, composite manufacturing plant engineers, and architect specification consultants. Secondary validation drew from EPA TSCA Title VI compliance filings, ICC-ES evaluation report databases, customs trade flow records, and state-level building code adoption trackers. Bottom-up volume estimates triangulated against top-down construction spending allocations across material categories.
Calibration against historical price-volume relationships and regulatory adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, installation complexity tier, end-use application, and climate-zone performance requirement. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs incorporated housing starts volatility patterns and wildfire code adoption diffusion rates.
Sensitivities concentrate around petrochemical feedstock cost spikes, Canadian lumber supply disruptions from beetle infestation harvest restrictions, and municipal green building mandate acceleration. Forecasts reflect documented assumptions about regulatory enforcement consistency and residential construction cyclicality. Macroeconomic contraction, tariff regime shifts, or breakthrough bio-based material commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Piping Systems Market