
 Modular Commercial Building System Market | 2026-2036
Modular Commercial Building System Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Commercial Building System Market Insights
Skilled construction labor shortages across developed economies is unwinding traditional on-site build schedules and redirecting capital toward factory-controlled modular fabrication. Laing O'Rourke leverages its Design for Manufacture and Assembly expertise to compress program durations on complex commercial projects. Bouygues Construction anchors its European position through integrated timber-frame and concrete-frame module production. Skanska competes on sustainability credentials, embedding lifecycle carbon tracking into every volumetric delivery.
A modular commercial building system comprises factory-engineered volumetric units, panelized assemblies, or container-adapted structures manufactured under controlled conditions and transported to site for installation. These systems typically achieve tolerances of ±2mm and incorporate MEP rough-ins prior to delivery, enabling completion rates of up to 90% off-site. The primary commercial purpose is to reduce construction duration, minimize weather delays, and standardize quality across multi-unit developments. Volumetric modules currently lead value generation due to their high finish levels and minimal on-site labor requirements, while flat-pack configurations represent the fastest-expanding category for remote or infrastructure-constrained geographies. Steel-frame technology dominates in multi-story commercial applications where structural load-bearing capacity governs design, though timber-frame alternatives are capturing share in low-rise office and educational segments where carbon accounting influences procurement.
Building codes in the United States fall under ICC and state-level jurisdictions, with California's Title 24 energy standards and New York City's Local Law 97 carbon caps directly shaping module specifications for projects in those markets. The EU Construction Products Regulation harmonizes CE marking requirements across member states, while the UK's Building Safety Regulator now mandates gateway compliance for volumetric structures exceeding defined height thresholds. Stakeholders must monitor how evolving embodied carbon regulations in Germany, France, and the United Kingdom reconfigure material specifications and factory location decisions across their supply networks.
Market Dynamics
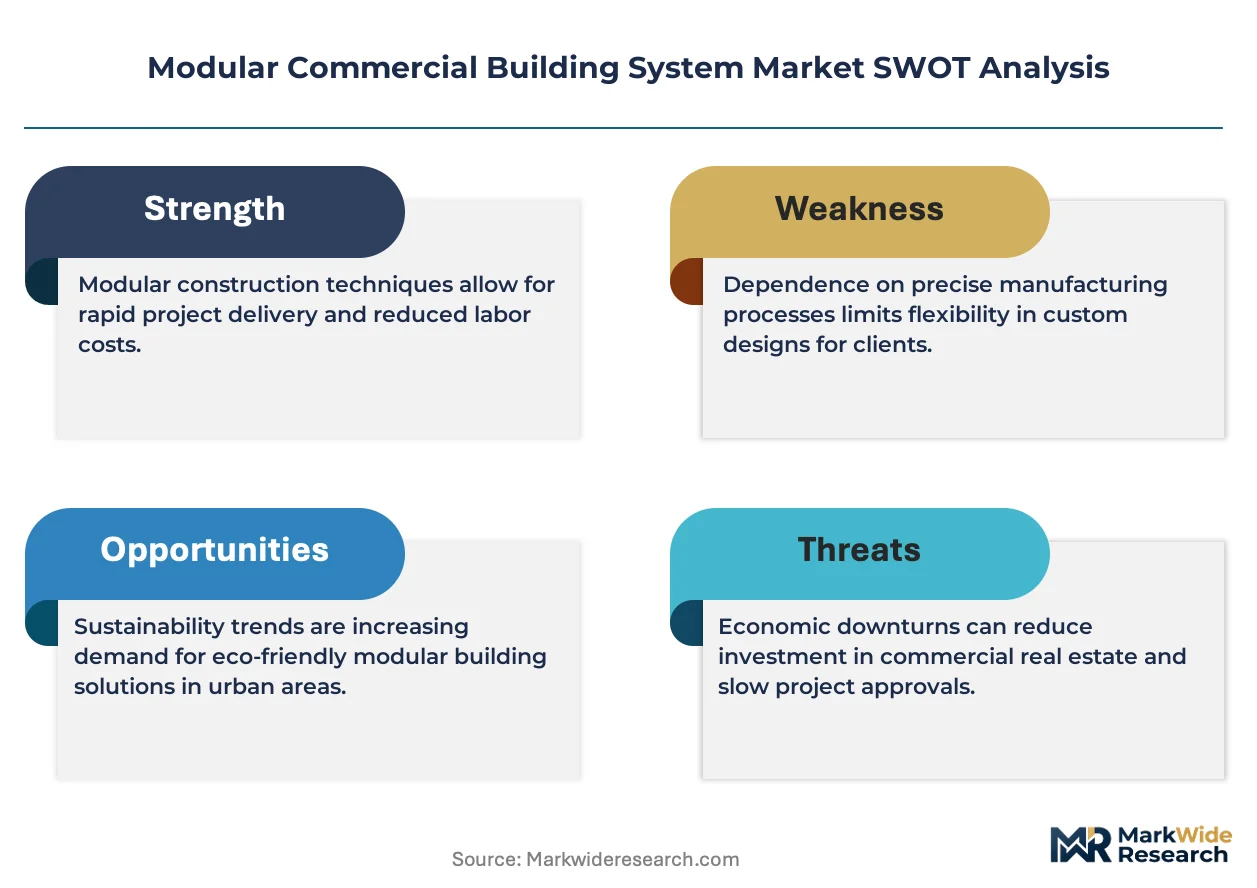
EU Green Deal embodied carbon reporting requirements are redirecting procurement specifications across the modular commercial building system value chain, compressing material selection windows and elevating low-carbon steel and timber-frame modules in competitive bids.
Growth Catalysts
- Healthcare facility acceleration:Hospital developers in Germany and the United States are specifying volumetric modules to compress program durations on acute-care expansions.
- Local Law 97:New York City's carbon caps are forcing commercial developers toward factory-built solutions with verified lifecycle emissions tracking.
- Timber-frame technology:Cross-laminated timber modules are capturing share in low-rise office and educational segments where carbon accounting governs procurement decisions.
Market Restraints
- Steel price volatility:Structural steel input costs fluctuate with energy markets, compressing margins on multi-story commercial frame contracts.
- Factory concentration risk:Volumetric module production clusters in Germany and the United Kingdom, creating geographic supply vulnerability for southern European projects.
- Dimensional transport limits:Highway corridor clearances restrict module widths to 4.3 meters in most jurisdictions, constraining open-plan commercial layouts.
Strategic Opportunities
- Remote infrastructure markets:Flat-pack panelized systems are penetrating mining and energy extraction camps in Australia and Canada where conventional construction logistics fail.
- EU AI Act compliance infrastructure:Data center developers are procuring modular server halls with embedded cooling and fire suppression to accelerate certification timelines.
- Building Safety Regulator gateway:The United Kingdom's new compliance thresholds for volumetric structures above defined heights are creating first-mover advantage for certified factory operators.
Industry Challenges
- MEP integration skill scarcity:Factory technicians capable of precision rough-in for commercial-grade mechanical, electrical, and plumbing systems command premium wages and extended recruitment cycles.
- CE marking timeline compression:EU Construction Products Regulation harmonization demands are extending factory certification cycles, delaying market entry for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Commercial Building System Market |
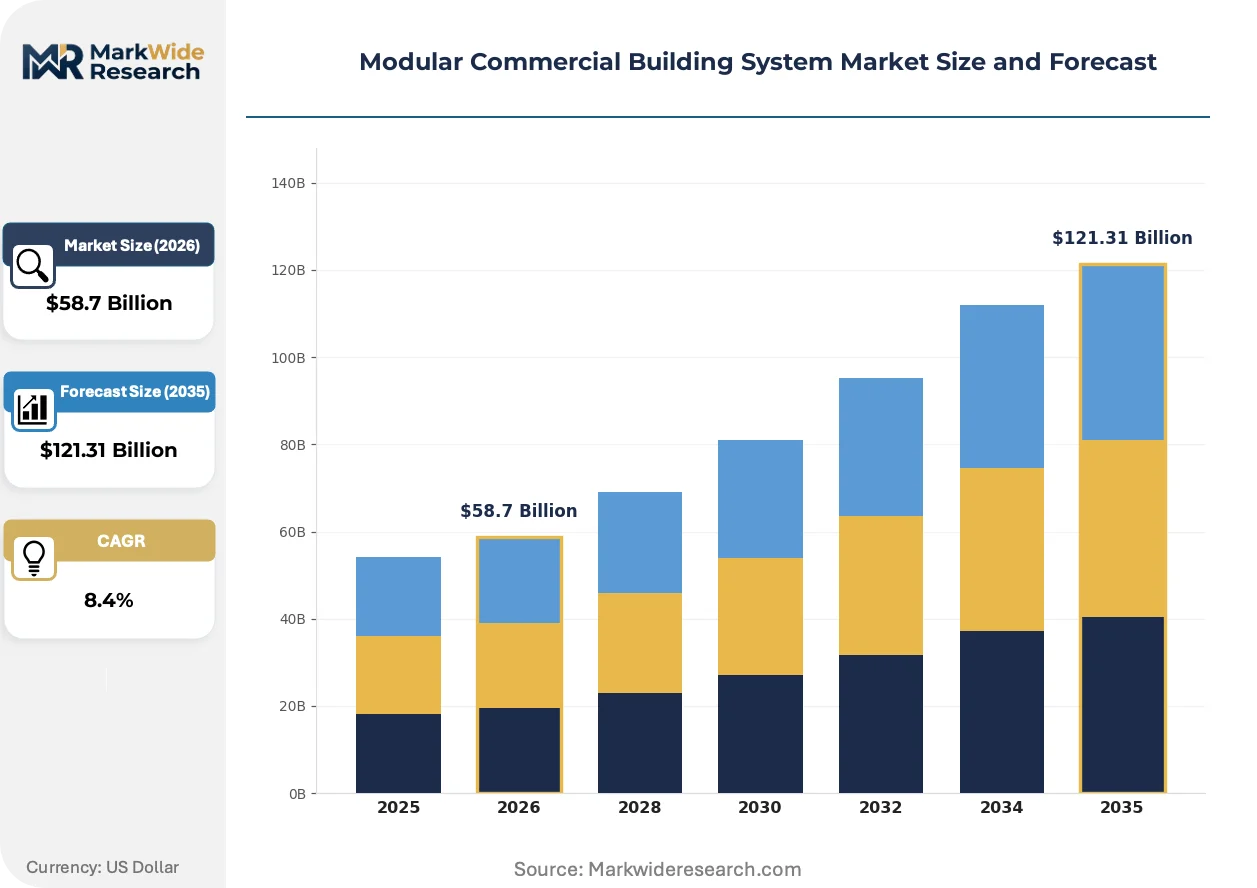
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-engineered Modules, Modular Panels, Container Units, Volumetric Modules, Flat-pack Modules Technology: Steel Frame, Timber Frame, Concrete Frame, Composite Materials, Structural Insulated Panels Application: Office Buildings, Retail Outlets, Hospitality Facilities, Educational Centers, Recreational Venues End User Industry: Construction Contractors, Property Developers, Facility Managers, Government Agencies, Corporate Enterprises |
| Companies Covered | Laing O'Rourke, Bouygues Construction, Skanska, Lendlease Corporation, Modulaire Group, ATCO Ltd., Clayton Homes, Red Sea International, Cavco Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Commercial Building System Market Trends and Innovations
Digital fabrication workflows and carbon-accounting software are converging to reshape how modular systems are engineered, certified, and procured across commercial building markets.
Building information modeling is decomposing traditional design-bid-build sequences into parallel factory engineering streams. Healthcare and hospitality developers in Germany are adopting BIM-to-fabrication pipelines that compress design-to-delivery cycles. This decomposition is collapsing the front-end engineering phase from months to weeks, enabling just-in-time module production that aligns with site readiness.
The EU Green Deal's embodied carbon disclosure mandates are forcing material specification transparency across member states. Steel and concrete suppliers must now provide Environmental Product Declarations to maintain eligibility for public and large-scale private projects. German and French commercial developers are responding by inserting timber-frame alternatives into specifications where structural loads permit, shifting competitive positioning toward forestry-integrated supply chains.
Integrated project delivery contracts are displacing conventional general contractor arrangements in complex commercial builds. Institutional investors and corporate occupiers in the United States and United Kingdom are demanding single-point accountability for cost and schedule performance. This contracting evolution is most visible in speculative office developments where yield-on-cost sensitivity drives procurement toward factory-controlled outcome guarantees rather than traditional lump-sum bids.
Modular Commercial Building System Market Segmentation
Modular commercial building systems fragment across product architecture, structural technology, and procurement channel. Each dimension carries distinct margin profiles and capital intensity requirements that reshape competitive positioning.
Product Type:
Premium margin pools concentrate in fully finished volumetric solutions where factory completion rates minimize site labor risk.
- Volumetric Modules:Factory-built three-dimensional units arrive with MEP rough-ins, interior finishes, and fixtures installed. Healthcare developers in Germany specify these for acute-care expansions where program compression justifies unit cost premiums. The EU Green Deal's embodied carbon reporting favors timber-frame volumetric variants in low-rise specifications.
- Flat-pack Modules:Panelized assemblies ship disassembled for on-site erection, reducing transport costs and dimensional constraints. Mining and energy extraction camps in Australia and Canada procure these where conventional construction logistics fail. Remote infrastructure markets are expanding most quickly for this configuration.
- Pre-engineered Modules:Standardized structural frames with partial enclosure systems serve repetitive commercial typologies.
- Modular Panels:Wall and floor assemblies integrate insulation, sheathing, and weather barriers for rapid enclosure.
- Container Units:Adapted shipping containers provide cost-competitive shell structures for temporary or mobile applications.
The dominant share belongs to Volumetric Modules, while Flat-pack Modules are closing the gap fastest.
Technology:
Structural material selection directly governs load-bearing capacity, carbon accounting eligibility, and factory capital requirements.
- Steel Frame:Hot-rolled and cold-formed steel sections deliver structural performance for multi-story commercial stacks exceeding five levels. New York City's Local Law 97 carbon caps favor steel-frame modules with verified lifecycle emissions tracking from integrated mills.
- Timber Frame:Cross-laminated timber and glulam assemblies sequester carbon and satisfy EU Green Deal procurement specifications. Educational facilities in France and low-rise office developments in Germany specify these where structural loads permit and carbon accounting governs awards.
- Concrete Frame:Precast concrete modules provide acoustic separation and fire resistance for hospitality and residential-commercial hybrids.
- Composite Materials:Fiber-reinforced polymer and hybrid assemblies target corrosion-resistant or lightweight applications.
- Structural Insulated Panels:Foam-core sandwiches combine thermal performance with rapid enclosure for climate-sensitive builds.
Steel Frame retains the largest installed base, though Timber Frame is gaining share fastest in carbon-regulated procurement environments.
Application:
End-use typologies determine finish specifications, MEP complexity, and regulatory compliance thresholds.
- Office Buildings:Speculative and corporate-occupied developments demand flexible floor plates and integrated building management systems. Institutional investors in the United States and United Kingdom procure factory-built solutions with single-point accountability for cost and schedule performance.
- Hospitality Facilities:Hotel and serviced apartment developers require high-finish interiors and repetitive room modules. German factory operators command premium positioning for volumetric hotel units where design-to-delivery cycles compress front-end engineering.
- Retail Outlets:Big-box and convenience formats prioritize rapid deployment and standardized branding elements.
- Educational Centers:Schools and universities specify timber-frame alternatives where carbon accounting influences capital project awards.
- Recreational Venues:Sports and entertainment facilities require wide-span capabilities and specialized acoustic treatments.
Office Buildings generate the highest absolute volume, with Hospitality Facilities expanding most rapidly in premium urban markets.
End User Industry:
Procurement authority and risk allocation patterns diverge sharply across customer archetypes.
- Property Developers:Yield-on-cost sensitivity drives speculative developers toward factory-controlled outcome guarantees rather than traditional lump-sum bids. Integrated project delivery contracts displace conventional general contractor arrangements in complex commercial builds.
- Construction Contractors:Design-for-manufacture expertise separates tier-one firms from commodity competitors on program duration and quality standardization.
- Government Agencies:Public procurement mandates embedded carbon disclosure and CE marking compliance, extending factory certification requirements.
- Facility Managers:Operational lifecycle considerations influence retrofit and expansion module specifications.
- Corporate Enterprises:Occupier-controlled builds prioritize sustainability credentials and single-point accountability.
Property Developers command the largest contract value, while Government Agencies are tightening compliance requirements fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors procurement specifications across Germany, where factory-built volumetric units command premium positioning in office and hospitality applications. Healthcare facility developers in the United States and United Kingdom are accelerating modular adoption to compress project timelines.
Germany
Hospital developers specify volumetric modules for acute-care expansions where program compression justifies unit cost premiums. The EU Construction Products Regulation mandates CE marking for factory-engineered systems entering cross-border trade. Manufacturing clusters in Bavaria and North Rhine-Westphalia concentrate timber-frame and steel-frame production for low-carbon steel specifications.
United States
New York City commercial developers face Local Law 97 carbon caps forcing factory-built solutions with verified lifecycle emissions tracking. California's Title 24 energy standards directly shape module specifications for projects in that market. Factory operators in the Pacific Northwest and Southeast regions are expanding capacity to serve healthcare and data center procurement.
United Kingdom
The Building Safety Regulator now mandates gateway compliance for volumetric structures exceeding defined height thresholds. This creates first-mover advantage for certified factory operators serving speculative office developments. Manufacturing concentration in the Midlands and North England supplies timber-frame alternatives where carbon accounting governs capital project awards.
France
Educational facilities specify timber-frame modules where embodied carbon disclosure influences procurement decisions under EU Green Deal mandates. The national building code harmonizes with CE marking requirements while extending factory certification cycles. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes anchor cross-laminated timber module production for low-rise office segments.
Australia
Mining and energy extraction camps in Western Australia and Queensland procure flat-pack panelized systems where conventional construction logistics fail. Remote infrastructure markets are expanding most quickly for this configuration. Factory operators in New South Wales and Victoria are scaling production to serve data center developers procuring modular server halls with embedded cooling systems.
Modular Commercial Building System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the modular commercial building system value chain. The vendor base clusters around three strategic groups: integrated construction conglomerates with Design for Manufacture and Assembly expertise, specialized volumetric fabricators serving premium healthcare and hospitality segments, and scale-driven panelized system producers targeting remote infrastructure markets. Competitive moves center on strategic partnerships for MEP integration capabilities and geographic expansion into carbon-regulated procurement environments.
Among integrated construction conglomerates, Laing O'Rourke and Bouygues Construction occupy positions exemplifying the technology leadership archetype through factory-controlled fabrication expertise. Skanska represents the sustainability credentialing tier, embedding lifecycle carbon tracking into volumetric deliveries. These three entities anchor competitive positioning across European and North American markets where single-point accountability for cost and schedule performance displaces traditional lump-sum bidding arrangements.
| Leading Market Players |
|---|
| Laing O'Rourke |
| Bouygues Construction |
| Skanska |
| Lendlease Corporation |
| Modulaire Group |
| ATCO Ltd. |
| Clayton Homes |
| Red Sea International |
| Cavco Industries |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German factory operators and healthcare developers lock in volumetric module supply while anchoring price visibility through fixed-volume, escalation-adjusted terms. These arrangements insulate procurement teams from steel price volatility while committing capital to timber-frame capacity expansion under EU Green Deal compliance timelines.
Pricing Analysis
Price spreads between German and Australian modular systems reflect transport logistics and finish-grade differentiation. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified volumetric healthcare modules from flat-pack remote infrastructure configurations. Cost compression in steel-frame multi-story segments is intensifying because energy-linked input volatility compresses margins on fixed-price contracts. Property developers exhibit highest price sensitivity on speculative office builds, while hospital operators accept premiums for program-certain delivery.
Supply Chain Analysis
Germany and the United Kingdom anchor volumetric module fabrication, while Australia and Canada specialize in flat-pack panelized production for remote extraction camps. Raw material flows draw from Swedish cross-laminated timber mills, German cold-formed steel processors, and Chinese MEP component suppliers. Single-source vulnerability concentrates in highway corridor-dependent logistics, where dimensional transport limits constrain module widths to 4.3 meters across most jurisdictions. Distribution runs through factory-direct channels for large healthcare and hospitality contracts, with regional distributors serving smaller commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular commercial building system market sits in early-cycle expansion, with EU Green Deal embodied carbon mandates accelerating factory-built procurement beyond traditional early-adopter healthcare segments.
For Market Incumbents: Consolidate MEP integration capabilities through captive technician training programs or targeted acquisition of specialized rough-in firms. Anchor capacity in Germany and the United Kingdom to capture Building Safety Regulator gateway compliance premiums before certification bottlenecks harden. Defend against timber-frame entrants by locking long-term offtake with cross-laminated timber suppliers. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in France or Germany opens access to public procurement channels where compliance timelines exclude uncertified competitors. White-space concentrates in flat-pack panelized systems for Australian mining camps and EU data center cooling-integrated server halls. Go-to-market leverage rests on demonstrating logistics feasibility in infrastructure-constrained geographies where incumbent volumetric players face dimensional transport barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale timber-frame fabricators with existing forestry-integrated supply chains and dormant CE marking pathways. Long-term viability across the projection horizon hinges on positioning for carbon-accounting procurement dominance as EU member states tighten embodied carbon disclosure thresholds. Watch for inflection when German public procurement mandates shift from voluntary to mandatory modular specifications on projects exceeding defined capital thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Timber-Frame Certification Investment | CE marking for cross-laminated timber modules unlocks EU Green Deal-compliant public procurement in Germany and France. |
| MEP Integration Capability Buildout | Captive technician pipelines address factory skill scarcity compressing recruitment cycles for healthcare volumetric contracts. |
| Flat-Pack Logistics Optimization | Panelized system weight reduction penetrates Australian mining camps where conventional construction logistics fail. |
| Building Safety Regulator Gateway Pre-Compliance | Early certification for volumetric structures above height thresholds captures first-mover positioning in United Kingdom speculative office. |
| Long-Term Steel Supply Contracting | Fixed-price offtake with integrated mills insulates margins against energy-linked input volatility in multi-story commercial frames. |
Research Methodology
The analysis maps volumetric modules, flat-pack panelized systems, steel-frame technology, and timber-frame alternatives, each validated through factory operations directors, healthcare facility developers, MEP integration specialists, and procurement leads at construction conglomerates. Primary fieldwork combined structured interviews with secondary validation against EU Construction Products Regulation filings, national building code harmonization documents, and steel trade association input cost series. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across product architectures.
Consistency checks validated output ranges against external benchmarks including factory utilization disclosures, cross-border trade flows in prefabricated building components, and capital project award databases tracking modular specification rates. The analytical framework segments by product type, structural technology, application typology, and procurement channel across the analysis window. CAGR derivation rests on capacity expansion timelines, regulatory compliance phase-in schedules, and substitution elasticity estimates for conventional on-site construction in carbon-regulated procurement environments.
Underlying assumptions cover EU Green Deal implementation pacing, steel price volatility bands, and highway corridor clearance stability, with deviation risk concentrated in regulatory timeline acceleration or MEP technician supply constraints. Forecasts reflect these documented assumptions with acknowledged sensitivity to embodied carbon mandate enforcement intensity. Recalibration cycles align with material shifts in EU member state procurement specifications and Building Safety Regulator gateway threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Soil Stabilization Market