
 India Ready-Mix Concrete Market | 2026-2036
India Ready-Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
India Ready-Mix Concrete Market Outlook
Buyer concentration across India's infrastructure sector is broadening as government agencies and large contractors consolidate procurement volumes while mid-tier builders fragment into regional clusters. UltraTech Cement Ltd dominates bulk supply chains through captive limestone reserves and pan-India plant networks. ACC Ltd differentiates through technical advisory services tied to complex infrastructure grades. Nuvoco Vistas Corp. Ltd competes aggressively in western and eastern India with dedicated RMC plants serving industrial corridors.
Ready-mix concrete consists of cement, aggregates, water, and admixtures batched at central plants and delivered in plastic condition for on-site placement, typically achieving compressive strengths from M20 to M60 grade per BIS 456 specifications. The infrastructure application segment anchors volume demand as highway and rail projects specify higher-grade mixes with controlled slump and accelerated curing properties. Specialty product types command premium positioning where corrosion-resistant or self-compacting formulations address coastal and seismic zone requirements.
BIS grade certification, CEA building energy codes, and state-level RERA compliance frameworks collectively mandate documented mix designs and quality assurance protocols that elevate barriers for unorganized batching operations. The central bank's infrastructure lending priorities and NHAI's standardized contractor pre-qualification criteria further channel demand toward certified RMC suppliers. Stakeholders must monitor evolving green building mandates and carbon accounting rules that will reshape material specifications and supplier qualification criteria.
Market Dynamics
India's ready-mix concrete market is experiencing a structural squeeze between BIS grade certification mandates and the operational fragmentation of unorganized batching operations that still command significant volume in tier-2 and tier-3 construction corridors.
Growth Catalysts
- NHAI Highway Expansion:National highway projects specify M40-M60 grade concrete with documented quality assurance, creating guaranteed offtake volumes for certified RMC suppliers.
- Metro Rail Procurement:Urban mass transit authorities in Delhi, Mumbai, and Bengaluru mandate controlled-slump mixes with accelerated curing, locking in multi-year supply contracts.
- CEA Building Energy Codes:Commercial construction exceeding specified floor areas must demonstrate embodied carbon documentation, favoring centralized batching with traceable mix designs over site-mixed alternatives.
Market Restraints
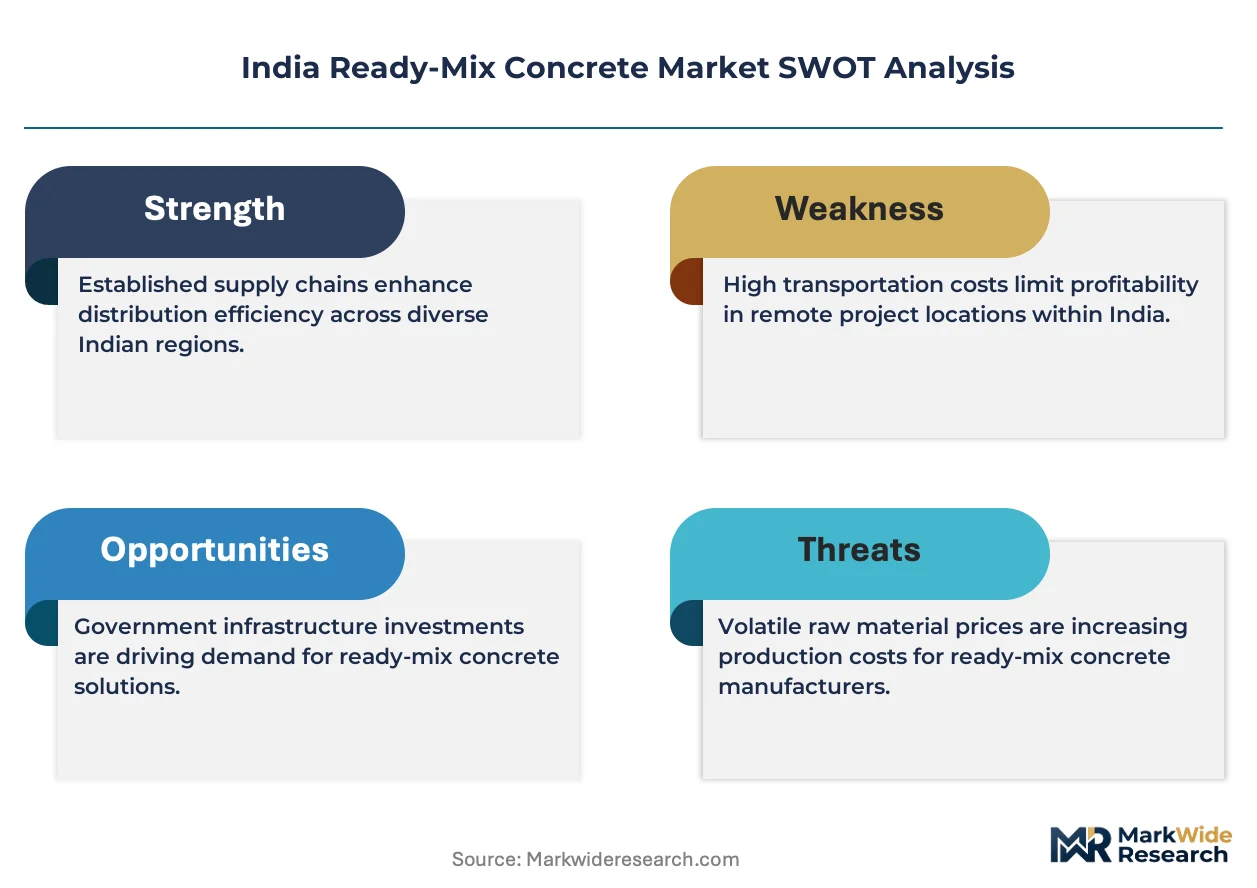
- Limestone Reserve Concentration:Captive access to quality limestone deposits clusters in Gujarat, Rajasthan, and Madhya Pradesh, creating freight-cost disadvantages for suppliers in eastern and northeastern states.
- Diesel Price Volatility:Transit mixer fleets consume high-sulfur diesel subject to fortnightly pricing revisions, compressing margins on distant deliveries beyond 50-kilometer radii.
- Seasonal Monsoon Disruption:Four-month rainfall periods across western and southern India halt outdoor placement, forcing capacity idling and fixed-cost absorption without revenue offset.
Strategic Opportunities
- Industrial Corridor Saturation:Dedicated freight corridors and port-linked manufacturing zones in Tamil Nadu and Andhra Pradesh lack established RMC infrastructure, presenting greenfield plant deployment potential.
- Self-Compacting Concrete Formulation:Dense reinforcement configurations in seismic-zone high-rises create demand for flowable mixes that reduce labor-intensive vibration requirements.
- RERA Compliance Tailwind:State-level real estate regulator mandates for documented construction quality are pushing mid-tier builders toward certified suppliers with audit-ready batch records.
Industry Challenges
- Skilled Mix Design Engineering Shortage:BIS 456 compliance requires certified concrete technologists, with accredited training programs producing fewer than 400 qualified professionals annually against industry demand.
- Admixture Supply Security:Superplasticizer and retarder chemicals rely on imported active ingredients, exposing mix consistency to shipping delays and foreign exchange fluctuation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ready-Mix Concrete Market |
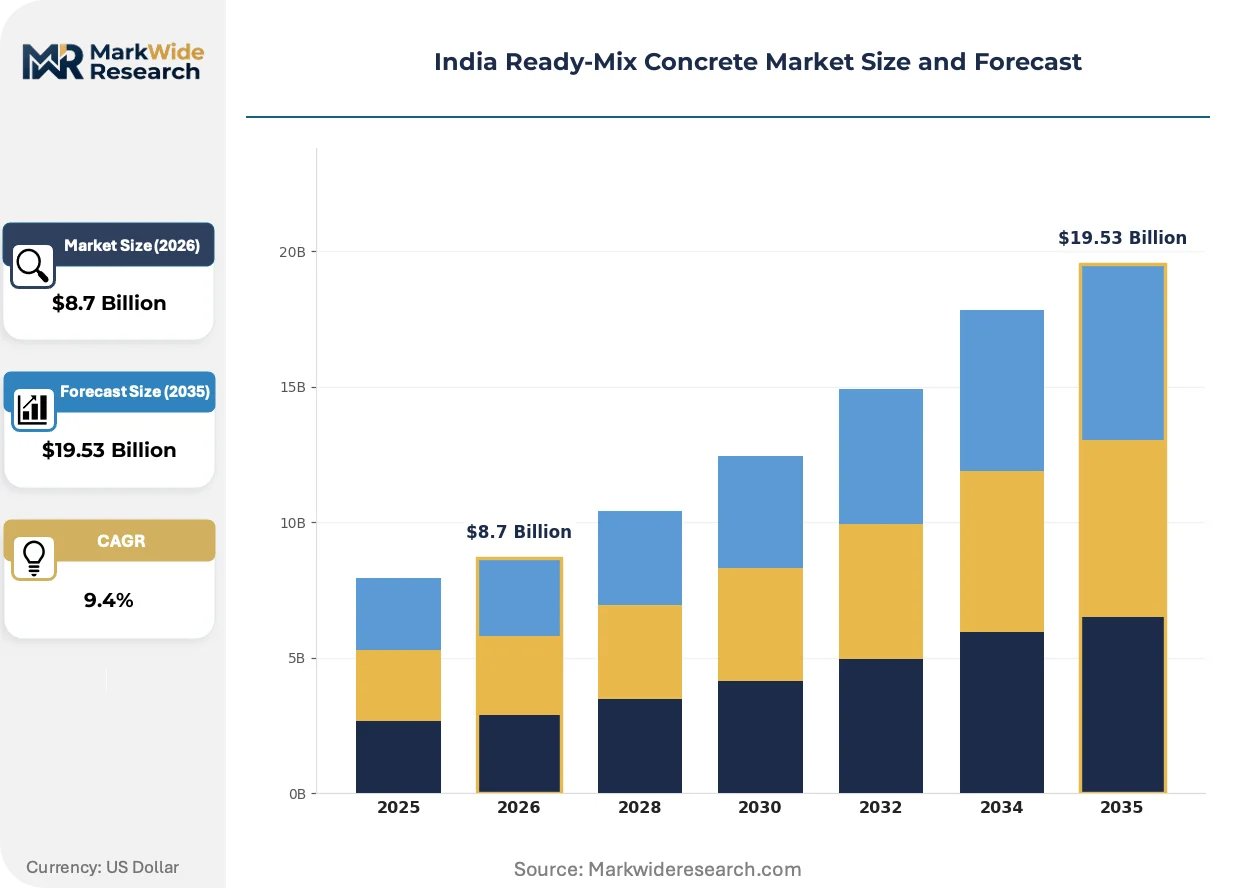
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Customized, Specialty, Eco-friendly Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Builders, Government Agencies, Homeowners Distribution Channel: Direct Sales, Retailers, Online, Distributors |
| Companies Covered | RDC Concrete India Pvt. Ltd., Sai RMC India, UltraTech Cement Ltd, Skyway RMC Plants Pvt. Ltd., SCC Group, Nuvoco Vistas Corp. Ltd., Adani Group, ACC Ltd., Prism Johnson Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ready-Mix Concrete Market Strategic Shifts
Digital batching controls and alternative binder chemistries are compressing quality variance margins while extending placement windows, reshaping how contractors schedule concrete pours across India's climatic zones.
Connected plant automation is integrating moisture sensors, weighbridge data, and GPS-tracked transit mixers into unified dispatch platforms. Large infrastructure contractors in Maharashtra and Karnataka are adopting these systems to coordinate just-in-time deliveries across multi-kilometer project sites. Real-time slump monitoring is integrating quality assurance directly into logistics workflows, reducing rejection rates at placement.
BIS has tightened permissible chloride content limits in concrete exposed to coastal environments, forcing reformulation of mixes for Mumbai, Chennai, and Kochi metropolitan construction. The revised IS 456:2000 provisions are accelerating displacement of sea-dredged aggregates with processed manufactured sand. Coastal contractors are responding by securing long-term supply agreements with inland crushing operations.
Consolidated project procurement is displacing fragmented builder-level ordering as state urban development authorities bundle RMC requirements across housing colonies and commercial complexes. This volume aggregation is compressing supplier margins while favoring producers with multi-plant networks capable of geographic redundancy. The shift is most visible in Gujarat and Telangana where development corporations pre-qualify suppliers through technical and financial capacity screening.
India Ready-Mix Concrete Market Segmentation
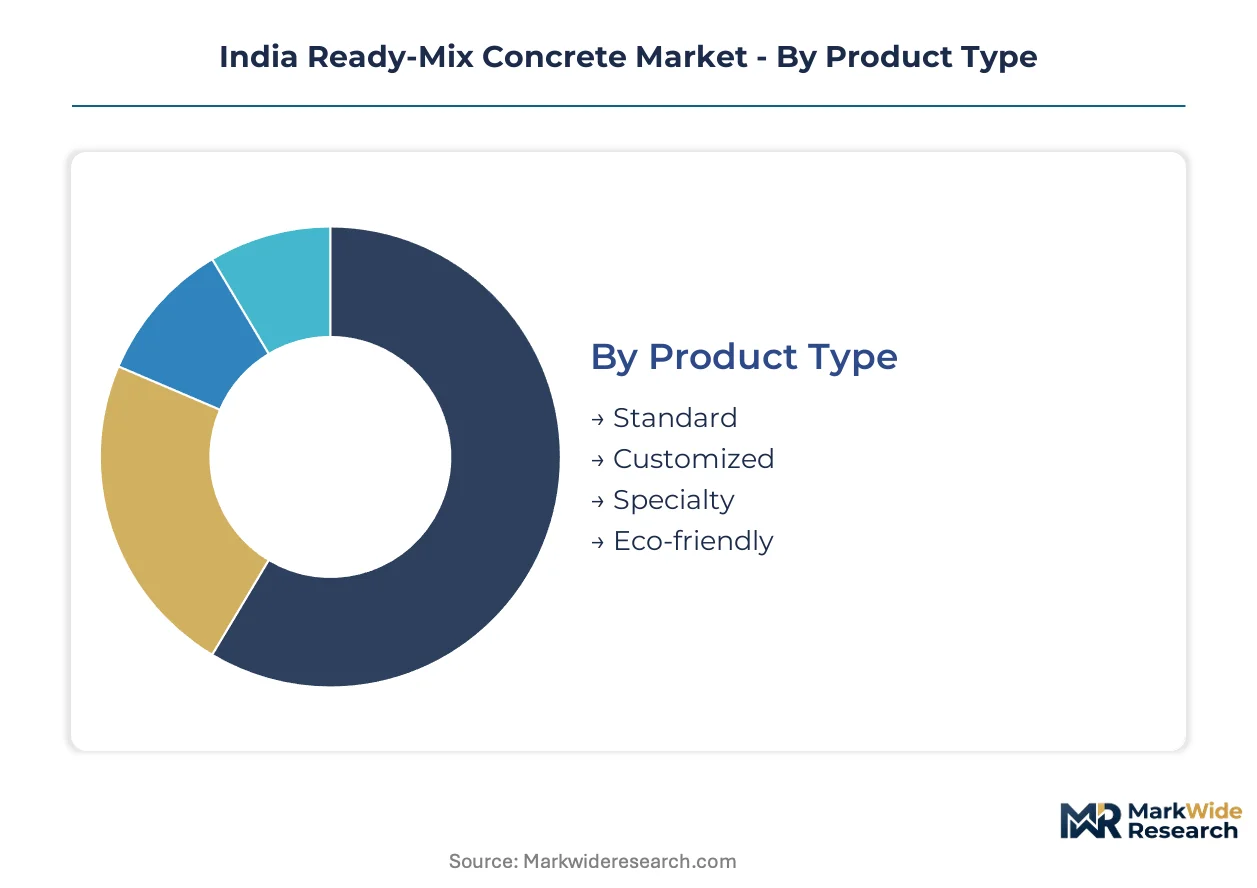
Segmentation in India's ready-mix concrete market reveals how BIS certification tiers, project scale requirements, and procurement channel preferences split demand across distinct operational and pricing bands. Contractors and government agencies prioritize documented quality assurance, while residential builders balance cost against grade compliance.
Product Type:
Standard mixes dominate volume throughput, yet premium formulations capture margin expansion as infrastructure specifications tighten.
- Standard:M20-M35 grade mixes batched to BIS 456 specifications for routine construction. Demand concentrates in Maharashtra and Gujarat residential clusters where mid-tier builders prioritize cost predictability over performance optimization.
- Customized:Project-specific formulations adjusting slump, setting time, and aggregate gradation for complex placements. Highway contractors in Karnataka and Telangana specify these for elevated corridor segments requiring extended workability windows.
- Specialty:Corrosion-resistant and high-early-strength variants for coastal and seismic zones.
- Eco-friendly:Reduced-clinker blends with fly ash or slag substitution meeting CEA embodied carbon thresholds.
Today's leader: Standard. Tomorrow's challenger: Eco-friendly.
Application:
Government procurement anchors volume, yet commercial construction offers pricing power through specification complexity.
- Infrastructure:NHAI highways and metro rail projects specifying M40-M60 grades with full quality documentation. Multi-year supply agreements in Delhi-Mumbai Industrial Corridor segments lock in certified suppliers.
- Commercial:High-rise and IT park construction in Bengaluru and Hyderabad demanding controlled-slump mixes for pumped placement. RERA compliance mandates push developers toward audit-ready batch records.
- Residential:Individual housing and apartment complexes across tier-2 cities.
- Industrial:Manufacturing plant foundations and warehouse slabs.
Infrastructure commands current procurement volumes. Commercial applications are climbing the fastest as RERA enforcement tightens.
End User:
Procurement scale and technical sophistication split the buyer base between consolidated agencies and fragmented builders.
- Government Agencies:NHAI, state PWDs, and metro rail authorities bundling multi-crore RMC requirements. Pre-qualification criteria favor suppliers with pan-India plant networks and BIS-certified quality labs.
- Contractors:Large infrastructure specialists coordinating just-in-time deliveries across kilometer-scale project sites. GPS-tracked transit mixer integration is becoming standard for national highway contractors.
- Builders:Mid-tier residential developers in tier-2 cities.
- Homeowners:Individual construction projects with small-batch requirements.
Government agencies set current procurement standards. Contractors are gaining share fastest as project bundling accelerates.
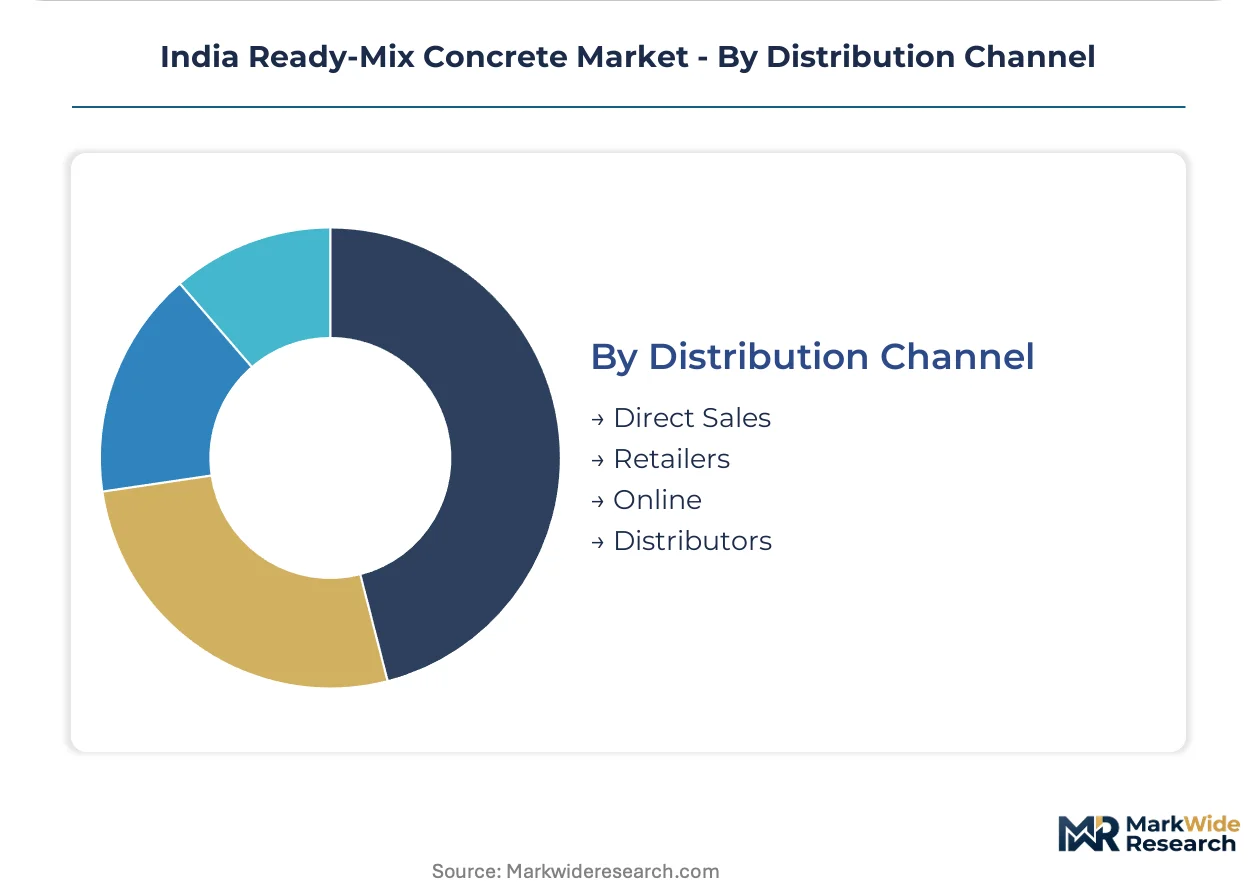
Distribution Channel:
Logistics integration and relationship depth determine channel viability across India's construction corridors.
- Direct Sales:Long-term supply contracts between RMC plants and large contractors or government agencies. Maharashtra and Gujarat infrastructure projects rely on dedicated fleet allocation with real-time dispatch coordination.
- Distributors:Regional intermediaries aggregating demand from fragmented builders in tier-2 and tier-3 markets. Eastern India depends on this channel where plant density remains thin.
- Retailers:Small-volume pickup operations serving homeowners and minor repairs.
- Online:Emerging platforms for price discovery and order placement.
Direct sales anchor current revenue concentration. Distributors represent the steepest expansion trajectory as organized RMC penetrates underserved states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's construction workforce concentrates in western and southern states where limestone reserves, port access, and metro rail investments create dense RMC demand clusters. Regional differentiation follows state-level infrastructure spending patterns and BIS enforcement intensity.
Maharashtra
Mumbai's coastal high-rises and Pune's industrial corridors drive M40-M60 grade consumption. BIS has tightened chloride limits for marine-zone construction, forcing aggregate sourcing shifts from sea-dredged to manufactured sand. The Mumbai-Pune Expressway expansion and Navi Mumbai airport lock in multi-year supply contracts with certified batching plants.
Gujarat
Captive limestone deposits in Saurashtra and Kutch anchor India's lowest-cost cement production. CEA building energy codes in Ahmedabad and Surat commercial zones mandate embodied carbon documentation, favoring fly-ash blended RMC over site-mixed alternatives. The Delhi-Mumbai Industrial Corridor segments through Vadodara and Bharuch concentrate dedicated plant networks.
Karnataka
Bengaluru's metro Phase 2 and elevated corridor projects specify controlled-slump mixes with GPS-tracked delivery. RERA enforcement in the state pushes mid-tier builders toward audit-ready batch records. The Electronic City and Whitefield IT corridors generate sustained commercial construction demand for pumped-placement concrete.
Tamil Nadu
Chennai's coastal exposure drives corrosion-resistant formulation demand under revised IS 456 provisions. The Chennai Metro expansion and port-linked manufacturing zones in Ennore lack established RMC infrastructure, presenting greenfield deployment opportunities. State PWD highway bundling is consolidating procurement toward pre-qualified suppliers.
Telangana
Hyderabad's pharmaceutical and IT park construction specifies extended workability windows for complex placements. The state urban development authority's project bundling across housing colonies compresses supplier margins while favoring multi-plant networks. ORR corridor development and metro rail procurement anchor volume demand.
India Ready-Mix Concrete Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across India's RMC market, creating a tiered structure where captive raw material access separates leaders from followers. The vendor base clusters around three strategic archetypes: integrated cement-RMC operators with limestone reserves, standalone batching specialists serving urban corridors, and construction-linked captive producers. Dominant competitive moves include backward integration into aggregate crushing and multi-plant geographic redundancy to secure NHAI pre-qualification.
Among integrated operators, UltraTech Cement Ltd and ACC Ltd exemplify the reserve-backed model with pan-India plant networks. Nuvoco Vistas Corp. Ltd occupies a focused position in western and eastern industrial corridors. These three represent how BIS certification requirements and documented quality assurance are consolidating procurement toward suppliers with captive technical infrastructure.
| Leading Market Players |
|---|
| RDC Concrete India Pvt. Ltd. |
| Sai RMC India |
| UltraTech Cement Ltd |
| Skyway RMC Plants Pvt. Ltd. |
| SCC Group |
| Nuvoco Vistas Corp. Ltd. |
| Adani Group |
| ACC Ltd. |
| Prism Johnson Ltd. |
| Others |
Value Chain & Pricing Dynamics
NHAI and state metro rail authorities bundling multi-crore procurement volumes anchor contract-based pricing with embedded quality premiums, while fragmented residential builders in tier-2 cities face spot-market volatility driven by diesel freight costs and seasonal demand swings.
Pricing Analysis
Service bundling splits the India RMC market between project-linked long-term offtake contracts and transactional spot purchases. Three-tier pricing structure across premium, standard, and economy levels separates M40-M60 infrastructure grades with full BIS documentation from M20-M35 residential mixes and unorganized site-batched alternatives. Price differentiation rests on certification grade and geographic delivery radius, with coastal corrosion-resistant formulations commanding quality premiums. Cost compression in the standard tier is intensifying because consolidated project procurement aggregates volumes across housing colonies and commercial complexes. Government agencies exhibit lowest price sensitivity due to mandated quality assurance, while individual homeowners face highest sensitivity with small-batch pickup operations.
Supply Chain Analysis
BIS certification and NHAI pre-qualification criteria gate supplier participation, favoring producers with captive limestone reserves and multi-plant networks. Geographic supply concentration centers on Gujarat, Rajasthan, and Madhya Pradesh where quality limestone deposits cluster, creating freight-cost disadvantages for eastern and northeastern states. Raw material dependencies hinge on cement clinker, processed manufactured sand, and imported superplasticizer active ingredients. Single-source vulnerability in admixture chemicals exposes mix consistency to shipping delays and foreign exchange fluctuation. Distribution runs through direct sales with dedicated fleet allocation for large contractors, supplemented by regional distributors aggregating fragmented builder demand in underserved corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India RMC market represents a late-cycle quality story as infrastructure specifications tighten toward M40-M60 grades with documented mix designs and coastal corrosion-resistant formulations displace conventional alternatives.
For Market Incumbents: Anchor pan-India plant networks through backward integration into aggregate crushing operations in limestone-deficient eastern states, defending against freight-cost disadvantages that erode margins on distant deliveries. Secure multi-year supply agreements with NHAI and metro rail authorities before pre-qualification windows close, leveraging existing BIS-certified quality labs as barriers to mid-tier challengers. For New Entrants and Emerging Players: Begin with greenfield plant deployment in Tamil Nadu and Andhra Pradesh industrial corridors where established RMC infrastructure remains thin and port-linked manufacturing zones generate concentrated demand. Target the self-compacting concrete segment for seismic-zone high-rises in Hyderabad and Bengaluru, partnering with regional distributors to aggregate fragmented builder demand without bearing full fleet capital burden. For Investors and Strategic Acquirers: Integrated cement-RMC operators with captive limestone reserves are the most active acquirer in this space, consolidating standalone batching specialists to secure geographic redundancy for NHAI pre-qualification. The 5-10 year viability window favors producers with documented carbon accounting capabilities ahead of CEA embodied carbon mandate expansion. Watch for BIS tightening chloride limits in additional coastal states as the inflection indicator accelerating displacement of unorganized batching operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aggregate Crushing | Captive manufactured sand supply secures mix consistency under tightened IS 456 chloride limits. |
| Multi-Plant Geographic Expansion | Pan-India network coverage satisfies NHAI pre-qualification criteria for bundled highway contracts. |
| Digital Batching Control Implementation | Real-time slump monitoring reduces rejection rates at placement for metro rail contractors. |
| Fly-Ash Blended Eco-Friendly Formulation | Reduced-clinker mixes align with CEA embodied carbon thresholds in Ahmedabad and Surat commercial zones. |
| Long-Term Supply Agreement with State PWDs | Project bundling across housing colonies locks in volume commitments with audit-ready batch records. |
Study Parameters
Direct dialogue with RMC plant managers, NHAI procurement officers, state PWD engineers, concrete technologists, and transit mixer fleet operators grounded the qualitative foundation, cross-referenced with BIS certification databases, NHAI contractor pre-qualification records, CEA building energy code filings, and state RERA compliance frameworks. Secondary validation drew from cement industry association reports, customs data on admixture chemical imports, and infrastructure project development databases. Bottom-up and top-down triangulation reconciled plant-level capacity assessments with aggregate demand projections across application segments.
Bottom-up modeling built volume forecasts from individual plant throughput capacities, utilization assumptions, and geographic demand clusters, while top-down approaches anchored projections in macro infrastructure spending trajectories and cement consumption correlations. Segmentation dimensions spanned product grade tier, application type, end-user procurement scale, and regional regulatory enforcement intensity. CAGRs were derived from slope analysis of year-over-year growth patterns adjusted for monsoon seasonality and project commissioning cycles. Key inputs included NHAI highway award timelines, metro rail phase completion schedules, and state-level RERA implementation pace.
Several conditions sit outside the modeled scope, including abrupt diesel price shocks beyond historical volatility bands, force majeure disruptions to monsoon patterns, and rapid unorganized sector consolidation through informal quality enforcement. Forecasts reflect assumptions about BIS certification adherence rates and CEA code expansion timelines that could shift materially. A model refresh is warranted upon material change in NHAI contractor pre-qualification criteria or BIS grade specification revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
North America Rainscreen Cladding Market