
 Vertical Baling Press Market | 2026-2036
Vertical Baling Press Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Baling Press Market Analytics
The gap between premium electric balers and commodity hydraulic units is repositioning procurement criteria across end-user categories. Bramidan Balers leverages its Scandinavian engineering heritage to dominate compact electric installations in Nordic distribution centers. Bollegraaf Recycling Solutions anchors its position through upstream control over sorting-to-baling integration lines for European material recovery facilities. AVERMANN Maschinenfabrik competes on manufacturing scale, sustaining cost leadership in medium-tonnage hydraulic systems for German manufacturing plants.
A vertical baling press compresses loose recyclable or waste materials into dense, uniform bales using vertically oriented rams, typically generating pressures from 20 to 200 tons depending on chamber size and drive configuration. The machine's primary purpose is to reduce material volume by ratios exceeding ten-to-one, cutting downstream transportation and storage costs for recyclers and waste handlers. Hydraulic systems still occupy the largest installed base, though electric drives represent the fastest-expanding segment as energy efficiency mandates tighten operational cost calculations. Material segmentation shows plastic and paper bales generating the densest margin pools, since contamination-sensitive buyers pay premiums for clean, high-density output from distribution centers and retail warehouses.
OSHA machine guarding standards in the United States and the EU Machinery Directive's CE marking requirements jointly shape safety interlock specifications and operator access protocols across export-bound product lines. EPA emissions guidelines for stationary equipment and REACH chemical compliance for hydraulic fluids further filter which drive technologies and seal materials gain market access. Stakeholders must monitor how pending amendments to EU waste framework directives redefine bale density standards, since tighter specifications would force retrofit cycles across installed hydraulic fleets.
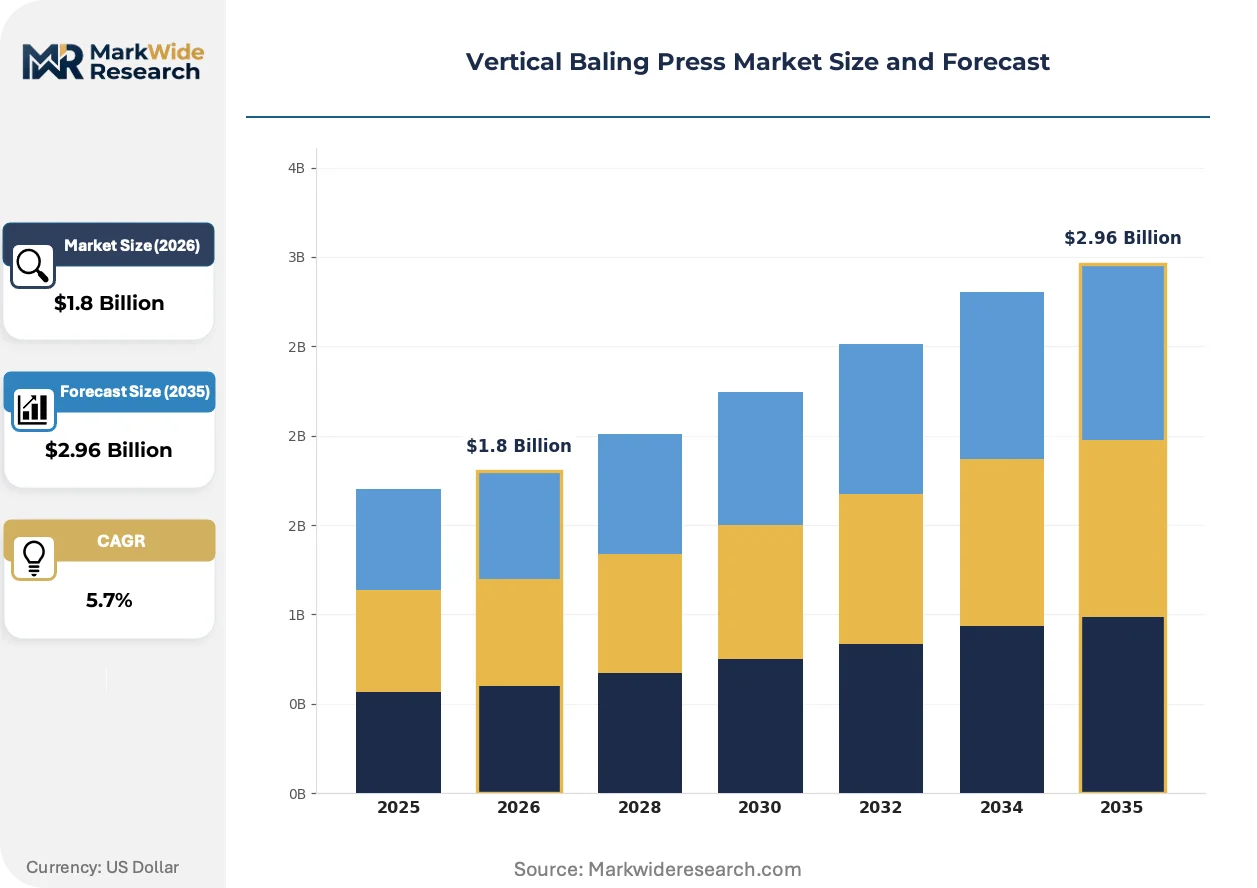
Market Dynamics
Electric drive systems are compressing the installed base advantage of hydraulic balers as energy efficiency mandates tighten operational cost calculations across recycling facilities and distribution centers.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases is accelerating electric drive adoption over hydraulic systems in European material recovery facilities, forcing fleet replacement cycles.
- Post-consumer cardboard volumes:E-commerce fulfillment centers in the United States are expanding baling capacity to handle rising packaging waste streams from retail distribution networks.
- Germany's packaging waste directives:Higher mandated material recovery rates are concentrating demand in the country's industrial belt for high-density output systems.
Market Restraints
- Steel price volatility:Chamber fabrication and ram assembly costs fluctuate with commodity input markets, compressing margins for mid-tonnage hydraulic system manufacturers.
- Hydraulic fluid compliance:REACH chemical restrictions on seal materials and fluid formulations are creating regulatory friction for legacy fleet maintenance across European installations.
- Electric drive capital intensity:Premium servo motor and control system costs limit penetration in price-sensitive municipal waste handling contracts.
Strategic Opportunities
- Underpenetrated Nordic distribution centers:Compact electric installations remain below saturation in Scandinavian logistics hubs seeking automated waste handling integration.
- Bale density standard tightening:Pending EU waste framework directive amendments would force retrofit cycles across installed hydraulic fleets, creating replacement demand.
- Sorting-to-baling integration:Convergence of optical sorting technology with compression systems opens upstream control positions for equipment providers serving material recovery facilities.
Industry Challenges
- CE marking timeline compression:EU Machinery Directive safety interlock specifications require extended certification cycles for export-bound product lines, delaying market entry.
- Hydraulic-electric skill bifurcation:Maintenance technician training programs have not kept pace with drive technology diversification, creating service capacity gaps.
- Legacy system integration:Retrofitting electric drives into existing material handling workflows requires custom control architecture, extending commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Baling Press Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electric, Manual Material: Plastic, Paper, Metal, Textile End User: Recycling Facilities, Manufacturing Plants, Warehouses, Distribution Centers Size: Compact, Medium, Large, Extra Large |
| Companies Covered | Bramidan Balers, Bollegraaf Recycling Solutions, AVERMANN Maschinenfabrik, Ausonia, Austropressen Roither Maschinenbau, CK International, COPEX SA, Delitek AS, ECOTECNICA S.R.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Baling Press Market Evolving Landscape
Servo-electric compression technology is actively displacing fluid power architectures while regulatory chemistry restrictions and buyer consolidation reshape competitive positioning across equipment categories.
Servo-electric ram actuation is rewriting the energy efficiency calculus for high-cycle operations. Distribution centers handling continuous cardboard streams are adopting these systems at accelerating rates to meet corporate sustainability targets. The technology is rewriting the total cost of ownership models that previously favored hydraulic first-cost advantages, compressing payback period assumptions from seven years toward three.
REACH chemical compliance for hydraulic fluids is tightening formulation restrictions across European installations. Seal material substitutions and biodegradable fluid mandates are raising maintenance complexity for legacy fleet operators. German manufacturing plants and material recovery facilities face the most acute adaptation pressure, with many accelerating electric conversion timelines to avoid fluid management liability.
Buyer consolidation among third-party logistics providers is concentrating procurement authority into fewer decision-makers. Large warehousing operators are unbundling after-sales service contracts from equipment purchases, forcing manufacturers to compete on transparent lifecycle cost models rather than bundled maintenance packages. This pattern is most visible in United States distribution center networks, where national account structures dominate capital allocation for waste handling infrastructure.
Vertical Baling Press Market Segmentation
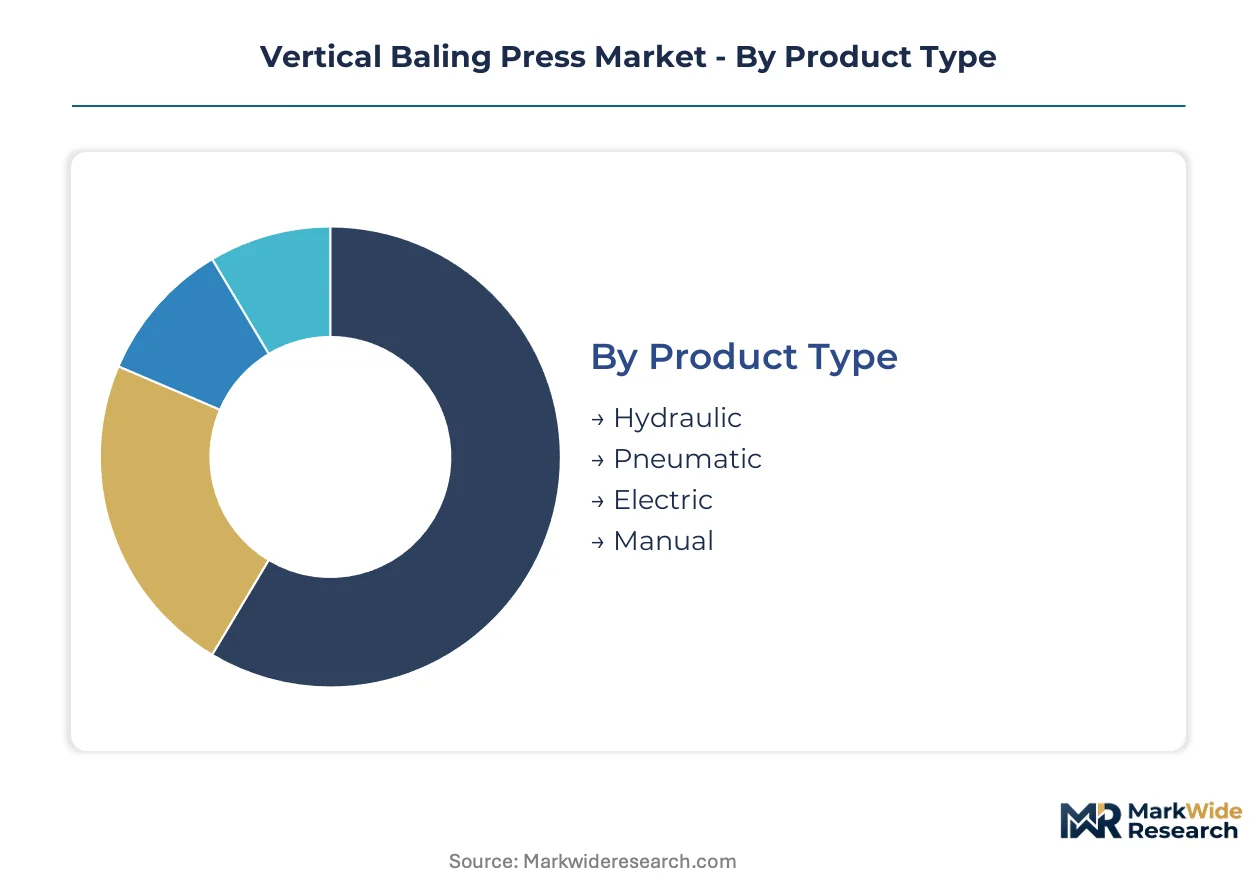
Vertical baling press procurement decisions diverge sharply between standalone installations for small-volume generators and integrated systems embedded within automated material handling lines. Understanding these integration patterns reveals which segments command premium pricing versus commodity positioning across equipment categories.
Product Type:
Standalone hydraulic units dominate independent recycling yards while electric drives penetrate embedded warehouse systems where energy efficiency mandates reshape total cost calculations.
- Hydraulic:Fluid power systems generate 20 to 200 tons of compression force through piston-driven rams, dominating installed base in independent recycling facilities where first-cost sensitivity outweighs efficiency concerns. Demand concentrates in Germany's industrial belt, where REACH chemical restrictions on hydraulic fluids are accelerating fleet replacement timelines among manufacturing plants seeking to avoid compliance liability.
- Electric:Servo motor actuation eliminates fluid power infrastructure, cutting energy consumption by half in high-cycle distribution center operations. Scandinavian logistics hubs are adopting these systems fastest as corporate sustainability targets compress payback period assumptions from seven years toward three.
- Pneumatic:Compressed air drives suit light-duty textile and foam compression in garment manufacturing clusters where explosive atmosphere risks preclude electrical systems.
- Manual:Hand-lever mechanisms serve micro-generators in rural retail locations lacking three-phase power access or capital for automated equipment.
Volume placements concentrate in hydraulic systems; the faster expansion belongs to electric drives.
Material:
Contamination sensitivity and bale density requirements segment material handling into high-margin clean streams versus commoditized mixed waste applications.
- Plastic:Film and rigid container baling demands precision compression to prevent contamination that voids buyer premiums. Post-consumer cardboard volumes from e-commerce fulfillment centers are expanding plastic film separation capacity as distribution centers seek higher material recovery rates.
- Paper:OCC and mixed paper grades generate the densest margin pools when bale density meets mill specifications. EU waste framework directive amendments pending would tighten density standards, forcing retrofit cycles across installed hydraulic fleets serving material recovery facilities.
- Metal:Ferrous and non-ferrous scrap compression requires reinforced chamber construction to withstand abrasive wear in metalworking plants.
- Textile:Fiber baling for secondary raw material markets concentrates in garment manufacturing districts with established take-back programs.
Revenue pools are deepest in paper handling; plastic applications are climbing the fastest as film packaging waste streams multiply.
End User:
Procurement authority fragmentation separates municipal contracting structures from consolidated national account decision-making in logistics networks.
- Recycling Facilities:Material recovery facilities demand sorting-to-baling integration lines with upstream optical separation compatibility. North American facilities are expanding capacity to handle rising post-consumer cardboard volumes from retail distribution networks.
- Distribution Centers:National warehousing operators unbundle after-sales service from equipment purchases, forcing transparent lifecycle cost competition. United States e-commerce fulfillment networks dominate capital allocation for automated waste handling infrastructure.
- Manufacturing Plants:Industrial waste generators prioritize reliability in continuous production environments where downtime costs exceed equipment price differentials.
- Warehouses:Third-party logistics providers concentrate procurement authority into fewer decision-makers seeking compact electric installations for space-constrained facilities.
Contract volume concentrates in recycling facilities; distribution centers are gaining share fastest as buyer consolidation accelerates.
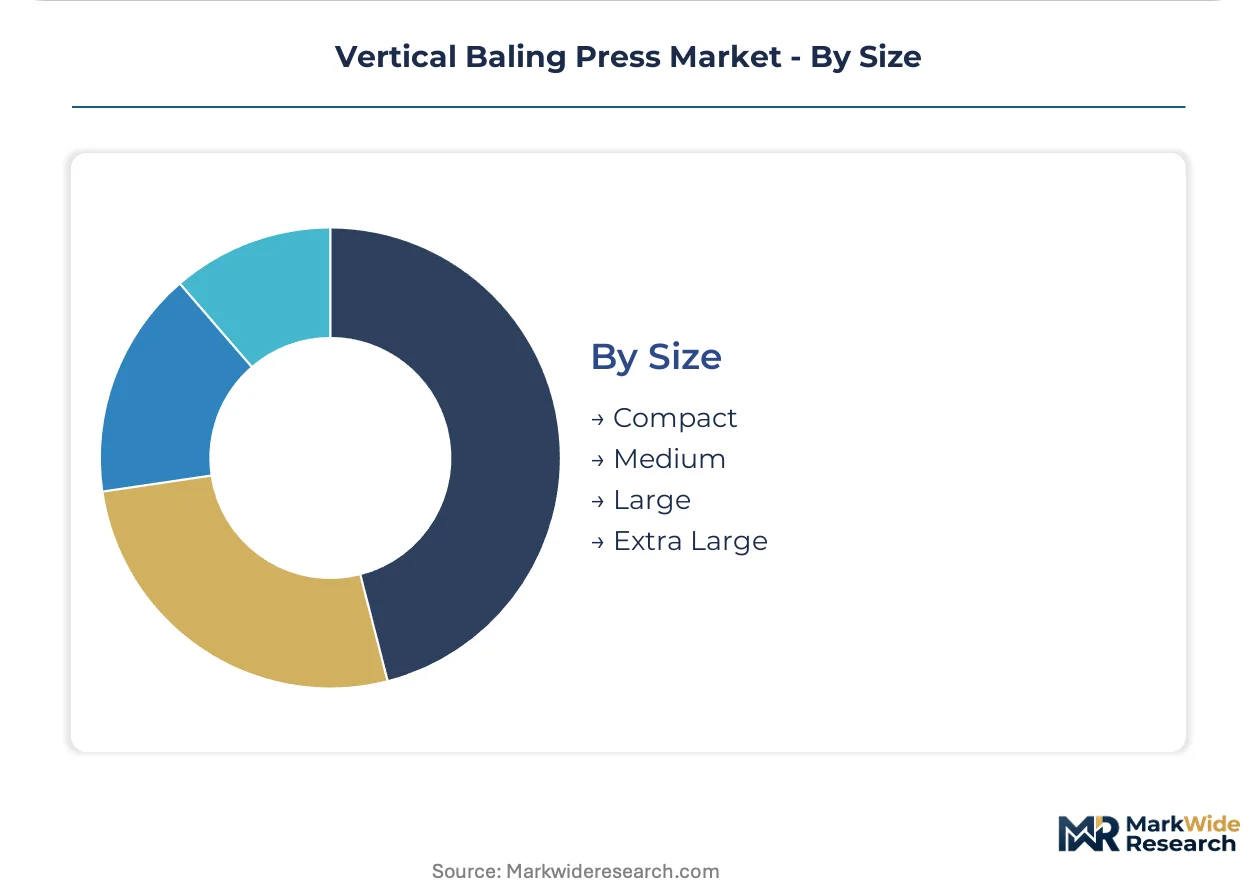
Size:
Footprint constraints and throughput requirements segment installations by chamber capacity and ram force specifications.
- Compact:Units under one meter width serve space-constrained retail backrooms and small logistics hubs where floor space commands premium valuations.
- Medium:Standard chamber dimensions balance throughput and footprint for independent recycling yards with moderate material volumes.
- Large:Extended ram stroke and expanded chamber capacity serve high-volume manufacturing plants generating continuous waste streams.
- Extra Large:Industrial-scale compression systems integrate with conveyor-fed sorting lines in material recovery facilities processing municipal collection volumes.
Shipment volume concentrates in medium tonnage; compact units are expanding most quickly as urban logistics densification intensifies space constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial belt concentrates European baling press demand as packaging waste directives tighten recovery mandates across manufacturing clusters.
United States
E-commerce fulfillment centers in California and Texas are expanding baling capacity to handle surging post-consumer cardboard volumes from retail distribution networks. OSHA machine guarding standards shape safety interlock specifications for export-bound product lines. Chicago-area logistics hubs are retrofitting hydraulic fleets with electric drives to meet corporate sustainability targets.
Germany
Manufacturing plants in North Rhine-Westphalia prioritize reliability in continuous production environments where downtime costs exceed equipment price differentials. The EU F-Gas Regulation accelerates electric drive adoption over hydraulic systems, forcing fleet replacement cycles. Bavarian material recovery facilities face acute REACH chemical compliance pressure on hydraulic fluid formulations.
China
Yangtze River Delta garment manufacturing clusters drive demand for light-duty textile compression systems where explosive atmosphere risks preclude electrical installations. The country's dual carbon goals tighten operational cost calculations for recycling facility operators. Shenzhen-area distribution centers are piloting servo-electric ram actuation for high-cycle cardboard handling.
Japan
Kanto region logistics operators unbundle after-sales service contracts from equipment purchases, forcing transparent lifecycle cost competition. METI energy efficiency guidelines reshape procurement criteria for warehouse automation investments. Osaka-area compact electric installations are penetrating space-constrained urban facilities.
India
Maharashtra's industrial corridors generate continuous waste streams requiring large-chamber compression systems for manufacturing plants. BIS standards filter equipment specifications for domestic market access. Gujarat's material recovery facilities are expanding sorting-to-baling integration capacity to handle rising municipal collection volumes.
Vertical Baling Press Market Competitive Landscape
Premium-margin players sit above commodity-margin players across drive technology specialization, with electric servo specialists commanding pricing power over hydraulic fabricators. The vendor base organizes into three tiers: integrated sorting-to-baling solution providers, standalone equipment manufacturers, and regional assembly shops serving price-sensitive municipal contracts. Strategic archetypes include upstream-integrated system architects, manufacturing-scale cost leaders, and compact-installation specialists. Dominant competitive moves center on technology licensing partnerships for servo control architectures and geographic expansion into underpenetrated Nordic distribution centers.
Among European specialists, Bramidan Balers and Bollegraaf Recycling Solutions occupy positions at opposite ends of the integration spectrum. Bramidan exemplifies the compact electric installation archetype leveraging Scandinavian engineering heritage for space-constrained logistics hubs. Bollegraaf anchors the upstream-integrated tier through control over sorting-to-baling integration lines for material recovery facilities. AVERMANN Maschinenfabrik represents the manufacturing-scale cost leadership model sustaining position in medium-tonnage hydraulic systems for German industrial plants.
| Leading Market Players |
|---|
| Bramidan Balers |
| Bollegraaf Recycling Solutions |
| AVERMANN Maschinenfabrik |
| Ausonia |
| Austropressen Roither Maschinenbau |
| CK International |
| COPEX SA |
| Delitek AS |
| ECOTECNICA S.R.L. |
| Others |
Value Network & Pricing Analysis
Scandinavian servo-electric engineering talent concentration in Denmark and southern Sweden feeds labor-cost differentials that widen pricing-tier spreads between premium electric balers and commodity hydraulic units. German hydraulic fabricators leverage proximity to Ruhr Valley steel suppliers to defend mid-market positioning against Nordic electric specialists.
Pricing Analysis
Value-based pricing anchored to bale density throughput and uptime guarantees separates premium electric installations from commodity hydraulic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-marked servo systems with integrated safety interlocks command substantial premiums over basic hydraulic units lacking EU Machinery Directive compliance. Cost compression in mid-tonnage hydraulic tiers is intensifying because steel price volatility erodes fabrication margins. Municipal waste handling contracts exhibit highest price sensitivity due to constrained capital budgets, while German manufacturing plants prioritize reliability over first-cost differentials.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national distribution center operators, while regional equipment distributors serve independent recycling yards with fragmented procurement authority. Manufacturing concentrates in Germany, Denmark, and China—German fabricators dominate hydraulic system production, Danish specialists anchor servo-electric component supply, and Chinese assembly plants feed light-duty pneumatic and manual units for Asian garment clusters. Chamber fabrication draws from high-grade structural steel and precision-machined ram assemblies, with seal materials and hydraulic fluids subject to REACH chemical restrictions. Single-source vulnerability in servo motor control architecture creates supply risk for electric drive expansion plans. Distribution runs through manufacturer-direct national accounts for large warehousing operators and authorized dealer networks for smaller installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric drive component capacity constraints—particularly precision servo motors and control systems—prop pricing power for suppliers capable of guaranteed delivery timelines. This supply-constrained structure favors incumbents with captive component sourcing.
For Market Incumbents: To counter emerging Chinese electric drive specialists, secure backward integration into servo motor manufacturing or exclusive technology licensing partnerships with European control system architects. Prioritize capacity addition in Poland or Czech Republic to circumvent German labor cost inflation while maintaining EU regulatory proximity for CE marking efficiency. For New Entrants and Emerging Players: The mid-market price-point gap between Bramidan's premium compact electrics and unbranded Asian hydraulic imports offers white-space entry opportunity. Target underpenetrated Nordic third-party logistics warehouses seeking automated waste handling integration. Lead with transparent lifecycle cost models that unbundle after-sales service from equipment purchase, mirroring procurement pattern shifts in United States distribution center networks. For Investors and Strategic Acquirers: Re-rating potential sits with sorting-to-baling integration specialists given pending EU waste framework directive amendments tightening bale density standards. Long-term viability across the analysis window favors upstream-integrated system architects over standalone equipment fabricators. Monitor German material recovery facility retrofit announcement velocity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Technology Licensing | Control system partnerships with Danish engineering specialists accelerate electric drive penetration in distribution centers. |
| Sorting-to-Baling Integration Development | Upstream optical sorting compatibility positions equipment providers for material recovery facility upgrade cycles. |
| CE Marking Pre-Certification Investment | Extended EU Machinery Directive compliance timelines favor early-mover certification strategies for export-bound product lines. |
| Nordic Distribution Center Expansion | Compact electric installation demand in Scandinavian logistics hubs remains below saturation with corporate sustainability targets tightening. |
| Biodegradable Hydraulic Fluid Formulation | REACH chemical compliance investments deflect regulatory liability for legacy fleet operators in German manufacturing plants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this vertical baling press market assessment. Primary interviews with maintenance directors at German manufacturing plants, OEM procurement teams serving distribution center networks, aftermarket service heads at European equipment providers, and plant engineers at material recovery facilities combined with secondary validation from EU F-Gas Regulation implementation reports, EPA stationary equipment emissions guidelines, and REACH chemical restriction databases. Bottom-up installation unit tracking and top-down equipment spending triangulation reconciled volume estimates.
Data-stream reconciliation across shipment records, import-export documentation, and capital expenditure disclosures stabilized segmentation outputs. Drive technology, material handling application, end-user category, and regional regulatory cluster dimensions were modeled throughout the forecast period. CAGRs were derived from installed base replacement cycles and new capacity addition trajectories. Energy efficiency mandate tightening and corporate sustainability target adoption served as primary demand-side forecast inputs, while steel price volatility and servo motor supply availability anchored supply-side constraints.
Inputs from equipment manufacturer order backlogs and recycling facility capital budgets were available through the study window; gaps in municipal waste handling contract award timing introduce uncertainty bands around public sector demand projections. Forecasts reflect assumptions regarding EU waste framework directive amendment progression and electric drive cost curve trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Slag Handling Equipment Market