
 Composite Slate Roofing Market | 2026-2036
Composite Slate Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Slate Roofing Market Analysis
Polymer resin is consolidating its position as the dominant matrix material in composite slate manufacturing, displacing traditional cementitious binders through superior impact resistance and reduced installed weight. DaVinci Roofscapes leverages proprietary mineral-composite engineering to sustain premium positioning in the residential re-roofing channel. CertainTeed Corporation anchors its competitive stance through vertically integrated polymer sourcing and national distribution scale. Brava Roof Tile differentiates via multi-width profile replication that mimics natural slate irregularity.
Composite slate roofing comprises engineered tiles manufactured from polymer blends, mineral fillers, and UV stabilizers, typically weighing one-third of natural slate while achieving Class 4 impact ratings and wind resistance to 110 mph. The product serves architects and contractors seeking authentic slate aesthetics without structural reinforcement requirements or brittle fracture risks. Polymer slate leads product type value contribution due to color-through construction and thermal stability, while rubber slate captures fastest growth from recycled tire content alignment with LEED procurement criteria. Residential application dominates volume, though institutional retrofitting commands superior per-project margins as schools and municipalities prioritize lifecycle cost over first cost.
FEMA building codes and ICC-ES AC438 acceptance criteria govern product qualification for windborne debris regions, directly constraining which formulations qualify for coastal installation permits. ASTM D638 tensile testing and ASTM D256 impact protocols create baseline performance thresholds that filter marginal suppliers from specification-grade projects. EPA stormwater regulations and evolving state-level cool roof mandates in California and Florida further shape formulation chemistry toward reflective pigments and recycled content thresholds. Stakeholders must monitor pending updates to UL 2218 impact standards and regional insurance underwriting shifts that increasingly tie premium discounts to certified impact-resistant roofing systems.
Market Dynamics
Residential re-roofing demand in hurricane-prone US states is compressing specification timelines and forcing manufacturers to accelerate impact-rated product certification cycles.
Growth Catalysts
- ICC-ES AC438 Acceptance Criteria:FEMA building codes in windborne debris regions mandate third-party validation, filtering marginal suppliers and elevating specification-grade manufacturers.
- Recycled Polymer Formulations:EPA stormwater management guidelines push ASTM D3462-compliant manufacturers toward post-consumer content to meet evolving sustainability procurement mandates.
- Southeastern US Insurance Incentives:Florida and Georgia underwriting shifts tie premium discounts to Class 4 impact-rated roofing, accelerating homeowner replacement cycles.
Market Restraints
- Petrochemical Feedstock Volatility:Polymer resin prices fluctuate with crude oil indices, squeezing margin stability for mineral-composite blenders.
- Natural Slate Substitution Threat:Authentic slate retains architect preference in historic preservation districts where authenticity premiums override lifecycle cost arguments.
- Structural Load Certification Friction:UL 2218 testing protocols create 12-18 month qualification timelines that freeze new entrants from coastal permit markets.
Strategic Opportunities
- Institutional Retrofit Channel:School districts and municipal buildings prioritize lifecycle cost over first cost, opening premium-margin projects for Class A fire-rated systems.
- California Cool Roof Mandates:Title 24 energy code updates create demand for reflective-pigmented polymer slate in high solar gain zones.
- LEED Procurement Alignment:Rubber slate from recycled tire content captures specification preference from sustainability-focused commercial developers.
Industry Challenges
- Polymer Compounding Expertise Scarcity:UV stabilizer and mineral filler optimization requires specialized formulation chemists concentrated among legacy roofing manufacturers.
- Multi-Jurisdiction Certification Burden:Separate Florida Product Approval, Texas Department of Insurance, and Miami-Dade County NOA processes fragment compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Slate Roofing Market |
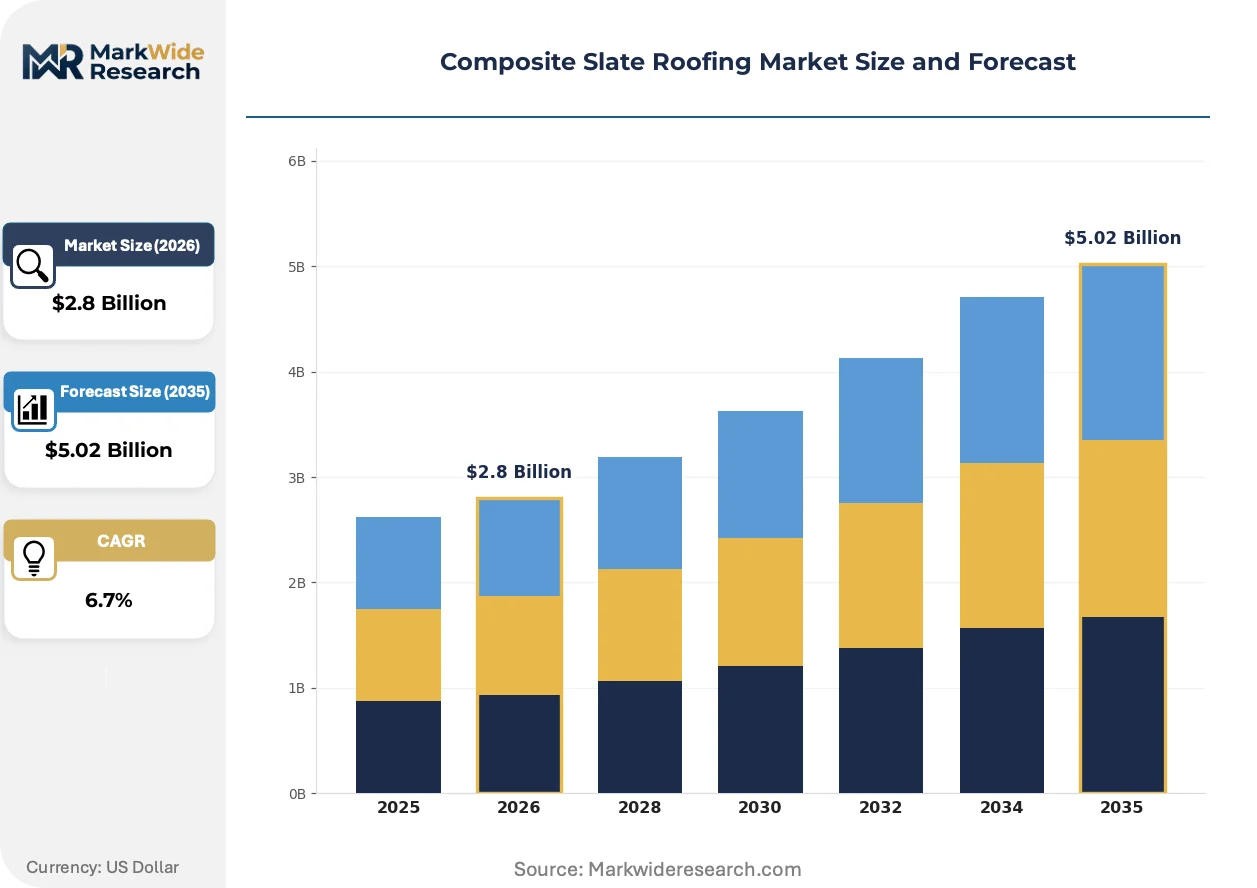
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Slate, Polymer Slate, Fiberglass Slate, Rubber Slate Application: Residential, Commercial, Institutional, Industrial Installation Type: New Construction, Retrofitting, Renovation, Repair Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | Brava Roof Tile, Ply Gem Roofing, DaVinci Roofscapes, Westlake Royal Building Products, Moderne Slate Roofing Systems, CertainTeed Corporation, Enviroshake Quality Engineered Roofing, CeDUR Synthetic Roofing Products, EcoStar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Slate Roofing Market Emerging Trajectories
Formulation chemistry and certification protocols are converging to reshape competitive positioning around impact performance and recycled content thresholds rather than aesthetics alone.
Mineral-filled polymer compounds are expanding into residential re-roofing as the dominant matrix technology. Suburban homeowners in Texas and North Carolina specify these systems for Class 4 hail resistance without structural reinforcement. The technology is expanding into hurricane-rated product lines that displace cementitious alternatives through reduced installed weight and superior thermal cycling durability.
ASTM D638 tensile testing protocols are tightening baseline performance thresholds for specification-grade projects. Manufacturers must document elongation-at-break and flexural modulus under accelerated UV exposure to qualify for coastal installation permits. Polymer slate producers with captive testing laboratories capture specification preference from architects requiring documented lifecycle performance data.
Insurance-driven procurement is compressing contractor specification cycles in Florida and Louisiana. Homeowners now demand certified impact-resistant systems upfront rather than accepting standard asphalt shingle quotes with upgrade options. This shift elevates distributor stocking requirements and pushes national roofing suppliers to carry composite slate inventory in regional hurricane belts rather than factory-direct fulfillment models.
Composite Slate Roofing Market Segmentation
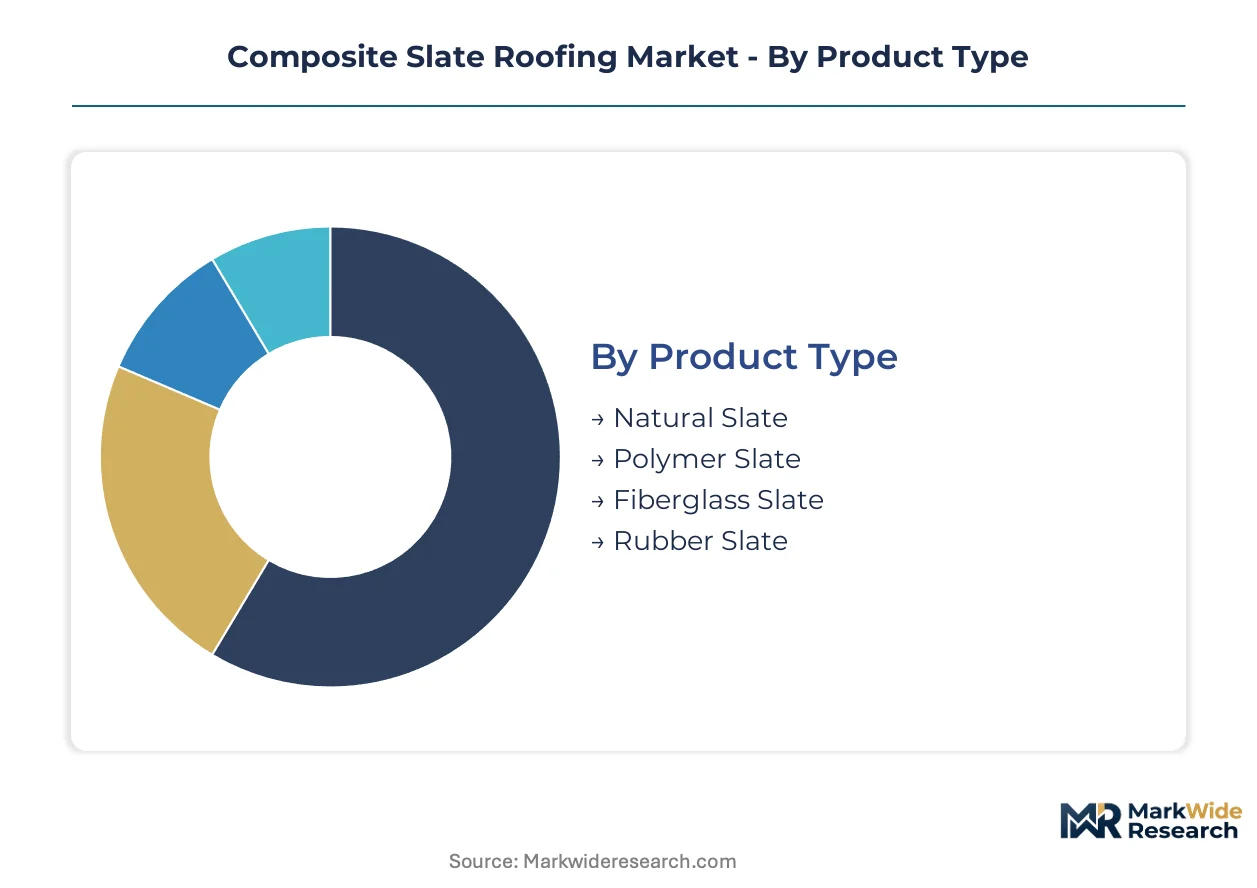
Composite slate roofing manufacturers configure production lines around material chemistry, project scale, and contractor procurement patterns. Segmentation reveals where specification-grade formulations command premium pricing versus commodity substitution.
Product Type:
Standardization dominates at the commodity end with natural slate, while engineered polymers offer customizable performance tiers for code-sensitive applications.
- Polymer Slate:Mineral-filled thermoplastic compounds deliver color-through construction and thermal stability across freeze-thaw cycles. Demand concentrates in Texas and Florida residential re-roofing, where Class 4 impact ratings satisfy insurance underwriting requirements without structural reinforcement.
- Rubber Slate:Recycled tire-derived formulations achieve LEED procurement alignment through post-consumer content thresholds. Commercial developers in California specify these systems for sustainability scoring, though UV stabilizer degradation limits warranty terms versus virgin polymer alternatives.
- Natural Slate:Quarried stone retains architect preference in historic preservation districts where authenticity overrides lifecycle cost analysis.
- Fiberglass Slate:Chopped strand mat composites offer intermediate weight reduction for coastal wind zones.
Leading the category by volume: Polymer Slate. Growing fastest: Rubber Slate.
Application:
Margin concentration follows project complexity, with institutional retrofits tolerating extended payback periods versus residential first-cost sensitivity.
- Residential:Suburban re-roofing in hurricane-prone states drives volume, with homeowners selecting impact-rated systems to capture insurance premium discounts. Florida and Georgia building codes accelerate replacement cycles beyond standard asphalt shingle lifespans.
- Institutional:School districts and municipal buildings prioritize lifecycle cost over first cost, opening premium-margin projects for Class A fire-rated systems with documented durability data.
- Commercial:Retail and office developers balance aesthetic requirements against capital expenditure constraints.
- Industrial:Warehouse and manufacturing facilities prioritize functional weatherproofing over architectural replication.
Highest revenue per square foot: Institutional. Steepest expansion trajectory: Residential.
Installation Type:
Retrofit volume reflects aging housing stock replacement, while new construction offers cleaner substrate conditions for adhesive and fastening systems.
- Retrofitting:Existing structure upgrades dominate southeastern US demand, as homeowners replace storm-damaged asphalt with impact-rated composite alternatives without structural engineering review.
- New Construction:Builder-specified systems in Texas master-planned communities integrate composite slate from architectural review committee approval through final inspection.
- Renovation:Partial roof replacement addresses isolated damage while matching existing aesthetic profiles.
- Repair:Spot fixes for wind or hail damage require inventory-matched replacement tiles.
Retrofitting commands volume share. New construction posts the fastest gains.
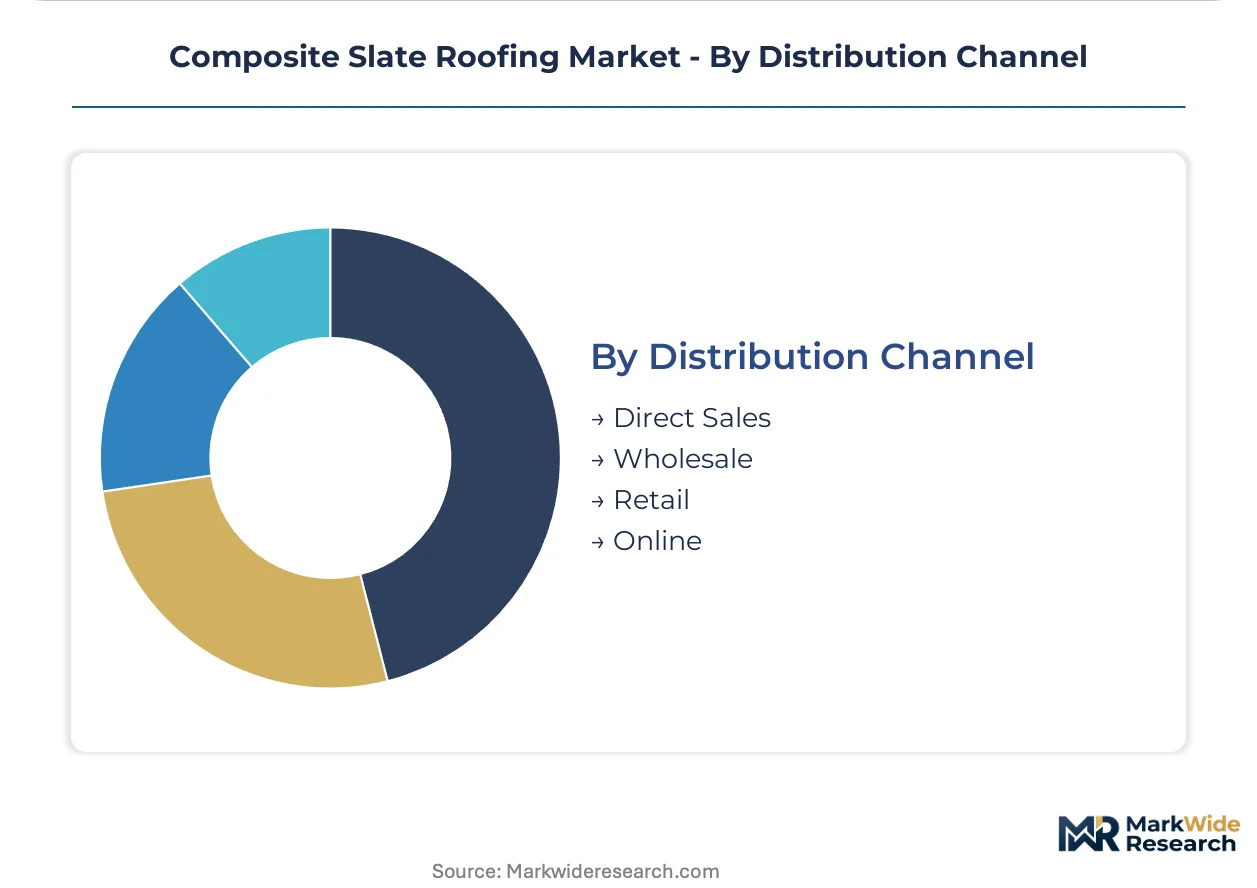
Distribution Channel:
Channel selection reflects contractor scale and project urgency, with hurricane-season demand spikes favoring stocked inventory over factory-direct fulfillment.
- Wholesale:Regional roofing distributors in Florida and Louisiana maintain composite slate inventory for contractor emergency response, compressing specification timelines during storm recovery periods.
- Direct Sales:Large-scale institutional projects bypass intermediaries for manufacturer-engineered system packages including specification support and warranty administration.
- Retail:Home improvement centers serve DIY-adjacent homeowners in suburban markets with standardized profile offerings.
- Online:Digital procurement expands for specification research and sample ordering, though final purchase remains contractor-mediated.
Wholesale anchors volume. Direct sales capture the highest project values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Florida and Texas concentrate composite slate demand through tax-advantaged redevelopment incentives. Hurricane-prone coastal counties accelerate re-roofing cycles as insurance underwriters mandate impact-rated materials.
United States
Florida's Miami-Dade County and Houston's Harris County drive residential retrofit volume through FEMA-mandated windborne debris protection. The EPA's stormwater management guidelines push manufacturers toward recycled polymer formulations. Tampa-St. Petersburg contractors stock composite slate inventory for emergency response during hurricane season.
Canada
Ontario's Greater Toronto Area prioritizes Class A fire-rated roofing for suburban infill developments. Health Canada's building code harmonization with ICC-ES standards streamlines product approval for US-exporting manufacturers. Vancouver's Lower Mainland contractors specify lightweight polymer slate for seismic zone retrofits.
Germany
Bavaria's historic preservation districts sustain natural slate preference, though polymer alternatives penetrate new construction in Munich's outer suburbs. REACH regulations constrain UV stabilizer chemistry, favoring mineral-composite formulations with documented ECHA compliance. Stuttgart's industrial belt hosts testing laboratories for accelerated weathering protocols.
United Kingdom
Southeast England's conservation areas resist synthetic materials, while Greater Manchester's housing associations specify rubber slate for social housing sustainability targets. Building Regulations Part B fire safety standards elevate Class A-rated systems in high-density London developments. Birmingham's distribution hubs stock composite inventory for midlands contractor networks.
Australia
New South Wales bushfire-prone zones mandate non-combustible roofing under AS 3959 construction standards. Sydney's North Shore architects specify polymer slate for coastal salt-spray resistance without structural reinforcement. Melbourne's southeastern suburbs drive volume through insurance-linked hail damage replacement programs.
Composite Slate Roofing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium residential channels favoring specification-grade suppliers while volume new construction tolerates private-label alternatives. The vendor base concentrates among mineral-composite formulators with captive polymer compounding capabilities and legacy roofing manufacturers extending portfolios through acquisition. Three archetypes dominate: vertically integrated polymer producers, specialty roofing distributors with in-house fabrication, and architectural product conglomerates diversifying from siding and trim. Capacity expansion in hurricane-belt distribution centers and strategic partnerships with regional insurance underwriters represent the dominant competitive moves.
Within the premium-tier specialist archetype, DaVinci Roofscapes and CertainTeed Corporation exemplify mineral-composite engineering leadership, while Brava Roof Tile occupies a differentiated position through multi-width profile replication. These three anchors represent distinct strategic postures: proprietary formulation chemistry, backward-integrated polymer sourcing, and aesthetic customization capability respectively.
| Leading Market Players |
|---|
| Brava Roof Tile |
| Ply Gem Roofing |
| DaVinci Roofscapes |
| Westlake Royal Building Products |
| Moderne Slate Roofing Systems |
| CertainTeed Corporation |
| Enviroshake Quality Engineered Roofing |
| CeDUR Synthetic Roofing Products |
| EcoStar |
| Others |
Supply Flow & Price Mechanics
Florida's insurance-linked procurement mandates compress contractor specification timelines and force distributors to carry hurricane-belt inventory, elevating spot pricing for certified impact-rated formulations while pressuring manufacturers to absorb petrochemical feedstock volatility through backward-integrated polymer sourcing.
Pricing Analysis
Short-lead-time premiums dominate contractor procurement in Louisiana and Florida during storm recovery periods, with spot inventory commanding substantial markups over factory-direct fulfillment. Three-tier pricing structure across specification-grade, builder-grade, and economy-tier formulations separates ICC-ES AC438-certified systems from marginal alternatives. Cost compression in the rubber slate segment is intensifying because recycled tire feedstock competition from other construction applications limits supply scalability. Residential re-roofing homeowners exhibit highest price sensitivity, while institutional retrofit buyers tolerate extended payback premiums for documented lifecycle performance data.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast polymer compounders concentrated in Texas and Louisiana, where hurricane disruption risk elevates inventory carrying costs for national distributors. Raw material dependencies center on mineral filler supply from Georgia and Alabama quarries, UV stabilizer chemicals subject to REACH-equivalent EPA scrutiny, and post-consumer tire rubber from regional recycling networks. Tariff exposure on specialty polymer resins creates margin instability for non-integrated formulators. Distribution runs through regional roofing wholesalers maintaining hurricane-season safety stock in Tampa, Houston, and Miami-Dade contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
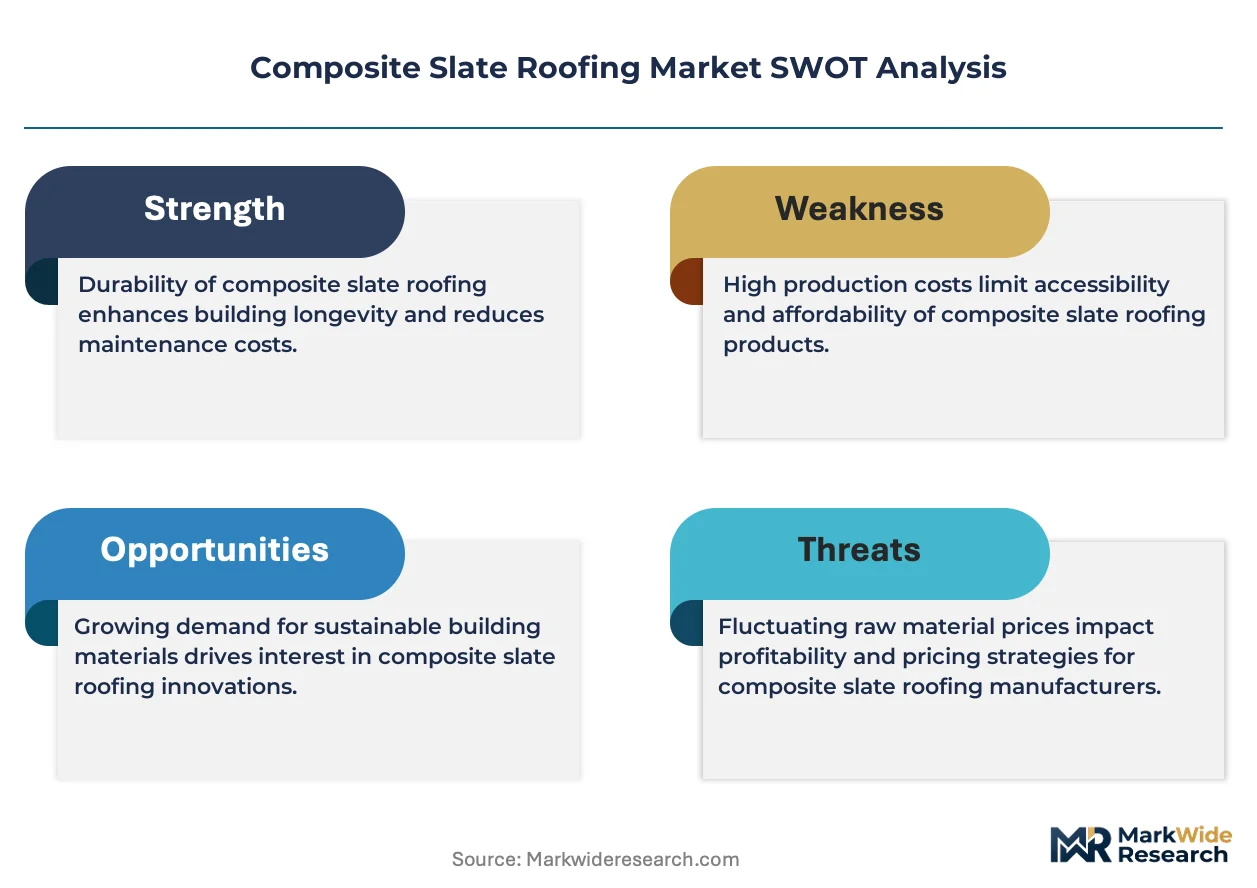
Polymer compounding expertise scarcity constrains capacity expansion, propping specification-grade pricing as ICC-ES certification backlogs freeze marginal suppliers from coastal permit markets.
For Market Incumbents: Lock in captive mineral filler supply through quarry partnerships in Georgia and Alabama, and accelerate Miami-Dade County NOA renewal cycles before UL 2218 protocol updates tighten impact testing thresholds. Natural slate substitution in historic preservation districts threatens premium residential positioning, requiring enhanced lifecycle cost documentation to defend specification preference. For New Entrants and Emerging Players: Municipal school district procurement teams represent an underserved buyer archetype prioritizing documented durability over first-cost minimization, creating white-space entry through Class A fire-rated system packages with extended warranty terms. California Title 24 cool roof compliance offers the most penetrable regulatory wedge, with reflective-pigmented polymer slate capturing specification preference from sustainability-focused commercial developers. Direct sales channel bypass of wholesale markup supports competitive positioning against established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors mineral-composite formulators with captive testing laboratories and existing ICC-ES AC438 validation, as certification timeline advantages compound over new entrants facing 12-18 month qualification freezes. Long-term viability hinges on backward integration into polymer resin supply or strategic offtake agreements with Gulf Coast petrochemical producers. Watch for Florida Product Approval board staffing expansions as the inflection signal for accelerated coastal market access.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Fast-Tracking Investment | UL 2218 and ICC-ES AC438 pre-validation secures Florida and Texas coastal permit eligibility ahead of competitors. |
| Backward Integration into Polymer Compounding | Captive resin production insulates margin stability from crude oil index volatility and Gulf Coast supply disruption. |
| Hurricane-Belt Distribution Center Expansion | Regional safety stock in Tampa and Houston compresses contractor lead times during storm recovery demand spikes. |
| Recycled Content Formulation Scale-Up | Post-consumer tire rubber alignment with LEED procurement criteria captures California commercial developer specifications. |
| Institutional Direct Sales Channel Buildout | School district and municipal lifecycle-cost-focused procurement bypasses wholesale markup and elevates project margins. |
Methodological Framework
Multi-period observation of ICC-ES certification timelines, insurance underwriting shifts, and polymer resin price indices anchored the trend analysis, supplemented by interviews with roofing contractors in Florida and Texas, specification-grade manufacturer technical directors, regional wholesale distributor inventory managers, and municipal facilities procurement officers. Secondary validation drew from EPA stormwater guideline updates, ASTM D3462 and D638 protocol revisions, FEMA building code adoption tracking, and state-level cool roof mandate filings. Bottom-up project pipeline enumeration triangulated against top-down construction spending forecasts.
Segment-weighting across product chemistry, application type, installation method, and distribution channel shaped the analytical framework, with polymer slate, rubber slate, and natural slate volume allocations calibrated to regional building permit data and insurance-linked replacement cycle surveys. CAGRs derived from regression against housing stock age profiles, hurricane frequency indices, and recycled content procurement mandate adoption curves. Forecast inputs included petrochemical feedstock futures trajectory and ICC-ES laboratory capacity expansion announcements.
Revisions become necessary when UL 2218 impact testing protocol updates materialize, when Florida or Texas insurance underwriting criteria shift, or when REACH-equivalent EPA restrictions on UV stabilizer chemistry tighten. Forecasts reflect documented assumptions regarding certification timeline stability and polymer compounding capacity growth. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Global Rainscreen Cladding Market