
 Seal Coat Market | 2026-2036
Seal Coat Market Size, Share, and Industry Trends Forecast 2026-2036
Seal Coat Market Analytics
Fragmentation among municipal procurement authorities is repositioning how seal coat suppliers structure their bidding and service networks. Crafco Inc. leverages its geographic density across Midwestern states to sustain maintenance contract renewals. SealMaster anchors its position through integrated distribution and applicator training programs. GemSeal Pavement Products differentiates via refined asphalt emulsion formulations that comply with evolving environmental standards.
Seal coat is a protective surface treatment comprising bituminous binders, mineral aggregates, and performance additives that cure to form a weather-resistant membrane over asphalt or concrete substrates. Application thickness typically ranges from 0.12 to 0.25 inches, with curing times of 4 to 24 hours depending on formulation and ambient conditions. Asphalt emulsion formulations command the largest volume share due to regulatory pressure on coal tar alternatives, while polyurethane segments attract premium pricing in industrial and high-traffic commercial settings. Acrylic products occupy a growing niche in decorative and light-duty residential driveways where aesthetic performance matters.
EPA regional offices and state-level environmental agencies enforce restrictions on polycyclic aromatic hydrocarbon content, compelling reformulation across coal tar-dependent suppliers. ASTM D5727 and AASHTO specifications govern product performance testing, creating compliance barriers for imported or non-standard formulations. Local air quality districts in California and Texas impose additional volatile organic compound limits that filter market access. Stakeholders must monitor regulatory divergence between federal baseline standards and accelerating state-level bans to anticipate raw material cost shifts and qualification requirements.
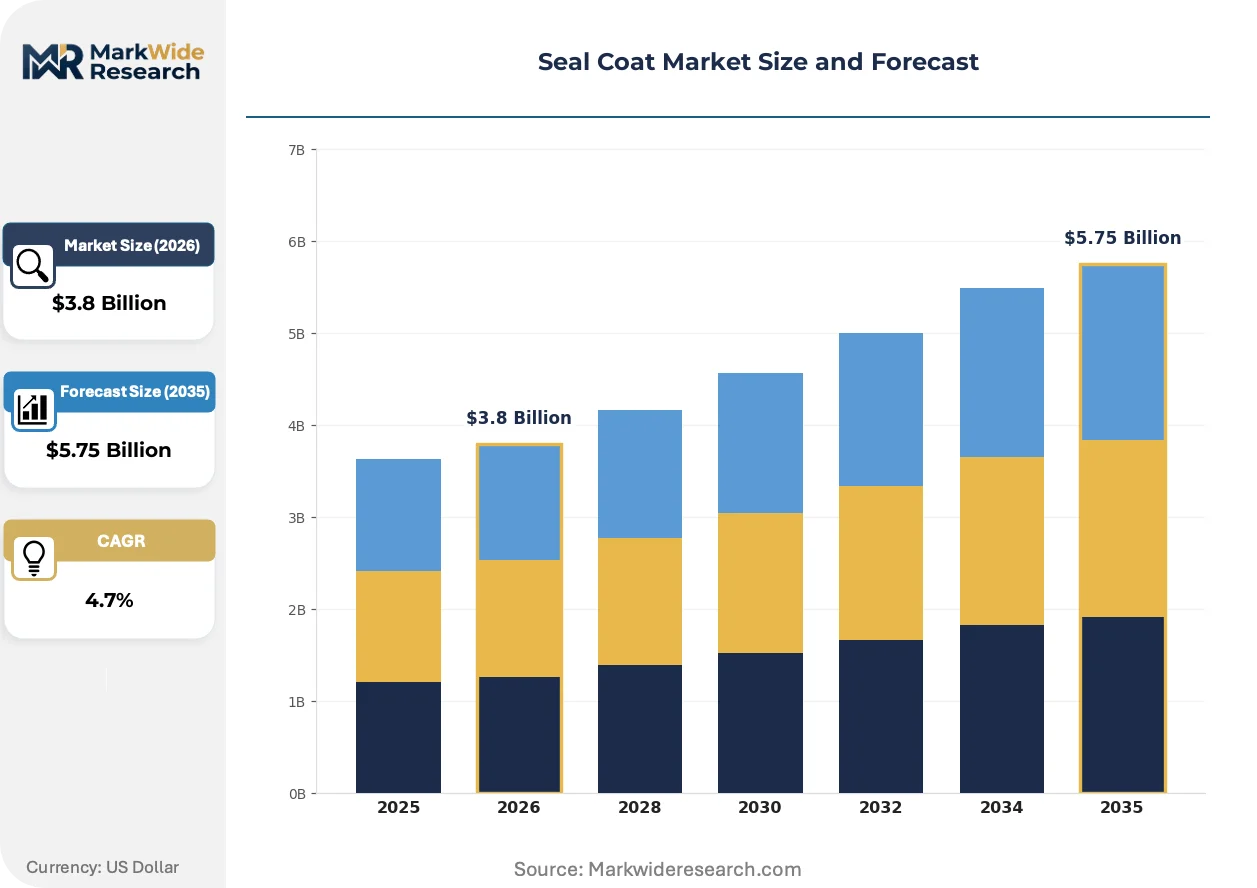
Market Dynamics
Coal tar phase-out mandates are forcing immediate formulation pivots across the seal coat supply base, with asphalt emulsion suppliers capturing displaced volume and polymer-modified alternatives gaining specification traction in high-performance segments.
Growth Catalysts
- EPA Regional Enforcement:Polycyclic aromatic hydrocarbon restrictions in the Great Lakes and Mid-Atlantic regions are redirecting municipal procurement toward compliant asphalt emulsion formulations, accelerating supplier qualification cycles.
- Municipal Resurfacing Cycles:Sun Belt infrastructure agencies are expanding seal coat program budgets to address pavement degradation from intensified thermal stress and ultraviolet exposure.
- Polyurethane Performance Tier:Industrial facility operators in logistics and manufacturing verticals are specifying high-build polyurethane systems for loading docks and heavy-traffic zones requiring extended service intervals.
Market Restraints
- Crude-Derived Input Volatility:Asphalt cement and petroleum resin costs fluctuate with refinery output decisions, compressing blending margin predictability for emulsion manufacturers.
- Application Labor Scarcity:Skilled spray-applicator availability constrains peak-season throughput in Midwestern and Northeastern markets, creating installation bottlenecks during optimal weather windows.
- Coal Tar Inventory Stranding:Distributors holding legacy coal tar stock face write-down risk as municipal specifications exclude these formulations from bid eligibility.
Strategic Opportunities
- Acrylic Residential Positioning:Decorative seal coat systems for driveway aesthetics present untapped volume in suburban housing markets where color stability and gloss retention command price premiums.
- Fast-Track Curing Chemistry:Additive packages enabling 2-to-4-hour return-to-service are capturing specification share from airport and commercial parking operators minimizing operational disruption.
- Integrated Service Contracts:Bundling material supply with surface preparation and application labor is displacing transactional product sales in municipal and commercial accounts.
Industry Challenges
- Applicator Certification Gaps:ASTM D5727 proficiency requirements and state-specific applicator licensing create training backlogs that delay crew deployment during seasonal demand peaks.
- Formulation Requalification Timelines:AASHTO performance testing protocols extend product approval cycles to 12-to-18 months, freezing supplier competitive response speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seal Coat Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Asphalt Emulsion, Coal Tar, Polyurethane Application: Paving, Driveways, Parking Lots, Industrial End User: Commercial, Residential, Government, Infrastructure Formulation: Concentrated, Ready-to-Use, Custom Blends, Eco-Friendly |
| Companies Covered | Crafco Inc., GemSeal Pavement Products, SealMaster, Seal Master Corp., GuardTop, RaynGuard, Star Seal Inc., Fahrner Asphalt Sealers LLC, Neyra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seal Coat Market Evolving Landscape
Formulation chemistry is pivoting toward bio-based modifiers and recycled content integration as regulatory pressure and circular economy mandates reshape material specifications across public infrastructure procurement.
Polymer-modified asphalt emulsions incorporating styrene-butadiene-rubber and recycled tire rubber are rewriting performance benchmarks for crack resistance and skid friction. State DOT laboratories in Texas and California are fast-tracking these specifications for high-volume roadways. The technology is compressing the traditional trade-off between environmental compliance and pavement durability that constrained earlier-generation alternatives.
REACH substance restrictions and EU Green Deal procurement criteria are filtering into North American municipal bid templates through cross-border engineering firm influence. European environmental product declarations now appear as scored evaluation criteria in RFPs issued by sustainability-committed cities. Suppliers lacking ISO-compliant lifecycle documentation face systematic disqualification from premium public contracts.
Municipal fleet operators are consolidating seal coat procurement through cooperative purchasing agreements and state-contract vehicles, displacing fragmented local bidding. Texas Department of Transportation and Florida DOT master agreements are becoming default sourcing mechanisms for county and municipal maintenance divisions. This concentration is most visible in Sun Belt states where pavement preservation program standardization reduces administrative overhead.
Seal Coat Market Segmentation
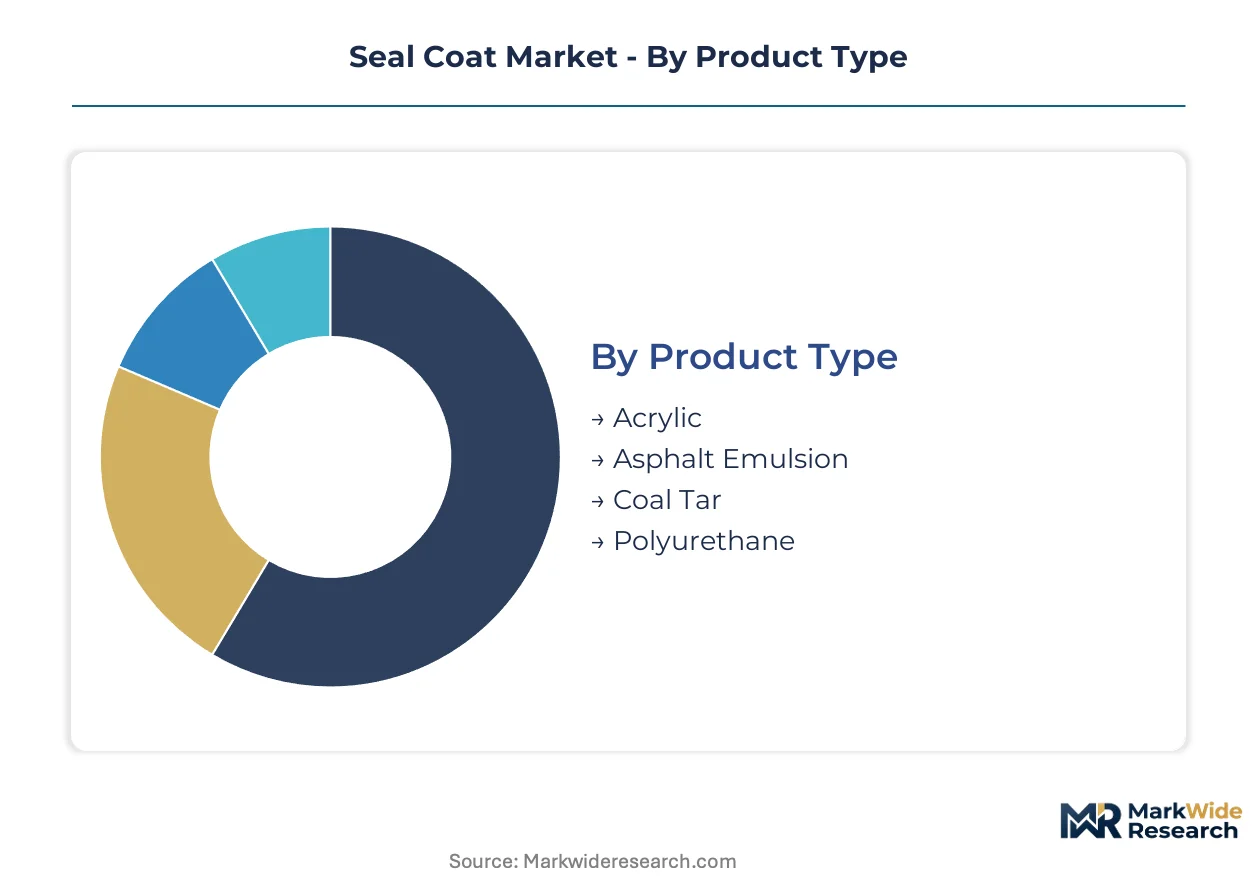
Segmentation in the seal coat market reveals how formulation chemistry, application environment, and procurement authority interact to determine supplier positioning. Understanding these divides exposes where margin pools concentrate and which specification changes threaten incumbent formulations.
Product Type:
Upgrade cycles from legacy coal tar formulations toward compliant alternatives are redrawing volume leadership across product categories.
- Asphalt Emulsion:Water-based bituminous dispersions with mineral fillers and polymer modifiers cure through evaporation to form flexible membranes. Municipal agencies in Texas and Florida specify these formulations for road resurfacing programs under EPA polycyclic aromatic hydrocarbon restrictions. The segment captures displaced volume from coal tar phase-outs.
- Polyurethane:Two-component aliphatic or aromatic systems build high-film-thickness barriers with exceptional chemical resistance and UV stability. Industrial facility operators at logistics hubs and manufacturing plants specify these for loading docks and heavy-traffic zones requiring extended service intervals between recoats.
- Acrylic:Water-dispersed polymer sealers emphasize color retention and decorative finish for aesthetic-driven applications.
- Coal Tar:Refined coal tar pitch formulations face inventory stranding as state-level bans eliminate municipal bid eligibility.
Volume placements concentrate in Asphalt Emulsion; the faster expansion belongs to Polyurethane.
Application:
Surface preparation requirements and traffic load severity segment the market by technical performance tier rather than material cost alone.
- Parking Lots:Medium-duty formulations balance skid resistance, weatherproofing, and rapid return-to-service for commercial property managers. Retail and office complex operators in Sun Belt states prioritize formulations curing within 4-to-6 hours to minimize revenue disruption.
- Industrial:High-build systems withstand chemical spills, thermal cycling, and heavy vehicle loads. Manufacturing plants and distribution centers specify polymer-modified or polyurethane chemistries for loading docks and warehouse floors where downtime costs exceed material premiums.
- Paving:Roadway and highway applications dominate municipal procurement volumes with standardized performance specifications.
- Driveways:Residential installations favor ease of application and aesthetic outcomes over extended durability.
Procurement scale favors Paving; Industrial commands the steepest expansion trajectory.
End User:
Contracting authority and budget cycle predictability determine formulation specification rigor and supplier relationship intensity.
- Government:Federal, state, and municipal agencies enforce ASTM D5727 and AASHTO compliance with documented environmental product declarations. Cooperative purchasing agreements through Texas Department of Transportation and Florida DOT consolidate procurement, favoring suppliers with master contract qualification.
- Infrastructure:Highway authorities and bridge maintenance divisions specify high-performance formulations with extended warranty requirements. State DOT laboratories in California and Texas fast-track polymer-modified specifications for high-volume roadways.
- Commercial:Property management firms and retail operators prioritize total project cost and application speed.
- Residential:Homeowner-driven demand concentrates in decorative acrylic systems for driveway aesthetics.
Budget concentration sits with Government; Infrastructure shows the most rapid specification advancement.
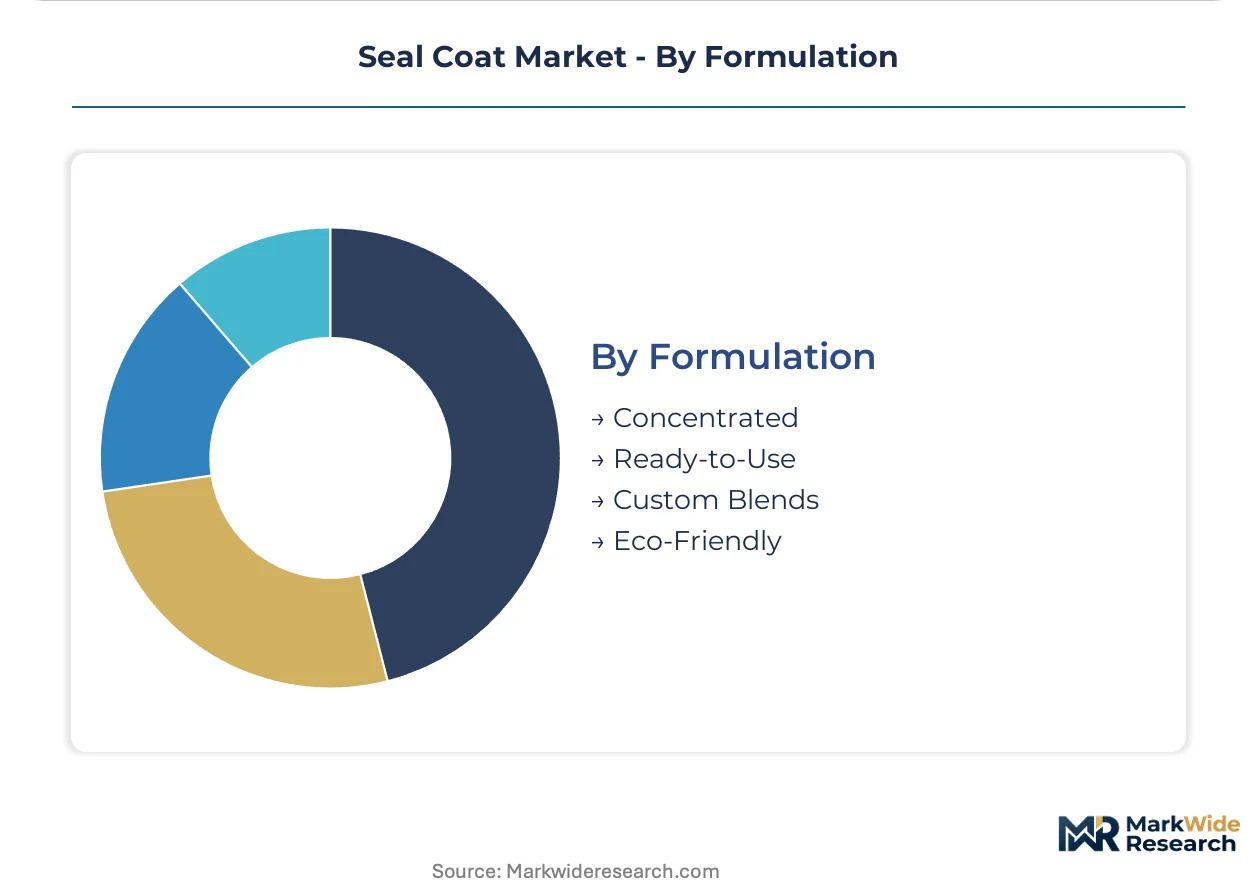
Formulation:
Supply chain configuration and blending economics separate concentrated manufacturing from localized mixing operations.
- Ready-to-Use:Factory-blended emulsions with precise solids content and additive packages eliminate field mixing variability. Municipal applicators and commercial contractors in labor-constrained Midwestern markets prefer these for consistent performance and reduced crew training requirements.
- Eco-Friendly:Bio-based modifiers, recycled tire rubber, and reduced volatile organic compound content satisfy procurement criteria influenced by EU Green Deal documentation. Sustainability-committed cities now score environmental product declarations as weighted evaluation factors.
- Concentrated:High-solids formulations reduce transportation costs and allow field dilution for large-scale projects.
- Custom Blends:Project-specific additive packages address unique substrate conditions or performance requirements.
Shipment volumes favor Ready-to-Use; Eco-Friendly is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for seal coat concentrates heavily in the United States, where municipal infrastructure agencies and state DOTs drive procurement volumes through standardized pavement preservation programs. Texas, Florida, and California dominate specification-setting and cooperative purchasing consolidation. Secondary markets in Canada and select European jurisdictions follow regulatory templates established by American environmental agencies.
United States
State DOT master agreements in Texas and Florida consolidate procurement for county and municipal maintenance divisions. EPA regional offices enforce polycyclic aromatic hydrocarbon restrictions across the Great Lakes and Mid-Atlantic, redirecting formulation demand toward asphalt emulsion alternatives. Sun Belt cities including Houston, Phoenix, and Atlanta expand seal coat program budgets to address thermal stress degradation on extensive pavement networks.
Canada
Provincial transportation ministries in Ontario and Quebec specify polymer-modified emulsions for highway resurfacing cycles. Environment Canada aligns volatile organic compound limits with California Air Resources Board stringency, filtering market access for non-compliant imports. Municipal fleet operators in the Greater Toronto Area consolidate procurement through cooperative purchasing agreements modeled on Texas DOT templates.
Germany
Federal highway administration specifications emphasize durability testing under freeze-thaw cycling conditions. REACH substance restrictions and EU Green Deal procurement criteria influence bid templates through cross-border engineering firm documentation requirements. Industrial applicators in the Ruhr Valley and Bavaria specify high-build polyurethane systems for logistics facility loading docks.
Australia
State road authorities in New South Wales and Victoria fast-track polymer-modified specifications for high-volume regional highways. Local air quality districts impose volatile organic compound limits comparable to California standards. Infrastructure maintenance contractors in Sydney and Melbourne integrate environmental product declarations as scored evaluation criteria in public tenders.
United Arab Emirates
Municipal infrastructure agencies in Dubai and Abu Dhabi specify seal coat systems for road networks subjected to extreme thermal cycling and ultraviolet exposure. Dubai Municipality procurement guidelines incorporate sustainability scoring influenced by EU Green Deal documentation standards. Commercial developers on the Al Maktoum International Airport corridor specify fast-cure formulations to minimize operational disruption during application windows.
Seal Coat Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue eco-friendly formulation niches and integrated service contracting. The vendor base clusters around three strategic archetypes: regional blending operations with dense distribution networks, national formulators with master contract qualifications, and specialized applicators bundling material supply with installation labor. Competitive moves concentrate on securing state DOT master agreements and acquiring distressed coal tar distributors facing inventory stranding.
Within the regional blending tier, Crafco Inc. and GemSeal Pavement Products exemplify geographic density strategies across Midwestern and Sun Belt markets respectively. SealMaster occupies a position as a national formulator with integrated distribution infrastructure. These three entities represent distinct approaches to municipal procurement consolidation: Crafco through maintenance contract renewals, GemSeal through refined asphalt emulsion compliance positioning, and SealMaster through applicator training program standardization.
| Leading Market Players |
|---|
| Crafco Inc. |
| GemSeal Pavement Products |
| SealMaster |
| Seal Master Corp. |
| GuardTop |
| RaynGuard |
| Star Seal Inc. |
| Fahrner Asphalt Sealers LLC |
| Neyra |
| Others |
Value Network & Pricing Analysis
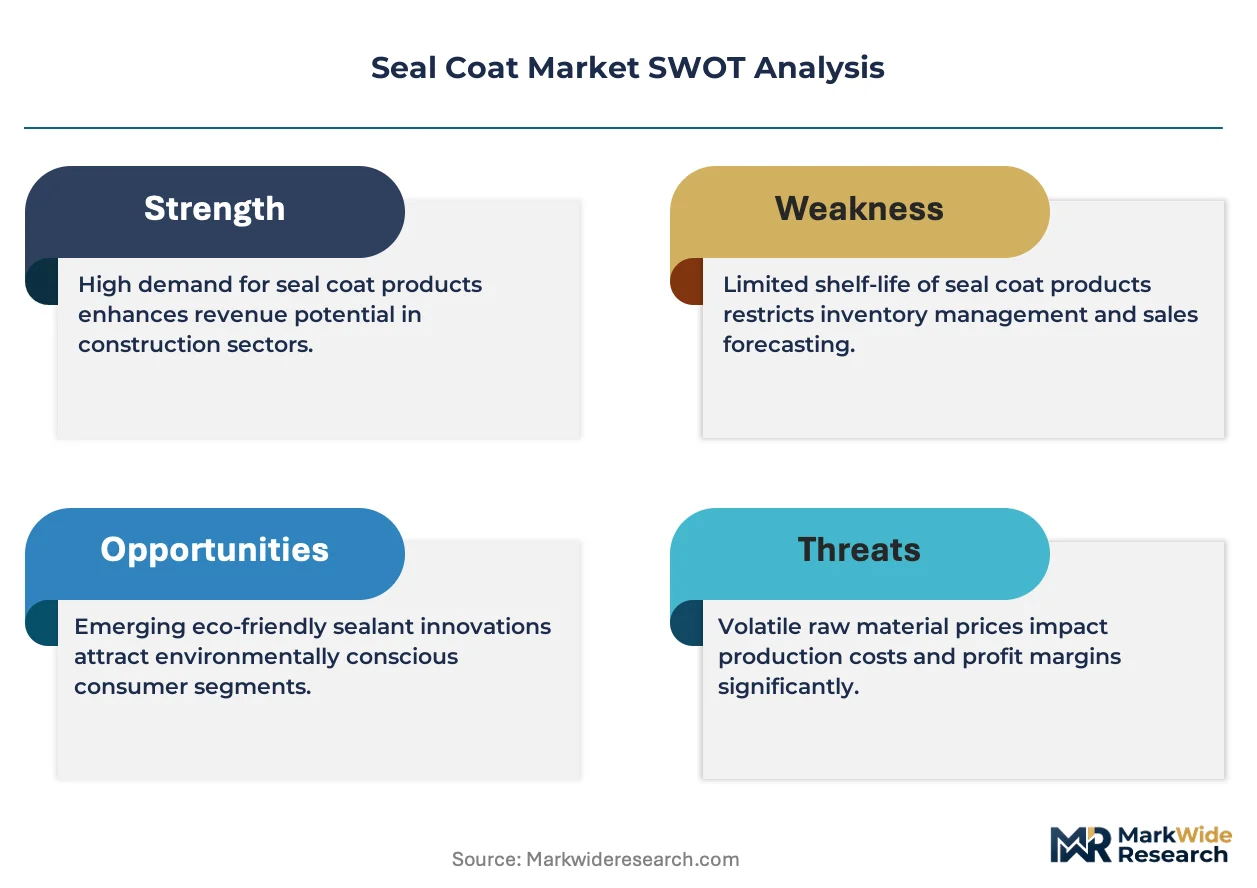
Asphalt cement costs from Gulf Coast refineries cascade through three pricing tiers before reaching municipal applicators, with polymer-modified formulations capturing margin premiums while standard emulsions compete on volume scale.
Pricing Analysis
Volume placements concentrate in standard asphalt emulsion tiers while polyurethane systems command margin premiums. Price differentiation hinges on EPA compliance certification and polymer loading rates. Pricing pressure stems from crude-derived input volatility compressing blending margins. Municipal agencies exhibit highest price sensitivity; industrial facility operators accept material premiums for extended service intervals.
Supply Chain Analysis
Recycled tire rubber flows from automotive dismantlers back into polymer-modified emulsion production, closing material loops for sustainability-committed procurement. Manufacturing concentrates in the United States, with secondary blending operations in Canada and Germany. Formulation chemistry draws from petroleum resins, mineral aggregates, and performance additives. Single-source vulnerability in specialty polymer supply creates qualification bottlenecks. Distribution runs through state DOT master agreements and cooperative purchasing vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration races into applicator training networks and captive raw material supply, with backward integration into asphalt emulsion production separating sustainable competitors from margin-squeezed blenders.
For Market Incumbents: Cement state DOT master agreement positions through integrated service contracting bundling material supply with surface preparation labor. Acquire distressed coal tar distributors facing inventory stranding to capture displaced volume relationships. Prioritize ASTM D5727 certification investments to accelerate requalification timelines against emerging polymer-modified entrants.
For New Entrants and Emerging Players: The gap between premium polyurethane systems and economy-grade acrylic residential sealers presents white-space opportunity. Target suburban driveway aesthetics in Sun Belt housing markets where color stability commands price premiums. Pursue fast-track curing chemistry specifications for airport and commercial parking operators minimizing operational disruption.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional blending operations with dense Midwestern distribution networks and maintenance contract renewal pipelines. Long-term viability centers on securing master agreement qualifications before cooperative purchasing consolidation hardens. Monitor EPA regional enforcement acceleration as inflection indicator for asphalt emulsion volume displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Asphalt Emulsion Production | Captive supply of bituminous binders insulates Gulf Coast refinery output volatility from blending margins. |
| Applicator Training Program Standardization | SealMaster's certified crew networks create switching costs for municipal procurement consolidation. |
| Fast-Track Curing Chemistry Development | Additive packages enabling 2-to-4-hour return-to-service capture specification share from airport operators. |
| Environmental Product Declaration Certification | ISO-compliant lifecycle documentation prevents disqualification from sustainability-scored municipal RFPs. |
| Cooperative Purchasing Agreement Qualification | Texas DOT and Florida DOT master agreements become default sourcing mechanisms for county maintenance divisions. |
Research Methodology
State DOT procurement databases, EPA enforcement action records, and AASHTO specification filings formed the secondary backbone. Primary interviews with municipal pavement preservation directors, asphalt emulsion plant managers, commercial seal coat applicators, and polymer additive suppliers validated demand drivers. Customs data on bituminous binder imports and refinery output disclosures anchored supply-side modeling. Bottom-up project pipelines and top-down infrastructure budget allocations were triangulated for volume reconciliation.
Historical trendline analysis of municipal resurfacing program expenditures established baseline growth patterns across the projection horizon. Segmentation modeling incorporated formulation chemistry tiers, application environment severity, and procurement authority concentration. CAGRs were derived from regression analysis against pavement network mileage, thermal stress indices, and regulatory phase-out timelines. Polymer modification adoption rates and cooperative purchasing consolidation velocity served as key forecast inputs.
Inputs from DOT budget appropriations and refinery production reports were available through the study window; gaps in real-time applicator labor availability data introduce uncertainty bands around peak-season throughput assumptions. Forecasts reflect documented assumptions regarding EPA regional enforcement pacing and state-level ban acceleration. Practitioners should monitor polycyclic aromatic hydrocarbon restriction expansion and crude price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Angular Rubber Expansion Joints Market