
 North America Roofing Market | 2026-2036
North America Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Roofing Market Insights
Market Dynamics
Canada's manufacturing base is tilting toward engineered polymer and modified bitumen capacity to serve cross-border project pipelines. Owens Corning leverages its fiberglass mat supply chain to sustain cost advantages in asphalt shingle production. CertainTeed anchors its position through specialty accessories and ventilation systems that complement core roofing sales. Carlisle Companies dominates commercial membrane segments with TPO and EPDM formulations engineered for extended lifecycle performance.
Product and Segment Structure
Roofing encompasses the design, manufacture, and installation of protective envelope systems that shield structures from precipitation, thermal transfer, and wind uplift, with modern assemblies integrating underlayment, insulation, and drainage layers to achieve fire ratings and energy performance targets. Asphalt shingles occupy the largest volume share in residential replacement, though metal roofing captures expanding share in regions with high wind-load requirements and extended warranty expectations. The commercial segment channels demand toward single-ply membranes and built-up roofing where installation type splits between new construction and renovation cycles determine contractor specialization and margin profiles.
Regulatory Environment
US building codes governed by ICC and state-level amendments shape material approval pathways, while EPA regulations on volatile organic compounds constrain adhesive and coating formulations used in low-slope applications. NRCA certification programs and manufacturer warranty standards further segment contractor eligibility and project bidding access. Stakeholders must track evolving energy code adoptions across jurisdictions and assess how insurance underwriting shifts following severe weather events will alter replacement timelines and material specifications.
Market Dynamics
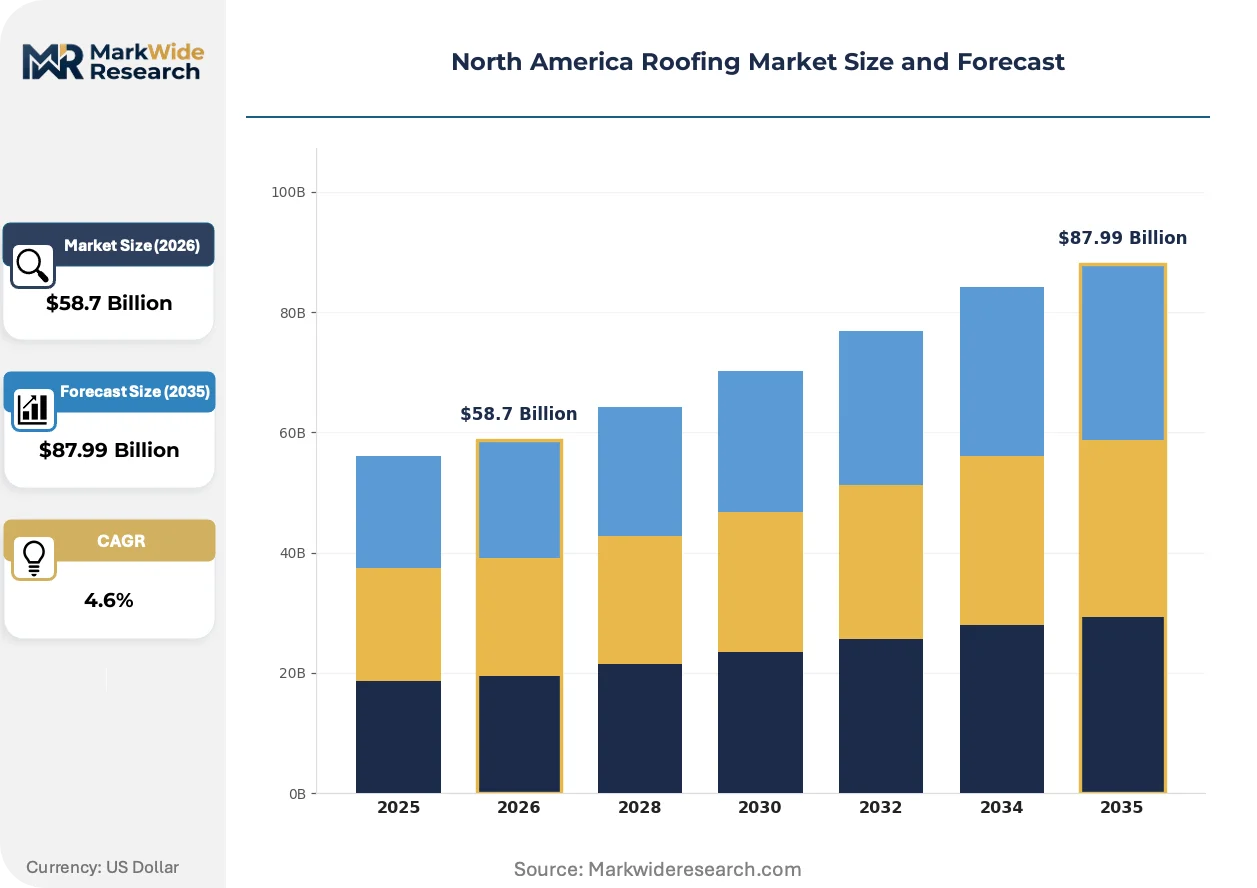
Residential retrofit activity across the Sun Belt is compressing replacement cycles as migration patterns concentrate demand in hurricane-exposed states, while California Title 24 energy codes redirect material specifications toward reflective and insulated assemblies.
Growth Catalysts
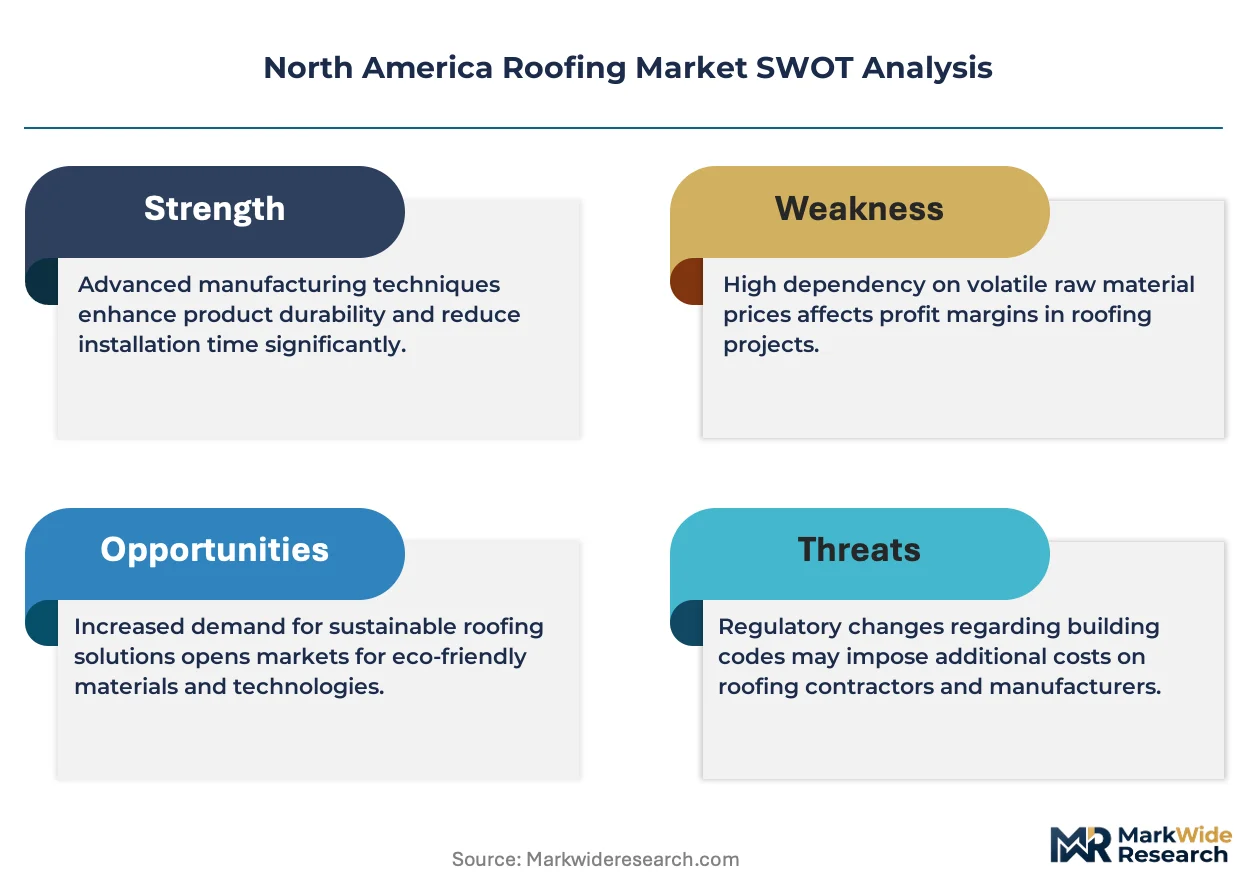
- Cool Roof Mandates:California Title 24 energy codes and parallel ordinances in Arizona and Texas jurisdictions are redirecting specifications toward reflective membrane and metal systems that reduce cooling loads.
- Hurricane Exposure:Florida and Gulf Coast wind-load requirements are accelerating metal roofing adoption in residential replacement as insurers tighten eligibility for traditional asphalt shingle coverage.
- Cross-Border Pipelines:Canadian engineered polymer capacity expansion is serving US commercial membrane demand through integrated supply chains anchored in Ontario and Quebec manufacturing bases.
Market Restraints
- Asphalt Binder Volatility:Refinery output fluctuations and petrochemical feedstock pricing are compressing margins for asphalt shingle manufacturers dependent on consistent bitumen supply.
- Adhesive Formulation Constraints:EPA volatile organic compound regulations are limiting solvent-based adhesive options for low-slope membrane attachment, forcing reformulation investments.
- Metal Sheet Concentration:Domestic steel and aluminum coil supply concentrates in a narrow supplier base, exposing contractors to lead-time volatility on standing-seam and shingle-style metal products.
Strategic Opportunities
- Photovoltaic Integration:Building-integrated solar roof tiles and membrane-ready PV mounting systems are converging as California and Texas utilities expand net-metering incentives for distributed generation.
- Texas Metro Expansion:Dallas-Fort Worth and Houston residential construction is outpacing national averages, creating white space for contractors specializing in wind-rated asphalt and entry-level metal systems.
- Direct-to-Contractor Platforms:Digital procurement channels are disintermediating traditional two-step distribution for specialty accessories and ventilation components in the residential repair segment.
Industry Challenges
- NRCA Certification Bottlenecks:Manufacturer warranty eligibility requirements are constraining contractor bidding access as training program capacity lags replacement demand surge in Florida and California markets.
- Legacy System Integration:Spray polyurethane foam recovery and re-roofing over existing built-up assemblies is complicating project scoping and moisture assessment protocols for commercial renovation contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Roofing Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
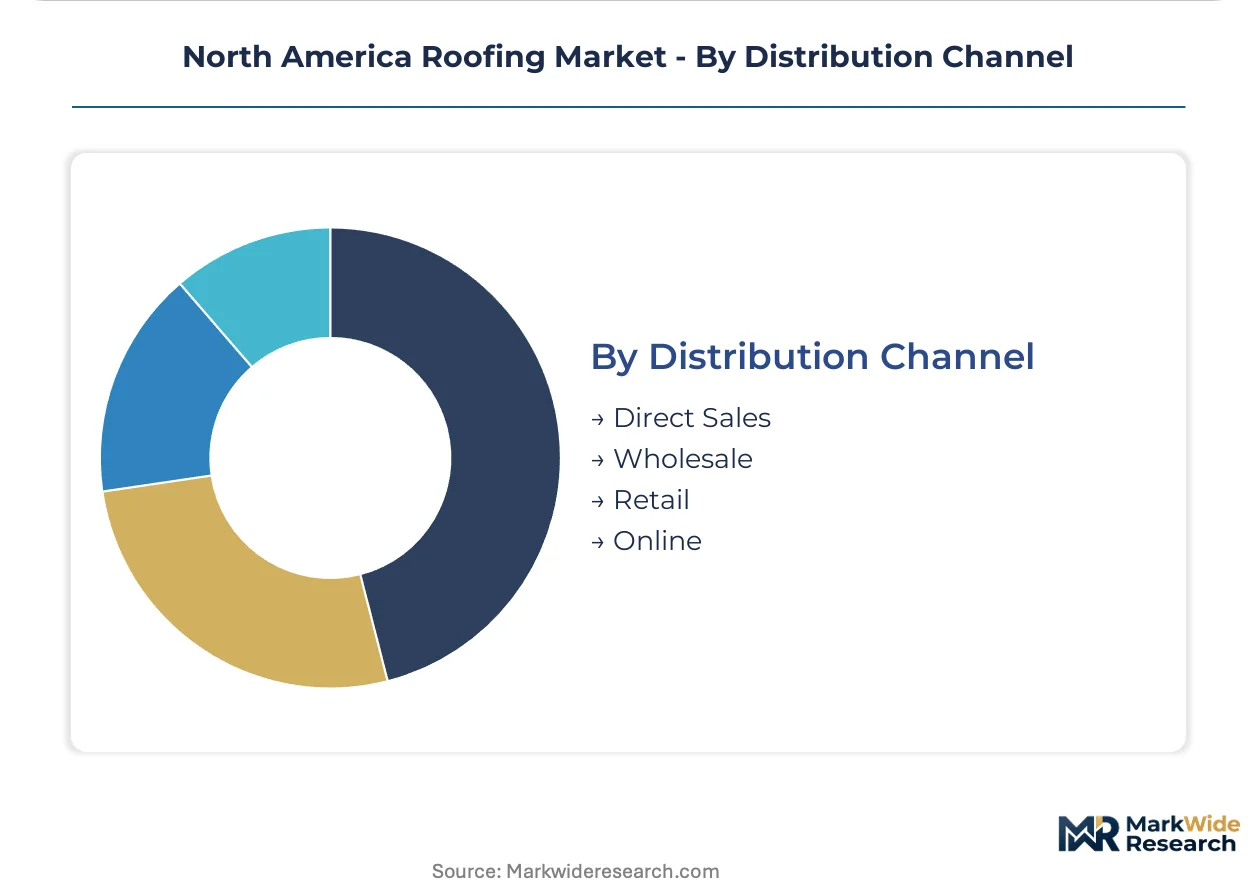
| Segmentation | Product Type: Asphalt Shingles, Metal Roofing, Clay Tiles, Built-Up Roofing End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Replacement, Repair, Renovation Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | GAF Materials LLC, Owens Corning, CertainTeed LLC, Carlisle Companies Incorporated, TAMKO Building Products LLC, IKO Industries Ltd., Johns Manville Corp., Tecta America, CentiMark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Roofing Market Trends and Innovations
Digital tools and sensor-enabled assemblies are compressing inspection cycles and reshaping how contractors validate warranty claims, while energy-code stringency is forcing material specification convergence across jurisdictions.
Aerial measurement platforms utilizing LiDAR and photogrammetry are digitizing roof geometry capture for residential contractors, reducing estimation labor and compressing bid turnaround from days to hours. Large regional installers in Texas and Florida are adopting these platforms fastest, using automated pitch and area calculations to standardize material takeoffs across distributed crews. This capability is digitizing how insurers validate storm-damage claims, accelerating settlement timelines and replacement project initiation.
California Title 24 and parallel code adoptions in Arizona are mandating minimum solar reflectance index values for low-slope commercial roofing, disqualifying dark EPDM and conventional built-up systems in new construction and major renovation. TPO and PVC membrane manufacturers are expanding light-stable pigment capacity to serve compliance-driven specification shifts. The commercial segment in California, Arizona, and Nevada is responding by consolidating procurement around single-ply systems with documented thermal emittance certification.
Homeowner purchasing patterns are fragmenting across channel types as big-box retailers expand installed-sales programs for asphalt shingle replacement, competing with established roofing contractors for the same project pipeline. Independent contractors in suburban Texas and Florida markets are responding by unbundling material supply from labor, allowing customers to source shingles through retail channels while retaining installation revenue. This disintermediation is most visible in hail-damage corridor states where insurer-preferred contractor networks are eroding traditional referral relationships.
North America Roofing Market Segmentation

Material selection across the North America roofing market splits sharply between residential retrofit cycles and commercial membrane specifications. End-use requirements, installation timing, and channel economics create distinct competitive arenas that reshape contractor specialization and manufacturer positioning.
Product Type:
Use cases span from cost-sensitive residential replacement to hurricane-rated commercial envelopes, with material specification driven by wind-load requirements, thermal performance mandates, and lifecycle cost expectations.
- Asphalt Shingles:Fiberglass-reinforced mat saturated with asphalt and surfaced with mineral granules delivers the dominant residential replacement volume. Demand concentrates in Texas and Florida suburban markets where insurer-preferred contractor networks accelerate hail-damage replacement cycles.
- Metal Roofing:Standing-seam and shingle-style profiles fabricated from galvanized steel or aluminum coil serve high wind-load zones and extended warranty expectations. Florida and Gulf Coast jurisdictions are redirecting residential specifications toward metal systems as insurers tighten eligibility for traditional asphalt coverage following repeated hurricane exposure.
- Clay Tiles:Terra cotta and concrete tile profiles provide thermal mass and fire resistance for Mediterranean and Spanish Colonial architectural styles.
- Built-Up Roofing:Multi-ply asphalt and felt assemblies with aggregate surfacing serve low-slope commercial renovation where existing substrate conditions complicate membrane conversion.
Established volume favors asphalt shingles; emerging adoption favors metal roofing.
End User:
Customer type determines specification complexity, with residential owners prioritizing aesthetic matching and commercial facilities managers emphasizing warranty terms and energy performance documentation.
- Residential:Single-family and multi-family property owners drive replacement demand through insurance claims and energy upgrade incentives. Sun Belt migration patterns concentrate activity in Texas, Florida, and California where Title 24 codes redirect specifications toward reflective assemblies.
- Commercial:Office, retail, and hospitality facilities channel procurement toward single-ply membranes with documented thermal emittance certification. California, Arizona, and Nevada jurisdictions mandate minimum solar reflectance index values that disqualify dark EPDM in new construction.
- Industrial:Manufacturing and warehouse facilities prioritize puncture resistance and chemical compatibility over thermal performance.
- Institutional:Schools, hospitals, and government buildings emphasize fire ratings and extended manufacturer warranties in competitive bidding.
Residential replacement generates the highest transaction velocity; commercial new construction commands the most complex specification protocols.
Installation Type:
Project timing shapes contractor capacity allocation, with storm-driven replacement surges compressing schedules and new construction following development cycle lags.
- New Construction:Greenfield residential and commercial development follows building permit issuance and framing completion schedules. Dallas-Fort Worth and Houston metro expansion is outpacing national averages, creating white space for contractors specializing in wind-rated systems.
- Replacement:Full tear-off and re-roofing dominates residential revenue as hurricane and hail events accelerate depreciation timelines. Florida and Gulf Coast markets are compressing replacement cycles as migration patterns concentrate demand in storm-exposed geographies.
- Repair:Spot remediation and partial replacement serves insurance deductibles and maintenance budgets.
- Renovation:Major alteration projects integrate roofing with solar readiness and insulation upgrades.
Replacement work absorbs peak contractor capacity; new construction offers more predictable scheduling.
Distribution Channel:
Channel economics fragment as digital platforms disintermediate traditional two-step distribution for specialty components and big-box retailers capture installed-sales volume.
- Direct Sales:Manufacturer-to-contractor relationships anchor commercial membrane and large residential project procurement. Carlisle Companies and Owens Corning sustain volume through dedicated account management for regional installer networks.
- Wholesale:Two-step distribution through specialty roofing suppliers serves independent contractors with credit terms and local inventory. This channel retains dominance in asphalt shingle and accessory categories.
- Retail:Big-box home improvement chains are expanding installed-sales programs for asphalt shingle replacement, competing directly with established contractors for suburban Texas and Florida project pipelines.
- Online:Digital procurement channels are disintermediating traditional distribution for ventilation components and specialty accessories in the residential repair segment.
Wholesale retains commercial membrane dominance; online platforms are gaining fastest in accessory categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes roofing materials through hurricane-driven replacement cycles and energy-code mandates, while Canada channels demand through cross-border commercial pipelines and engineered polymer manufacturing capacity.
United States
Texas and Florida dominate residential replacement volume as migration patterns concentrate demand in hail-damage corridors and hurricane-exposed geographies. EPA volatile organic compound regulations constrain adhesive formulations for low-slope commercial applications, forcing membrane manufacturers toward water-based chemistries. Dallas-Fort Worth and Houston metro expansion outpaces national construction averages, creating contractor capacity shortages for wind-rated asphalt and entry-level metal systems.
Canada
Ontario and Quebec manufacturing bases are expanding engineered polymer and modified bitumen capacity to serve US commercial membrane demand through integrated cross-border supply chains. Health Canada and PMRA regulate construction material emissions and chemical safety standards that align with US EPA frameworks, facilitating seamless product registration. Toronto and Montreal industrial clusters anchor membrane formulation and accessory production for North American distribution.
Mexico
Northern border states and Mexico City Metro absorb residential construction demand as manufacturing relocation and nearshoring accelerate housing development in industrial corridors. The national building code regulator CONAVI enforces seismic and thermal performance standards that redirect specifications toward reinforced concrete tile and insulated metal panel systems. Monterrey and Tijuana construction markets concentrate contractor specialization in rapid-turnover residential envelopes serving export-oriented manufacturing campuses.
North America Roofing Market Competitive Landscape
Capability concentration sits with integrated manufacturers commanding raw material supply chains; scale advantage sits with distributors and installers managing regional contractor networks. The market structures around three tiers: fiberglass mat and asphalt compounders, membrane formulators, and installation-specialized service providers. Strategic moves cluster on backward integration into mineral granule and polymer feedstock production, alongside geographic densification in Sun Belt metro corridors.
Among US-based integrated manufacturers, Owens Corning and GAF Materials LLC exemplify the raw-material-captive archetype, while Carlisle Companies Incorporated occupies a position within the commercial membrane specialization tier. These entities represent distinct competitive vectors: fiberglass supply chain control versus TPO and EPDM formulation expertise for extended-lifecycle commercial applications.
| Leading Market Players |
|---|
| GAF Materials LLC |
| Owens Corning |
| CertainTeed LLC |
| Carlisle Companies Incorporated |
| TAMKO Building Products LLC |
| IKO Industries Ltd. |
| Johns Manville Corp. |
| Tecta America |
| CentiMark Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Canadian engineered polymer manufacturing is tightening supplier leverage across the commercial membrane segment, compressing bid windows for US contractors while elevating price floors for TPO and EPDM specifications. This utilization squeeze propagates through cross-border procurement pipelines, forcing distributors to accept shorter payment terms and accelerating spot-market volatility for modified bitumen inputs.
Pricing Analysis
Long-term offtake contracts dominate commercial membrane procurement, with Carlisle Companies and Johns Manville anchoring volume through multi-year supply agreements that lock in base resin pricing. Price differentiation separates premium TPO formulations with enhanced UV stabilization from standard-grade products, while economy-tier asphalt shingles compete on raw material efficiency. Cost compression in the residential retrofit segment is intensifying because Owens Corning and GAF Materials LLC are expanding fiberglass mat capacity, eroding regional price premiums. Commercial facilities managers exhibit the lowest price sensitivity, prioritizing warranty documentation and thermal emittance certification over unit cost.
Supply Chain Analysis
Contract manufacturing for metal roofing coil concentrates in domestic steel mills and aluminum smelters clustered around the Great Lakes and Gulf Coast, with Nucor and Alcoa holding captive capacity for standing-seam profiles. Raw material sourcing draws from petroleum bitumen refineries in Texas and Louisiana, fiberglass mat production in Ohio and South Carolina, and polymer resin formulation in Ontario and Quebec. Tariff exposure on Canadian aluminum imports creates pricing volatility for metal roofing contractors serving Florida wind-load markets. Distribution runs through two-step wholesale networks for asphalt shingles and direct manufacturer-to-contractor channels for commercial membranes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America roofing market sustains defensive moats through regulatory entrenchment: NRCA certification requirements and manufacturer warranty eligibility create switching costs that lock contractors into established supply relationships. This structural barrier protects incumbent volume while constraining new entrant access to storm-damage replacement pipelines.
For Market Incumbents: Harden certification control by expanding NRCA training program capacity in Florida and California markets, constraining contractor bidding access for emerging competitors. Deepen backward integration into mineral granule production to offset asphalt binder volatility, securing cost advantages against regional asphalt shingle competitors. Prioritize direct-to-contractor digital platform investments to disintermediate wholesale distribution in the residential repair segment. For New Entrants and Emerging Players: Build out specialty metal roofing fabrication capacity targeting Texas metro expansion corridors, where wind-rated system demand outpaces established contractor coverage. Target the photovoltaic-integrated roof tile segment in California, where Title 24 compliance requirements and net-metering incentives create specification white space. Pursue installed-sales partnerships with big-box retailers to access suburban replacement pipelines without building independent contractor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across engineered polymer membrane manufacturing, as EPA VOC regulations force water-based adhesive reformulation investments and light-stable pigment capacity expansion. Acquisition candidates with captive fiberglass mat supply or established NRCA-certified installer networks offer the strongest five-to-ten-year viability profiles. Monitor EPA enforcement patterns on volatile organic compound regulations as the primary inflection signal for membrane manufacturer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Granule Supply | Owens Corning's captive granule production insulates asphalt shingle margins against raw material volatility. |
| NRCA Certification Program Expansion | Manufacturer warranty eligibility constraints lock contractor access, protecting incumbent market share in storm-exposed states. |
| Photovoltaic-Ready Membrane Development | Building-integrated solar compatibility aligns with California Title 24 and Texas net-metering incentive expansion. |
| Direct-to-Contractor Digital Platform Launch | Disintermediation of wholesale distribution captures margin in residential repair and ventilation accessory categories. |
| Cross-Border Engineered Polymer Capacity Addition | Ontario and Quebec manufacturing bases serve US commercial demand through integrated North American supply chains. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with roofing contractors, commercial facilities managers, and distribution channel partners, alongside secondary validation through NRCA certification databases, EPA regulatory filings, and building permit issuance records. Primary fieldwork captured contractor capacity constraints, warranty eligibility requirements, and specification shift patterns across Sun Belt markets. Secondary sources included ICC code adoption tracking, state-level energy code amendments, and manufacturer technical documentation. Bottom-up triangulation across project pipelines and top-down validation against regional construction expenditure estimates anchored volume and value outputs.
Forecast inputs considered material substitution elasticity, migration-driven housing demand, and regulatory compliance cost pass-through across the projection horizon. Segmentation dimensions modeled include product type, end-user category, installation timing, and distribution channel, with additional disaggregation by state-level energy code stringency and wind-load requirement tiers. CAGRs were derived through regression analysis of historical replacement cycles and forward projection of permit issuance trends. Industry-specific inputs incorporated insurer coverage eligibility shifts for asphalt shingles in hurricane corridors and Title 24 adoption trajectories in western states.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Canadian engineered polymer manufacturers or accelerated metal roofing adoption driven by insurer mandate tightening would shift outcomes beyond modeled ranges. Quarterly review of NRCA certification program waitlists, EPA VOC regulation enforcement actions, and Texas-Florida building permit issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
North Africa Cement Market