
 China UPVC Doors and Windows Market | 2026-2036
China UPVC Doors and Windows Market Size, Share, and Industry Trends Forecast 2026-2036
China UPVC Doors and Windows Market Outlook
Premium thermal-break UPVC systems is decoupling from commodity-grade white profiles in China's construction supply chain. Yingde Conch Profiles Co., Ltd. anchors the mid-market through captive extrusion capacity across five provincial hubs. Lesso leverages backward integration into PVC resin compounding to control input costs for standard-grade window lines. VEKA Plastics (Shanghai) Co., Ltd. differentiates via European-origin formulation licensing targeted at high-rise commercial specifications.
Unplasticized polyvinyl chloride doors and windows are rigid thermoplastic building envelope components extruded from PVC-U compound with titanium dioxide stabilization, calcium carbonate filler loading, and multi-chamber hollow profiles designed to achieve thermal transmittance coefficients below 2.0 W/m²K for compliance with northern climate zone requirements. Casement windows and sliding doors occupy the volume core of residential new construction, while retrofit installation demand accelerates fastest as aging aluminum-frame stock reaches replacement cycles in Shanghai and Beijing housing estates. Custom build applications for hospitality projects command margin pools that standard installation contracts cannot replicate.
China's GB/T 8814 profile standards, administered by SAMR, set dimensional tolerance and impact resistance minimums that filter small extruders from municipal tender participation. MIIT's dual carbon goals pressure manufacturers toward lead-free stabilizer formulations and recycled content verification. MEE enforcement of VOC emission limits at extrusion plants raises compliance capital requirements. Stakeholders must monitor whether provincial green building rating systems will mandate passive-house-grade UPVC performance tiers ahead of national code revisions.
Market Dynamics
MIIT's dual carbon targets are compressing lead-based stabilizer formulations while forcing extruders toward recycled PVC verification systems, fundamentally restructuring compounding economics across northern climate zone supply chains.
Growth Catalysts
- GB/T 8814 profile standard upgrades:SAMR-administered dimensional tolerance and impact resistance minimums are filtering sub-scale extruders from municipal tender pools, concentrating volume among certified fabricators.
- Thermal transmittance compliance pressure:Updated GB standards for building energy efficiency are mandating sub-2.0 W/m²K coefficients for exterior envelope components in cold climate zones.
- Jiangsu-Zhejiang manufacturing cluster density:Proximity to PVC resin supply and coastal export infrastructure is capturing both domestic replacement cycles and Southeast Asian project demand.
Market Restraints
- Calcium-zinc stabilizer cost premium:Lead-free formulation migration under MEE enforcement is adding 8-12% to compound input costs versus legacy stabilizer systems.
- MEE VOC emission compliance capital intensity:Extrusion plant air treatment upgrades are raising minimum viable scale thresholds for provincial operating licenses.
- Aluminum-frame substitution in high-rise commercial:Structural load-bearing specifications above 30 stories continue specifying thermally broken aluminum despite UPVC thermal superiority.
Strategic Opportunities
- Tier-two city retrofit acceleration:Aging aluminum-frame housing estates in Chengdu and Xi'an are entering replacement cycles with thermal efficiency upgrade mandates.
- Passive house performance tier pre-emption:Provincial green building rating systems in Jiangsu and Zhejiang may mandate PHI-certified UPVC specifications ahead of national code revisions.
- Hospitality custom build margin pools:Boutique hotel and serviced apartment projects are specifying acoustic-rated, color-customized systems unavailable through standard installation channels.
Industry Challenges
- Recycled content verification protocol gaps:MIIT circular economy targets lack standardized testing methodologies for post-consumer PVC feedstock qualification.
- Fabricator-installer coordination fragmentation:Project delays from site measurement errors and thermal-break assembly sequencing are compressing contract profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China UPVC Doors and Windows Market |
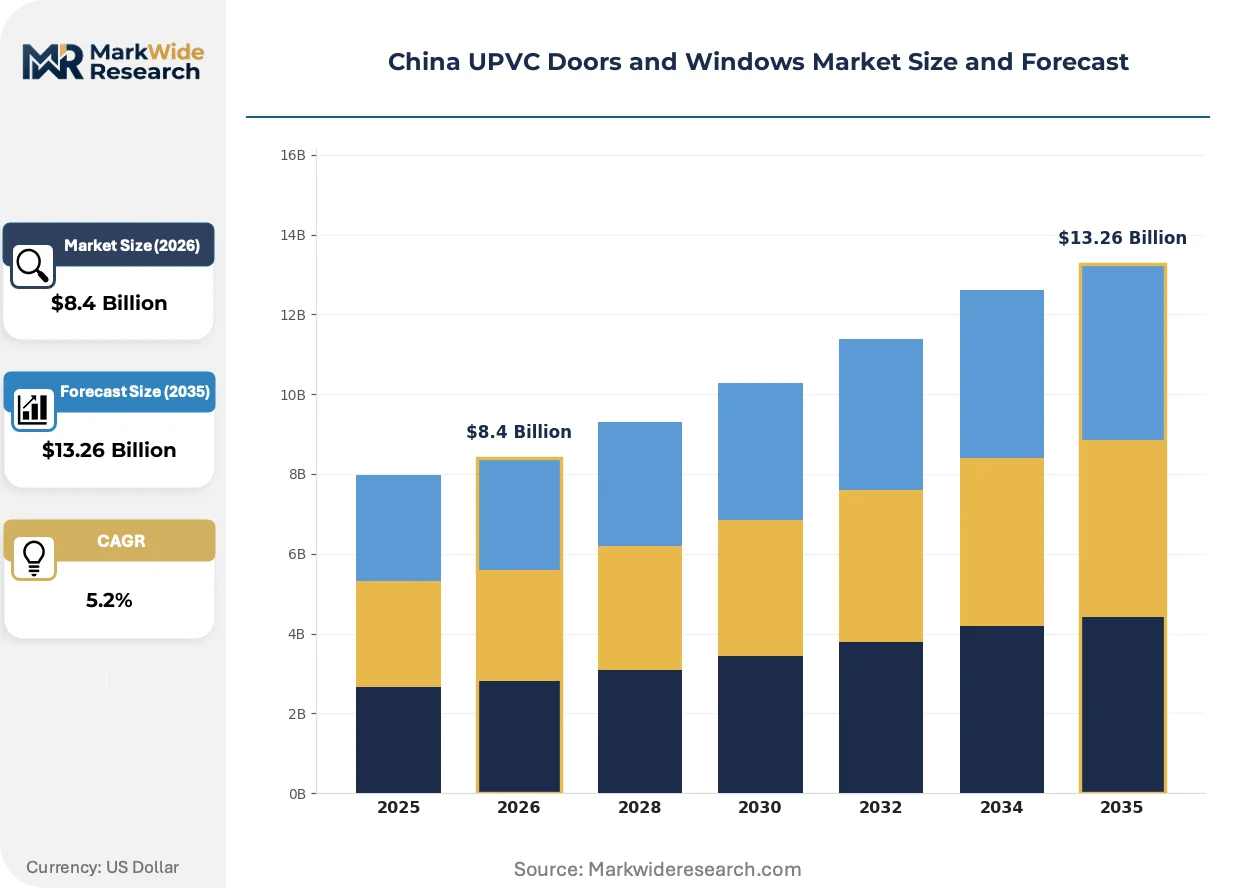
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Casement Windows, Awning Windows, French Doors End User: Residential Sector, Commercial Buildings, Industrial Facilities, Hospitality Application: New Construction, Renovation, Replacement, Custom Build Installation Type: Standard Installation, Custom Installation, Retrofit Installation, DIY Kits |
| Companies Covered | Ropo, Oridow, Fonirte, Weifang Beidi Plastic Industry Co., Ltd., Yingde Conch Profiles Co., Ltd., Lesso, VEKA Plastics (Shanghai) Co., Ltd., Reaching Build, Zhejiang Yuanwang Windows and Doors Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China UPVC Doors and Windows Market Strategic Shifts
Formulation chemistry and digital fabrication methods are converging to compress lead times for customized thermal-break configurations while regulatory pressure accelerates material circularity investments.
Multi-chamber hollow profile extrusion with optimized air cavity geometry is expanding into high-rise residential specifications previously reserved for aluminum systems. Tier-one developers in Shanghai and Beijing are specifying six-chamber designs for curtain wall integration. This expansion is compressing the traditional material-grade hierarchy between premium aluminum and standard UPVC in commercial bids.
MIIT's mandatory recycled content disclosure requirements for construction materials are forcing compounders to establish post-industrial PVC collection partnerships. Verification protocols under SAMR supervision are creating first-mover advantages for extruders with captive recycling infrastructure. Northern climate zone projects are prioritizing suppliers with certified circular content ahead of tender deadlines.
Direct-to-developer specification relationships are displacing traditional distributor-mediated procurement in tier-one city projects. Large residential developers are unbundling frame supply from installation contracts to capture margin through captive fabrication partnerships. This channel compression is most visible in Beijing and Shenzhen where consolidated developer portfolios enable volume-based master agreements.
China UPVC Doors and Windows Market Segmentation
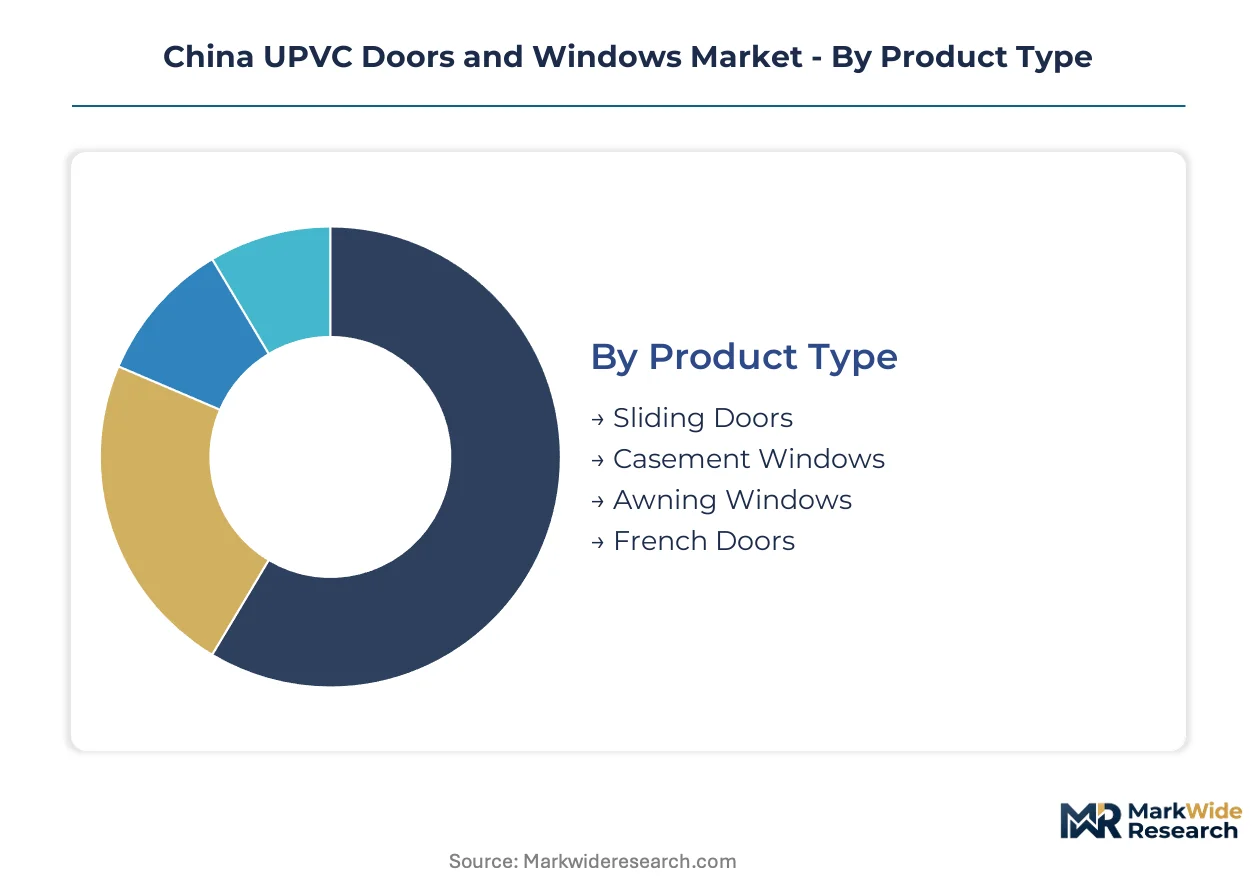
UPVC frame procurement in China fragments across four distinct category systems. Each dimension reveals divergent margin structures, certification requirements, and channel access patterns that shape competitive positioning.
Product Type:
Buyer differentiation in this category hinges on thermal performance specifications and structural load requirements rather than aesthetic preference alone.
- Sliding Doors:Multi-track roller systems with reinforced steel inserts accommodate larger glass panels for balcony enclosures. Demand concentrates in Jiangsu province high-rise residential towers where space-efficient opening mechanisms maximize floor area utilization.
- Casement Windows:Side-hinged sash designs with multi-point locking hardware achieve superior air tightness ratings. Beijing and Shanghai retrofit projects specify these for aging aluminum-frame replacement cycles driven by GB energy efficiency compliance deadlines.
- Awning Windows:Top-hinged configurations with rain-shedding geometry suit humid coastal climates.
- French Doors:Double-leaf swing systems with low-threshold profiles target premium villa segments.
Casement windows lead volumes today; sliding doors are gaining share fastest.
End User:
Project scale and specification authority separate buyers across this dimension, from consolidated developer portfolios to fragmented owner-operator decisions.
- Residential Sector:Tier-one city developers specify six-chamber thermal-break profiles for new construction, while tier-two retrofit demand accelerates in Chengdu and Xi'an housing estates. SAMR certification requirements filter sub-scale fabricators from municipal tender participation.
- Commercial Buildings:Curtain wall integration specifications above 15 stories demand reinforced mullion profiles with structural silicone compatibility. Shanghai Lujiazui and Shenzhen Qianhai projects drive specification migration toward European-origin formulation licensing.
- Industrial Facilities:Dust-sealed configurations with positive-pressure compatibility serve cleanroom envelope requirements.
- Hospitality:Acoustic-rated and color-customized systems command margin pools unavailable through standard channels.
Residential sector leads volumes today; hospitality is expanding most quickly.
Application:
Timing relative to construction phase determines procurement channel and margin capture potential for fabricators.
- New Construction:Developer-direct master agreements with captive fabrication partnerships displace traditional distributor channels. Volume concentration in Beijing and Shenzhen enables specification lock-in before ground-breaking.
- Renovation:Aging stock replacement in 1990s-era housing estates drives demand for dimensionally compatible retrofit profiles. Measurement accuracy requirements compress profitability for installer-fabricator coordination.
- Replacement:Thermal efficiency upgrade mandates accelerate aluminum-to-UPVC conversion in northern climate zones.
- Custom Build:Boutique project specifications with non-standard color and hardware configurations.
New construction leads volumes today; renovation is climbing the fastest.
Installation Type:
Skill intensity and site coordination requirements create tiered service margin structures across procurement modes.
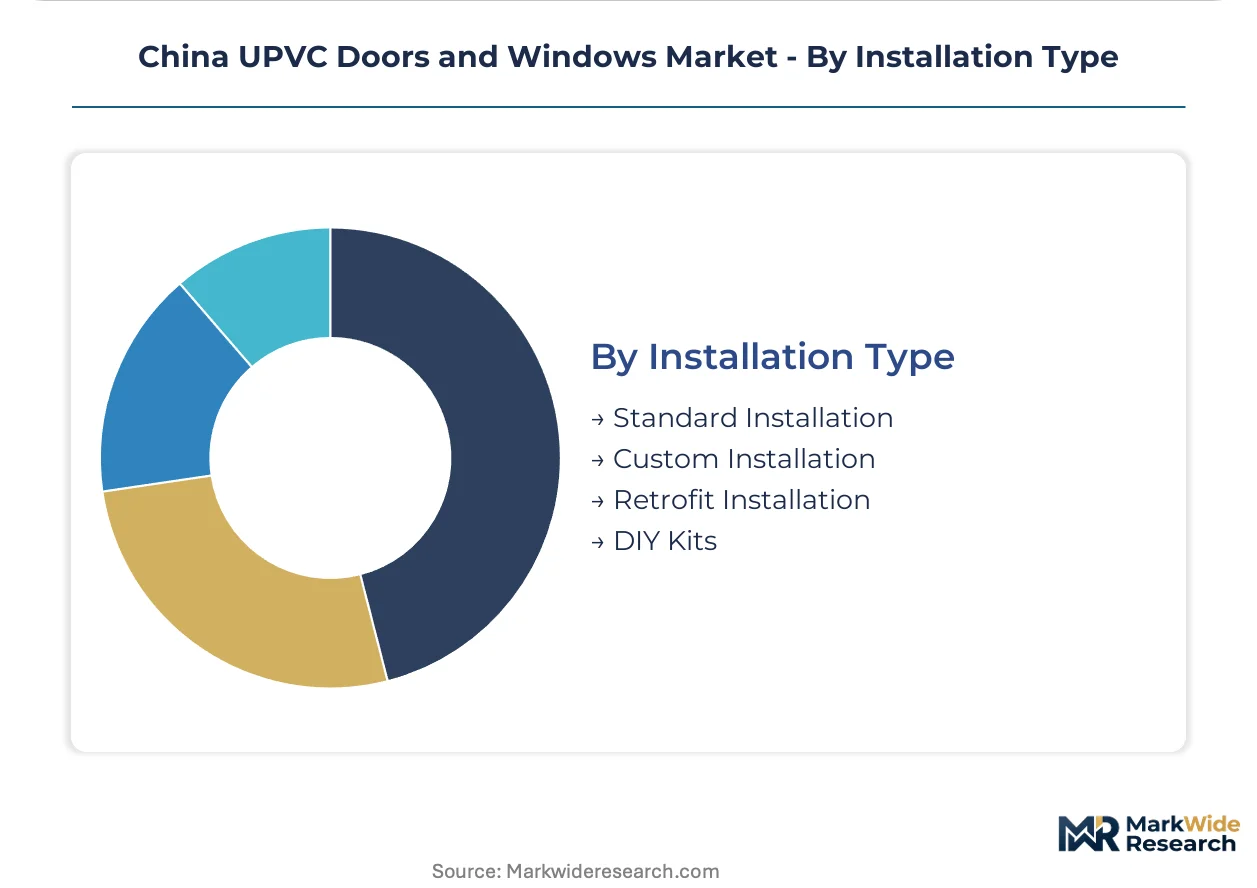
- Standard Installation:Pre-sized frame units with fixed hardware packages serve volume residential projects. Fabricator efficiency depends on dimensional accuracy from developer-provided architectural drawings.
- Custom Installation:Site-measured fabrication with thermal-break assembly sequencing requires skilled technician deployment. Project delays from measurement errors compress contract profitability.
- Retrofit Installation:Demolition-compatible removal systems with minimal structural disturbance.
- DIY Kits:Pre-cut profile sections with snap-together corner joints for informal housing segments.
Standard installation leads volumes today; custom installation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's UPVC door and window demand concentrates in coastal manufacturing belts, whereas interior provinces accelerate retrofit cycles under thermal efficiency mandates. Provincial GB standard enforcement varies across climate zones, creating divergent specification requirements. Sub-regional clusters in Jiangsu and Zhejiang dominate export-oriented production capacity.
Jiangsu Province
Nanjing and Suzhou developers specify six-chamber thermal-break profiles for high-rise residential towers under local green building rating systems. SAMR-administered GB/T 8814 certification filters sub-scale fabricators from municipal tender pools. The Yangtze River Delta manufacturing corridor captures both domestic replacement demand and Southeast Asian project exports through Ningbo-Zhoushan port infrastructure.
Zhejiang Province
Hangzhou and Ningbo fabricators supply casement window systems for Shanghai retrofit projects driven by aluminum-frame replacement cycles. Provincial energy efficiency codes mandate sub-2.0 W/m²K thermal transmittance coefficients ahead of national schedule. The Shaoxing extrusion cluster specializes in color-customized hospitality specifications for boutique hotel developers.
Beijing-Tianjin-Hebei
Beijing housing estates from the 1990s are entering aluminum-to-UPVC conversion cycles under northern climate zone compliance deadlines. MEE enforcement of VOC emission limits at extrusion plants raises capital barriers for new market entrants. Tianjin's port-linked industrial zones serve as distribution nodes for northeastern provincial projects.
Sichuan-Chongqing
Chengdu tier-two developers accelerate thermal efficiency upgrades in aging residential compounds under western region urban renewal programs. MIIT dual carbon targets pressure local fabricators toward lead-free stabilizer formulations. The Chongqing manufacturing base supplies interior provinces with cost-optimized sliding door systems for high-density residential towers.
Shandong Peninsula
Qingdao and Yantai fabricators target Korean and Japanese export markets with European-origin formulation licensing for commercial specifications. Local GB standard implementation focuses on impact resistance minimums for coastal wind load conditions. The Weihai processing cluster specializes in reinforced steel insert profiles for large-format glass installations.
China UPVC Doors and Windows Market Competitive Environment
Top-tier vendors anchor premium specification tiers, while mid-market fabricators compete on extrusion scale and provincial distribution density. The vendor base stratifies across three performance tiers: European-licensed formulation specialists, captive-resin compounders with backward integration, and regional extruders serving municipal tender pools. Strategic differentiation concentrates on thermal-break assembly capability, recycled content verification systems, and direct-to-developer procurement relationships. Competitive moves center on capacity consolidation in Jiangsu-Zhejiang corridors and specification partnerships with tier-one residential developers.
Within the European-licensed tier, VEKA Plastics (Shanghai) Co., Ltd. represents formulation technology transfer from German parent operations. Yingde Conch Profiles Co., Ltd. and Lesso exemplify scale-driven compounders with captive resin operations and five-province hub networks. These three entities occupy distinct positioning vectors: technology licensing, vertical manufacturing control, and distribution density respectively.
| Leading Market Players |
|---|
| Ropo |
| Oridow |
| Fonirte |
| Weifang Beidi Plastic Industry Co., Ltd. |
| Yingde Conch Profiles Co., Ltd. |
| Lesso |
| VEKA Plastics (Shanghai) Co., Ltd. |
| Reaching Build |
| Zhejiang Yuanwang Windows and Doors Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap extruders across Jiangsu and Zhejiang provinces anchor supply concentration while enforcing pricing discipline through captive resin compounding and direct-to-developer contracting. Their refusal to absorb calcium-zinc stabilizer cost premiums is compressing margins for distributor-dependent fabricators in northern climate zones.
Pricing Analysis
Frame supply unbundled from installation contracts now dominates tier-one city procurement, with developer-direct master agreements capturing margin through captive fabrication partnerships. Three-tier pricing structure across PHI-certified, SAMR-compliant, and municipal-tender grades separates premium thermal-break systems from commodity white profiles. Pricing pressure stems from MEE-mandated VOC abatement capital requirements that smaller extruders cannot amortize. Tier-two retrofit installers exhibit highest price sensitivity, while hospitality developers prioritize acoustic performance over unit cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from Beijing and Shanghai developers are fragmenting procurement across Jiangsu, Zhejiang, and Shandong extrusion bases. PVC resin supply draws from Sinopec and CNPC petrochemical corridors, titanium dioxide stabilizers feed from domestic chloride-process plants, and calcium-zinc additive packages source from specialty chemical importers. Single-source vulnerability concentrates in European-origin formulation licensing held by VEKA Plastics Shanghai. Distribution runs through provincial fabricator networks with municipal tender access rather than national wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Jiangsu-Zhejiang manufacturing clusters with coastal export infrastructure and interior provinces facing MEE compliance capital barriers. The cost differential in lead-free stabilizer formulation compliance separates viable scale operators from filtered sub-scale competitors.
For Market Incumbents: Cement specification lock-in through early-stage developer engagement before ground-breaking in tier-one residential towers. Deepen backward integration into post-industrial PVC collection infrastructure ahead of MIIT mandatory recycled content disclosure. Aluminum-frame substitution in high-rise commercial remains the persistent threat; counter with six-chamber curtain wall integration pilots in Shanghai Lujiazui projects.
For New Entrants and Emerging Players: Launch via hospitality custom-build channels in Shaoxing and Hangzhou where color-customized acoustic systems command premium positioning unavailable through standard installation networks. Target Chengdu and Xi'an tier-two retrofit acceleration where aging aluminum-frame estates enter replacement cycles with limited incumbent specification relationships. Pursue provincial green building rating system pre-emption ahead of national GB code revisions.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional extruders with municipal tender access but lacking direct-to-developer relationships. Long-term viability hinges on circular economy infrastructure positioning through the next building stock replacement cycle. Monitor SAMR recycled content verification protocol finalization as inflection indicator for first-mover compounders with captive recycling partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin Compounding | Lesso and Conch anchor input cost control across five-province hub networks. |
| Recycled Content Verification Infrastructure | MIIT circular economy targets reward extruders with post-industrial collection partnerships. |
| Direct-to-Developer Specification Relationships | Beijing and Shenzhen consolidated portfolios enable volume-based master agreement capture. |
| Passive House Performance Tier Pre-emption | Jiangsu and Zhejiang provincial rating systems may mandate PHI-certified specifications early. |
| Hospitality Custom-Build Channel Development | Shaoxing cluster specializes in acoustic-rated color-customized systems for boutique hotel developers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion plant managers, municipal procurement officers at Beijing and Shanghai housing authorities, developer specification leads, and hospitality project architects with secondary validation. Customs data on PVC resin and titanium dioxide imports, MIIT circular economy policy filings, SAMR GB/T 8814 certification registries, and provincial green building rating system documentation anchored supply-side triangulation. Bottom-up fabricator capacity surveys and top-down construction completion data cross-validated volume estimates.
Segment-weighting approaches distributed value across product type, end user, application timing, and installation complexity dimensions throughout the forecast period. CAGRs derived from housing stock age profiles, climate zone energy efficiency mandate schedules, and export channel penetration assumptions. Thermal transmittance compliance deadlines and recycled content verification protocol implementation timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential aluminum-frame technological advances in high-rise structural specifications, abrupt MEE enforcement intensity variations, and trade policy disruptions affecting Southeast Asian export channels. Forecasts reflect documented assumptions regarding GB standard revision pacing and provincial green building rating system adoption. Deviation in MIIT dual carbon target acceleration or SAMR recycled content testing methodology finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
GCC Ceramic Tiles Market