
 Wind Turbine Foundation Market | 2026-2036
Wind Turbine Foundation Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Foundation Market Analysis
Modularization of jacket and tripod foundation components is expanding buyer choice by enabling staged offshore assembly and reducing heavy-lift vessel dependency. Peikko Group leverages its bolted connection technology to reduce welding hours at marshalling ports. Siemens Gamesa Renewable Energy anchors its foundation strategy through integrated turbine-tower-foundation design packages. Bladt Industries A/S specializes in serial production of transition pieces, competing on fabrication throughput rather than custom engineering.
A wind turbine foundation is the structural substructure that transfers rotor, nacelle, and tower loads into seabed or soil strata, typically fabricated from high-yield steel tubulars or pre-stressed concrete with cathodic protection systems rated for 25-year design lives. Its primary commercial purpose is to maintain turbine operational alignment within millimetric tolerances under cyclic wave, wind, and seismic loading across variable geotechnical conditions. Monopile foundations dominate shallow-water installations but face margin compression as diameters exceed ten meters, while jacket structures capture premium pricing in water depths beyond fifty meters where fabrication complexity rises. Gravity-based concrete systems retain share in markets with strong local cement supply chains and restricted pile-driving windows due to marine mammal regulations.
DNV-ST-0126 and IEC 61400-3-1 set structural design and load-case requirements for offshore foundations, with national regulators such as Germany's BSH and the Netherlands' Rijkswaterstaat layering environmental impact and seabed-interaction conditions on project approvals. The EU Green Deal's embodied-carbon tracking requirements and the CSRD's scope-3 disclosure rules are forcing foundation fabricators to document steel sourcing and recycling content across supply tiers. Stakeholders must monitor floating foundation pilot-to-commercial transitions, as semi-submersible and tension-leg platform designs could displace fixed-bottom demand in transitional water depths where installation economics remain unsettled.
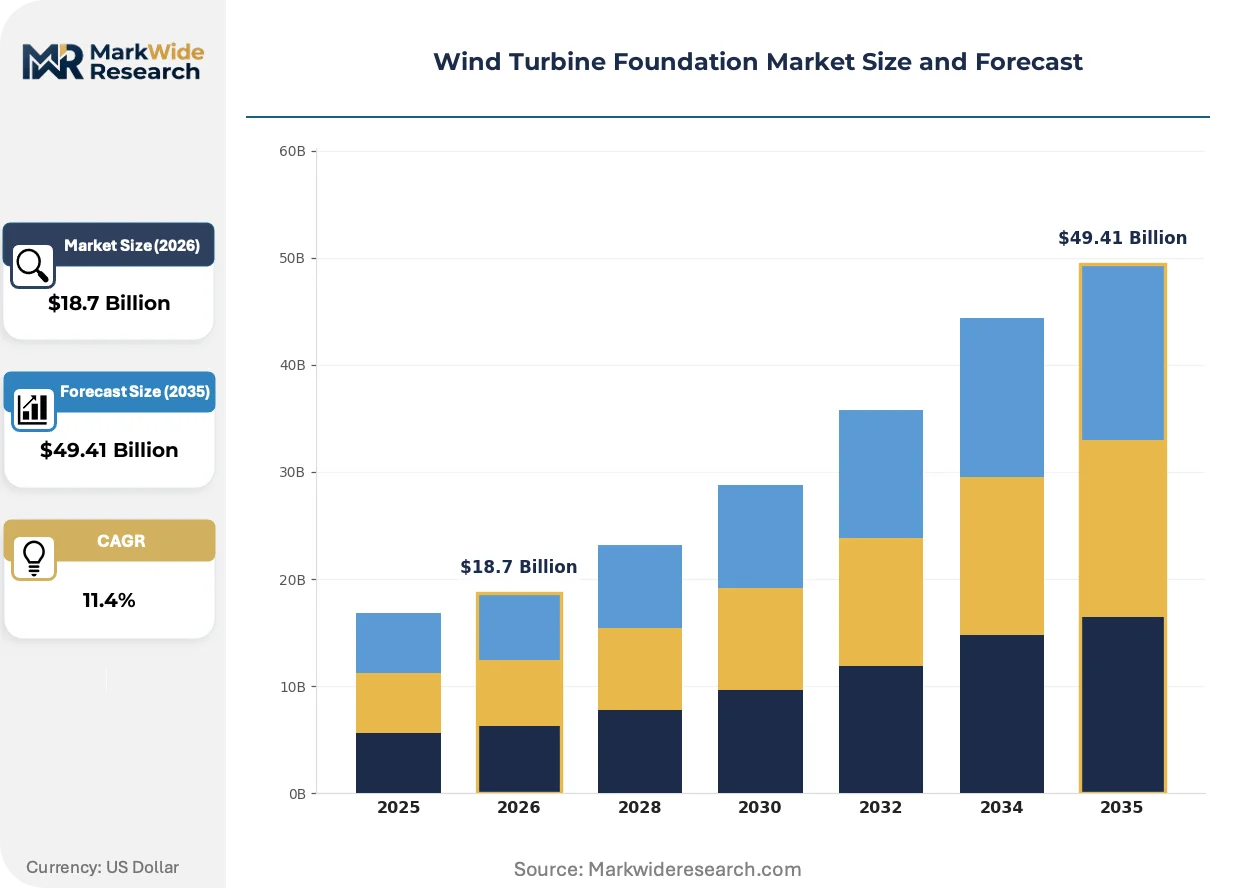
Market Dynamics
Offshore wind developers are accelerating procurement of deeper-water foundation systems as monopile economics deteriorate in waters exceeding 40 meters, forcing fabricators to retool for jacket and floating platform production while EU carbon-tracking mandates compress supplier margins.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Steel-recycling thresholds and scope-3 disclosure rules under CSRD are redirecting procurement toward low-carbon fabrication, creating first-mover advantage for suppliers with verified circular supply chains.
- North Sea auction mechanisms:Germany's BSH and the Netherlands' Rijkswaterstaat are bundling foundation-ready site conditions into lease awards, reducing geotechnical risk premiums for developers.
- Jacket modularization:Staged offshore assembly of tubular components is reducing heavy-lift vessel dependency and compressing installation windows in the Danish and UK sectors.
Market Restraints
- Specialized installation vessel scarcity:The global fleet of jack-up vessels capable of handling 10-meter+ monopiles remains concentrated among three European contractors, creating queue bottlenecks at North Sea marshalling ports.
- High-yield steel price volatility:S355ML and S420ML plate costs fluctuate with energy-intensive European mill output, squeezing fabrication margins on fixed-price EPC contracts.
- Marine mammal regulatory windows:Germany's BSH and seasonal piling restrictions in the Dutch Borssele zone compress foundation installation into 6-8 month annual windows, extending project timelines.
Strategic Opportunities
- Floating foundation commercialization:Semi-submersible and tension-leg platform designs targeting 60-80 meter water depths in the Scottish and Norwegian sectors could unlock sites previously uneconomic for fixed-bottom structures.
- Integrated turbine-tower-foundation packages:OEMs are bundling structural design liability, creating openings for fabricators willing to assume performance risk across the full load path.
- Baltic Sea expansion:Poland and Lithuania are issuing maiden offshore leases with shallower seabed profiles favoring gravity-based concrete systems where local cement supply chains exist.
Industry Challenges
- Welding inspector certification backlog:DNV-ST-0126 and IEC 61400-3-1 compliance requires specialized offshore structural welders, with training pipeline lagging fabrication capacity expansion in Germany and Denmark.
- Geotechnical survey coordination:Foundation design fixation depends on high-resolution seabed data, but survey vessel availability conflicts with fishing and oil-and-gas activity in crowded North Sea corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Foundation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Foundation Type: Monopile, Gravity-Based, Jacket, Tripod Installation Method: Floating, Fixed-Bottom, Offshore, Onshore Material: Concrete, Steel, Composite, Reinforced End User: Utility Companies, Independent Power Producers, Government, Developers |
| Companies Covered | Peikko Group, Principal Power Inc., Siemens Gamesa Renewable Energy, Suzlon Group, Vestas Wind Systems A/S, Aker Solutions, Ramboll Group, Goldwind, Bladt Industries A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Foundation Market Emerging Trajectories
Fabrication technology and regulatory disclosure requirements are converging to reshape competitive positioning in offshore foundation supply, with modular construction methods and carbon-accounting systems emerging as primary differentiators.
High-strength concrete gravity-base systems is overtaking steel monopiles in markets with restricted piling windows and strong local cement industries. Polish and Lithuanian developers are specifying pre-stressed concrete caissons for Baltic installations to avoid seasonal marine mammal restrictions. This technology is overtaking conventional steel procurement in the eastern North Sea basin where geotechnical conditions permit and supply chain localization is prioritized.
CSRD scope-3 disclosure rules and EU Green Deal embodied-carbon tracking are forcing foundation fabricators to document steel sourcing across tier-2 and tier-3 suppliers. German and Dutch regulators are layering verification requirements onto project approvals, with BSH now requiring Environmental Product Declarations for transition pieces. Jacket and monopile suppliers with integrated scrap-to-billet traceability are capturing preferential qualification status in North Sea auction rounds.
Buyers are consolidating procurement authority into integrated EPC packages that bundle foundation, tower, and turbine installation risk. Ørsted and RWE are awarding single-contractor responsibility for complete offshore structural delivery, displacing fragmented component sourcing. This concentration is most visible in German and Dutch auction rounds where balance-of-plant cost certainty outweighs unit-price optimization in developer scoring criteria.
Wind Turbine Foundation Market Segmentation
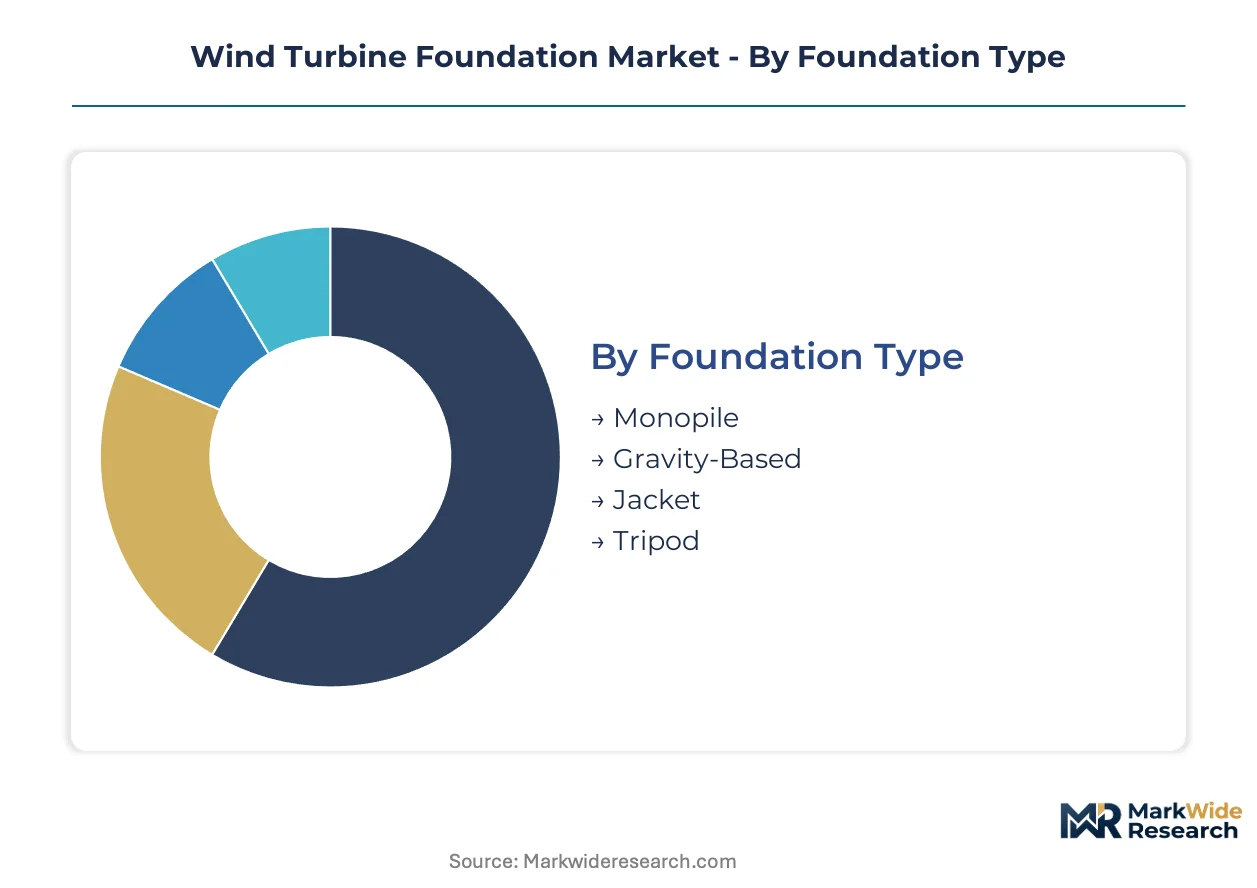
Foundation selection determines installation vessel requirements, fabrication lead times, and carbon-accounting complexity across offshore wind portfolios. Procurement officers balance geotechnical constraints against supply chain localization mandates when segmenting supplier contracts.
Foundation Type:
Standardization dominates shallow-water procurement while deeper sites force custom engineering with extended design cycles.
- Monopile:Single large-diameter steel tubulars driven or drilled into seabed strata. Demand concentrates in German and Dutch auction rounds where water depths stay below 40 meters and pile-driving equipment is readily available.
- Jacket:Lattice frameworks of welded tubulars transferring loads through multiple pile points. Expansion is steepest in Scottish and Norwegian sectors where water depths exceed 50 meters and geotechnical conditions favor multi-point anchoring.
- Gravity-Based:Massive pre-stressed concrete caissons relying on dead weight for stability. Polish and Lithuanian developers specify these for Baltic installations with restricted seasonal piling windows.
- Tripod:Three-legged steel structures bridging monopile simplicity with jacket load distribution. Limited deployment in transitional depths where seabed preparation costs remain manageable.
Most installed capacity flows through monopile foundations. Expansion is steepest in jacket structures.
Installation Method:
Water depth and port infrastructure availability segment contractor specialization across the North Sea basin.
- Fixed-Bottom:Piled or gravity-based structures permanently anchored to seabed. German BSH and Dutch Rijkswaterstaat approvals concentrate here for waters under 60 meters.
- Floating:Semi-submersible or tension-leg platforms moored with catenary or taut leg systems. Scottish developers pilot these for 60-80 meter depths where fixed-bottom economics deteriorate.
- Offshore:Assembly and commissioning at sea requiring heavy-lift vessels and specialized jack-ups. Queue bottlenecks persist at Esbjerg and Rotterdam marshalling ports.
- Onshore:Foundation preparation and partial assembly at coastal facilities before tow-out. Danish contractors favor this approach to compress offshore weather windows.
Fixed-bottom methods retain the dominant share. Floating platforms are gaining share fastest where water depths exclude conventional alternatives.
Material:
Carbon-intensity tracking under EU Green Deal and CSRD scope-3 rules segments procurement toward traceable supply chains.
- Steel:High-yield tubulars and plates in S355ML and S420ML grades with cathodic protection. Sourcing concentrates at European mills with verified scrap-to-billet recycling documentation.
- Concrete:Pre-stressed caissons and gravity bases using locally sourced cement. Polish and Baltic markets prioritize this for supply chain localization and marine mammal compliance.
- Reinforced:Steel-reinforced concrete combining tensile and compressive performance. Limited deployment in hybrid foundation concepts.
- Composite:Fiber-reinforced polymers for secondary structural elements and corrosion protection. Early-stage adoption for transition piece components.
Steel dominates procurement volumes. Concrete is expanding most quickly in markets with restricted piling seasons and strong local cement industries.
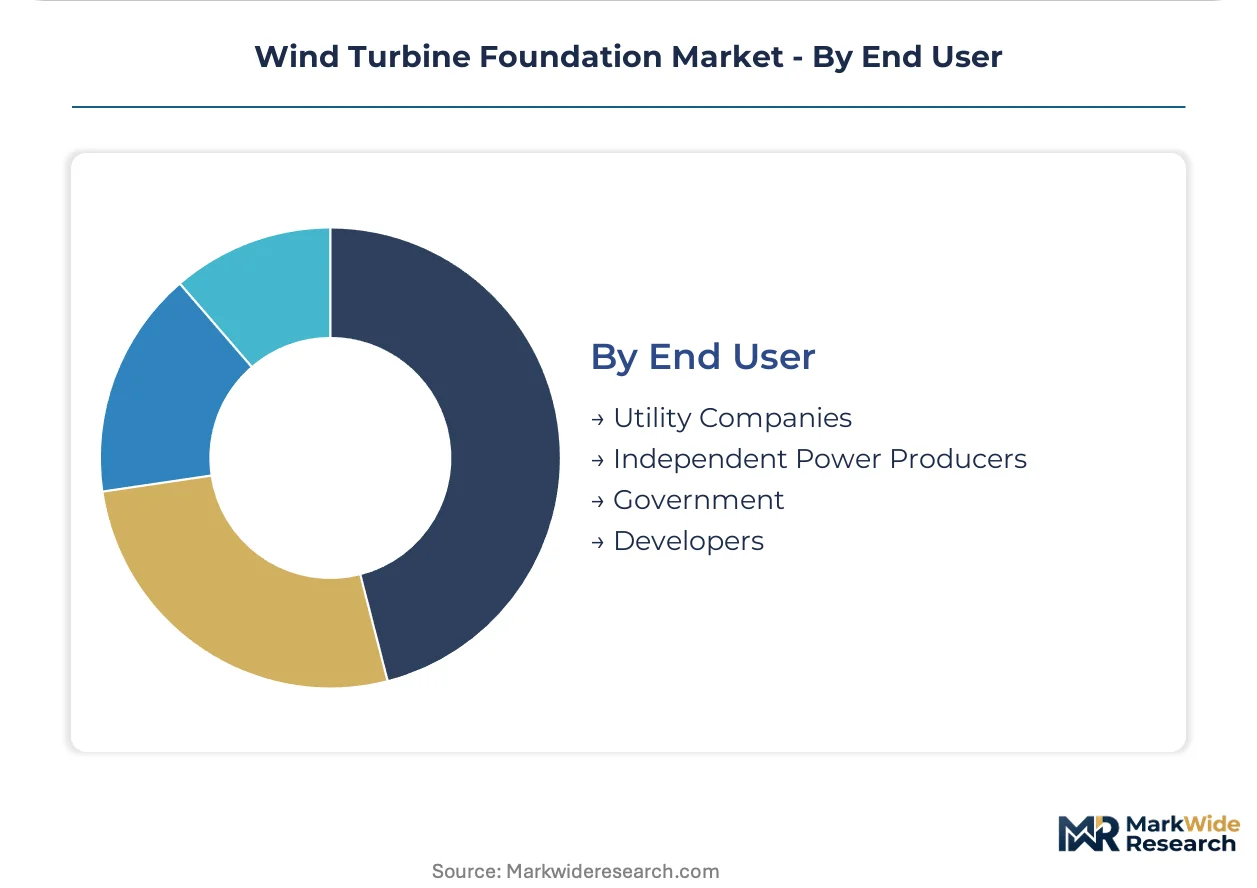
End User:
Balance-sheet capacity and risk tolerance segment contracting structures from component supply to full EPC wraps.
- Utility Companies:Vertically integrated developers with captive installation vessels and long-term steel offtake agreements. Ørsted and RWE consolidate procurement authority into single-contractor responsibility.
- Independent Power Producers:Project-specific vehicles financing through non-recourse debt. These buyers fragment component sourcing to optimize unit pricing.
- Developers:Early-stage site holders securing permits and grid connections before construction financing. Foundation selection remains flexible until final investment decision.
- Government:State-backed entities in Poland and Lithuania issuing maiden offshore leases with localized content requirements.
Utility companies command the largest foundation procurement volumes. Independent power producers are expanding most quickly as auction mechanisms attract new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind foundation engineering scaled commercially in the Danish and German North Sea sectors during the early 2000s, establishing fabrication protocols and installation vessel specifications that now propagate across emerging markets.
Germany
BSH approval requirements drive demand for certified low-carbon steel foundations in German auction rounds. The EU Green Deal's embodied-carbon tracking mandates now layer onto project permits, forcing fabricators to document scrap-to-billet supply chains. Port clusters at Cuxhaven and Rostock concentrate jacket and monopile marshalling activity for Baltic and North Sea developments.
United Kingdom
Scottish developers pilot floating semi-submersible platforms for 60-80 meter water depths where fixed-bottom economics falter. The Crown Estate leasing rounds bundle seabed survey data with site awards, compressing geotechnical risk premiums. Manufacturing gravity concentrates at Scottish ports including Nigg and Arnish, where jacket fabrication yards retool for deeper-water structures.
Netherlands
Rijkswaterstaat environmental windows restrict foundation piling to 6-8 month annual cycles in Dutch Borssele zones. CSRD scope-3 disclosure rules now require Environmental Product Declarations for transition pieces entering national waters. Rotterdam marshalling ports face queue bottlenecks as jack-up vessel availability fails to match auction pipeline velocity.
Poland
Maiden offshore lease awards in Polish Baltic waters favor gravity-based concrete systems to evade seasonal marine mammal restrictions. Local cement supply chains and pre-stressed caisson fabrication capabilities attract procurement localization mandates. Port infrastructure at Gdansk and Szczecin develops specialized heavy-lift quays for concrete foundation tow-out operations.
Norway
Equinor and Statkraft drive floating platform commercialization in Norwegian fjord zones with 200+ meter depths. National regulators emphasize tension-leg platform certification protocols adapted from offshore oil and gas structural standards. Fabrication yards at Verdal and Stord leverage subsea engineering heritage to capture emerging floating foundation contracts.
Wind Turbine Foundation Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fabrication complexity and carbon-accounting verification depth. The vendor base stratifies between integrated EPC contractors bundling turbine-tower-foundation liability and specialized component fabricators competing on throughput. Three archetypes dominate: steel monopile serial producers, jacket modularization specialists, and concrete gravity-base system engineers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with fabricators securing marshalling port access and installation vessel slot agreements.
Among Nordic fabricators, Bladt Industries A/S and Aker Solutions exemplify distinct positioning archetypes within the premium tier. Peikko Group occupies a position representing bolted-connection technology specialists reducing welding dependencies at coastal assembly sites. Siemens Gamesa Renewable Energy anchors the integrated-package vector, bundling structural design liability across turbine, tower, and foundation load paths. These three entities collectively illustrate how competitive positioning fragments between fabrication-scale efficiency and integrated performance-guarantee models.
| Leading Market Players |
|---|
| Peikko Group |
| Principal Power Inc. |
| Siemens Gamesa Renewable Energy |
| Suzlon Group |
| Vestas Wind Systems A/S |
| Aker Solutions |
| Ramboll Group |
| Goldwind |
| Bladt Industries A/S |
| Others |
Supply Flow & Price Mechanics
Jacket modularization and floating platform retooling are compressing fabrication margins while concentrating procurement power among EPC-integrated developers with captive vessel access.
Pricing Analysis
Project-based long-term offtake contracts dominate foundation procurement, with price differentiation driven by carbon-certification grade under EU Green Deal mandates and installation-vessel slot availability. Cost compression in monopile fabrication is intensifying because diameter scaling beyond ten meters erodes economies of scale. Utility companies with balance-sheet capacity show lowest price sensitivity, while independent power producers optimizing unit economics exhibit highest sensitivity to foundation unit costs.
Supply Chain Analysis
Welding inspector certification backlogs at German and Danish fabrication yards are extending lead times for DNV-ST-0126-compliant jacket structures. Supply concentrates in Germany, Denmark, and Poland, with high-yield S355ML and S420ML steel plate sourcing tethered to European mill output cycles. Single-source vulnerability persists for heavy-lift jack-up vessels capable of handling ten-meter-plus monopiles. Distribution runs through Rotterdam and Esbjerg marshalling ports with queue-managed slot allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wind turbine foundation market functions as a regulatory compounder where EU Green Deal embodied-carbon mandates and CSRD scope-3 disclosure rules are accelerating procurement consolidation around verified low-carbon supply chains.
For Market Incumbents: Extend certification depth into tier-2 and tier-3 steel sourcing to defend against emerging fabricators with integrated scrap-to-billet traceability. Secure marshalling port access and installation vessel slot agreements in Rotterdam and Esbjerg to lock out competitors facing queue bottlenecks. Vertical integration into transition piece fabrication preserves margin capture as EPC bundling displaces component sourcing. For New Entrants and Emerging Players: Begin with gravity-based concrete systems in Polish and Lithuanian Baltic markets where local cement supply chains and restricted piling windows favor new engineering entrants. Target government-backed maiden lease awards with localized content requirements as the most penetrable demand segment. Lead with Environmental Product Declaration capabilities to qualify for BSH and Rijkswaterstaat approval pathways. For Investors and Strategic Acquirers: Roll-up economics work for specialized jacket modularization fabricators because EPC consolidation is fragmenting component procurement into throughput-competitive tiers. Long-term viability hinges on floating platform commercialization readiness for Scottish and Norwegian 60-80 meter depth markets. Watch semi-submersible pilot-to-commercial transition rates as the inflection signal for fixed-bottom demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Recycling | Scrap-to-billet traceability secures preferential BSH qualification status under EU Green Deal mandates. |
| Marshalling Port Capacity Expansion | Specialized heavy-lift quays at Gdansk and Szczecin unlock Baltic gravity-base concrete foundation tow-out operations. |
| Floating Platform Certification Investment | Tension-leg platform protocols adapted from Equinor's offshore oil heritage accelerate Norwegian fjord zone commercialization. |
| Integrated EPC Package Capability | Single-contractor responsibility for turbine-tower-foundation bundles matches Ørsted and RWE procurement consolidation patterns. |
| Welding Inspector Training Pipeline | DNV-ST-0126 and IEC 61400-3-1 compliance capacity expansion addresses inspector certification backlogs in Germany and Denmark. |
Methodological Framework
Multiple input streams — foundation fabricator production data, offshore wind project development databases, and European steel mill output records — were reconciled through bottom-up and top-down triangulation. Primary interviews with EPC contractors, utility procurement officers, and marine warranty surveyors were validated against secondary sources including BSH approval filings, Rijkswaterstaat environmental impact assessments, and EU ETS carbon-accounting disclosures.
Data-stream reconciliation across foundation type, water depth tier, installation method, and end-user contracting structure anchored the analytical framework over the projection horizon. CAGRs were derived from installed capacity buildout trajectories segmented by monopile, jacket, gravity-base, and floating platform categories. Forecast inputs incorporated jack-up vessel fleet availability, high-yield steel price volatility, and marine mammal regulatory window constraints.
Several conditions sit outside the modeled scope, including unannounced floating platform technology breakthroughs, abrupt EU carbon-border adjustment mechanism expansions, and geopolitical disruptions to North Sea port operations. Forecasts reflect documented assumptions about auction mechanism continuity and vessel delivery schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Chimney Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Solar Farm Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Biogas Plant Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Solar Boat Market
Renewable Energy
Net-Zero Energy Buildings Market