
 United Arab Emirates Renewable Energy Market | 2026-2036
United Arab Emirates Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Renewable Energy Market Analytics
Abu Dhabi's solar manufacturing cluster is restructuring domestic supply chains for photovoltaic module assembly and concentrated solar power component fabrication. Masdar leverages its integrated project development platform across utility-scale solar and wind installations in the emirate. EWEC anchors procurement volumes through competitive auctions for independent power producers. DEWA sustains its technology leadership via the Mohammed bin Rashid Al Maktoum Solar Park expansion.
Renewable energy encompasses power generation systems that harness solar irradiance, wind kinetic energy, biomass organic matter, or hydrokinetic water flow without depleting fossil fuel reserves, with photovoltaic panels converting sunlight at 15-22% cell efficiency rates and concentrated solar power towers achieving 600°C molten salt storage temperatures for dispatchable evening generation. Solar dominates installed capacity across the Emirates, while concentrated solar power captures premium margins through integrated thermal storage that extends generation past sunset. Utility end users command the largest share of offtake volumes under long-term power purchase agreements, and commercial installations on warehouse and retail rooftops represent an emerging margin pool as distributed generation regulations mature.
MOHAP oversees environmental impact assessments for energy infrastructure, while the UAE's National Energy Strategy 2050 mandates clean power targets that reshape utility procurement schedules and grid interconnection standards. DEWA's distributed renewable energy regulations enable net metering for commercial and residential rooftop systems, expanding market access beyond utility-scale developers. Stakeholders must monitor auction tariff trajectories and storage co-location requirements as the next wave of project bidding reshapes capital allocation priorities.
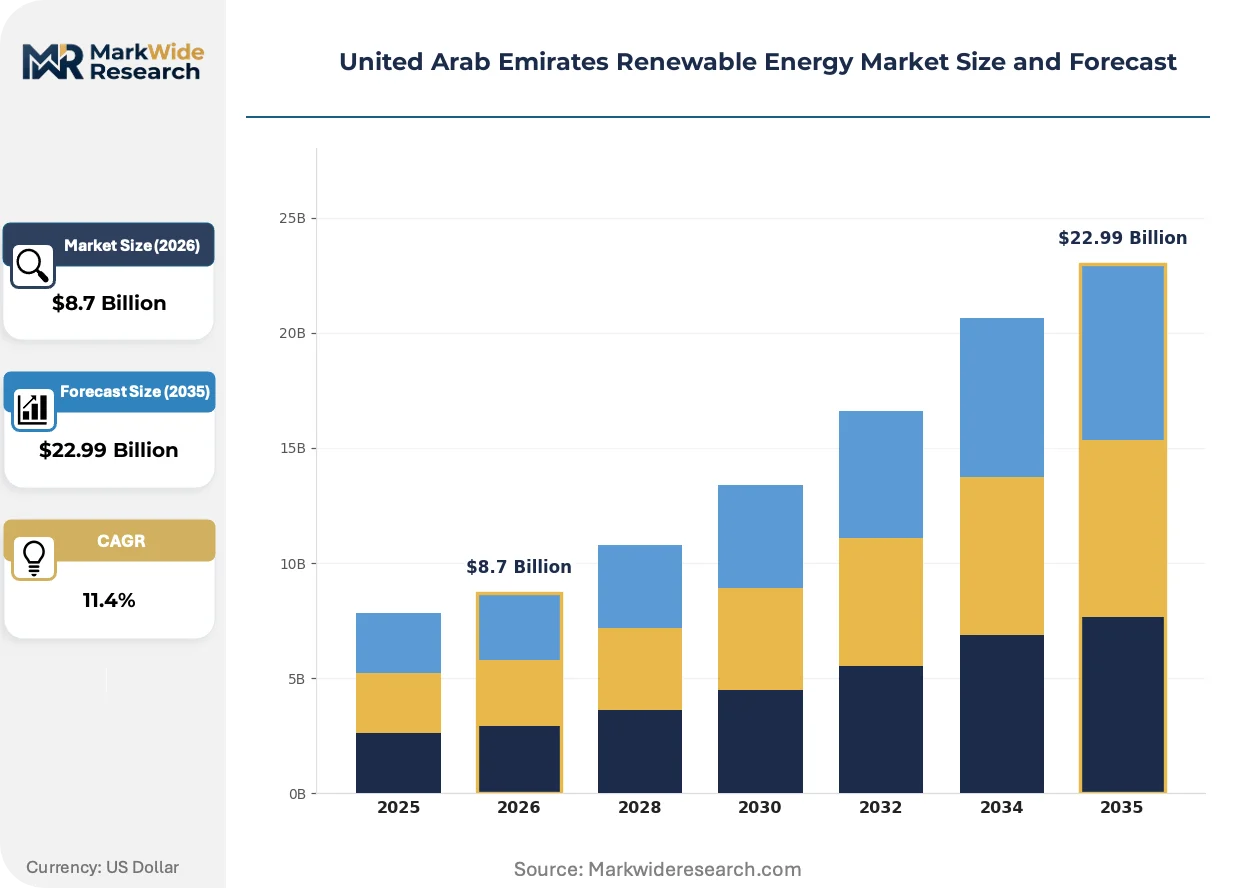
Market Dynamics
Utility-scale solar procurement auctions across Abu Dhabi and Dubai are compressing tariff benchmarks and forcing capital reallocation toward storage-integrated project configurations. EWEC and DEWA competitive bidding rounds now mandate co-located battery systems, reshaping developer technical requirements and financing structures.
Growth Catalysts
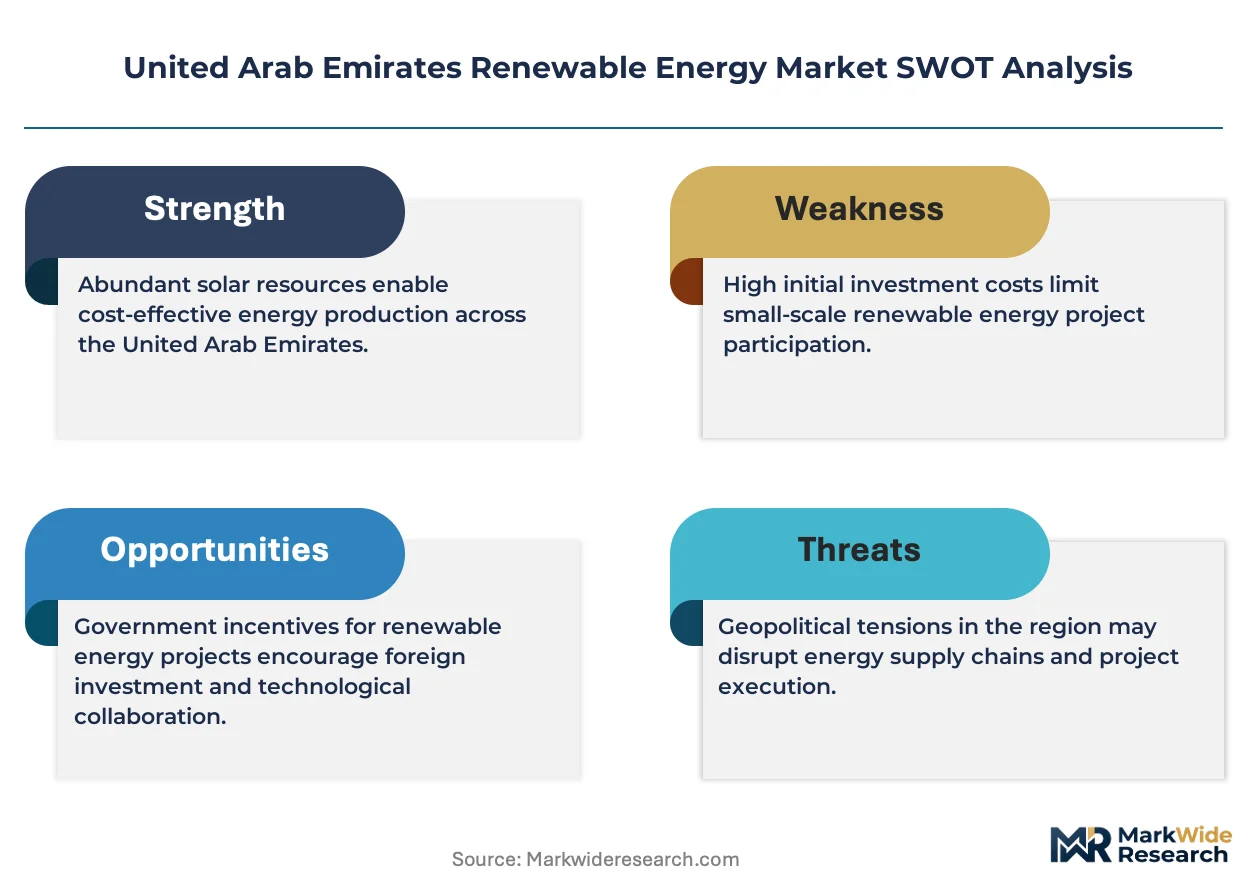
- National Energy Strategy 2050:The UAE's clean power mandate accelerates utility procurement schedules and establishes interconnection standards that reduce project approval timelines for independent power producers.
- Concentrated solar power with molten salt storage:Thermal storage systems achieving 600°C temperatures enable dispatchable evening generation, capturing premium capacity payments beyond photovoltaic daylight output.
- Abu Dhabi:The emirate's solar manufacturing cluster anchors domestic supply chains for photovoltaic module assembly, reducing import dependency and logistics costs for local developers.
Market Restraints
- Polysilicon price volatility:Raw material input swings compress developer margins and complicate long-term power purchase agreement pricing commitments.
- Land availability constraints:Desert terrain suitability assessments and environmental permitting create site concentration risk around Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park zones.
- Grid interconnection capacity:Transmission infrastructure buildout lags behind generation deployment, creating curtailment risk for utility-scale installations in remote locations.
Strategic Opportunities
- Commercial rooftop distributed generation:Warehouse and retail building stock across Dubai offers underpenetrated surface area for behind-the-meter photovoltaic systems as net metering regulations mature.
- Green hydrogen production:Electrolyzer-integrated renewable projects create new offtake demand streams from industrial decarbonization mandates in steel and ammonia sectors.
- DEWA distributed renewable regulations:The framework enables residential net metering participation, expanding market access beyond utility-scale independent power producers.
Industry Challenges
- Grid-scale battery integration complexity:Co-located storage systems require specialized power electronics engineering and control system expertise that remains scarce in regional labor markets.
- Environmental impact assessment timelines:MOHAP permitting procedures for desert ecosystem disruption create execution delays that extend project development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Renewable Energy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Wind, Biomass, Hydro Technology: Photovoltaic, Concentrated Solar Power, Wind Turbine, Hydrokinetic End User: Utility, Commercial, Industrial, Residential Installation: Onshore, Offshore, Ground Mounted, Rooftop |
| Companies Covered | Engie SA, TotalEnergies Renewables, Masdar, Trina Solar, Jinko Power, Emirates Water & Electricity Company (EWEC), EDF Renewables, DEWA, Yellow Door Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Renewable Energy Market Evolving Landscape
Bifacial photovoltaic modules and automated robotic cleaning systems are reshaping project economics across utility-scale installations. Technology convergence between generation and storage assets is compressing operational paradigms.
Bifacial solar panels capturing reflected irradiance from desert sand surfaces are electrifying capacity factor assumptions for new project bids. Developers incorporating this technology into Al Dhafra-scale installations report energy yield improvements that justify module cost premiums. The structural consequence is electrifying competitive positioning for engineering-procurement-construction contractors with advanced irradiance modeling capabilities.
MOHAP environmental impact assessment protocols now mandate biodiversity offset calculations for solar park developments. The regulation extends project development timelines but creates standardized permitting pathways that reduce regulatory uncertainty. Commercial rooftop segments face adapted requirements that balance ecosystem protection with distributed generation deployment goals.
Long-term power purchase agreements with industrial offtakers are displacing traditional utility-centric contracting models. Aluminum smelters and desalination operators in Abu Dhabi now negotiate direct renewable supply contracts that bypass Emirates Water & Electricity Company intermediation. This procurement evolution concentrates credit risk assessment demands on developer balance sheets.
United Arab Emirates Renewable Energy Market Segmentation
Segmentation in the UAE renewable energy market reveals how procurement authority, technology maturity, and site constraints allocate capital across divergent project configurations. Understanding these divisions exposes where tariff compression hits hardest and where regulatory tailwinds concentrate developer returns.
Product Type:
Buyers in this category differentiate by resource availability and dispatchability requirements rather than cost alone.
- Solar:Photovoltaic and concentrated solar power systems dominate procurement volumes across Abu Dhabi and Dubai. Utility-scale auctions at Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park anchor national capacity targets under the National Energy Strategy 2050.
- Wind:Onshore installations in northern emirates exploit coastal wind corridors with capacity factors improving as turbine hub heights increase. EWEC procurement rounds now include wind alongside solar to diversify generation profiles.
- Biomass:Organic waste-to-energy projects concentrate near urban centers with established feedstock collection infrastructure.
- Hydro:Limited to small run-of-river installations in mountainous northern terrain with constrained expansion potential.
Volume sits with Solar; growth tilts toward Wind as coastal resource assessments mature.
Technology:
Technology selection tracks the trade-off between capital efficiency and operational flexibility in desert climates.
- Photovoltaic:Bifacial modules capturing reflected irradiance from desert sand surfaces now dominate new project bids. DEWA and EWEC procurement mandates increasingly specify automated robotic cleaning systems to maintain performance ratios.
- Concentrated Solar Power:Molten salt storage achieving 600°C temperatures enables dispatchable evening generation. This technology captures premium capacity payments that photovoltaic daylight output cannot access.
- Wind Turbine:Larger rotor diameters and taller towers extract energy from low-wind-speed coastal corridors previously deemed uneconomical.
- Hydrokinetic:Tidal and river current systems remain pre-commercial with no operational installations in UAE waters.
Photovoltaic commands current deployment; Concentrated Solar Power offers the steepest expansion trajectory as storage co-location requirements tighten.
End User:
End user segmentation reflects divergent contracting structures and offtake risk profiles.
- Utility:Emirates Water & Electricity Company and DEWA anchor procurement through competitive auctions for independent power producers. Long-term power purchase agreements underwrite project finance with sovereign-backed credit enhancement.
- Commercial:Warehouse and retail rooftop installations represent an emerging margin pool. Net metering regulations enable behind-the-meter generation that reduces grid dependency for logistics and retail operators.
- Industrial:Aluminum smelters and desalination operators negotiate direct renewable supply contracts that bypass utility intermediation.
- Residential:Distributed generation participation remains constrained by rooftop ownership patterns and interconnection queue delays.
Utility absorbs the dominant share of capital; Commercial is climbing the fastest as distributed regulations mature.
Installation:
Installation type determines land use intensity and environmental permitting complexity.
- Ground Mounted:Utility-scale solar parks at Al Dhafra and Mohammed bin Rashid Al Maktoum concentrate capacity in desert zones with minimal competing land claims. MOHAP environmental impact assessments now mandate biodiversity offset calculations for these developments.
- Rooftop:Commercial building stock across Dubai offers underpenetrated surface area for distributed generation. DEWA regulations enable net metering that expands market access beyond utility-scale developers.
- Onshore:Wind turbine foundations in northern emirates face geotechnical constraints from coastal saline soils.
- Offshore:No operational capacity exists; resource assessments in Arabian Gulf waters remain preliminary.
Ground Mounted holds installed capacity; Rooftop gains share fastest as building-integrated photovoltaic costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desert solar irradiance concentrates development potential across the Arabian Peninsula, with coastal wind corridors and urban building stock diversifying resource portfolios beyond photovoltaic ground-mount installations.
Dubai
Mohammed bin Rashid Al Maktoum Solar Park anchors utility-scale procurement through DEWA competitive auctions. The emirate's distributed renewable regulations enable net metering for commercial rooftop systems. Jebel Ali and Dubai Industrial City warehouse clusters offer underpenetrated surface area for behind-the-meter photovoltaic deployment.
Abu Dhabi
Al Dhafra solar complex concentrates photovoltaic and concentrated solar power capacity under EWEC procurement mandates. Masdar leverages its integrated development platform across utility-scale installations. Khalifa Industrial Zone hosts module assembly facilities that reduce import dependency for domestic developers.
Sharjah
Waste-to-energy projects exploit established feedstock collection infrastructure from urban centers. The emirate's environmental regulations under MOHAP jurisdiction mandate biodiversity assessments for desert ecosystem disruption. Industrial zones near the coast face saline soil constraints for ground-mounted installations.
Northern Emirates
Coastal wind corridors in Ras Al Khaimah and Fujairah exploit improved turbine hub heights for low-wind-speed resource extraction. Mountainous terrain constrains hydrokinetic expansion to small run-of-river configurations. Port infrastructure supports component logistics for offshore wind assessments in preliminary phases.
United Arab Emirates Renewable Energy Market Competitive Landscape
Global majors compete with regional champions across procurement auction participation and technology integration capabilities. The vendor base stratifies into sovereign-linked developers, European energy conglomerates, and Asian equipment suppliers. Three archetypes dominate: integrated project developers with captive engineering capabilities, independent power producers reliant on competitive bidding, and technology-agnostic engineering-procurement-construction contractors. Capacity expansion and strategic partnerships constitute the dominant competitive moves as auction mandates tighten storage co-location requirements.
Among European energy conglomerates, Engie SA and TotalEnergies Renewables exemplify the integrated developer archetype through their Middle East platform presence. Masdar occupies a distinctive position as a sovereign-linked developer with domestic supply chain integration. These entities anchor competitive positioning across utility-scale auction participation and long-term power purchase agreement structuring.
| Leading Market Players |
|---|
| Engie SA |
| TotalEnergies Renewables |
| Masdar |
| Trina Solar |
| Jinko Power |
| Emirates Water & Electricity Company (EWEC) |
| EDF Renewables |
| DEWA |
| Yellow Door Energy |
| Others |
Value Network & Pricing Analysis
Specialized power electronics engineers concentrated in Dubai and Abu Dhabi command wage premiums that widen pricing spreads between integrated EPC providers and pure-play developers bidding into EWEC and DEWA auctions. Labor-cost differentials across these skill clusters translate directly into tiered service bundling strategies, with premium tiers capturing extended warranty and performance guarantees.
Pricing Analysis
Warranty and O&M service bundling separates premium developer bids from unbundled equipment-only proposals in competitive auctions. Contract structures stratify across integrated EPC with 25-year asset management, standard build-transfer with limited defect coverage, and economy tier equipment supply without performance guarantees. Price differentiation hinges on bankability of offtake contracts and technology performance warranties. Margins are tightening in the economy tier as polysilicon input volatility compresses developer returns. Utility offtakers demonstrate lowest price sensitivity due to sovereign-backed credit enhancement, while commercial rooftop buyers exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Direct-to-utility procurement channels handle hyperscale project demand from EWEC and DEWA, while distributor networks serve commercial and industrial distributed generation. Manufacturing concentration centers on China for photovoltaic cells and modules, South Korea for battery storage systems, and domestic UAE facilities for module assembly at Khalifa Industrial Zone. Component sourcing draws from polysilicon feedstock, lithium-ion cells, and power conversion electronics. Single-source vulnerability in battery cell supply creates exposure to export restriction risks. Distribution runs through EPC contractors for utility-scale deployment and electrical wholesalers for commercial rooftop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE renewable energy market sits in a technology-transition phase where bifacial photovoltaic systems with robotic cleaning integration displace legacy monofacial fixed-tilt configurations across new project bids.
For Market Incumbents: Lock in long-term polysilicon supply agreements to defend margins against raw material volatility threatening project finance viability. Secure captive engineering talent pools in power electronics and grid integration to maintain technical differentiation as storage co-location mandates intensify. Vertical integration into module assembly within Khalifa Industrial Zone reduces logistics exposure and import dependency.
For New Entrants and Emerging Players: Warehouse operators in Jebel Ali and Dubai Industrial City represent an underserved buyer archetype with unmet demand for behind-the-meter rooftop systems. Target commercial distributed generation segments where net metering regulations are maturing and competition remains fragmented. Pursue direct contracting relationships with industrial offtakers in aluminum smelting and desalination bypassing utility intermediation.
For Investors and Strategic Acquirers: Re-rating potential sits with engineering-procurement-construction contractors possessing advanced irradiance modeling capabilities given bifacial technology yield premiums reshaping competitive positioning. Long-term viability favors entities with integrated development platforms spanning project origination through asset management. Monitor auction tariff trajectories and storage co-location penetration rates as inflection indicators for capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Integration | Battery-integrated solar bids satisfy EWEC and DEWA auction mandates reshaping project economics. |
| Domestic Module Assembly Scale-up | Khalifa Industrial Zone manufacturing reduces import dependency and logistics costs for local developers. |
| Direct Industrial Offtake Contracting | Bypassing Emirates Water & Electricity Company intermediation captures premium margins from aluminum smelters. |
| Commercial Rooftop Platform Buildout | Net metering-enabled distributed generation expands market access beyond utility-scale independent power producers. |
| Green Hydrogen Electrolyzer Integration | Industrial decarbonization mandates in steel and ammonia sectors create new offtake demand streams. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings presented in this analysis. Primary interviews with these stakeholders combined with secondary validation from IEA reports, EIA data, FERC filings, and project development databases establish empirical grounding. Bottom-up capacity installation tracking and top-down policy target reconciliation triangulate market sizing across the analysis window.
Historical reference periods spanning completed auction rounds and operational project commissioning anchored the forecast window to observable deployment trajectories. The analytical framework models segmentation across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type throughout the forecast period. CAGRs derive from capacity addition run-rates, tariff compression curves, and technology cost reduction trajectories. Key forecast inputs include auction participation patterns and storage co-location adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polysilicon price volatility, grid interconnection buildout delays, and regulatory shifts in distributed generation frameworks. Forecasts reflect assumptions around technology learning curves and policy continuity without guarantee. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
Romania Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Solar Boat Market
Renewable Energy
Biogas Plant Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Solar Oven Market