
 Multi-Point Ground Flares (MPGF) Market | 2026-2036
Multi-Point Ground Flares (MPGF) Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Point Ground Flares (MPGF) Market Insights
The direct-sales channel between flare-system OEMs and integrated refinery operators is narrowing as EPC contractors consolidate procurement authority. Zeeco leverages its combustion-technology heritage to anchor long-term service contracts in the Gulf. John Zink Hamworthy Combustion sustains engineering intensity through its dedicated flare-R&D centers. Honeywell International competes by bundling MPGF units with its broader process-automation portfolio.
Multi-Point Ground Flares are elevated combustion devices that distribute hydrocarbon waste gas across multiple burner tips at ground level, typically achieving destruction-removal efficiencies above 98 percent through staged air-fuel mixing and proprietary tip geometries. These systems serve primarily to eliminate volatile organic compounds and hazardous air pollutants from refinery upset conditions, chemical-plant venting, and landfill-gas recovery operations. Fixed Flares dominate installed base value due to permanent refinery infrastructure commitments, while Portable Flares capture incremental demand from shale-patch drilling and temporary turnaround projects. The Oil & Gas end-user segment concentrates procurement volume, though Environmental Services accounts for the fastest-growing share as biogas-capture regulations tighten across North America and Europe.
EPA flare-monitoring rules under 40 CFR Part 60 Subpart Ja mandate continuous tip-monitoring and visible-emission limits, forcing upgrades of legacy single-point systems. The EU methane-emission framework and F-Gas Regulation impose parallel combustion-efficiency benchmarks, shaping product-access requirements for suppliers serving European petrochemical complexes. Stakeholders must monitor how Saudi Arabia's national oil company integrates MPGF specifications into its domestic EPC tender standards, as this template propagates across Middle Eastern project finance.
Market Dynamics
Refinery operators face mounting pressure to eliminate visible flaring during startup and upset conditions, forcing a wholesale replacement of single-point elevated flares with ground-level distributed combustion architectures that satisfy both EPA visible-emission limits and community nuisance standards.
Growth Catalysts
- Sour-gas processing expansion:Middle Eastern national oil companies are building petrochemical complexes that handle high-hydrogen-sulfide feedstocks, requiring MPGF systems capable of staged combustion for acid-gas streams.
- 40 CFR Part 60 Subpart Ja:EPA's continuous tip-monitoring mandate is compelling US refineries to retire unmonitored legacy flares and install ground-based alternatives with integrated sensor networks.
- Landfill-gas recovery:North American waste-management operators are deploying portable MPGF units at closed municipal landfills to destroy methane-rich off-gas under tightening state-level climate mandates.
Market Restraints
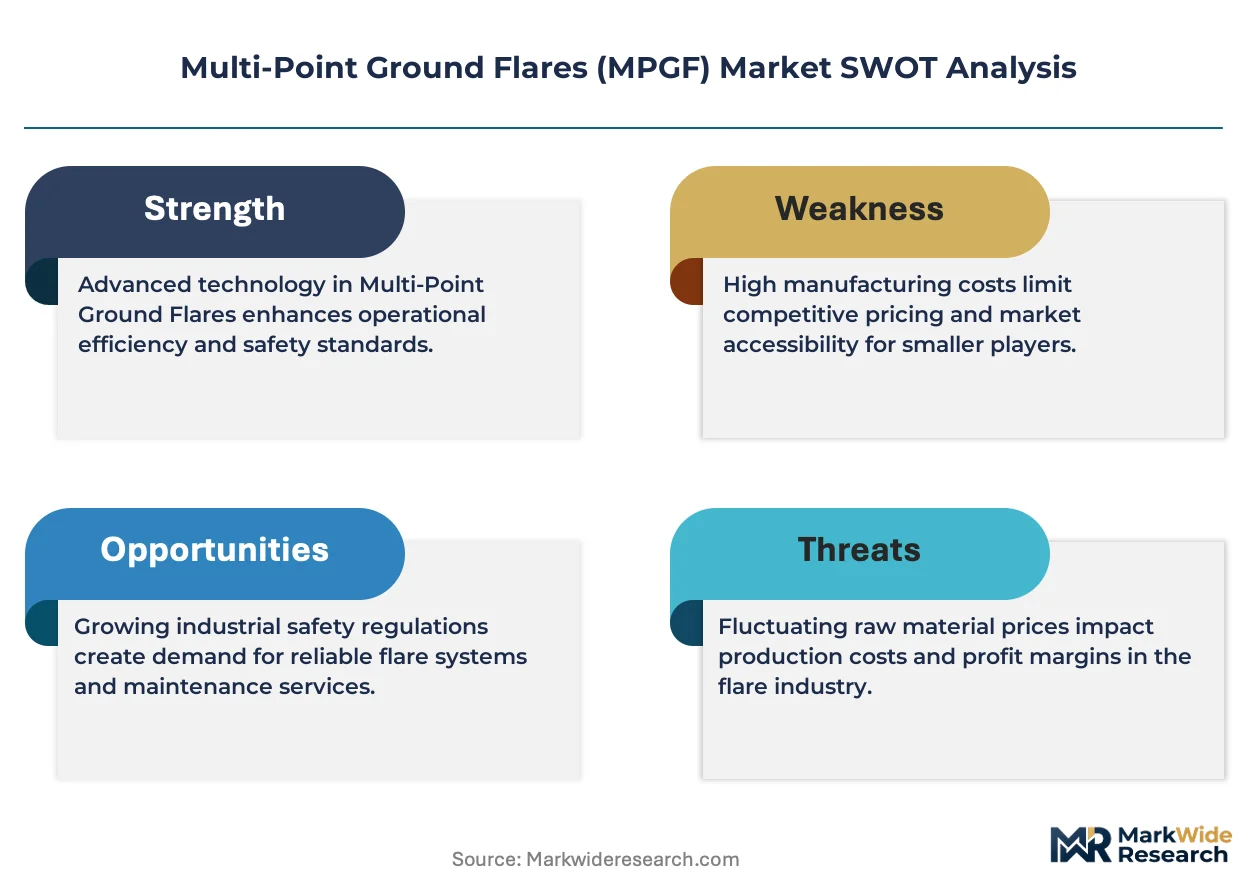
- Specialized alloy costs:Burner-tip assemblies require Inconel and Hastelloy formulations to withstand sour-gas corrosion, exposing OEMs to nickel price volatility and long lead times from specialty foundries.
- Fabrication concentration:Pressure-vessel and flare-stack manufacturing clusters in the US Gulf Coast and Northeast China create geographic supply vulnerability for project timelines.
- Combustion-efficiency ceilings:Current tip geometries achieve 98-99% destruction-removal efficiency, leaving minimal headroom for regulatory buffers if methane-emission standards tighten further.
Strategic Opportunities
- Biogas upgrading sites:Agricultural digesters and wastewater treatment plants in Germany and Denmark represent underpenetrated demand for small-scale MPGF systems that handle variable biogas composition.
- Modular skid integration:Packaged MPGF units pre-integrated with gas-compression and control systems are opening direct sales to midstream operators bypassing traditional EPC channels.
- EU methane-emission framework:The bloc's tiered verification and repair requirements for oil and gas infrastructure are accelerating replacement cycles for unmeasured flaring assets.
Industry Challenges
- Combustion-engineering talent scarcity:Experienced flare-design specialists with expertise in computational fluid dynamics and flame-stability modeling are concentrated at a handful of legacy suppliers.
- Legacy control-system integration:Refinery distributed control systems using proprietary protocols from the 1990s require costly middleware development to interface with modern MPGF monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Point Ground Flares (MPGF) Market |
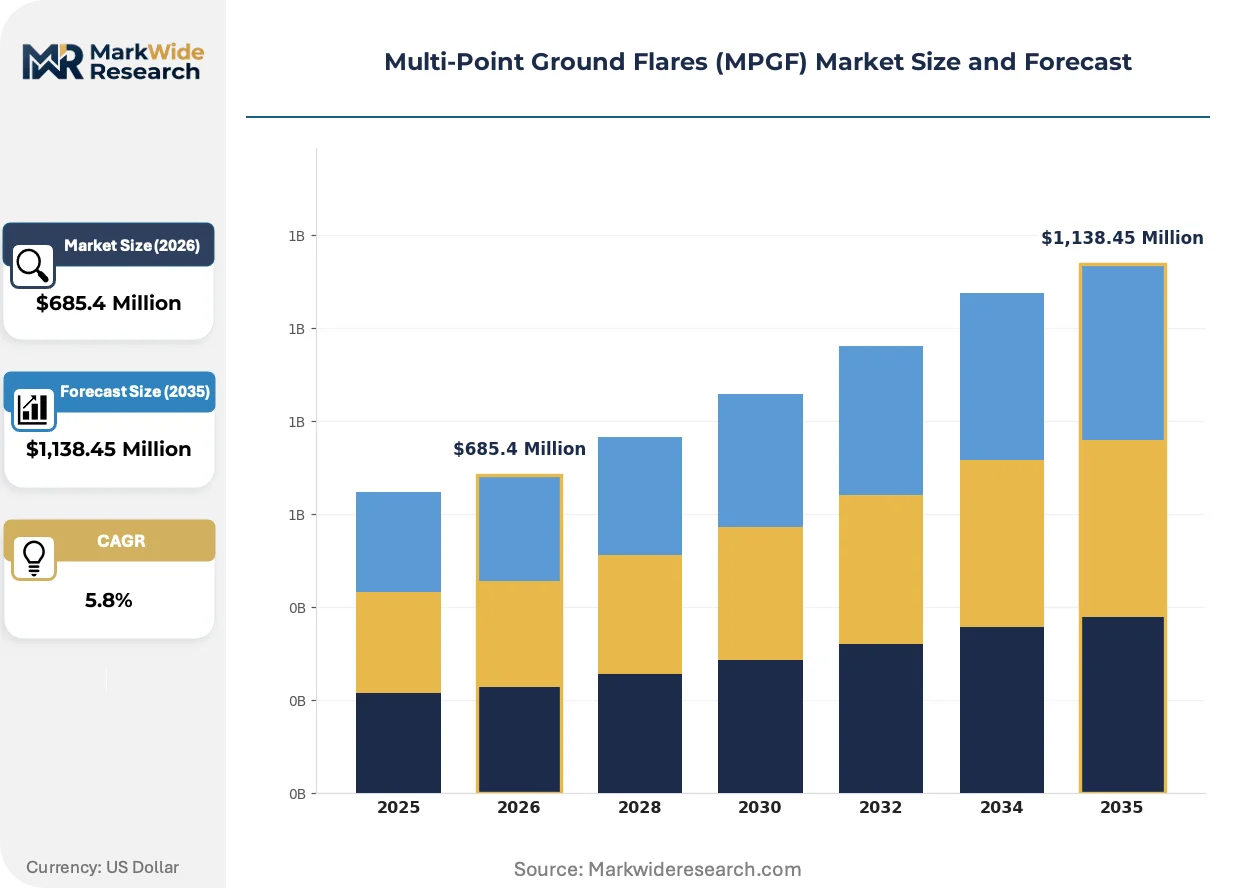
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Flares, Portable Flares, Flare Systems, Dual-Point Flares Installation Type: Onsite Installation, Offsite Installation, Modular Setup, Custom Installation End User: Oil & Gas, Chemical Industry, Waste Management, Environmental Services Fuel Type: Natural Gas, Propane, Biogas, Others |
| Companies Covered | Zeeco, John Zink Hamworthy Combustion, Honeywell International, ABB Group, Eaton Corporation, Schneider Electric SE, Hubbell Incorporated, HiTemp Technology, Fives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Point Ground Flares (MPGF) Market Trends and Innovations
Staged air-fuel mixing architectures and real-time optical flame-detection systems are converging to redefine combustion-performance benchmarks, while procurement authority migrates from owner-operators toward consolidated EPC engineering teams.
Pilotless ignition systems using high-energy spark electrodes and ultraviolet flame sensors are collapsing the traditional distinction between continuous-pilot and intermittent-flare operating modes. Offshore platform operators in the North Sea are adopting these systems to eliminate pilot-gas consumption during low-flow venting events. The technology is collapsing maintenance schedules and fuel-cost structures that have governed flare economics for four decades.
EPA's 2024 enforcement memorandum on startup, shutdown, and malfunction events is extending continuous monitoring requirements to flares handling refinery fuel gas and process off-gas previously exempt under grandfather clauses. Refineries in Texas and Louisiana are responding by retrofitting ground-flare bases with redundant thermocouple arrays and video-imaging systems. The policy is accelerating capital-commitment timelines for turnaround windows that were previously deferred.
Long-term service contracts bundling combustion-hardware supply with predictive maintenance and tip-replacement programs are displacing transactional equipment sales in the Middle East. Saudi Aramco and ADNOC are consolidating procurement through preferred EPC panels that specify multi-year performance guarantees. The model is most visible in Jubail and Ruwais industrial cities, where integrated project-delivery contracts now dominate greenfield petrochemical awards.
Multi-Point Ground Flares (MPGF) Market Segmentation
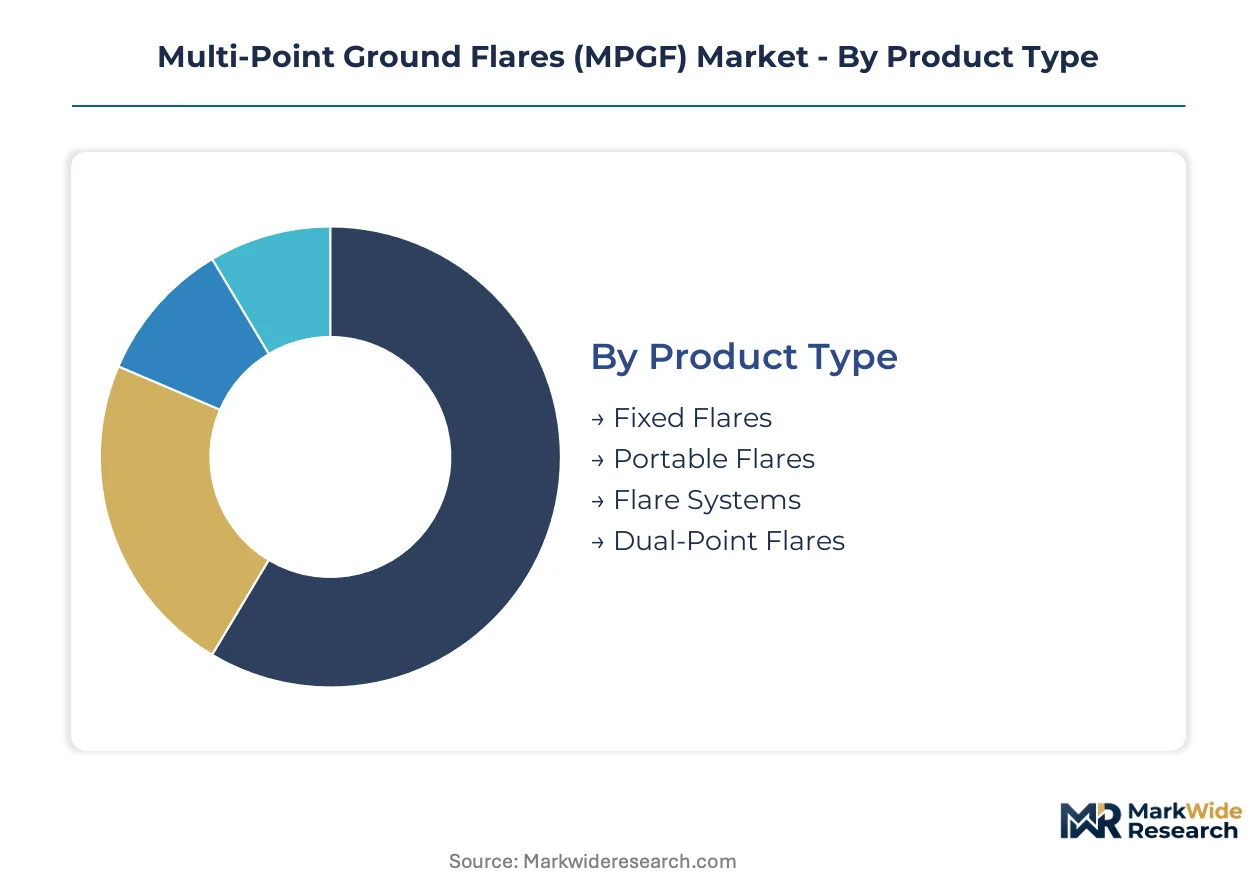
Multi-Point Ground Flares serve distinct operational profiles across permanent infrastructure and temporary deployment scenarios. Segment boundaries reflect combustion-capacity requirements, regulatory compliance tiers, and mobility constraints that shape procurement specifications.
Product Type:
Mature permanent installations dominate capital allocation, while emerging mobile formats capture episodic demand from exploration and turnaround cycles.
- Fixed Flares:Permanent ground-level combustion arrays with reinforced concrete foundations and integrated staging manifolds. Saudi Aramco's Jubail and Ruwais petrochemical complexes anchor procurement volume as sour-gas processing capacity expands across the Gulf.
- Portable Flares:Skid-mounted units with rapid-deployment frames and self-contained fuel trains. Shale-patch operators in Texas and North Dakota deploy these for drilling-completion flaring where pipeline connectivity lags production timelines.
- Flare Systems:Turnkey architectures bundling burner tips, ignition controls, and monitoring instrumentation.
- Dual-Point Flares:Compact two-tip configurations for intermediate flow-rate applications.
Fixed Flares retains volume leadership; Portable Flares holds the steepest expansion curve.
Installation Type:
Cost tiering separates capital-intensive foundation work from modular formats that compress project timelines.
- Onsite Installation:Full civil-works construction with embedded pilings and permanent utility connections. US Gulf Coast refineries favor this approach under EPA 40 CFR Part 60 Subpart Ja mandates requiring hardwired monitoring infrastructure.
- Modular Setup:Pre-fabricated skids with plug-and-play utility interfaces. Midstream operators in the Permian Basin deploy these to bypass traditional EPC procurement channels and accelerate compliance deadlines.
- Offsite Installation:Remote fabrication with final assembly at destination.
- Custom Installation:Site-specific engineering for constrained footprints or extreme corrosion environments.
Onsite Installation commands the premium tier; Modular Setup is gaining share fastest among time-constrained buyers.
End User:
Application intensity varies across hydrocarbon extraction, chemical synthesis, and waste-stream destruction.
- Oil & Gas:Upstream production facilities, gas-processing plants, and refinery complexes managing routine venting and upset conditions. Kuwait's Al-Zour refinery and UAE's Ruwais expansion anchor regional demand as sour-crude throughput rises.
- Environmental Services:Landfill-gas destruction and biogas upgrading facilities. German and Danish agricultural digesters drive adoption under EU methane-emission framework verification requirements.
- Chemical Industry:Petrochemical crackers and specialty chemical plants handling variable off-gas composition.
- Waste Management:Municipal landfill operators and industrial waste processors.
Oil & Gas retains volume leadership; Environmental Services climbs the fastest as biogas regulations tighten.
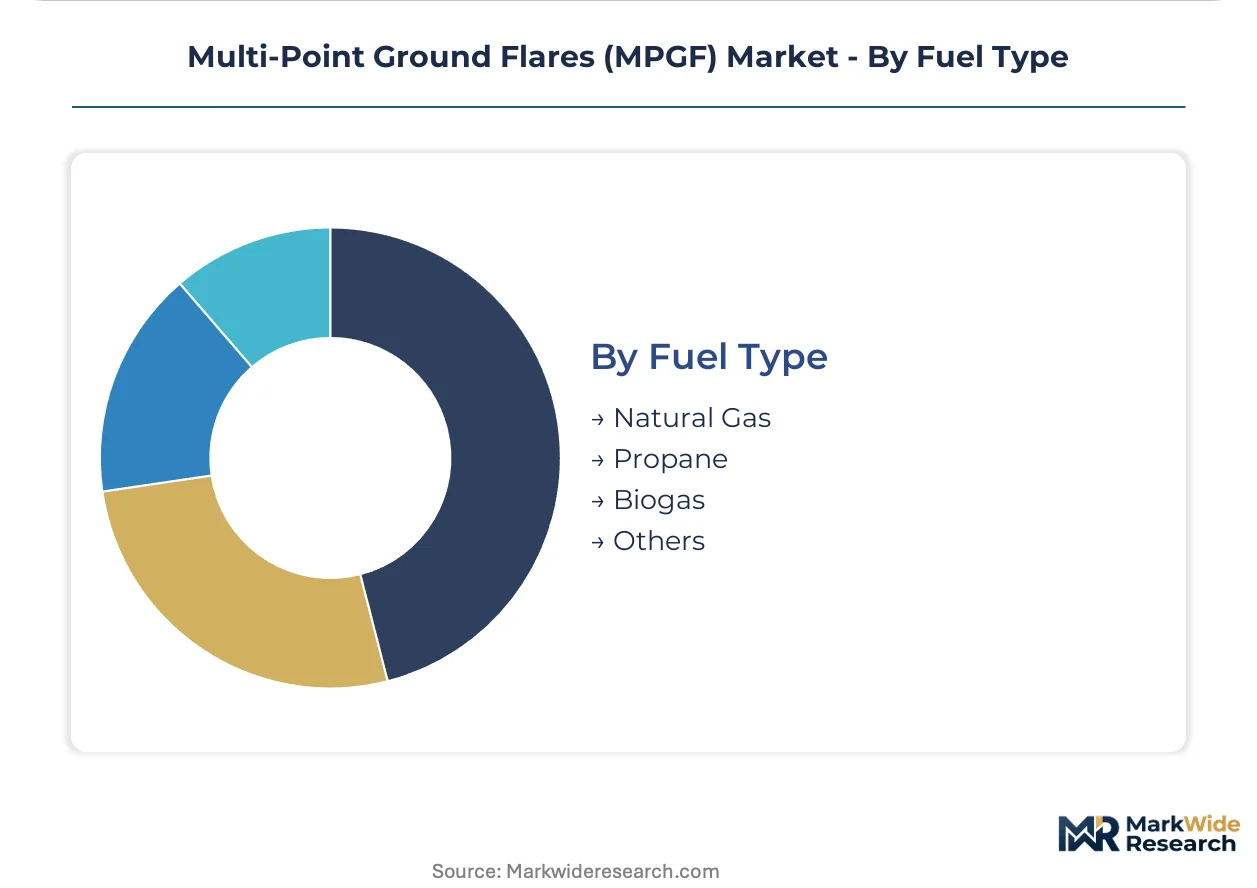
Fuel Type:
Feedstock chemistry dictates burner-tip metallurgy and air-fuel staging geometry.
- Natural Gas:Methane-rich streams with consistent heating value and minimal contaminants. Standard refinery fuel-gas systems in Louisiana and Texas deploy these configurations under visible-emission limits.
- Biogas:Variable-composition streams from anaerobic digestion with elevated CO2 fractions and siloxane traces. Danish wastewater treatment plants and German agricultural facilities specify corrosion-resistant tip assemblies.
- Propane:Liquefied petroleum gas venting from storage and distribution infrastructure.
- Others:Acid-gas streams, refinery fuel gas with elevated hydrogen sulfide, and synthetic off-gas mixtures.
Natural Gas retains volume leadership; Biogas shows the steepest expansion trajectory as carbon-accounting frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Cooperation Council's integrated pipeline network underwrites the Middle East's dominance in sour-gas processing infrastructure. This regional concentration shapes procurement patterns across the MPGF value chain.
Saudi Arabia
Saudi Aramco's Jubail and Ruwais petrochemical complexes anchor regional demand for staged combustion systems. The kingdom's domestic EPC tender standards propagate specifications across Gulf project finance. Jazan Economic City and Ras Al-Khair industrial zones concentrate new capacity additions for acid-gas handling.
United States
EPA's 40 CFR Part 60 Subpart Ja enforcement memorandum compels Texas and Louisiana refineries to retrofit ground-flare bases with redundant monitoring arrays. The Permian Basin's midstream operators deploy modular skid formats to compress compliance timelines. Houston's fabrication corridor supplies pressure-vessel assemblies for domestic turnaround cycles.
United Arab Emirates
ADNOC's Ruwais expansion and Al Yasat offshore developments drive procurement for high-hydrogen-sulfide feedstock handling. The country's preferred EPC panel structure consolidates multi-year performance guarantees. Abu Dhabi's KIZAD industrial zone hosts integrated project-delivery contracts for downstream complexes.
Germany
The EU methane-emission framework's tiered verification requirements accelerate replacement cycles for unmeasured flaring assets. Agricultural digesters in Lower Saxony and Bavaria specify corrosion-resistant tip assemblies for variable biogas composition. The Ruhr industrial corridor maintains legacy refinery infrastructure requiring control-system middleware upgrades.
Canada
Alberta's oil sands operators face provincial methane-reduction mandates targeting venting from upstream production facilities. The Scotford Upgrader and Strathcona refinery complexes anchor demand for permanent ground-level combustion arrays. Calgary's engineering services cluster supports modular deployment across the Western Canadian Sedimentary Basin.
Multi-Point Ground Flares (MPGF) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on burner-tip and ignition-module supply. The vendor base stratifies between full-service combustion houses and modular skid fabricators. Three archetypes dominate: legacy flare-technology heritage players, diversified process-automation conglomerates, and regional EPC-integrated suppliers. Competitive moves concentrate on long-term service contract bundling and predictive-maintenance program anchoring.
Within the heritage-technology tier, Zeeco and John Zink Hamworthy Combustion exemplify combustion-engineering specialists with concentrated flare-R&D capabilities. Honeywell International occupies a position among diversified industrial conglomerates bundling MPGF units with broader automation portfolios. These three anchors represent distinct strategic postures toward EPC channel consolidation and direct owner-operator engagement.
| Leading Market Players |
|---|
| Zeeco |
| John Zink Hamworthy Combustion |
| Honeywell International |
| ABB Group |
| Eaton Corporation |
| Schneider Electric SE |
| Hubbell Incorporated |
| HiTemp Technology |
| Fives |
| Others |
Pricing and Supply Chain Analysis
Houston's fabrication corridor anchors North American pressure-vessel capacity, concentrating burner-tip assembly production among a handful of specialty foundries. This geographic clustering grants incumbent OEMs pricing leverage over midstream operators facing compressed compliance timelines under EPA mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Premium tiers bundle predictive maintenance and tip-replacement guarantees; standard tiers cover hardware-only transactions; economy tiers serve temporary shale-patch deployments. Price differentiation hinges on metallurgical certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because portable flare fabricators compete on deployment speed. Midstream operators in the Permian Basin exhibit the highest price sensitivity; Saudi Aramco's preferred EPC panels demonstrate the lowest due to multi-year performance guarantee requirements.
Supply Chain Analysis
Export-control restrictions on high-temperature alloy formulations limit burner-tip technology flows to certain jurisdictions. Manufacturing concentrates in the United States, Germany, and Japan. Supply chains draw from nickel ore processing in Indonesia, specialty steel rolling in South Korea, and precision machining in Switzerland. Single-source vulnerability persists for Inconel and Hastelloy castings from a limited supplier base. Distribution runs through EPC contractor procurement panels in the Middle East and direct OEM sales to North American midstream operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Saudi Aramco and ADNOC consolidate procurement through preferred EPC panels, fragmenting direct access for smaller combustion-technology vendors.
For Market Incumbents: Insulate service revenue streams by anchoring long-term performance guarantees with Gulf national oil companies. Deepen backward integration into specialty alloy foundries to buffer nickel price volatility. Counter modular skid competitors by embedding predictive maintenance platforms that lock in replacement-part demand. For New Entrants and Emerging Players: Small-scale biogas upgrading facilities in Denmark and Germany represent the most penetrable entry point given corrosion-resistant tip demand and limited incumbent service coverage. Portable flare rentals for North American shale-patch drilling completions offer second-mover traction where pipeline connectivity lags. Partner with agricultural digester operators on outcome-based destruction-efficiency contracts rather than capital-equipment sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors combustion-engineering specialists with captive CFD modeling capabilities and established tip-replacement annuity streams. Long-term viability rests on regulatory ratcheting rather than cyclical energy investment. Target acquisition archetypes include regional EPC-integrated suppliers in the Middle East with Aramco panel relationships. Monitor EPA enforcement memorandum expansion to refinery fuel-gas systems as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Bundling | Saudi Aramco's preferred EPC panels now mandate multi-year performance guarantees covering tip replacement and predictive maintenance. |
| Backward Integration into Specialty Alloys | Captive Inconel and Hastelloy supply buffers OEMs against nickel price volatility and extended foundry lead times. |
| Modular Skid Pre-integration | Packaged MPGF units with gas-compression and control systems bypass traditional EPC channels for Permian Basin midstream buyers. |
| Pilotless Ignition System Deployment | North Sea platform operators adopt high-energy spark electrodes to eliminate pilot-gas consumption and collapse maintenance schedules. |
| Biogas Corrosion-Resistant Tip Development | German and Danish agricultural digesters drive specification of siloxane-tolerant burner assemblies under EU methane verification. |
Research Methodology
Cross-validation between regulatory filing analysis and EPC procurement documentation anchors the qualitative findings. Primary interviews with flare-system OEM technical directors, refinery maintenance managers, and EPC contractor procurement leads combined with secondary validation from EPA enforcement memoranda, EU methane-emission framework texts, and Saudi Aramco tender specifications. Bottom-up unit deployment estimates triangulate against top-down petrochemical capacity expansion announcements across the analysis window.
Calibration against historical turnaround cycles and sour-gas processing capacity additions shapes the projection framework. Segmentation dimensions span product type, installation format, end-user industry, fuel chemistry, and regional regulatory cluster. CAGRs derive from modeled deployment trajectories under baseline, accelerated compliance, and deferred investment scenarios. Industry-specific inputs include refinery upset frequency distributions and biogas capture mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in nickel price volatility, Gulf project finance availability, or EPA enforcement intensity would shift the trajectory. Forecasts reflect assumptions regarding regulatory ratcheting continuity and sour-gas processing capacity expansion. Material shifts in EU methane-emission verification timelines or Middle Eastern EPC panel consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Seals Market