
 Liner Regulators Market | 2026-2036
Liner Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Liner Regulators Market Analytics
Modular power management IC bundling is restructuring how OEMs evaluate linear regulator suppliers. Texas Instruments leverages its broad analog portfolio to anchor multi-chip module strategies across automotive and industrial accounts. Analog Devices competes through precision voltage reference integration into signal-chain bundles. ROHM Semiconductor specializes in ultra-low-noise LDO variants for audio and RF subsystems.
A linear regulator is an integrated circuit that maintains a constant output voltage through a pass element operating in its active region, with dropout voltage, quiescent current, and load regulation serving as core performance parameters; it delivers clean, ripple-free DC power to noise-sensitive analog and mixed-signal electronics. Low-dropout regulators dominate margin pools in battery-powered and automotive applications where headroom voltage is constrained. Digital regulators represent the fastest-growing technology segment as firmware-configurable output enables dynamic voltage scaling in data processing units. Analog regulators remain mature but sustain volume in cost-sensitive consumer electronics and legacy industrial automation.
The EU Ecodesign Directive and REACH frameworks constrain material choices and minimum efficiency thresholds for linear regulators sold into European automotive and industrial channels. China's GB standards and MIIT efficiency certifications govern market access for imported power management ICs. FDA electromagnetic compatibility requirements shape regulator selection in medical device subsystems sold into the United States. Stakeholders must monitor how regional efficiency mandates diverge and whether single-SKU global qualification remains viable against multiplying local certification regimes.
Market Dynamics
Automotive electrification is compressing headroom margins in battery management systems, forcing linear regulator architectures toward sub-300mV dropout designs while multi-chip module bundling restructures supplier evaluation criteria across tier-one electronics manufacturing.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds for standby power consumption are accelerating replacement cycles in European industrial automation and white goods controllers.
- Battery management systems:Electric vehicle platform proliferation in Germany and China is pulling precision voltage regulation into high-volume automotive qualification pipelines.
- East Asian fabrication clusters:Taiwan and South Korea concentrate advanced BCD process capacity, enabling integrated LDO-plus-supervisor devices that reduce BOM complexity.
Market Restraints
- Silicon wafer supply concentration:300mm analog-grade substrate availability remains constrained by foundry allocation priorities in Taiwan, creating input cost volatility for discrete LDO manufacturers.
- Switching regulator substitution:Synchronous buck converters achieving 95%+ efficiency are displacing linear topologies in thermally unconstrained industrial power supplies above 500mA load.
- REACH substance restrictions:European chemical authorization requirements are complicating lead-frame plating chemistries and mold compound selections for automotive-qualified packages.
Strategic Opportunities
- Medical device subsystems:FDA electromagnetic compatibility requirements for patient-connected electronics are creating preference for ultra-low-noise LDOs in diagnostic imaging and patient monitoring equipment.
- Digital LDO convergence:Firmware-configurable output voltage with dynamic scaling capability is opening architectural slots in data processing units and AI accelerators.
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and testing are attracting regulator suppliers to establish local qualification support for domestic OEMs.
Industry Challenges
- Analog design expertise scarcity:Deep submicron BCD process characterization and noise optimization skills are concentrating among senior engineers at established IDMs, constraining fabless competitor scaling.
- Multi-certification timelines:Simultaneous AEC-Q100 automotive, IEC 61000 EMC, and medical IEC 60601 qualification runs are extending product release cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liner Regulators Market |
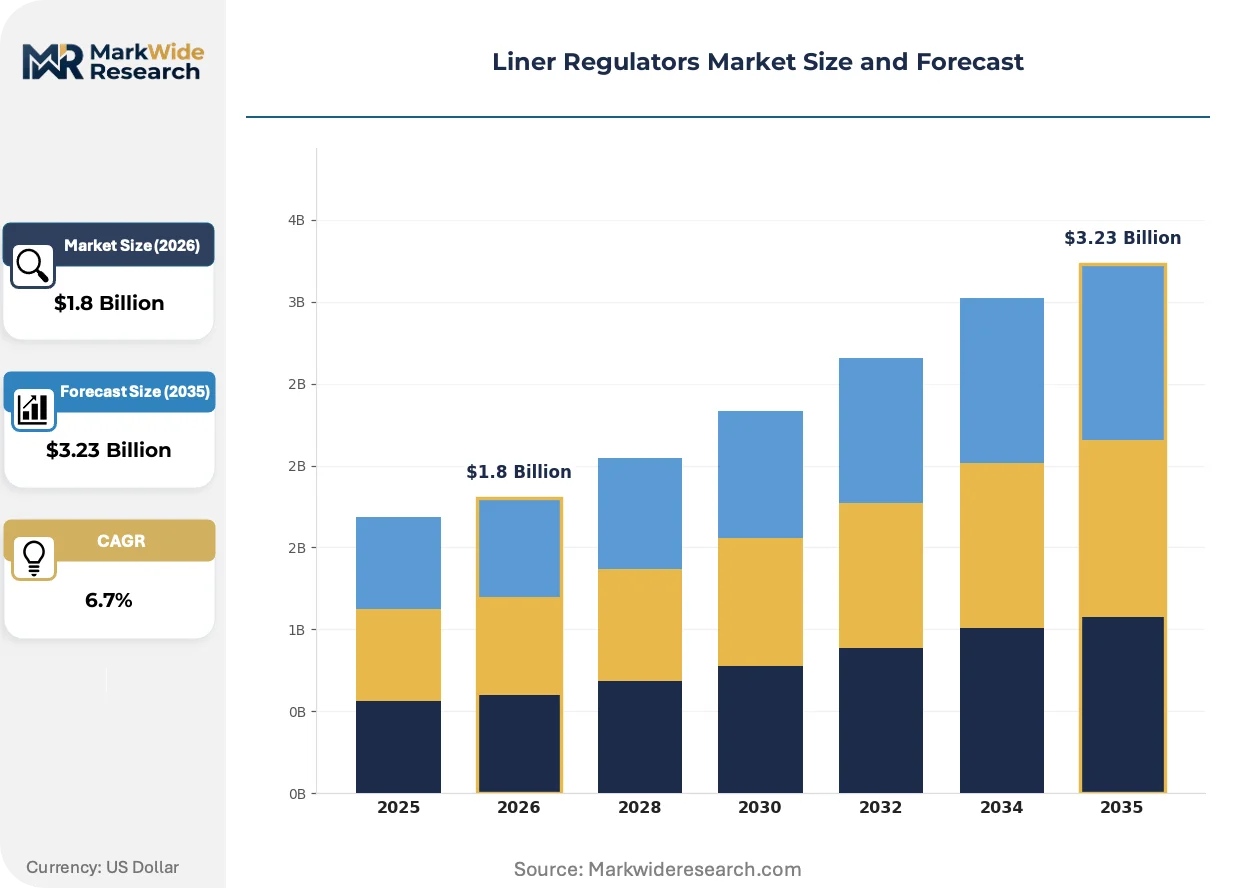
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Regulators, Digital Regulators, Low-Dropout Regulators, Switching Regulators End User: Consumer Electronics, Automotive Industry, Industrial Automation, Telecommunications Technology: Linear Technology, Switching Technology, Power Management ICs, Voltage References Application: Communication Systems, Power Supply Circuits, Audio Equipment, Data Processing Units |
| Companies Covered | Texas Instruments, Analog Devices, onsemi, STMicroelectronics, NXP Semiconductors, Infineon Technologies, Microchip Technology, Renesas Electronics, ROHM Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liner Regulators Market Evolving Landscape
Power management integration is collapsing discrete component counts into functional blocks, while regional efficiency mandates and procurement centralization are rewriting how suppliers compete on specification compliance and volume pricing.
Multi-output power management ICs with embedded LDO, DC-DC, and supervisor functions are modularizing subsystem power design. Automotive tier-one suppliers are adopting these consolidated devices aggressively to reduce PCB area and thermal management complexity. The shift is compressing demand for standalone linear regulators in body electronics and infotainment modules.
China's GB standards and MIIT efficiency certifications are tightening standby power limits for imported power management ICs. Domestic OEMs are now requiring pre-certified components to accelerate product registration timelines. Consumer electronics and small appliance manufacturers bear the heaviest compliance burden as they source across multiple supplier geographies.
Centralized procurement at automotive and industrial OEMs is consolidating supplier lists around vendors with broad analog portfolios. Buyers are unbundling after-sales technical support from component pricing, negotiating multi-year framework agreements with dedicated field application engineering coverage. This pattern is most visible in German and Japanese automotive supply chains where platform standardization drives volume concentration.
Liner Regulators Market Segmentation
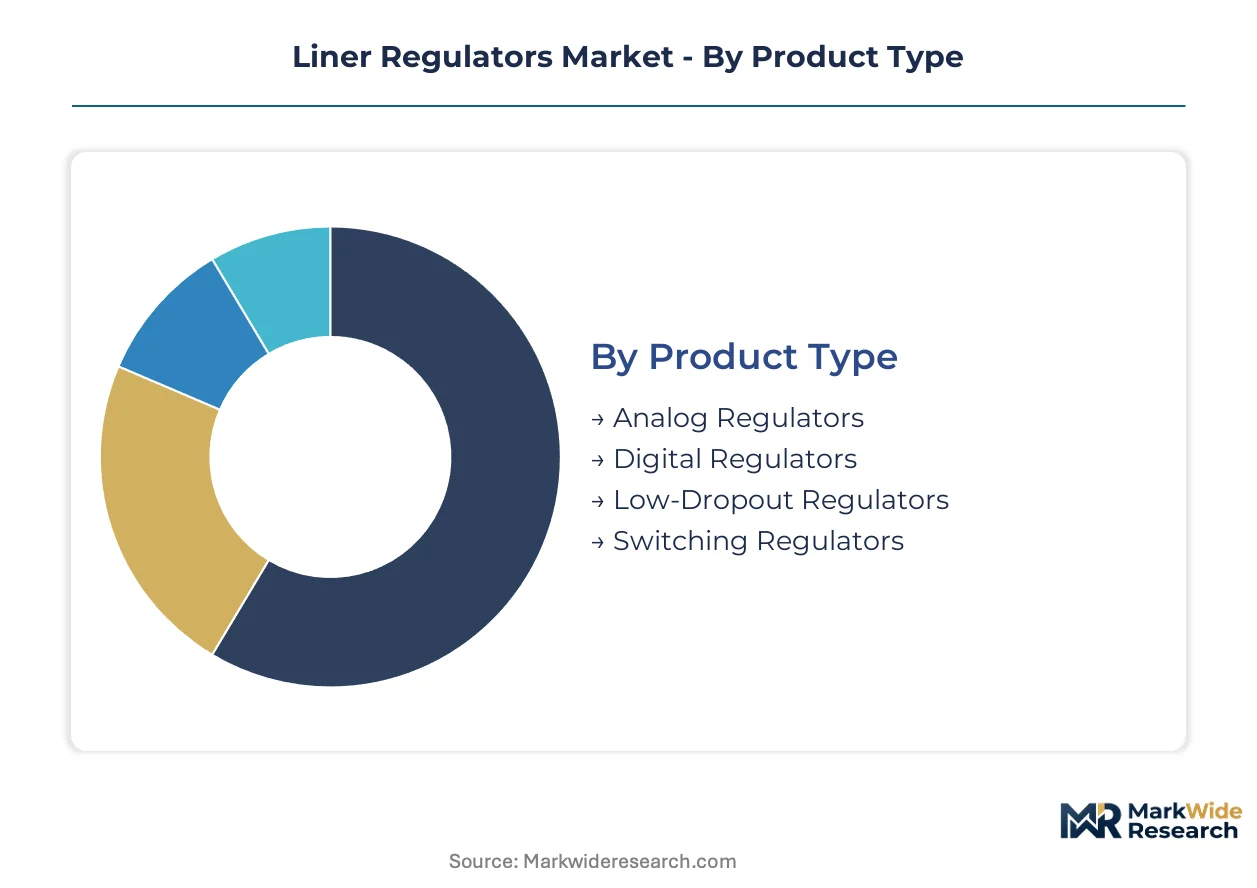
Linear regulator segmentation reveals how integration depth varies across power management architectures. Standalone discrete devices compete against embedded functional blocks within larger ICs, reshaping supplier economics and design-in requirements across electronics manufacturing.
Product Type:
Integration depth stratifies sharply here: discrete LDOs serve as standalone voltage conditioning elements, while digital and analog regulators increasingly embed into multi-output power management ICs.
- Low-Dropout Regulators:These devices maintain regulation with minimal headroom voltage between input and output rails, typically achieving dropout below 300mV at rated current. Automotive battery management systems in Germany and China pull the strongest procurement volumes as electrified platforms constrain available voltage margins.
- Digital Regulators:Firmware-configurable output voltage with dynamic scaling capability enables real-time power optimization in compute-intensive subsystems. Data processing units and AI accelerators in Taiwan and South Korea fabrication clusters are adopting these devices fastest for workload-adaptive supply rails.
- Analog Regulators:Mature voltage reference designs with fixed outputs sustain volume in cost-sensitive consumer electronics where programmability adds unnecessary BOM cost.
- Switching Regulators:Buck and boost topologies achieve higher efficiency but introduce ripple that requires downstream linear post-regulation in noise-sensitive signal chains.
Low-dropout regulators lead volumes today; digital regulators are gaining share fastest.
End User:
Application environments dictate thermal constraints, noise budgets, and qualification rigor, segmenting demand across radically different procurement specifications.
- Automotive Industry:AEC-Q100 qualification mandates temperature cycling, latch-up immunity, and extended operational ranges from minus 40 to 150 degrees Celsius. Battery management systems and advanced driver-assistance modules in German and Chinese OEM supply chains are absorbing precision LDOs with sub-1% load regulation.
- Industrial Automation:Programmable logic controllers and sensor interfaces require wide input voltage tolerance and robust electromagnetic compatibility per IEC 61000 standards. European factory automation retrofits under EU Ecodesign Directive efficiency mandates are accelerating replacement cycles in motor drive and process control electronics.
- Consumer Electronics:Smartphones, tablets, and wearables prioritize quiescent current minimization for battery life extension over absolute precision.
- Telecommunications:Base station and optical transport equipment demand ultra-low noise figures for RF signal integrity in 5G and fiber-optic subsystems.
Automotive procurement commands premium pricing tiers; industrial automation shows steepest expansion trajectory.
Technology:
Process node selection and circuit topology determine which technology layers dominate specific voltage-current operating envelopes.
- Linear Technology:Bipolar-CMOS-DMOS process integration enables high-voltage tolerance with precision analog performance. Taiwan and South Korean foundries concentrate advanced BCD capacity that supports integrated LDO-plus-supervisor devices reducing external component counts.
- Power Management ICs:Multi-rail consolidation embeds linear regulators alongside DC-DC converters, battery chargers, and sequencing logic in single-die or multi-chip modules. Automotive tier-one suppliers in Japan and Germany are adopting these aggressively to compress PCB area in body electronics.
- Switching Technology:Synchronous rectification and advanced control algorithms achieve 95-plus percent efficiency in thermally constrained enclosures.
- Voltage References:Precision bandgap designs provide stable bias points for data converters and sensor signal conditioning in medical and test equipment.
Power management ICs lead integration trends; linear technology sustains discrete volume in specialized applications.
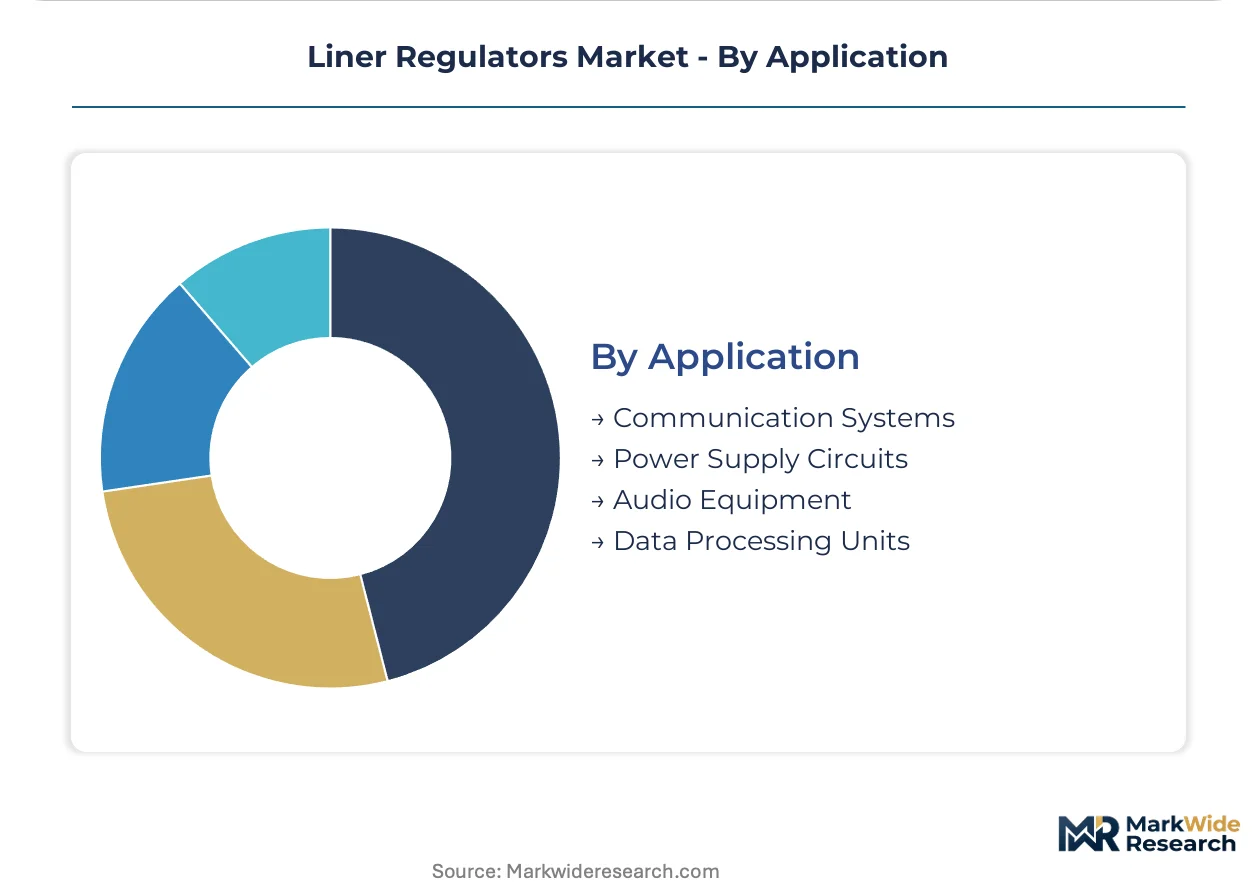
Application:
Signal integrity requirements and load transient characteristics segment applications across noise sensitivity and dynamic response specifications.
- Data Processing Units:Microprocessors, GPUs, and AI accelerators impose severe load step demands with millisecond-scale current transitions from idle to peak. Dynamic voltage scaling enabled by digital LDOs in Taiwan semiconductor clusters allows frequency-voltage coordination that minimizes energy per computation.
- Audio Equipment:High-fidelity amplifiers and professional recording interfaces demand sub-microvolt output noise to prevent audible artifacts in sensitive preamplification stages. ROHM Semiconductor and Analog Devices compete intensely for design wins in Japan and European professional audio OEMs.
- Communication Systems:RF transceivers and baseband processors require clean supply rails to maintain modulation accuracy and spurious emission compliance.
- Power Supply Circuits:Post-regulation stages clean switching ripple before delivery to analog subsystems in industrial and medical equipment.
Data processing units drive fastest technology turnover; communication systems sustain largest unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Linear regulator technology originated in Silicon Valley during the 1960s analog semiconductor boom, with precision voltage regulation expertise later migrating to German automotive electronics clusters and East Asian fabrication centers. This historical diffusion pattern explains today's geographic concentration of design-in capabilities and high-volume manufacturing.
United States
Medical device OEMs in Minnesota and Massachusetts drive procurement of ultra-low-noise LDOs for patient-connected diagnostics. FDA electromagnetic compatibility requirements constrain supplier qualification to AEC-Q100 and IEC 60601 dual-certified portfolios. Austin and Phoenix host expanding analog design centers serving defense and aerospace subsystems.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg absorb precision regulators for battery management systems in electrified platforms. EU Ecodesign Directive efficiency mandates accelerate replacement cycles in industrial automation controllers. Stuttgart and Munich clusters concentrate system-level integration expertise for multi-chip power modules.
China
Domestic EV manufacturers in Shenzhen and Shanghai pull high-volume LDO procurement for platform-standardized battery electronics. MIIT efficiency certifications and GB standards tighten standby power limits for imported power management ICs. Yangtze River Delta fabrication clusters enable integrated LDO-plus-supervisor devices reducing BOM complexity.
South Korea
Memory and display semiconductor manufacturers in Gyeonggi Province demand digital regulators with dynamic voltage scaling for process node migration. MFDS medical device regulations shape selection criteria for diagnostic imaging subsystems exported to OECD markets. Seoul Capital Area anchors BCD process development for sub-300mV dropout architectures.
Taiwan
Foundry capacity concentration in Hsinchu Science Park enables advanced BCD integration for automotive-qualified multi-output PMICs. TSMC and UMC process nodes support LDO embedding alongside DC-DC and battery management functions. Tainan and Taichung clusters specialize in cost-optimized discrete regulators for consumer electronics contract manufacturers.
Liner Regulators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification depth and analog portfolio breadth. The vendor base stratifies into three tiers: broad-line analog IDMs with automotive certification pipelines, precision specialists targeting medical and audio subsystems, and regional fabless competitors serving cost-optimized consumer electronics. Consolidation pressure intensifies as automotive OEMs reduce approved vendor lists to suppliers with multi-technology coverage. Dominant competitive moves include strategic partnerships for BCD process access and geographic expansion into India PLI scheme zones.
Among broad-line analog IDMs, Texas Instruments, Analog Devices, and Infineon Technologies occupy positions spanning automotive, industrial, and medical qualification tiers. These companies exemplify the integrated portfolio archetype where linear regulators anchor multi-chip module strategies. Precision specialists such as ROHM Semiconductor represent the noise-optimized segment serving audio and RF subsystem designers. The competitive dynamic centers on qualification timeline compression and field application engineering coverage rather than discrete product specifications alone.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| onsemi |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies |
| Microchip Technology |
| Renesas Electronics |
| ROHM Semiconductor |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement consolidation in Germany and China is forcing linear regulator suppliers to absorb qualification cost burdens upfront, compressing margins on standard-grade devices while amplifying pricing power for AEC-Q100 certified portfolios. This demand-side pressure cascades into foundry allocation priorities at Taiwan Semiconductor Manufacturing and United Microelectronics, where automotive process slots command premium wafer pricing against consumer-grade alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates linear regulator transactions, with AEC-Q100 automotive certification and sub-300mV dropout performance serving as primary price differentiation drivers. Cost compression in economy-tier discrete LDOs is intensifying because Chinese domestic suppliers are expanding 200mm fab capacity for white goods and consumer electronics. Industrial automation buyers in Europe show least price sensitivity due to EU Ecodesign Directive compliance mandates, while smartphone contract manufacturers in Tainan cluster exhibit highest sensitivity to per-unit component costs.
Supply Chain Analysis
AEC-Q100 and IEC 60601 qualification gating concentrates qualified supply among established IDMs with captive BCD process development, creating structural barriers for fabless competitors seeking automotive and medical entry. Manufacturing gravity centers on Taiwan, South Korea, and Germany, with advanced BCD integration drawing from 300mm analog-grade silicon wafers, gold wire bonding materials, and automotive-qualified mold compounds. Single-source vulnerability persists in 300mm wafer supply from Taiwan foundries, where allocation priorities favor high-margin PMIC integration over discrete regulators. Distribution runs through authorized distributors with field application engineering support for design-in intensive automotive and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme incentives for semiconductor assembly and testing offer 15-20% cost advantage against East Asian fabrication clusters, while EU Ecodesign Directive compliance costs in Europe sustain premium pricing tiers unavailable in unregulated markets.
For Market Incumbents: Cement automotive qualification pipeline dominance by expanding AEC-Q100 process development at Taiwan foundries, while backward integration into BCD process IP insulates against analog design expertise scarcity that threatens fabless competitor scaling. Synchronous buck converter substitution above 500mA loads demands defensive positioning through multi-chip module bundling that anchors linear regulators within broader power management portfolios. For New Entrants and Emerging Players: India's PLI scheme incentives open a window for domestic qualification support infrastructure serving contract manufacturers in Noida and Bengaluru, bypassing entrenched East Asian supply relationships. Target medical device subsystems requiring FDA electromagnetic compatibility and IEC 60601 dual certification, where ultra-low-noise LDO demand outpaces established supplier capacity. Pursue foundry partnerships with Tower Semiconductor or X-Fab for specialty BCD access rather than competing at commodity consumer electronics tiers. For Investors and Strategic Acquirers: Asymmetric upside sits with precision analog specialists holding dual automotive-medical certification portfolios, where qualification timeline compression creates scarcity value against broad-line IDM commoditization. Five-to-ten year viability hinges on BCD process node access and field application engineering density in German and Japanese automotive supply chains. Watch for MIIT efficiency certification tightening in China as inflection indicator signaling import substitution acceleration or partnership requirements for foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chip Module Integration | Texas Instruments and Infineon anchor automotive body electronics consolidation, reducing PCB area for tier-one suppliers. |
| BCD Process Partnership | ROHM Semiconductor secures sub-300mV dropout architectures through foundry collaboration with TSMC automotive nodes. |
| Medical Certification Dual-Track | Analog Devices pursues simultaneous FDA and IEC 60601 qualification for diagnostic imaging LDO design wins. |
| India PLI Zone Establishment | STMicroelectronics and onsemi localize assembly and testing to capture domestic OEM procurement under scheme incentives. |
| Digital LDO Firmware Development | Renesas Electronics invests dynamic voltage scaling IP for AI accelerator power management in Taiwan fabrication clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automotive tier-one procurement managers, analog IC design directors at established IDMs, field application engineers at authorized distributors, and regulatory affairs specialists at medical device OEMs with secondary validation against SEC 10-K filings, AEC-Q100 qualification databases, EU Ecodesign Directive implementation reports, and China MIIT efficiency certification registries. Bottom-up semiconductor unit shipment estimates and top-down power management IC market allocations were cross-referenced for triangulation.
Segment-weighting applied product type stratification across low-dropout, digital, and analog regulator categories, end-user differentiation among automotive, industrial, consumer, and medical applications, technology layering between discrete linear and integrated PMIC architectures, and geographic production clustering across Taiwan, South Korea, Germany, China, and the United States. CAGRs were derived from shipment volume trajectories and average selling price evolution across the projection horizon, with semiconductor fabrication capacity expansion schedules and regional regulatory implementation timelines serving as key forecast inputs.
Revisions become necessary when AEC-Q100 qualification timeline extensions, Taiwan foundry allocation disruptions, or REACH substance restriction amendments materialize beyond modeled assumptions. Forecasts reflect documented assumptions regarding electrification platform proliferation rates and efficiency mandate enforcement intensity. A model refresh is warranted upon material change in China GB standards implementation or India PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Railway Emergency Valves Market
Valves
North America Butterfly Valve Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Pinch Valve Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Cryogenic Valve Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Reciprocating Compressor Components Market
Valves
Fluid Transfer Solutions Market
Valves
HVAC Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Backflow Preventers Market
Valves
Safety Valve Market
Valves
North America Industrial Valves Market
Valves
Pressure Gauge Market
Valves
Global Gate Valve Market