
 Solar Chimney Market | 2026-2036
Solar Chimney Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Chimney Market Intelligence
Performance efficiency for large-scale electricity generation is decoupling from the cost-driven designs used in residential ventilation systems. EnviroMission Limited specializes in developing massive, utility-scale power plant concepts designed for maximum electrical output. In contrast, Solarventi Ltd competes by offering modular, pre-fabricated systems for building-integrated ventilation and thermal regulation. Abengoa Solar leverages its extensive engineering expertise to pursue large construction contracts for diverse solar thermal projects, including chimney-based designs.
A solar chimney is a renewable energy technology using solar radiation to heat air within a ground-level collector. This heated, less dense air rises through a tall central tower, creating a consistent updraft. This airflow can passively ventilate a building or actively drive turbines for electricity generation. The market's construction material segment shows a clear divide; concrete and steel dominate industrial solar chimneys, while polycarbonate and glass are preferred for smaller commercial and residential applications.
Product standards are influenced by frameworks like the EU's CE marking for construction components and specific GB standards in China. In the United States, incentives under policies such as the Inflation Reduction Act (IRA) shape investment decisions for renewable energy projects. Navigating the complex trade-offs between high-capital cost concrete structures and lower-cost, shorter-lifespan steel or composite designs remains a central challenge for project developers.
Market Dynamics
The primary structural force shaping the solar chimney market is the divergence between two distinct application paths: massive, capital-intensive power plants for electricity generation and smaller, cost-sensitive systems for building ventilation and agricultural drying, a split influencing all technology and material choices.
Growth Catalysts
- EU Green Deal Mandates:Building renovation waves promoted under the EU Green Deal encourage the integration of passive ventilation and heating systems, creating direct demand for residential and commercial solar chimney designs compliant with CE marking.
- Agricultural Sector Demand:The need for low-cost, off-grid crop preservation methods in sun-belt countries drives adoption for agricultural drying applications, offering a reliable alternative to fossil fuel-based or electrically powered dryers.
- Utility-Scale Projects:A push for large-scale renewable energy sources supports development of major solar chimney power plants, with project concentration in high-insolation regions like Spain and Australia for grid-scale electricity.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for constructing large-scale towers, particularly those using concrete and steel, presents a major financial barrier for utility-grade electricity generation projects.
- Geographic and Climatic Dependency:A solar chimney's power output and efficiency are fundamentally tied to consistent, high levels of solar radiation, restricting its economic viability to specific sun-belt geographies.
- Substitution from HVAC Systems:In the building ventilation segment, conventional powered HVAC systems and alternative passive designs remain a strong substitute, limiting adoption in markets without specific green building incentives.
Strategic Opportunities
- Hybrid System Development:Designing integrated facilities that combine electricity generation with secondary functions, such as process heat for industry or powering water desalination plants, creates new value propositions and revenue streams.
- Modular Systems for Rural Electrification:Deploying smaller, modular, and lower-cost solar chimney systems in underpenetrated markets across Africa and South Asia presents an opportunity to provide power for remote communities and agricultural co-ops.
- Thermal Energy Storage Integration:Combining solar chimney towers with molten salt or other thermal storage technologies enables extended operation, allowing for electricity generation or building climate control after sunset and on cloudy days.
Industry Challenges
- Standardization Gaps:A lack of universal performance and safety standards complicates international trade and project specification, forcing developers to navigate disparate regulatory frameworks like EU CE marking and China's GB standards.
- Complex Project Permitting:Securing land use rights, completing environmental impact assessments, and negotiating long-term power purchase agreements for large-scale power plants create lengthy and complex development cycles.
- Material Lifecycle Trade-Offs:Developers face a central challenge in balancing the long-term durability and low maintenance of high-cost concrete structures against the shorter lifespan and higher upkeep of lower-cost steel or composite designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Chimney Market |
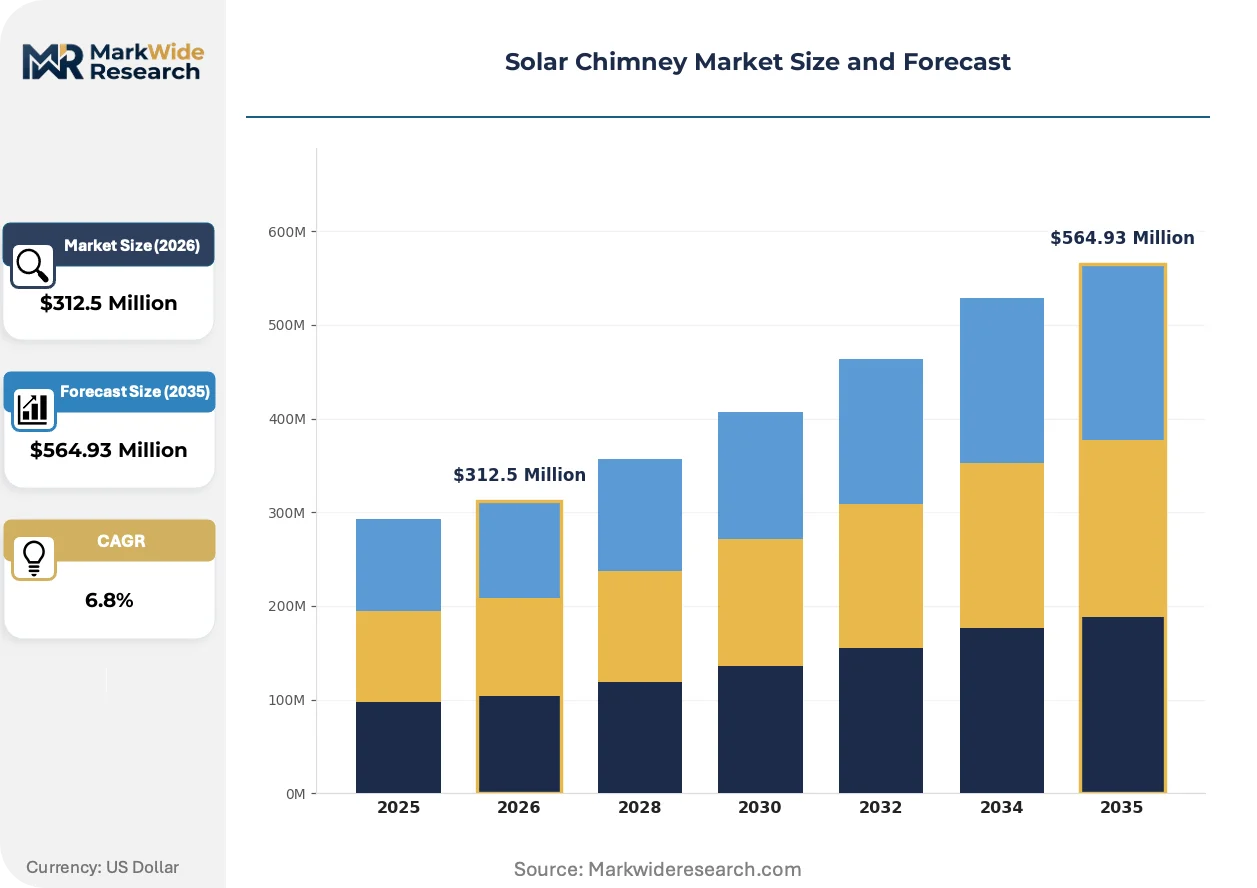
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solar Chimneys, Residential Solar Chimneys, Commercial Solar Chimneys, Hybrid Solar Chimneys Application: Electricity Generation, Ventilation Systems, Agricultural Drying, Thermal Regulation Construction Material: Concrete, Steel, Polycarbonate, Glass, Aluminum End User: Energy Producers, Building Contractors, Agricultural Firms, Green Technology Developers |
| Companies Covered | EnviroMission Limited, Solar Innovations, Helioakmi, Specflue, SolarReserve, Abengoa Solar, Frenell GmbH, Schuco International KG, Solarventi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Chimney Market Strategic Shifts & Innovations
Application-specific engineering is driving a bifurcation in the market. Designs are splitting between massive, utility-scale concepts optimized for electrical output and modular systems tailored for building-integrated thermal regulation, moving the industry away from a one-size-fits-all approach.
Modular Systems for Building Integration
Modular, pre-fabricated solar chimney systems using materials like polycarbonate and glass are designed specifically for building-integrated ventilation and passive heating. These systems are gaining traction in the commercial and residential construction sectors, particularly for retrofits in Europe seeking to meet new efficiency standards. This product evolution is decentralizing the market's focus from monolithic power plants toward distributed, building-level energy and ventilation solutions.
Incentive-Driven Project Viability
Incentive frameworks like the Inflation Reduction Act (IRA) in the United States are altering the financial landscape for renewable energy. The policy's tax credits substantially reduce the economic risk associated with high-capital technologies, including large-scale solar chimney power plants. Consequently, the utility-scale electricity generation segment is seeing renewed interest from developers re-evaluating project feasibility in the U.S. market.
Shift Toward Turnkey EPC Contracts
A notable shift in demand is occurring as large project owners move away from simple component procurement. They now favor comprehensive Engineering, Procurement, and Construction (EPC) contracts for complex solar thermal installations. This dynamic displaces specialized component suppliers, concentrating power with large engineering firms that can manage the entire project lifecycle. This pattern is most visible in the utility-scale sector in Spain and Australia.
Solar Chimney Market Segmentation
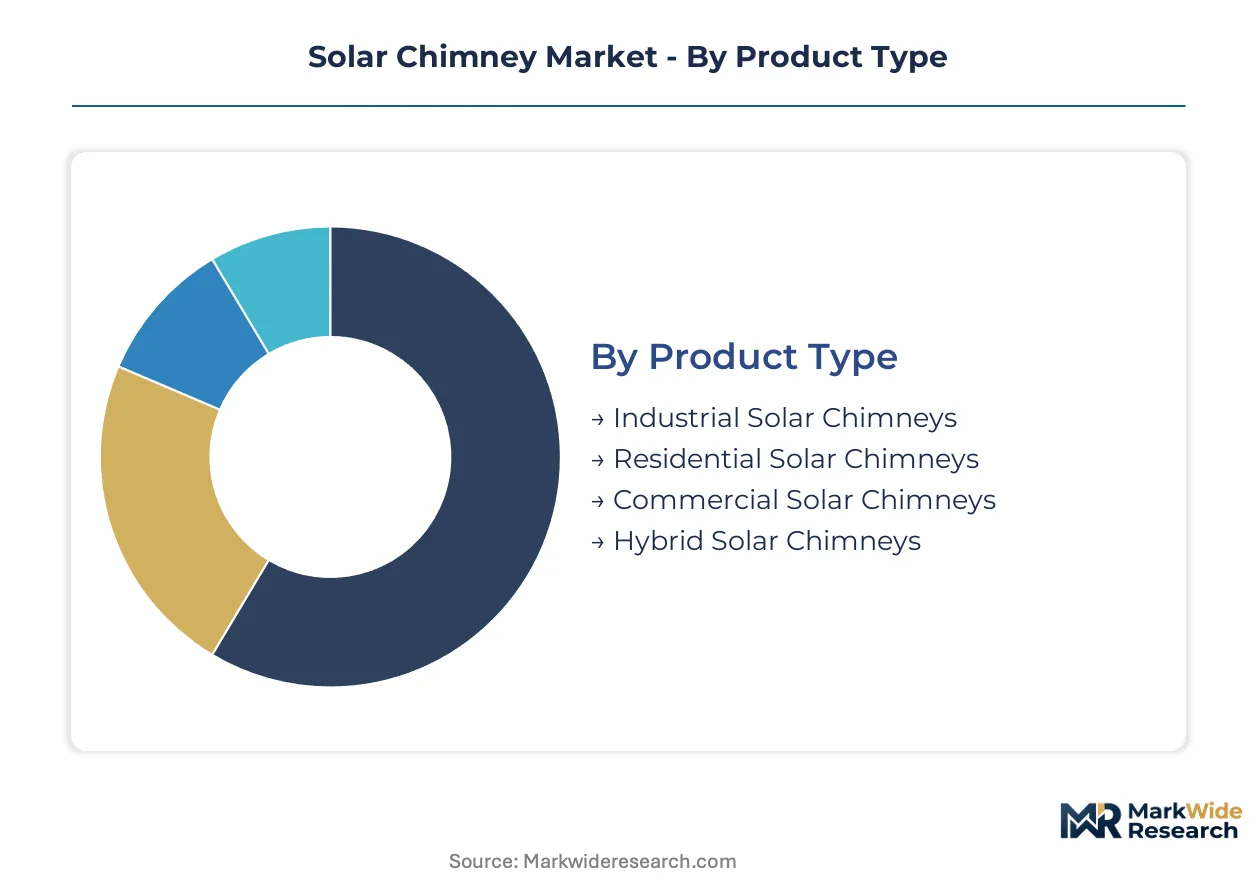
The solar chimney market's segmentation highlights the diverse technological approaches and end-use requirements driving its expansion. Understanding these distinct segments allows developers to tailor solutions, from large-scale power generation to building-integrated thermal systems. This differentiation is critical for strategic investment and product development within this evolving renewable energy sector.
Product Type:
The product type segmentation reveals a clear distinction in capital expenditure, with some designs requiring substantial upfront investment for large-scale energy projects.
- Industrial Solar Chimneys:These massive structures are typically integrated with power plants, featuring tall towers and expansive collectors designed for utility-scale output. Demand concentrates in sun-belt countries like Spain and Australia for grid-scale electricity generation, driven by utility-scale renewable energy mandates.
- Hybrid Solar Chimneys:Hybrid systems combine solar chimney principles with other energy sources, such as biomass or geothermal, to ensure consistent power output and extended operation. Strategic opportunities exist in regions with variable solar insolation or for industrial applications requiring continuous process heat, creating new value propositions.
- Residential Solar Chimneys:Smaller, often building-integrated systems provide passive ventilation and heating for individual homes and small-scale applications.
- Commercial Solar Chimneys:These systems are designed for larger commercial buildings, offering ventilation and thermal regulation for offices or public spaces.
Industrial Solar Chimneys absorb the bulk of installed capacity; Hybrid Solar Chimneys are expanding most quickly.
Application:
The application segmentation delineates the primary functions and economic drivers for solar chimney deployment across various sectors.
- Electricity Generation:This application involves using the consistent updraft within the chimney to drive turbines, converting thermal energy into electrical power for grid supply. Large-scale projects concentrate in high-insolation regions for grid-scale supply, driven by policies like the Inflation Reduction Act in the United States.
- Agricultural Drying:Solar chimneys provide a low-cost, sustainable method for preserving crops by circulating warm, dry air, reducing spoilage and extending shelf life. The need for off-grid crop preservation in sun-belt countries drives adoption, offering a reliable alternative to fossil fuel-based dryers.
- Ventilation Systems:These systems use the natural stack effect for passive building ventilation, improving indoor air quality and reducing reliance on mechanical systems.
- Thermal Regulation:Solar chimneys assist in managing building temperatures, reducing reliance on conventional heating and cooling systems for climate control.
Electricity Generation projects command the largest share of market investment, while Agricultural Drying applications demonstrate significant growth potential.
Construction Material:
The choice of construction material significantly impacts project durability, maintenance requirements, and overall capital expenditure for solar chimney installations.
- Concrete:Concrete is favored for its structural integrity, high thermal mass, and long lifespan, typically used in the construction of large industrial solar chimneys. Projects requiring maximum durability and low maintenance, particularly for utility-scale power plants, prioritize concrete in their designs.
- Polycarbonate:This lightweight, transparent polymer offers good insulation properties and is often used for collectors in smaller, modular systems due to its ease of fabrication. Modular systems for building-integrated ventilation and residential applications increasingly utilize polycarbonate due to its ease of installation.
- Steel:Steel structures provide strength and can be fabricated quickly, often used for towers in mid-sized industrial designs and support frameworks.
- Glass:Glass offers high transparency and durability for collectors, commonly found in commercial and some residential systems requiring aesthetic appeal.
- Aluminum:Aluminum provides corrosion resistance and light weight, suitable for framing and smaller structural components in various solar chimney designs.
Concrete remains the material of choice for high-durability, large-scale projects, while polycarbonate is gaining traction for its versatility in modular designs.
End User:
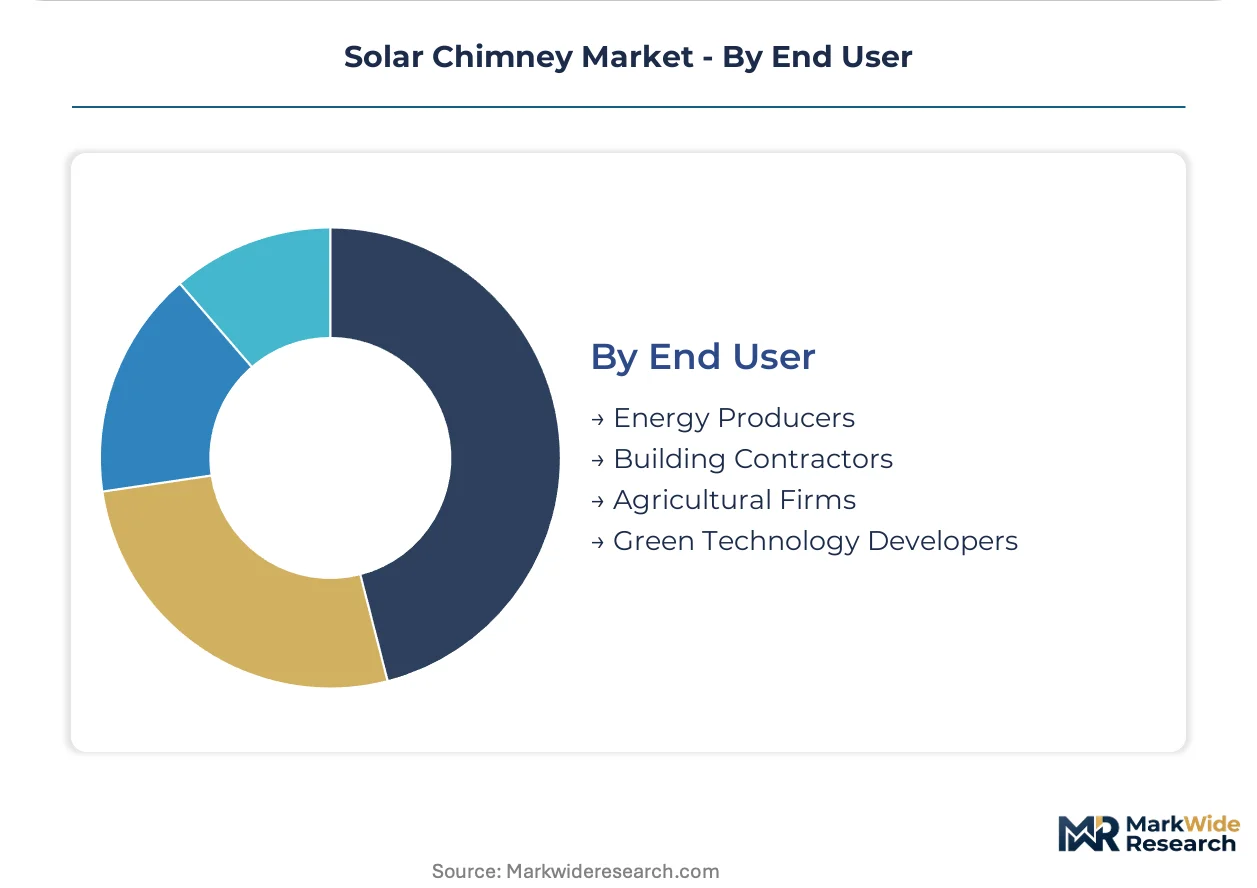
The end-user segmentation highlights the diverse customer base and the varying business models driving solar chimney adoption across different sectors.
- Energy Producers:These entities invest in utility-scale solar chimney power plants to generate and supply electricity to national grids, focusing on large-scale renewable energy portfolios. Companies like EnviroMission Limited focus on maximizing electrical output for grid integration, particularly in sun-belt regions.
- Building Contractors:Contractors integrate solar chimney systems into new constructions or existing building renovations for passive ventilation and thermal regulation solutions. EU Green Deal mandates for building renovation drive demand for building-integrated solutions compliant with CE marking.
- Agricultural Firms:These firms deploy solar chimneys for low-cost crop drying, improving preservation methods for produce and reducing post-harvest losses.
- Green Technology Developers:These developers focus on research, design, and implementation of innovative solar chimney solutions and hybrid systems for various applications.
Energy Producers represent the largest market segment by project value, with Building Contractors driving significant volume in distributed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Iberian Peninsula is concentrating significant investment for utility-scale solar chimney projects. Demand for these systems is driven by high solar insolation and a push for renewable energy integration. This region's focus on large-scale electricity generation shapes the market's initial deployment patterns.
Spain
Spain's high solar insolation drives demand for industrial solar chimneys, particularly for grid-scale electricity generation. The EU Green Deal mandates for renewable energy integration further support these large-scale projects. Andalusia, with its abundant sunshine, is a key region for developing major solar thermal power plants. Developers are pursuing extensive construction contracts in this sun-belt area.
Australia
Australian sun-belt regions require massive utility-scale power plant concepts for electrical output. The nation's renewable energy targets support the development of these large-scale solar chimney projects. Remote arid zones within Australia are seeing increasing interest for deploying these significant energy infrastructures. This concentration aligns with the push for grid-scale electricity.
United States
The United States market sees renewed interest in large-scale solar chimney power plants due to federal incentives. The Inflation Reduction Act (IRA) tax credits substantially reduce economic risk for high-capital renewable technologies. Southwestern states like California and Arizona are re-evaluating project feasibility for utility-scale electricity generation. This policy framework encourages significant investment in new solar thermal capacity.
Germany
Germany's market for solar chimneys focuses on building-integrated ventilation and passive heating systems. EU Green Deal mandates for building renovation waves encourage adoption of these energy-efficient solutions. Urban centers across Germany are seeing increased demand for retrofits compliant with CE marking, particularly for commercial and residential applications. This supports modular system deployment.
Solar Chimney Market Key Industry Players
Premium-margin players sit above commodity-margin players across the performance efficiency and capital cost spectrum. The market structure exhibits a clear bifurcation between massive utility-scale power plant developers and modular system providers for building integration. Strategic archetypes include specialized engineering firms, pre-fabricated system manufacturers, and large construction contractors. Companies are engaging in strategic partnerships for project execution and geographic expansion into high-insolation regions.
Within the utility-scale power plant development tier, EnviroMission Limited represents an archetype focused on maximizing electrical output for grid integration. Abengoa Solar exemplifies large construction firms leveraging extensive engineering expertise for diverse solar thermal projects, including chimney-based designs, often pursuing significant construction contracts. Conversely, Solarventi Ltd. occupies a position among modular, pre-fabricated system providers, targeting building-integrated ventilation and thermal regulation solutions for residential and commercial applications. These companies collectively anchor different segments of the evolving solar chimney market, from massive infrastructure to distributed systems.
| Leading Market Players |
|---|
| EnviroMission Limited |
| Solar Innovations |
| Helioakmi |
| Specflue |
| SolarReserve |
| Abengoa Solar |
| Frenell GmbH |
| Schuco International KG |
| Solarventi Ltd |
| Others |
Cost & Logistics Intelligence
Large infrastructure project financiers influence the solar chimney market by demanding long-term contract stability, which shapes material procurement and pricing for utility-scale developments. This financial structure underpins both supply chain investment and project cost management.
Pricing Analysis
Value-based pricing for solar chimney projects anchors on predicted energy output and long-term operational savings. The dominant pricing model is project-based, tailored to specific installation requirements and power purchase agreements. Price differentiation stems from construction material choices like concrete for industrial towers versus polycarbonate for modular systems, and geographic delivery costs. Agricultural firms and residential users exhibit the highest price sensitivity, facing pricing softness due to competition from conventional HVAC systems.
Supply Chain Analysis
Regional distribution centers support modular solar chimney system deployment for building integration, while large project logistics manage industrial components. Geographic supply concentration for materials like concrete and steel centers around established industrial economies, with specialized components sourced globally. The market relies on raw materials such as concrete, steel, polycarbonate, and glass. Standardization gaps pose a structural risk, complicating international trade and project specification, with distribution running through comprehensive EPC contracts for utility-scale projects and direct channels for pre-fabricated building systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar chimney market is a vertical-integration race, with developers pursuing comprehensive Engineering, Procurement, and Construction (EPC) capabilities. This allows firms to manage complex, large-scale projects from design to commissioning, controlling project costs and timelines.
For Market Incumbents:Anchor existing market share by deepening vertical integration into EPC services for utility-scale projects. Incumbents should invest in thermal energy storage technologies to mitigate the geographic and climatic dependency threat, ensuring consistent power output. Securing long-term power purchase agreements in sun-belt regions like Spain and Australia leverages established project experience. This strategy defends against new entrants targeting specific component supply.
For New Entrants and Emerging Players:Capture underpenetrated segments by offering modular, pre-fabricated solar chimney systems for building-integrated ventilation. The agricultural drying application presents a penetrable segment in sun-belt countries, leveraging low-cost crop preservation needs. Targeting rural electrification in Africa and South Asia with smaller, distributed systems offers a distinct go-to-market angle. This approach avoids direct competition with capital-intensive utility-scale projects.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized engineering firms in sun-belt countries like Spain, particularly those with strong EPC capabilities. The market exhibits long-term viability fueled by global decarbonization goals and the demand for passive building solutions. Acquiring modular system manufacturers provides access to the growing distributed energy and ventilation segment. A signal to watch is the expansion of incentive frameworks, such as further IRA tax credits, which can de-risk large-scale projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout in Sun-Belt Regions | This expands electricity generation potential in high-insolation geographies like Australia and the United States. |
| Vertical Integration into EPC Services | This allows firms like Abengoa Solar to manage complex projects from design through construction, enhancing control. |
| Modular System Product Launch | This targets the growing demand for building-integrated ventilation and thermal regulation in urban centers. |
| Thermal Energy Storage Integration | This extends operational hours for electricity generation and climate control, improving system reliability. |
| Green Building Certification Program | This ensures compliance with EU Green Deal mandates and attracts environmentally conscious building contractors. |
Research Approach
Document review covered industry reports, company filings, academic journals, and government publications, complemented by interviews with energy producers and building contractors. Additional primary insights came from agricultural firms and green technology developers. This approach combined bottom-up data collection with top-down market validation. Secondary sources included EIA data and EU Green Deal policy documents.
Volume and value projections resulted from an integrated analytical framework, combining qualitative insights with quantitative modeling. The analysis segmented the market by product type, application, construction material, and end user across the modeling period. Compound Annual Growth Rates were derived from historical trends and future market drivers. Key forecast inputs included regional solar insolation levels and government renewable energy mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to policy shifts, technological advancements, and capital expenditure fluctuations. Forecasts reflect documented assumptions regarding market dynamics and regulatory frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Point Absorber Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Solar Farm Market