
 Wind Turbine Market | 2026-2036
Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Market Analysis
Offshore-rated turbine specifications above twelve megawatts is unwinding the competitive map for original equipment manufacturers. Siemens Gamesa Renewable Energy leverages its North Sea installation track record to sustain premium positioning in floating foundation projects. Goldwind anchors its cost structure through in-house permanent magnet supply and captive blade manufacturing in Inner Mongolia.
A wind turbine converts kinetic energy from airflow into electrical power through rotor blades driving a generator, with contemporary offshore units exceeding two hundred meters in rotor diameter and requiring specialized corrosion-resistant coatings for salt-laden environments. Horizontal axis configurations dominate installed capacity while floating turbines represent the fastest-expanding application category as deeper-water sites open off Japan and Portugal. Gearless direct-drive technology commands margin premiums due to reduced maintenance intervals, though high-capacity geared designs retain share in onshore markets where capital cost sensitivity shapes procurement.
FERC interconnection standards in the United States, EU Green Deal carbon-border adjustments, and China's GB 18451 wind turbine design codes collectively determine where manufacturers can sell and what efficiency benchmarks they must meet. Japan's METI feed-in tariff revisions and South Korea's MFDS offshore certification protocols add further compliance layers for exporters. Stakeholders must weigh technology bets between scaling floating platforms against defending onshore cost positions as subsidy regimes fragment.
Market Dynamics
Offshore turbine scaling beyond twelve megawatts is compressing supplier margins while fragmenting procurement standards across coastal jurisdictions. The shift toward floating foundations in deep-water sites is rewiring manufacturing footprints and certification requirements simultaneously.
Growth Catalysts
- EU Green Deal blade recycling mandates:Material specifications for recyclable composites are pulling next-generation nacelle designs into European supply chains ahead of other regions.
- Floating foundation deployment:Water depths exceeding sixty meters off Japan and Portugal are unlocking acreage previously inaccessible to fixed-bottom installations.
- China's provincial manufacturing competition:Coastal provinces in Jiangsu and Guangdong are subsidizing blade and tower facilities to anchor supply chain clusters.
Market Restraints
- Permanent magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia and Sichuan basins, creating single-source vulnerability for direct-drive turbines.
- Specialized vessel bottlenecks:Installation jack-up fleets capable of handling fifteen-megawatt units number fewer than twenty globally, constraining project sequencing.
- Corrosion-resistant coating input costs:Epoxy formulations with salt-spray resistance above ten thousand hours require petrochemical feedstocks exposed to crude volatility.
Strategic Opportunities
- Deep-water sites off Scotland and Norway:Floating platform pilots at Hywind and Kincardine demonstrate commercial viability for water depths beyond eighty meters.
- Grid-scale storage hybridization:Co-located battery systems are smoothing intermittency for offtakers under FERC Order 841 compliance frameworks.
- Repurposing onshore towers for green hydrogen:Existing transmission infrastructure in Texas and Iowa is being retrofitted for electrolyzer feedstock supply.
Industry Challenges
- Composite technician certification gaps:Blade repair specialists with vacuum-infusion training remain scarce relative to installed base growth in the North Sea.
- Multi-jurisdiction type certification timelines:Simultaneous IEC 61400 and DNV-ST-0126 approvals add eighteen to twenty-four months to product launch cycles.
- Foundation supply chain reconfiguration:Transition from monopile to floating substructures requires steel fabricators to retool for concrete or tension-leg platform production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Market |
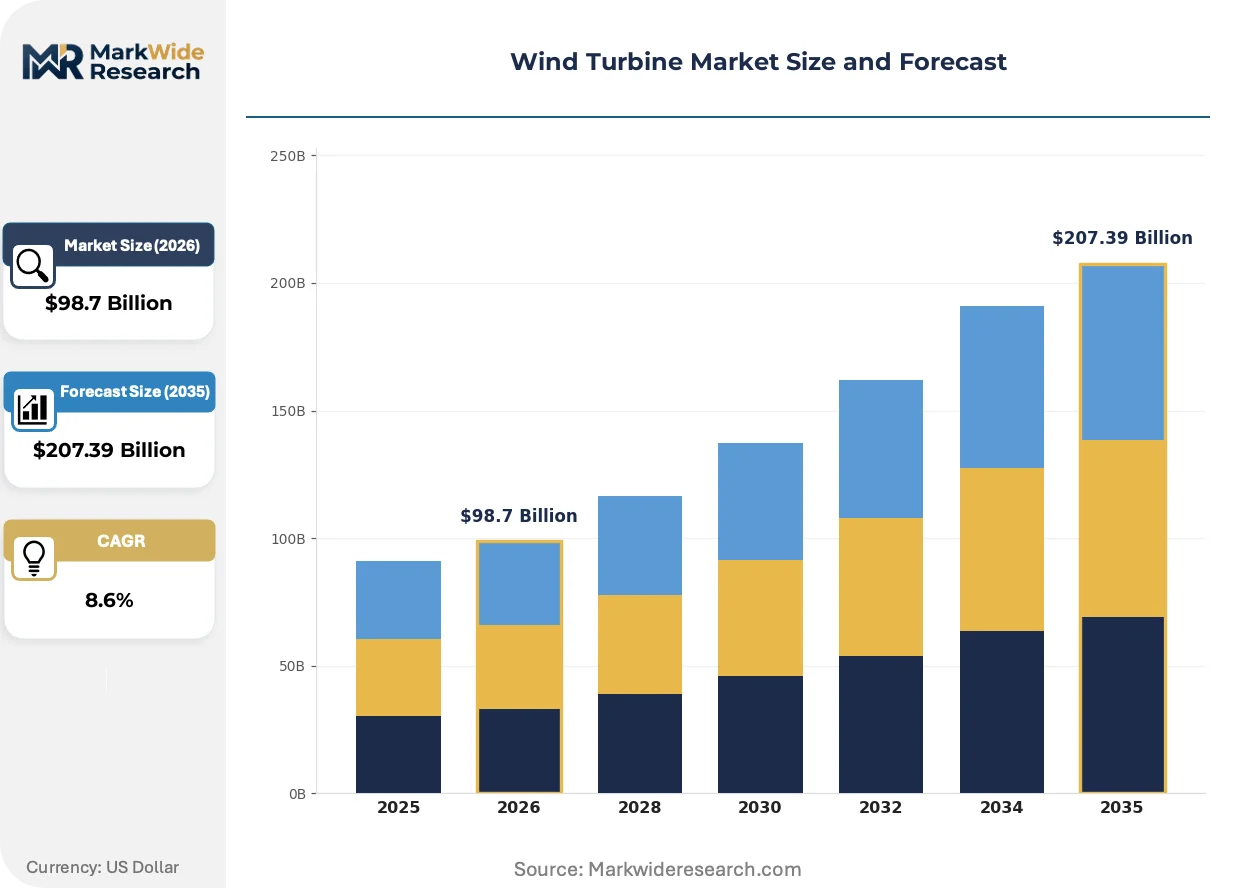
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $207.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Floating Turbines, Small Scale Application: Onshore, Offshore, Utility Scale, Distributed Generation Technology: Gearless, Direct Drive, Intermittent Operation, High Capacity End User: Utilities, Independent Power Producers, Commercial, Residential |
| Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, Goldwind, GE Vernova, ENERCON GmbH, Nordex SE, Mingyang Smart Energy, Envision Energy, Suzlon Energy Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Market Emerging Trajectories
Direct-drive generator architectures are compressing maintenance intervals while displacing geared drivetrains from premium offshore segments. Gearbox suppliers are defending onshore share through integrated condition-monitoring systems that extend service windows.
Permanent magnet synchronous generators using rare-earth-doped rotors are displacing doubly-fed induction machines in new offshore procurements above eight megawatts. European utilities with North Sea exposure are specifying direct-drive units for floating projects where crane access is constrained. The technology is displacing mid-capacity geared designs from water depths exceeding forty meters.
EU Green Deal carbon-border adjustment mechanisms are tightening embodied-carbon accounting for imported steel towers and nacelle housings. Manufacturers with European rolling-mill partnerships are securing preferential offtake terms against Asian competitors facing Scope 3 penalties. The regulation is forcing blade suppliers to document resin system chemistries through ECHA SCIP database entries.
Power purchase agreement structures are unbundling turbine supply from installation and long-term service obligations. Independent project developers in Texas and Oklahoma are procuring hardware through equipment-only tenders, then competitively bidding construction and O&M separately. The model is compressing supplier margins while expanding the addressable market for specialized installation contractors.
Wind Turbine Market Segmentation
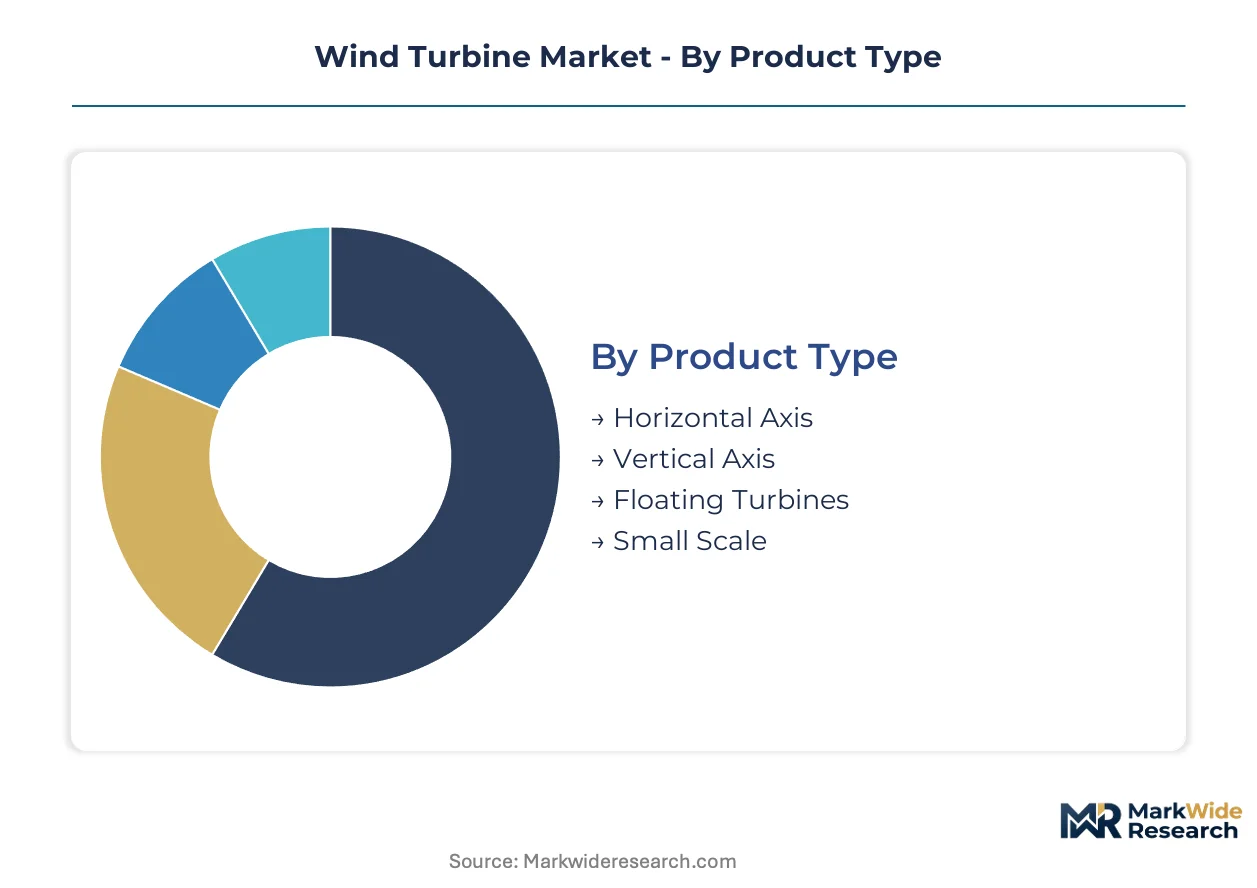
Wind turbine segmentation reveals how technology choices lock in decades-long cost structures and service footprints. Product architecture and application site characteristics together determine which suppliers can compete and where margin pools accumulate across the value chain.
Product Type:
Margin concentration follows rotor diameter scale and foundation complexity, with offshore-rated units commanding premium positioning through specialized corrosion engineering.
- Horizontal Axis:Dominant configuration featuring upwind rotor orientation with three blades attached to a horizontal shaft, typically mounted on tubular steel towers. Demand clusters in China's coastal provinces where Jiangsu and Guangdong compete for manufacturing clusters through provincial subsidy programs.
- Floating Turbines:Platforms anchored by tension-leg or semi-submersible designs enabling deployment in water depths exceeding sixty meters. Procurement from Japan's METI-backed projects and Portugal's WindFloat Atlantic installation is accelerating certification requirements for deep-water mooring systems.
- Vertical Axis:Darrieus and Savonius configurations with vertical rotor shafts, suited for urban environments with variable wind direction. Niche adoption persists in distributed applications where omnidirectional capture offsets lower efficiency coefficients.
- Small Scale:Units below one hundred kilowatts serving agricultural and remote installations, constrained by interconnection standards from FERC and equivalent national regulators.
Horizontal Axis holds installed capacity. Floating Turbines is rotating up the share rankings.
Application:
Cost tier stratification separates utility-scale procurement with twenty-year power purchase agreements from distributed generation with behind-the-meter economics.
- Offshore:Installations in marine environments requiring specialized installation jack-up vessels and salt-spray-resistant coatings above ten thousand hours. Water depths off Scotland and Norway exceeding eighty meters are validating floating platform commercial viability through Hywind and Kincardine pilots.
- Onshore:Land-based deployment across plains and ridge lines, with Texas and Iowa retrofitting existing transmission infrastructure for green hydrogen electrolyzer feedstock supply. Gearbox-integrated condition monitoring defends market share against direct-drive displacement.
- Utility Scale:Projects above fifty megawatts with centralized grid interconnection, subject to FERC Order 841 compliance frameworks for co-located battery hybridization.
- Distributed Generation:Behind-the-meter installations at commercial and industrial facilities, compressed by unbundled procurement models separating turbine supply from construction and O&M obligations.
Onshore dominates cumulative gigawatts. Offshore is expanding most quickly through deep-water site unlocking.
Technology:
Supply concentration for rare-earth permanent magnets in China's Inner Mongolia and Sichuan basins shapes which drivetrain architectures manufacturers can scale.
- Direct Drive:Gearless generator architectures with permanent magnet synchronous rotors eliminating gearbox maintenance. European utilities with North Sea exposure specify these for floating projects where crane access constraints favor reduced service intervals.
- Gearless:Synchronous generators without speed-increasing gearboxes, commanding margin premiums in offshore segments while defending onshore share through integrated electronics.
- High Capacity:Units exceeding twelve megawatts compressing supplier margins and fragmenting procurement standards across coastal jurisdictions with divergent certification timelines.
- Intermittent Operation:Grid-coupled systems with curtailment protocols and frequency response capabilities, shaped by national grid codes and GB 18451 design standards.
Direct Drive anchors offshore newbuilds. High Capacity is climbing the fastest as water depths extend.
End User:
Customer type determines contract structure complexity, with utilities favoring integrated EPC and long-term service agreements against independent developers unbundling procurement.
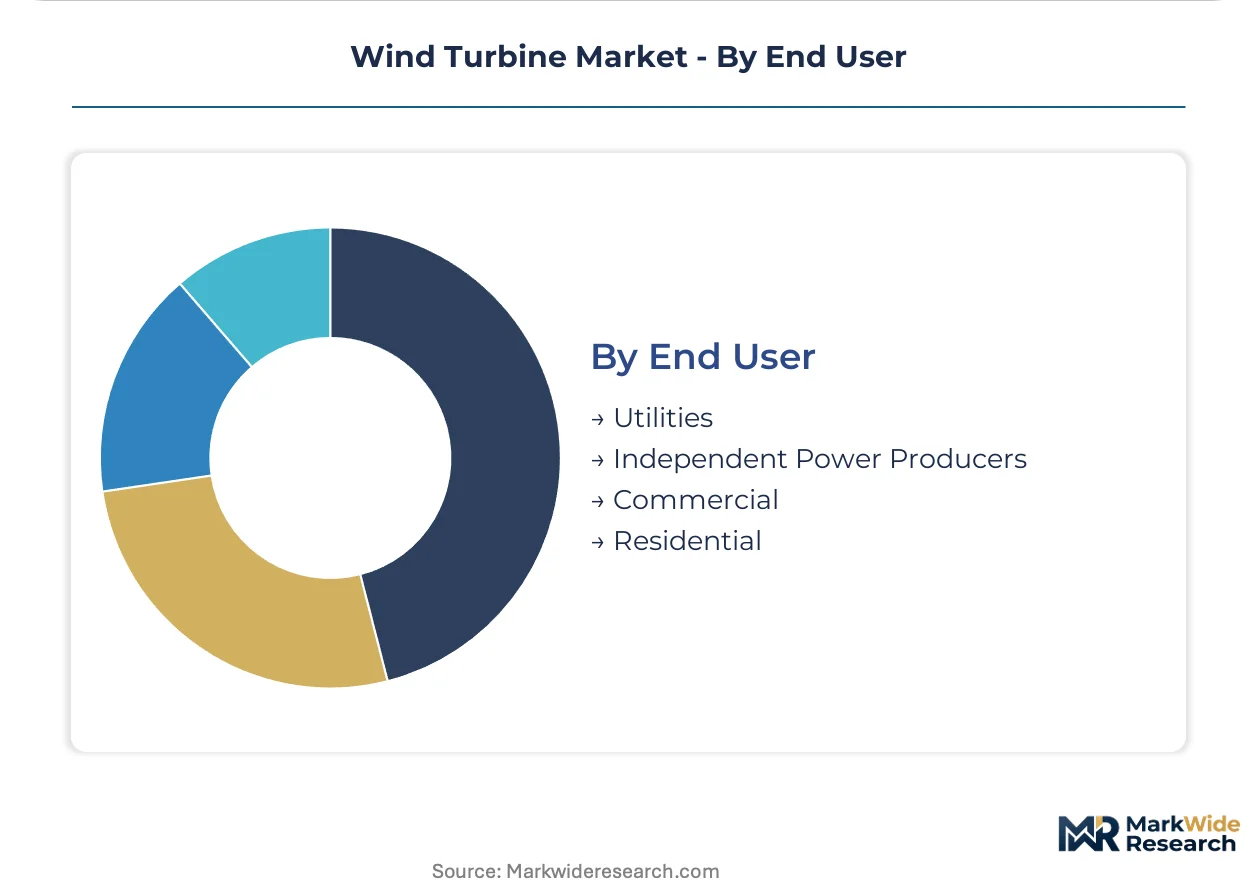
- Utilities:Vertically integrated grid operators with regulated return frameworks, expanding procurement of offshore platforms as water depths exceed fixed-bottom limits across the Americas.
- Independent Power Producers:Non-utility developers in Texas and Oklahoma competitively bidding equipment-only tenders, then separating construction and O&M through specialized contractors.
- Commercial:Corporate offtakers with renewable energy credit obligations and sustainability procurement mandates, concentrated in technology and financial services sectors.
- Residential:Single-property installations constrained by zoning ordinances and net metering policy fragmentation across state and provincial jurisdictions.
Utilities command project pipeline volume. Independent Power Producers is gaining share fastest through unbundled procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth processing clusters in China's Inner Mongolia and Sichuan basins concentrate permanent magnet supply for direct-drive architectures, while North Sea installation track records determine premium positioning in floating foundation procurement.
China
Provincial governments in Jiangsu and Guangdong compete for blade and tower manufacturing investment through subsidy programs. GB 18451 wind turbine design codes govern domestic certification requirements. Inner Mongolia hosts captive permanent magnet and blade production facilities that anchor Goldwind's cost structure.
United States
Utilities across coastal states expand procurement of offshore platforms as water depths exceed fixed-bottom limits. FERC interconnection standards and Order 841 compliance frameworks shape grid-scale storage hybridization. Texas and Iowa retrofit existing transmission infrastructure for green hydrogen electrolyzer feedstock supply.
Germany
EU Green Deal carbon-border adjustments tighten embodied-carbon accounting for imported steel towers and nacelle housings. ECHA SCIP database entries document resin system chemistries for blade suppliers. Northern ports serve as installation hubs for North Sea floating foundation projects.
Japan
METI feed-in tariff revisions accelerate floating turbine deployment in water depths exceeding sixty meters. MFDS-equivalent offshore certification protocols add compliance layers for equipment exporters. Coastal prefectures validate deep-water mooring systems through demonstration projects.
United Kingdom
Hywind and Kincardine floating platform pilots demonstrate commercial viability for water depths beyond eighty meters off Scotland. EU Green Deal blade recycling mandates pull next-generation nacelle designs into domestic supply chains. North Sea installation experience sustains premium service positioning.
Wind Turbine Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with offshore-rated specifications above twelve megawatts fragmenting procurement standards across coastal jurisdictions. The supplier base concentrates around three strategic archetypes: European incumbents with floating foundation track records, Chinese integrated manufacturers with captive magnet supply, and diversified industrial conglomerates with broad energy portfolios. Competitive dynamics center on M&A for installation vessel access and strategic partnerships for deep-water mooring system development.
Within the integrated manufacturing tier, Goldwind and Envision Energy exemplify cost leadership through upstream control over permanent magnet and blade production. Siemens Gamesa Renewable Energy occupies a position representing premium offshore specialization, leveraging North Sea installation experience for floating project procurement. Among diversified industrial players, GE Vernova anchors a portfolio-spanning approach across onshore and offshore segments.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy |
| Goldwind |
| GE Vernova |
| ENERCON GmbH |
| Nordex SE |
| Mingyang Smart Energy |
| Envision Energy |
| Suzlon Energy Limited |
| Others |
Supply Flow & Price Mechanics
Long-term power purchase agreements lock in turbine supply commitments and price visibility for offtakers across coastal jurisdictions, binding manufacturers to fixed delivery schedules while exposing them to rare-earth magnet cost volatility under China's export licensing regime.
Pricing Analysis
FERC Order 841 and EU Green Deal carbon-border adjustments dictate the pricing tier structure across utility-scale procurement. Three-tier pricing structure across premium offshore floating, standard fixed-bottom, and economy onshore configurations separates projects by water depth and certification complexity. Price differentiation hinges on IEC 61400 certification tier and bundled long-term service obligations. Cost compression in economy onshore tiers is intensifying because independent power producers unbundle construction and O&M through competitive bidding. Independent power producers in Texas and Oklahoma exhibit highest price sensitivity; European utilities with North Sea floating mandates show lowest.
Supply Chain Analysis
Port congestion at northern European installation hubs and container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for nacelle components. Permanent magnet supply concentrates in China's Inner Mongolia and Sichuan basins; blade manufacturing clusters in Jiangsu and Guangdong provinces. Rare-earth processing capacity, epoxy resin formulations, and specialized steel plate for towers constitute critical input dependencies. Single-source vulnerability for direct-drive generator magnets poses structural risk. Distribution runs through OEM-integrated EPC contractors and independent installation vessel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
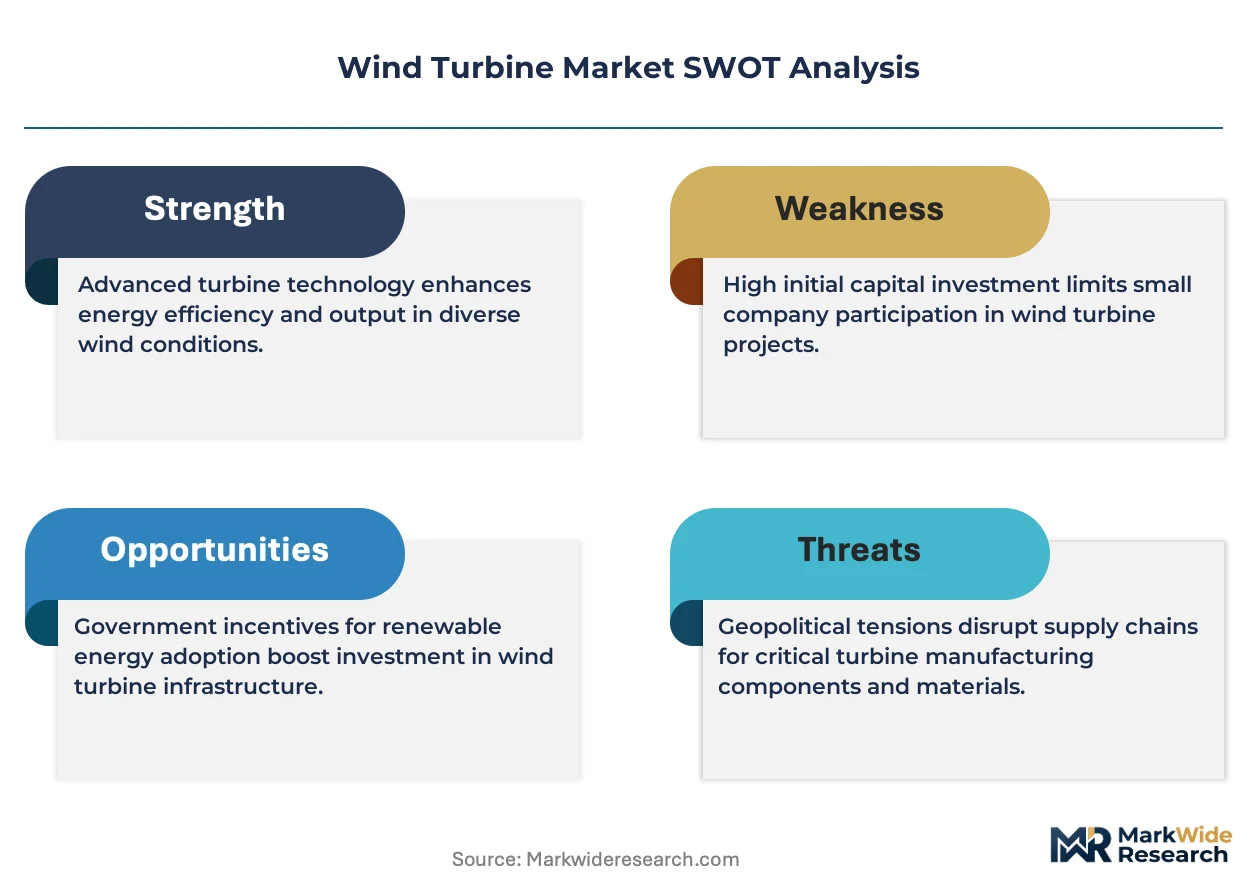
This market operates as a defensive-moat story anchored in regulatory entrenchment: FERC interconnection standards and EU Green Deal mandates create decade-long certification barriers that lock out unqualified suppliers.
For Market Incumbents: Fortify floating foundation track records through dedicated installation vessel partnerships, as jack-up fleet scarcity constrains project sequencing for competitors lacking maritime logistics control. Deepen backward integration into permanent magnet supply or secure long-term offtake from China's Inner Mongolia processors to hedge against export restriction risk. Prioritize DNV-ST-0126 certification investment to accelerate product launch cycles against eighteen-month approval timelines. For New Entrants and Emerging Players: Lead with grid-scale storage hybridization capabilities under FERC Order 841 compliance frameworks, targeting independent power producers in Texas and Oklahoma where unbundled procurement models expand addressable market for specialized contractors. Green hydrogen retrofit services for existing Iowa and Texas transmission infrastructure represent the most penetrable white-space application. Pursue strategic partnerships with European rolling mills to circumvent EU carbon-border adjustment penalties on imported steel towers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated OEMs with long-term O&M contracts attached to floating offshore installations, where crane access constraints extend maintenance intervals and lock in decade-long service relationships. Long-term viability centers on manufacturers with captive magnet supply or certified floating platform portfolios. Monitor MFDS-equivalent offshore certification protocol adoption in Japan as inflection indicator for deep-water mooring system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Installation Vessel Capacity Reservation | Secures project sequencing priority as global jack-up fleets capable of fifteen-megawatt handling number fewer than twenty units. |
| Permanent Magnet Supply Agreement | Locks in rare-earth rotor access from China's Inner Mongolia basin against export licensing volatility. |
| Floating Platform Certification Investment | Accelerates DNV-ST-0126 and IEC 61400 dual approval timelines for deep-water deployments off Scotland and Norway. |
| Blade Recycling Technology Partnership | Aligns nacelle designs with EU Green Deal composite recovery mandates through ECHA SCIP database compliance. |
| Grid-Scale Storage Hybridization | Captures FERC Order 841 co-location revenue streams for battery-turbine installations smoothing intermittency. |
Methodological Framework
Desk research of EIA generation databases, IEA renewable technology reports, FERC interconnection filings, and project development registries preceded structured interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators across the Americas, Europe, and Asia-Pacific. Primary fieldwork with original equipment manufacturer product managers and aftermarket service directors validated capacity expansion timelines and certification backlog estimates. Bottom-up project pipeline aggregation triangulated against top-down national renewable target assessments.
Variance decomposition across technology adoption curves, regulatory implementation schedules, and supply chain bottleneck resolution shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include rotor diameter scale, foundation type, drivetrain architecture, water depth category, and end-user procurement structure. CAGRs were derived from installed capacity buildout trajectories and average selling price evolution assumptions. Forecast inputs incorporated vessel fleet expansion schedules and rare-earth export quota announcements.
The analysis sits within stated boundaries; outcomes outside sustained subsidy regime continuity, unimpeded rare-earth supply flows, and installation vessel delivery timelines would require recalibration. Forecasts reflect documented assumptions regarding technology cost reduction curves and jurisdictional certification harmonization progress. Policy fragmentation, commodity price volatility, and logistics chokepoint persistence constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Wind Turbine Blades Market