
 Biogas Plant Market | 2026-2036
Biogas Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Biogas Plant Market Analysis
Municipal energy producers are restructuring procurement priorities toward landfill gas recovery and co-digestion systems. EnviTec Biogas AG leverages its engineering footprint across Central European agricultural zones. Wärtsilä Corporation anchors its position through combined heat and power integration capabilities. PlanET Biogas Global GmbH differentiates via modular plant architectures for distributed feedstock access.
Biogas plants are engineered facilities that process organic matter through anaerobic digestion or thermal conversion to produce methane-rich gas suitable for electricity generation, heat supply, or biomethane upgrading to pipeline quality, with typical digester retention times spanning 15 to 30 days and methane concentrations reaching 50 to 75 percent by volume. Anaerobic digestion occupies the dominant technology position due to proven operational economics and compatibility with varied feedstock streams. Agricultural waste and animal manure command substantial feedstock share where farming operations cluster densely. Small and medium scale installations are gaining structural momentum as distributed energy policies favor localized biogas production over centralized fossil alternatives.
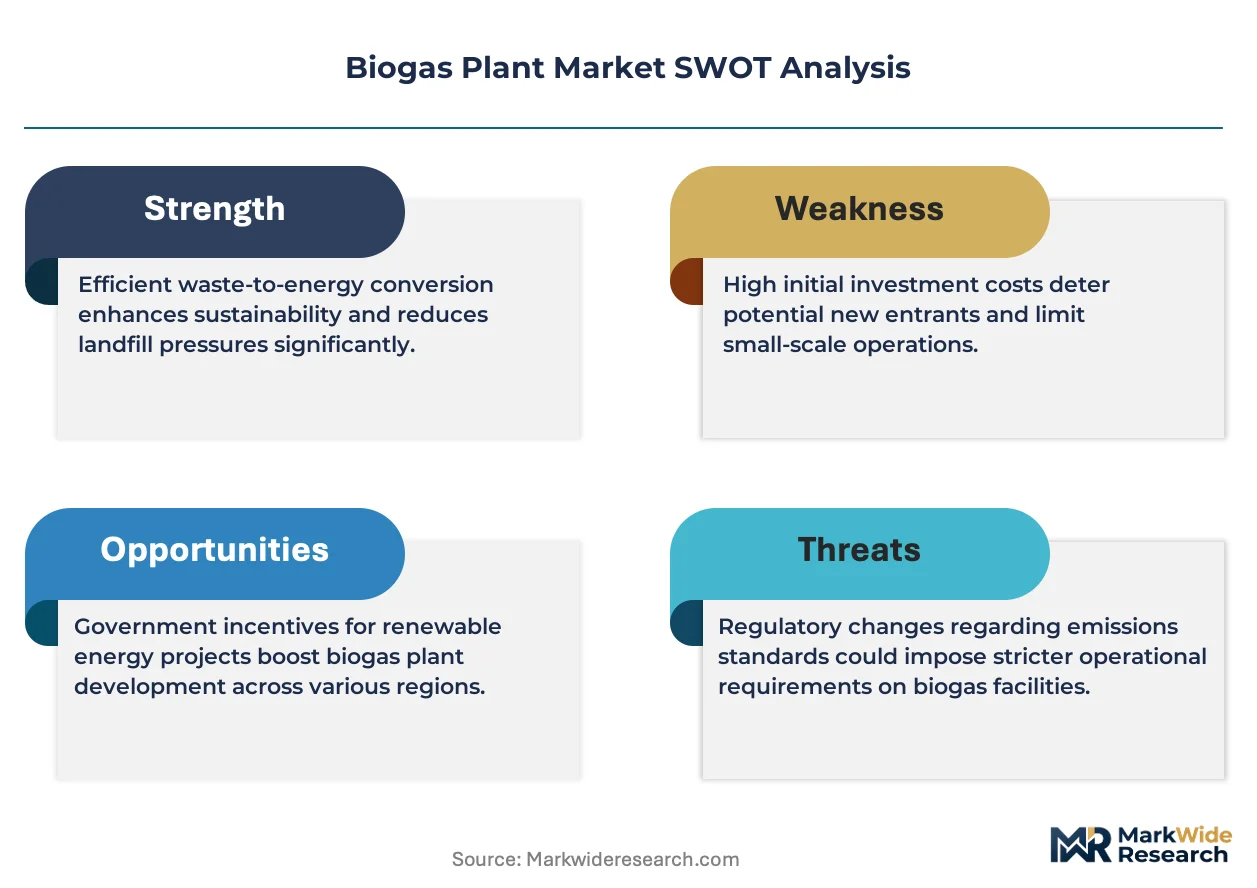
The EPA regulates biogas emissions under the Renewable Fuel Standard and Clean Air Act frameworks in the United States, while the EU Green Deal and F-Gas Regulation shape biomethane injection targets and greenhouse gas accounting methods across European member states. Germany's EEG mechanism directly influences plant revenue certainty through guaranteed feed-in tariffs. Stakeholders must monitor regulatory shifts in carbon credit eligibility and digestate handling standards to preserve project bankability across jurisdictions.
Market Dynamics
Germany's EEG feed-in tariff revisions are compressing project development timelines across Central European agricultural zones, forcing developers to lock in grid-connection permits before incentive step-downs take effect.
Growth Catalysts
- EU Green Deal biomethane targets:The European Commission's binding injection mandates are compelling municipal utilities to retrofit wastewater facilities for biogas capture and grid injection.
- Agricultural cluster density:Denmark's concentrated livestock operations generate feedstock economies that slash transport costs below break-even thresholds for small-scale digesters.
- Dry anaerobic digestion:This process variant accepts solid organic waste streams without pre-treatment, opening municipal source-separated organics as viable feedstock.
Market Restraints
- Digestate disposal costs:Nitrogen concentration limits in the EU Nitrates Directive impose spreading restrictions that add 15-20% to operating expenditures in intensive farming regions.
- Grid connection queuing:Distribution system operators in the Netherlands and Germany face 18-24 month backlogs for new biogas injection points.
- Natural gas price volatility:Unhedged exposure to TTF hub fluctuations erodes power purchase agreement economics for merchant biomethane projects.
Strategic Opportunities
- Carbon capture integration:Post-combustion CO2 separation from biogas upgrading units creates negative-emission certificates eligible for voluntary carbon markets.
- Italy's agro-energy decree:The 2023 legislative package allocates dedicated grid capacity and streamlined permitting for agricultural biogas in the Po Valley.
- Industrial heat offtake:Food processors and chemical manufacturers in Belgium are contracting long-term supply agreements to replace natural gas in thermal processes.
Industry Challenges
- Anaerobic process engineering talent:The specialized knowledge required for digester microbiology management and biogas yield optimization remains scarce outside established European markets.
- Digestate certification complexity:Cross-border recognition of organic fertilizer standards under divergent national implementations of EU Fertilizing Products Regulation creates trade barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biogas Plant Market |
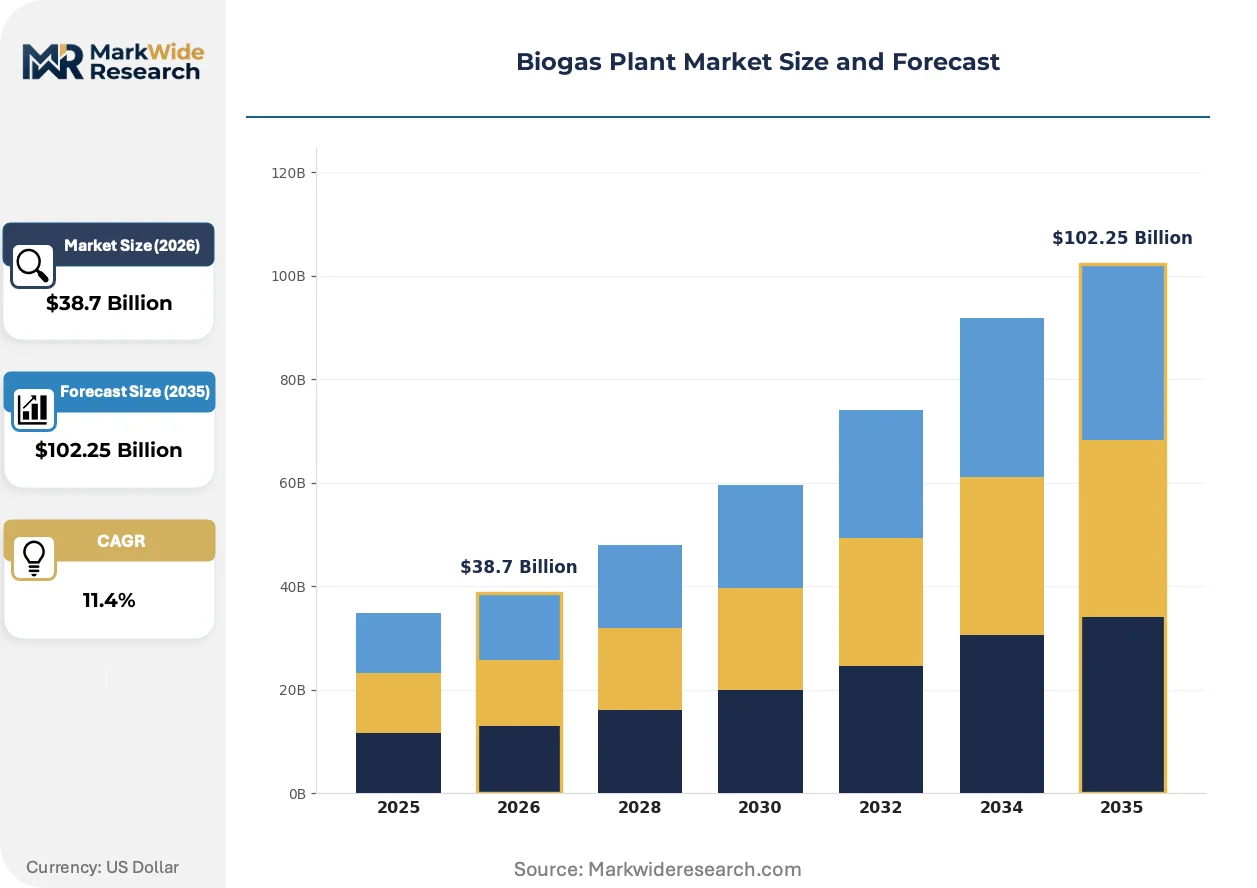
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Anaerobic Digestion, Landfill Gas Recovery, Thermal Gasification, Co-Digestion Feedstock Type: Agricultural Waste, Food Waste, Animal Manure, Energy Crops Plant Size: Small Scale, Medium Scale, Large Scale, Micro Scale End User: Agriculture, Energy Producers, Waste Management, Municipalities |
| Companies Covered | EnviTec Biogas AG, PlanET Biogas Global GmbH, Hitachi Zosen Inova AG, Wärtsilä Corporation, WELTEC BIOPOWER GmbH, Veolia Environnement S.A., Air Liquide S.A., BioConstruct GmbH, AB Energy S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biogas Plant Market Emerging Trajectories
Modular plant architectures are collapsing minimum viable scale thresholds, enabling distributed biogas production at feedstock source rather than centralized processing hubs.
Containerized dry fermentation systems are decentralizing biogas infrastructure by eliminating liquid effluent handling and reducing footprint requirements by 60% versus wet digestion. Agricultural cooperatives in northern Germany are deploying these units at individual farm level rather than shared central facilities. The shift is compressing feedstock logistics radius from 50 kilometers to under 5 kilometers, capturing methane emissions from on-farm manure storage.
The EU F-Gas Regulation's phasedown of fluorinated refrigerants is forcing biomethane upgrading plants to adopt membrane separation or pressure swing adsorption in place of energy-intensive cryogenic distillation. Equipment suppliers are engineering integrated upgrading modules that combine compression and purification in single-skid configurations. This regulatory pressure is accelerating capital refresh cycles in existing plants commissioned before 2015.
Energy-as-a-service contracting is displacing traditional equipment purchase models for industrial biogas installations. Chemical manufacturers in the Netherlands are signing 15-year heat supply agreements where developers retain asset ownership and operational risk. This structure transfers digestate management liability and carbon credit monetization to specialized operators with established offtake relationships.
Biogas Plant Market Segmentation
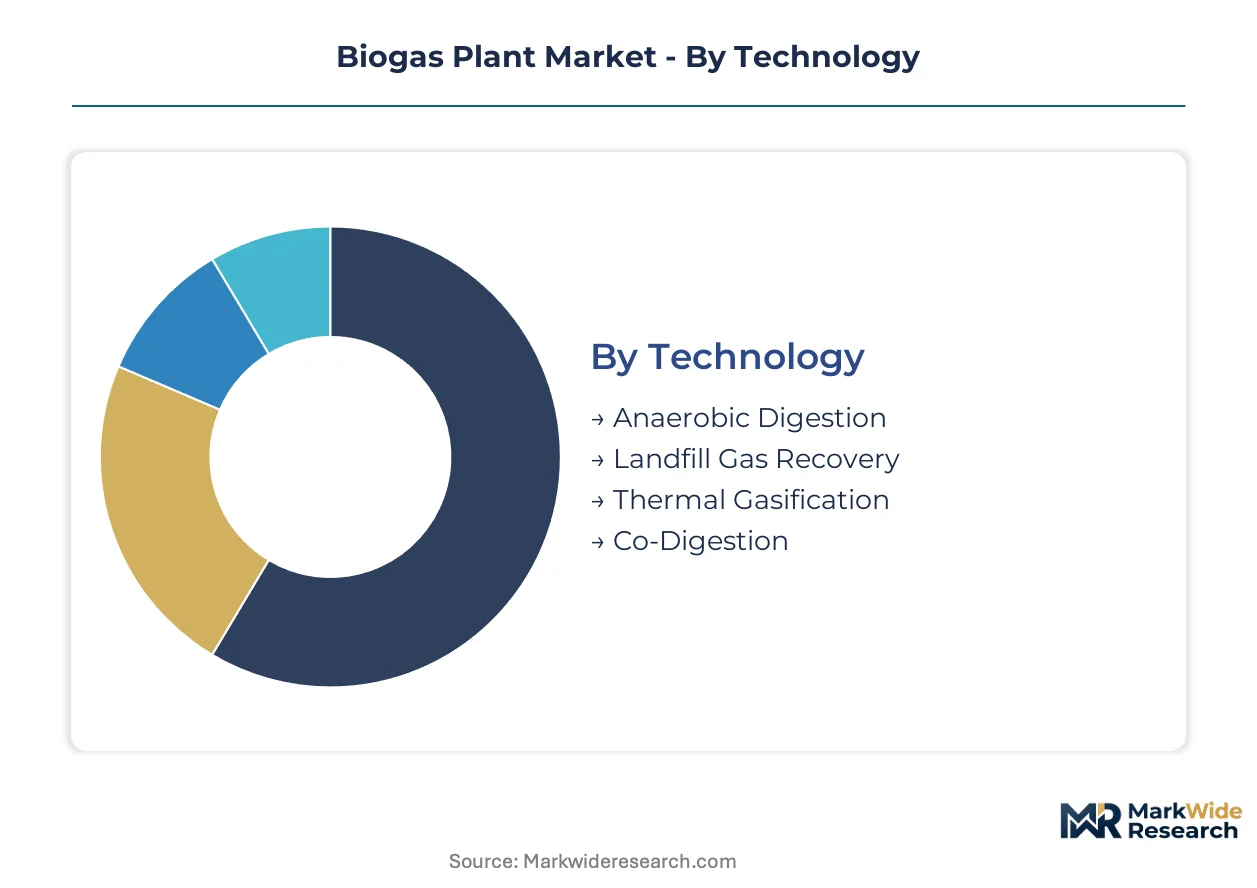
Technology and feedstock choices determine project economics across the biogas plant value chain. Plant scale and end-user configuration dictate capital deployment patterns and operational complexity. Understanding segment boundaries enables precise positioning of engineering capabilities and financing structures.
Technology:
Anaerobic digestion dominates installed capacity while thermal conversion commands premium project valuations.
- Anaerobic Digestion:Wet fermentation processes operate at mesophilic or thermophilic temperatures with 15-30 day retention periods. Germany's agricultural cooperatives favor this proven route for manure-to-energy conversion under EEG tariff structures.
- Landfill Gas Recovery:Passive collection systems extract methane from decomposing municipal waste with minimal feedstock logistics. France's landfill operators retrofit existing sites to meet EU methane reduction mandates and carbon credit eligibility.
- Thermal Gasification:High-temperature conversion of lignocellulosic biomass into synthetic gas.
- Co-Digestion:Blending multiple organic streams to optimize biogas yield and nutrient balance.
Today's leader: Anaerobic Digestion. Tomorrow's challenger: Co-Digestion.
Feedstock Type:
Volume concentration versus processing cost defines competitive positioning across organic input categories.
- Agricultural Waste:Crop residues and post-harvest biomass provide seasonal feedstock volumes with established collection infrastructure. Denmark's intensive farming regions achieve transport economies below break-even thresholds for centralized digesters.
- Animal Manure:Continuous-flow organic material with consistent moisture content and methane potential. The Netherlands' livestock clusters generate sufficient volumes to sustain multiple mid-scale plants per municipality.
- Food Waste:High-energy organic discards from commercial and industrial sources.
- Energy Crops:Dedicated agricultural production of maize silage and grass silage for biogas feedstock.
Agricultural Waste anchors current deployment. Food Waste is climbing the fastest as source-segregation mandates expand across European municipalities.
Plant Size:
Capital intensity and regulatory thresholds segment project development strategies across capacity bands.
- Small Scale:Sub-500kW electrical output installations serving single farms or small cooperatives. Italy's agro-energy decree streamlines permitting for these distributed units in the Po Valley agricultural zone.
- Medium Scale:500kW-2MW capacity range balancing feedstock aggregation costs with equipment standardization. Belgium's industrial heat offtake contracts favor this scale for food processor energy supply agreements.
- Large Scale:Multi-megawatt facilities requiring extensive feedstock logistics and grid upgrade investments.
- Micro Scale:Sub-100kW containerized units for individual farm operations.
Medium Scale captures current investment flows. Micro Scale presents the steepest expansion trajectory as modular architectures collapse minimum viable thresholds.
End User:
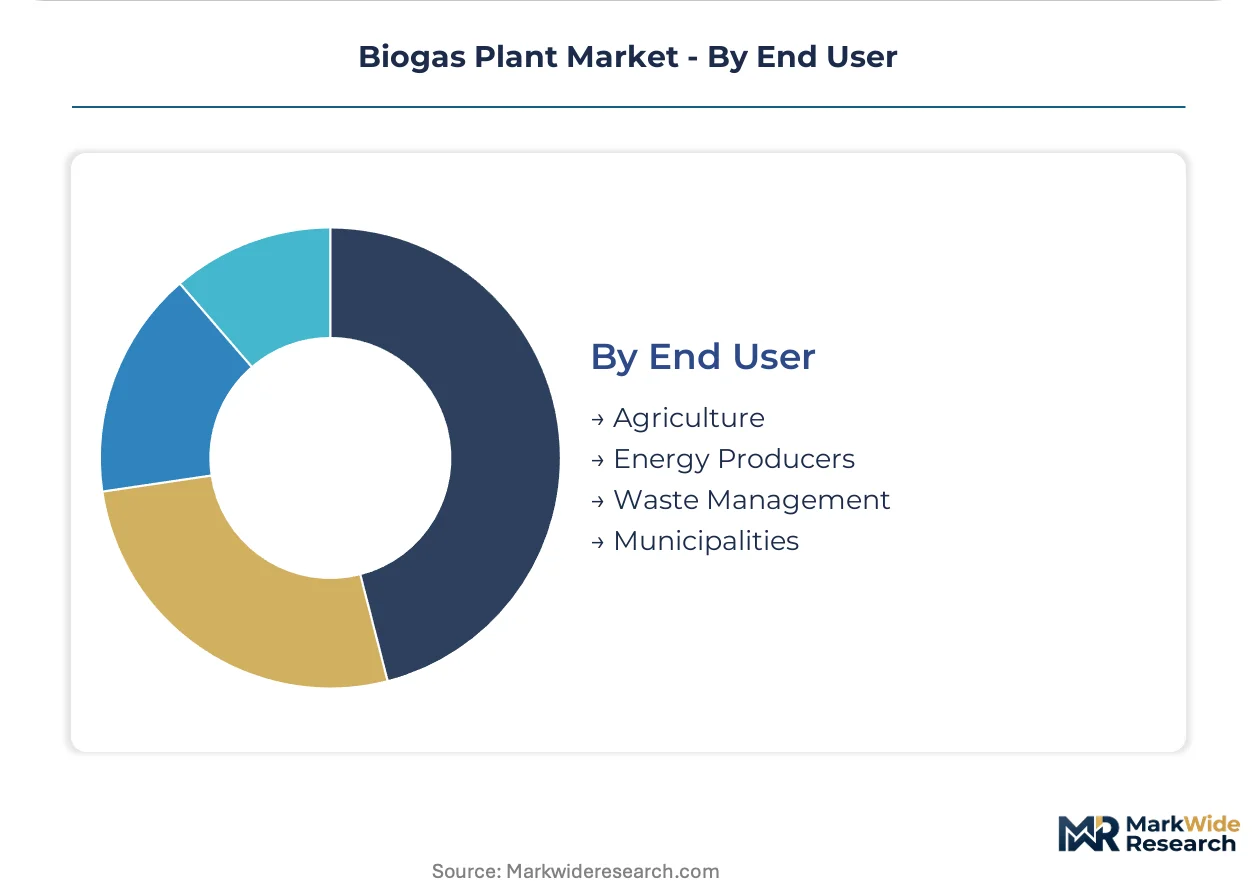
Revenue model stability varies sharply across customer categories and regulatory exposure profiles.
- Energy Producers:Grid-connected electricity generators selling under feed-in tariffs or power purchase agreements. Germany's EEG mechanism provides revenue certainty that attracts project finance for utility-scale developments.
- Municipalities:Public wastewater treatment and waste management authorities integrating biogas into circular economy frameworks. The EU Green Deal's binding biomethane targets compel these entities to retrofit anaerobic digestion capacity.
- Agriculture:Farm-level operators seeking energy self-sufficiency and digestate fertilizer value.
- Waste Management:Private and public landfill operators monetizing methane capture obligations.
Energy Producers hold dominant share. Municipalities are gaining share fastest as regulatory mandates harden across member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting biogas investment toward jurisdictions with stable incentive frameworks and streamlined permitting, compressing development timelines where feed-in tariffs remain bankable.
Germany
Agricultural cooperatives in Lower Saxony and Bavaria are accelerating digester construction ahead of EEG tariff step-downs. The federal network agency maintains grid-connection priority for biomethane injection projects meeting sustainability criteria. Brandenburg's dairy clusters host multiple mid-scale facilities capturing manure methane under revised carbon credit eligibility rules.
Denmark
Livestock density in Jutland generates feedstock economies sustaining village-scale digesters without long-haul transport. The Danish Energy Agency's biogas upgrading subsidies cover membrane separation equipment retrofits. Central Denmark Region cooperatives deploy containerized dry fermentation at individual farm level rather than shared central facilities.
Netherlands
Greenhouse horticulture operators in Westland contract biogas-derived heat under 15-year supply agreements replacing natural gas. The national climate agreement mandates 2 TWh biomethane injection by 2030 with dedicated grid capacity reservations. Gelderland's pig farming concentrations sustain co-digestion plants processing manure alongside food industry residues.
Italy
The 2023 agro-energy decree allocates streamlined permitting for sub-500kW agricultural installations in the Po Valley. Lombardy and Emilia-Romagna maize silage producers retrofit existing digesters for biomethane upgrading to meet transport fuel quotas. Veneto's dairy cooperatives cluster multiple small-scale units within 10-kilometer feedstock radii.
France
Landfill operators in Île-de-France retrofit gas collection systems to meet EU methane reduction mandates and carbon credit eligibility. The national biomethane injection target of 14 TWh by 2030 drives wastewater facility upgrades in Greater Paris. Brittany's pork production regions face digestate spreading restrictions under the Nitrates Directive, increasing operating expenditures for intensive farming operations.
Biogas Plant Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering-procurement-construction integrators dominating utility-scale developments while modular fabricators capture distributed agricultural installations. The vendor landscape organizes into three tiers: full-service EPC providers with anaerobic digestion expertise, equipment specialists focusing on upgrading and gas treatment systems, and regional integrators serving localized feedstock clusters. Consolidation pressure is intensifying as developers seek single-source accountability for complex biomethane-to-grid projects. Strategic partnerships between digester engineers and gas grid operators are displacing arm's-length equipment procurement.
Within the full-service EPC tier, EnviTec Biogas AG and Wärtsilä Corporation exemplify divergent positioning strategies, with the former anchoring agricultural zone deployment across Central Europe and the latter integrating combined heat and power capabilities into utility-scale configurations. PlanET Biogas Global GmbH occupies a position within the modular architecture segment, representing the shift toward distributed feedstock access models. These three entities collectively illustrate how competitive differentiation now hinges on project delivery structure rather than equipment specification alone.
| Leading Market Players |
|---|
| EnviTec Biogas AG |
| PlanET Biogas Global GmbH |
| Hitachi Zosen Inova AG |
| Wärtsilä Corporation |
| WELTEC BIOPOWER GmbH |
| Veolia Environnement S.A. |
| Air Liquide S.A. |
| BioConstruct GmbH |
| AB Energy S.p.A. |
| Others |
Supply Flow & Price Mechanics
Specialized anaerobic process engineers concentrated in Germany and Denmark command wage premiums that compress pricing spreads between premium-tier EPC providers and economy-tier regional fabricators. Labor-cost differentials in biogas plant construction directly determine tier boundaries as EEG tariff deadlines force developers toward faster deployment models.
Pricing Analysis
Distributor margins on upgrading equipment and gas treatment skids absorb 12-18% of project capital expenditure before EPC integrators apply their construction markup. Pricing stratifies across premium, standard, and economy tiers based on certification grade under EU sustainability criteria and after-sales service bundling. Cost compression in the standard tier is intensifying because membrane separation suppliers are consolidating procurement volumes. Municipal utilities show the highest price sensitivity due to public procurement rules, while industrial heat offtakers demonstrate the least sensitivity given long-term contract security.
Supply Chain Analysis
Freight costs for stainless-steel digester vessels and gas upgrading membranes from Germany, Italy, and the Netherlands constitute 8-12% of delivered equipment value for projects in peripheral agricultural zones. Raw material dependencies center on specialty steel grades, polymer membrane substrates, and precision compressor components. Single-source vulnerability in membrane separation technology creates concentration risk as the EU F-Gas Regulation accelerates equipment refresh cycles. Distribution runs through EPC integrators with established relationships to agricultural cooperatives and municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biogas plant market functions as a stable compounder where EU Green Deal biomethane mandates provide demand visibility that insulates against commodity price volatility.
For Market Incumbents: Hedge revenue exposure to EEG tariff step-downs by accelerating biomethane upgrading investments that qualify for carbon credit monetization. Deepen backward integration into digestate handling services to capture operating expenditure streams that competitors cannot replicate. Lock in long-term heat supply agreements with industrial offtakers before new entrants capture Belgium and Netherlands chemical manufacturing demand. For New Entrants and Emerging Players: The mid-market pricing gap between premium EPC providers and economy-tier fabricators offers entry space for modular specialists with containerized dry fermentation expertise. Target Italy's Po Valley agricultural zone where the 2023 agro-energy decree streamlines permitting for sub-500kW installations. Pursue energy-as-a-service contracting models that transfer operational risk to specialized operators while retaining asset ownership. For Investors and Strategic Acquirers: Utility-scale renewable energy developers are the most active acquirer in this space as they seek biogas-to-grid integration capabilities for portfolio diversification. The five-to-ten-year viability window favors platform acquisitions of regional EPC integrators with established agricultural cooperative relationships. Monitor carbon credit eligibility rule changes under the EU Emissions Trading System as the primary inflection indicator for project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Biomethane Upgrading Retrofit | Captures EU Green Deal injection mandates and extends plant revenue life under tightening sustainability criteria. |
| Digestate Handling Service Integration | Addresses Nitrates Directive compliance costs while creating recurring revenue streams from agricultural offtakers. |
| Industrial Heat Supply Contracting | Locks in 15-year revenue visibility with Netherlands and Belgium chemical manufacturers replacing natural gas. |
| Containerized Dry Fermentation Deployment | Collapses minimum viable scale thresholds for Denmark and northern Germany farm-level methane capture. |
| Carbon Capture Module Addition | Generates negative-emission certificates eligible for voluntary carbon markets beyond compliance obligations. |
Methodological Framework
Multiple input streams — structured interviews with EPC project developers, utility planning officers, and agricultural cooperative managers, alongside regulatory filing analysis and equipment supplier disclosures — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged digester engineering specialists, biomethane grid injection coordinators, and digestate certification auditors across Germany, Denmark, and the Netherlands. Secondary validation drew from EU ETS implementation reports, national energy agency statistics, F-Gas Regulation compliance databases, and anaerobic digestion trade association capacity surveys.
Data-stream reconciliation across technology segmentation, plant capacity tiers, feedstock categories, and end-user configurations anchored the analytical framework throughout the projection horizon. CAGRs were derived from installed capacity buildout trajectories, tariff schedule step-downs, and biomethane injection target compliance timelines. Forecast inputs incorporated EEG revision implementation pace, EU Green Deal mandate enforcement stringency, and membrane separation technology substitution rates.
The model assumes a particular technology adoption path; alternative pathways for dry anaerobic digestion containerization would alter the outlook if feedstock logistics economics shift faster than projected. Forecasts reflect assumptions about regulatory stability, carbon credit market liquidity, and agricultural commodity price relationships that could revise under policy discontinuity or trade disruption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Solar Boat Market
Renewable Energy
East Africa Renewable Energy Market