
 Tidal Turbines Market | 2026-2036
Tidal Turbines Market Size, Share, and Industry Trends Forecast 2026-2036
Tidal Turbines Market Insights
Modular platform configurations for tidal turbine deployment is hardening as the dominant procurement format among European and North American buyers. Nova Innovation Ltd anchors its market presence through integrated turbine-and-anchor systems designed for rapid installation. Andritz AG leverages its hydropower engineering heritage to compete on large-diameter horizontal axis designs with extended operational lifespans.
Tidal turbines are submerged or floating rotary devices that extract kinetic energy from tidal currents, typically featuring horizontal or vertical axis rotors with diameters ranging from 10 to 30 meters and generating capacities from 0.5 to 4 MW per unit for grid-connected electricity production. Horizontal axis configurations currently dominate installed capacity due to higher proven efficiency in bidirectional flow environments, while floating installation platforms represent the fastest-growing segment as developers target deeper water sites beyond fixed-bottom economic limits. Utility companies constitute the primary end-user category, with independent power producers gaining traction through power purchase agreements for island and coastal community supply.
The European Marine Energy Centre in Scotland, France's ANSM coastal consenting framework, and Health Canada's environmental assessment protocols collectively shape device certification timelines and site access conditions across the industry's leading development corridors. These regulatory bodies enforce specific load-testing, ecological monitoring, and grid interconnection standards that directly determine project bankability and technology qualification pathways. Stakeholders must monitor evolving marine spatial planning allocations and cumulative impact thresholds as pipeline projects compete for limited high-velocity tidal channels.
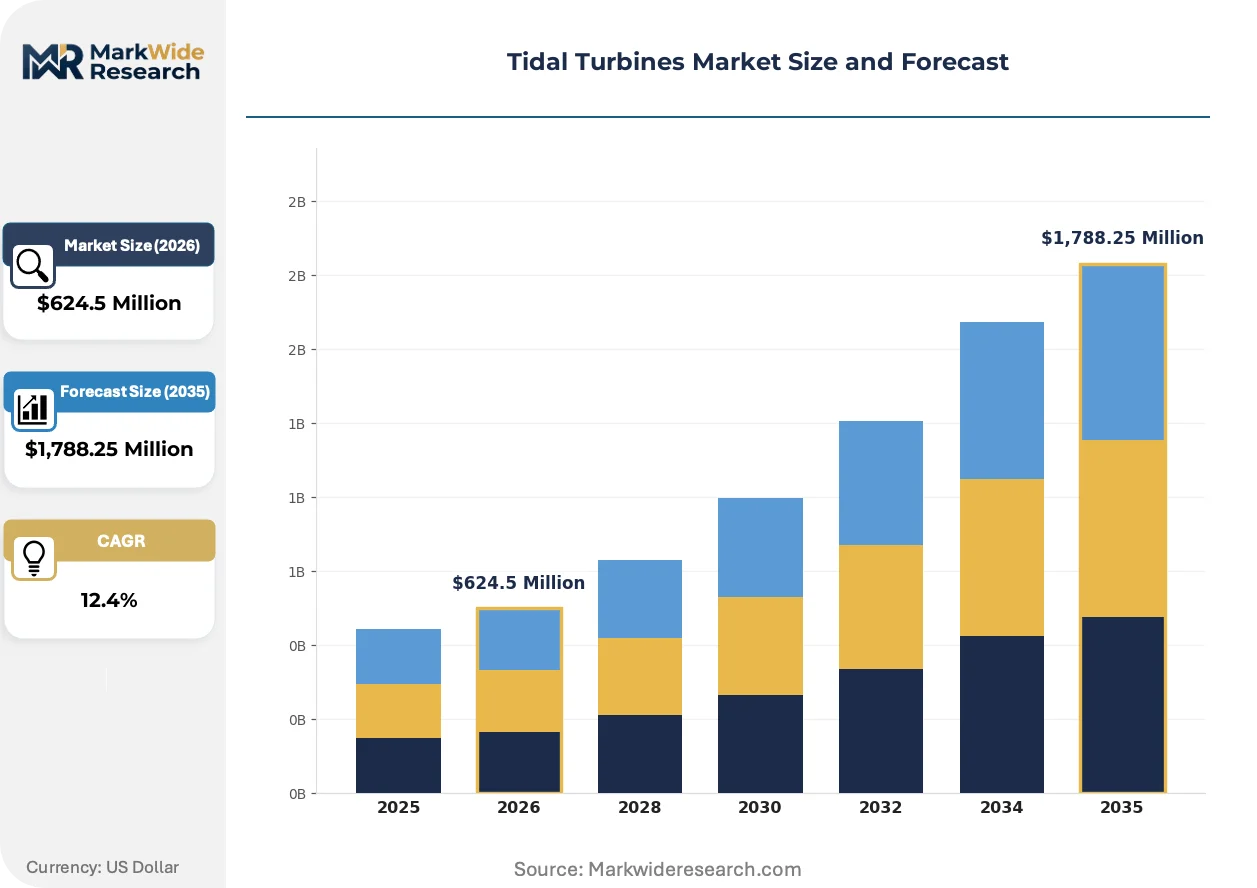
Market Dynamics
Modular floating platform architectures are compressing installation timelines and opening deeper water sites previously excluded from fixed-bottom economics, reshaping developer site selection criteria across high-velocity tidal corridors.
Growth Catalysts
- EU Green Deal marine spatial planning:Streamlined consenting frameworks in France, the United Kingdom, and Canada accelerate demonstration project deployment timelines.
- Utility procurement of grid-connected arrays:Coastal zone utilities scale direct power purchase agreements for baseload renewable supply.
- Pentland Firth velocity corridors:Scotland's concentrated tidal resource attracts concentrated developer pipeline activity.
Market Restraints
- Specialized vessel dependency:Heavy-lift installation and maintenance operations require scarce marine construction assets concentrated in North Sea ports.
- Bi-directional flow engineering complexity:Horizontal axis designs face yaw mechanism reliability constraints in reversing current environments.
- Environmental assessment duration:Health Canada and ANSM ecological monitoring mandates extend pre-construction phases by 18-36 months.
Strategic Opportunities
- Island community microgrids:Remote coastal settlements in Scotland and Atlantic Canada present captive demand for distributed tidal generation.
- Hybrid wave-tidal convergence:Integrated platform designs capture complementary energy profiles from co-located resources.
- France's ANSM adaptive consenting:Risk-based environmental assessment pathways reduce regulatory friction for proven device architectures.
Industry Challenges
- Marine electrical technician scarcity:Subsea cable termination and wet-mate connector expertise resides with a limited pool of offshore oil and gas veterans.
- Type certification timeline compression:EMEC load-testing protocols require multi-year operational data collection before commercial bankability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tidal Turbines Market |
| Market Size in 2026 | $624.5 Million |
| Market Size in 2035 | $1,788.25 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Submerged, Floating Technology: Variable Pitch, Fixed Pitch, Biomechanical, Turbine Type Installation: Onshore, Offshore, Deep Water, Shallow Water End User: Utility Companies, Independent Power Producers, Government Entities, Research Institutions |
| Companies Covered | Nova Innovation Ltd, Lockheed Martin Corp, Andritz AG, Sustainable Marine Energy Ltd, Hyundai Heavy Industries Group, Orbital Marine Power Ltd, Minesto AB, Oceana Energy Co, SIMEC Atlantis Energy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tidal Turbines Market Trends and Innovations
Floating foundation systems are unlocking previously inaccessible water depths while digital twin integration transforms predictive maintenance economics for submerged rotating machinery.
Direct-drive permanent magnet generators are eliminating gearbox failure modes in harsh marine environments. Developers targeting Bay of Fundy and Brittany sites adopt these architectures for reduced maintenance intervals. The technology is decentralizing operational risk away from centralized drivetrain overhaul toward modular field-replaceable power electronics.
The EU Green Deal's marine renewable energy targets are mandating streamlined consenting through delegated acts under revised Renewable Energy Directive. Member states must transpose risk-proportionate assessment frameworks by specified deadlines. France and Scotland are accelerating device qualification pathways while maintaining ANSM and EMEC ecological safeguards.
Power purchase agreement structures are migrating from feed-in tariff dependence toward merchant exposure with floor price guarantees. Independent power producers in Canada and France negotiate synthetic offtake arrangements with industrial coastal consumers. This reconfiguration concentrates credit risk assessment on buyer offtake certainty rather than regulated tariff stability.
Tidal Turbines Market Segmentation
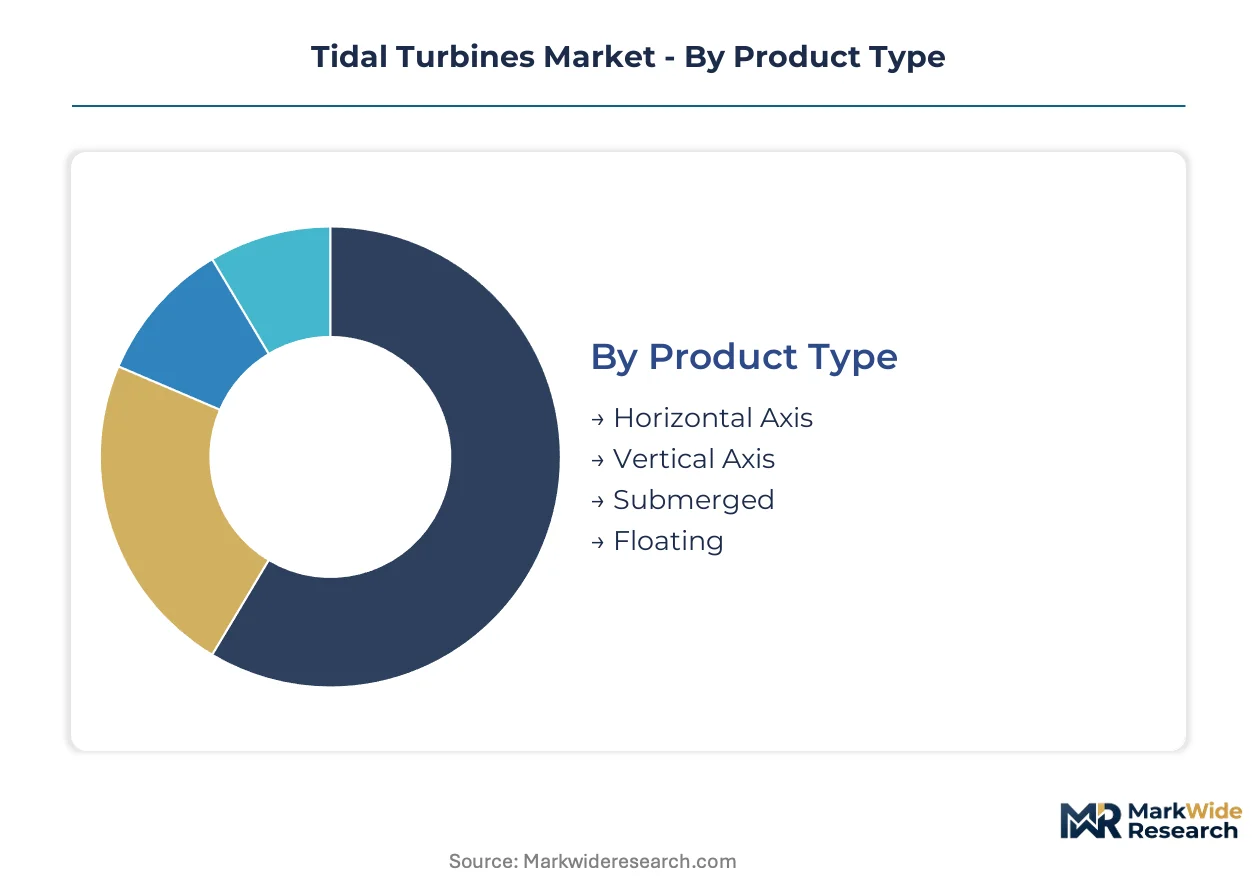
Tidal turbine procurement patterns diverge sharply between grid-connected utility arrays and distributed demonstration installations. Technology selection hinges on site-specific velocity profiles, water depth constraints, and regulatory qualification pathways rather than standardized product specifications.
Product Type:
Horizontal axis configurations integrate directly into seabed-fixed arrays for high-velocity corridor deployment, while floating platforms serve as modular systems adaptable to deeper water sites beyond fixed-bottom economic thresholds.
- Horizontal Axis:Bidirectional rotor designs with diameters of 15-25 meters dominate Pentland Firth and Bay of Fundy installations. EMEC certification requirements and utility procurement specifications favor these configurations for proven efficiency in reversing current environments.
- Vertical Axis:Omnidirectional flow capture eliminates yaw mechanism complexity. Developers targeting lower-velocity sites in Brittany and Atlantic Canada deploy these systems where current direction variability exceeds horizontal axis optimal operating envelopes.
- Submerged:Fully submerged architectures minimize surface visual impact and navigational interference. France's ANSM coastal consenting framework prioritizes these configurations for near-shore sites with marine traffic density.
- Floating:Tension-leg and semi-submersible platforms unlock water depths beyond 50 meters. Scotland's deeper western channel sites drive adoption where seabed geology precludes pile-driven foundations.
Volume placements concentrate in Horizontal Axis; the faster expansion belongs to Floating.
Technology:
Cost tier differentiation separates field-proven pitch control architectures from emerging biomechanical approaches still accumulating operational hours.
- Variable Pitch:Active blade angle adjustment optimizes energy extraction across tidal cycle velocity variations. Nova Innovation and Andritz AG deployments in Scotland and Canada utilize these systems for 15-20% capacity factor improvements over fixed alternatives.
- Fixed Pitch:Simplified mechanical design reduces capital cost and maintenance intervals. Island community microgrids in Atlantic Canada and Scottish archipelagos favor these systems for operational reliability in remote settings with limited technician access.
- Biomechanical:Bio-inspired flexible blade structures mimic aquatic organism propulsion mechanics. Early-stage developers in France and the United Kingdom test these architectures for reduced acoustic signature and marine life interaction risk.
- Turbine Type:Encompasses proprietary drivetrain configurations including direct-drive permanent magnet and geared induction systems. Health Canada environmental assessment protocols require acoustic characterization specific to each turbine type classification.
Procurement concentrates in Variable Pitch for utility-scale arrays; Fixed Pitch commands island and remote coastal installations.
Installation:
Geographic deployment constraints determine site classification more than technical system boundaries, with depth and seabed conditions overriding simple onshore-offshore distinctions.
- Onshore:Estuarine and coastal lagoon installations with grid connection via conventional cable infrastructure. Limited viable sites remain in France's Rance estuary and selected British Columbia locations.
- Offshore:Near-shore seabed-fixed arrays in 20-40 meter depths. The Pentland Firth and Bay of Fundy host concentrated offshore deployment pipelines under active marine spatial planning allocations.
- Deep Water:Sites exceeding 50 meters depth requiring floating foundation systems. Scotland's western approaches and Atlantic Canada's Laurentian Channel represent prospective deep water corridors.
- Shallow Water:Depths below 20 meters with simplified foundation requirements. Brittany's coastal channels and selected Nova Scotia inlets support shallow water economics for early-stage developers.
Developer activity clusters in Offshore; Deep Water claims the steepest expansion trajectory as floating platforms mature.
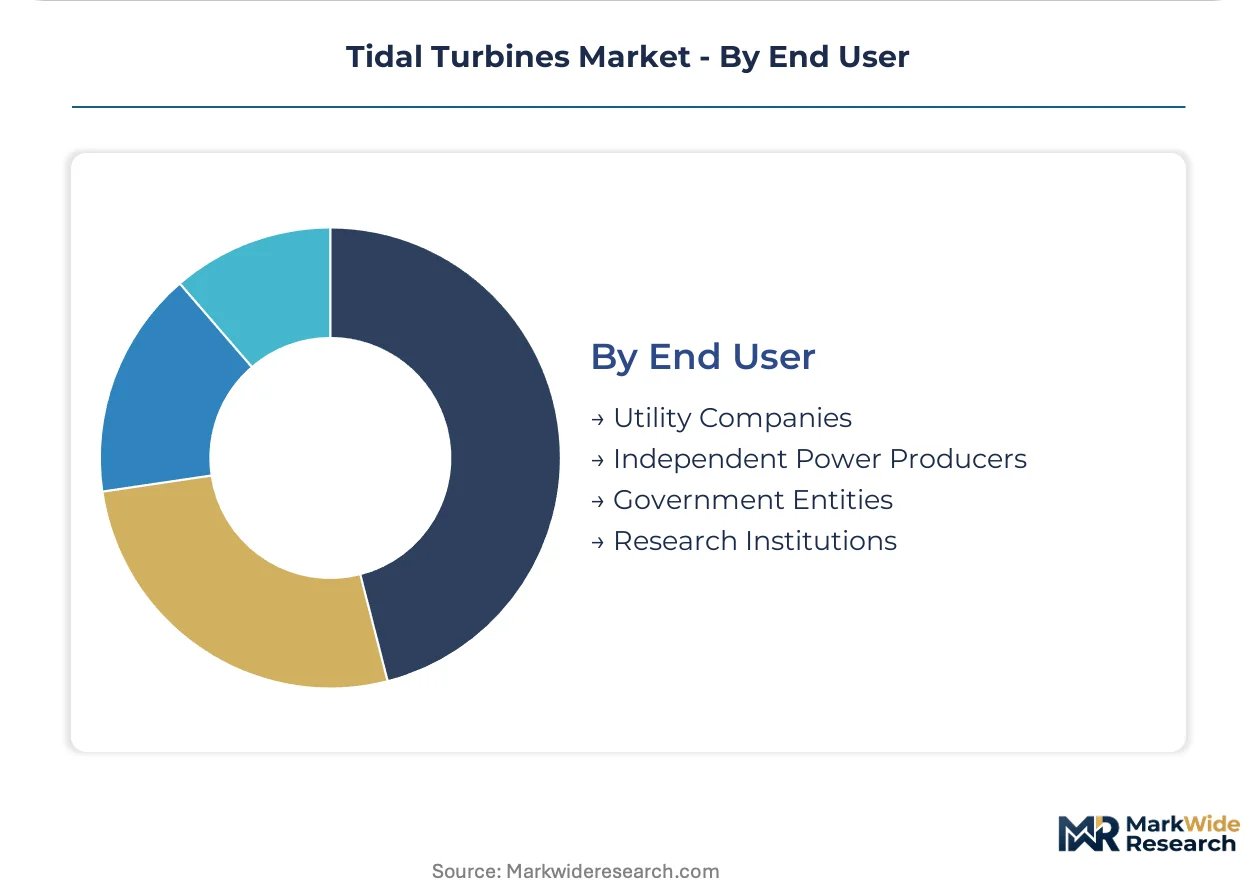
End User:
Customer type dictates financing structure, risk tolerance, and regulatory engagement intensity across the project development cycle.
- Utility Companies:Vertically integrated coastal utilities in France, the United Kingdom, and Canada procure grid-connected arrays through direct capital deployment. Power purchase agreement structures migrate toward merchant exposure with floor price guarantees.
- Independent Power Producers:Project developers negotiate synthetic offtake arrangements with industrial coastal consumers. Credit risk assessment concentrates on buyer offtake certainty rather than regulated tariff stability.
- Government Entities:Public sector procurement supports demonstration and pre-commercial arrays. EU Green Deal marine renewable energy targets and national innovation funding programs in France and Scotland channel public capital toward technology qualification.
- Research Institutions:Universities and national laboratories operate test berths at EMEC and parallel facilities. Device certification timelines and site access conditions for commercial developers depend partly on research institution priority allocations.
Capital deployment concentrates in Utility Companies; Independent Power Producers are gaining share fastest through power purchase agreement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland hosts the densest concentration of tidal turbine manufacturing capacity, while Canada and France absorb the bulk of deployed generation assets. Project pipelines cluster around velocity corridors where marine spatial planning has secured development rights.
United Kingdom
Scotland's Pentland Firth anchors European deployment activity, with EMEC certification protocols qualifying devices for commercial arrays. The UK government's Contracts for Difference mechanism supports tidal stream projects through dedicated pot allocations. Orkney Islands test berths host multiple device configurations undergoing load-testing for grid-connected utility procurement.
Canada
The Bay of Fundy corridor in Nova Scotia and New Brunswick concentrates North American tidal resource potential with velocity profiles exceeding 5 meters per second. Health Canada environmental assessment protocols mandate 18-36 month ecological monitoring phases before construction permits issue. Fundy Ocean Research Center coordinates stakeholder engagement for marine spatial planning in high-velocity channels.
France
Brittany's Raz Blanchard and Fromveur passages drive national tidal development priorities under the EU Green Deal marine renewable energy targets. ANSM coastal consenting frameworks apply risk-proportionate assessment pathways for proven device architectures. Quimper and Brest harbor clusters support subsea cable manufacturing and marine electrical assembly for regional projects.
South Korea
Jindo Uldolmok Strait hosts Asia's most advanced tidal stream demonstration site with 1.5 MW operational capacity. The Ministry of Trade, Industry and Energy channels public R&D funding through the Korea Institute of Ocean Science and Technology. Ulsan shipyard complexes leverage offshore oil and gas fabrication expertise for tidal platform construction.
United States
Alaska's Cook Inlet and Washington State's Puget Sound contain prospective velocity corridors awaiting federal marine spatial planning frameworks. FERC pilot project licenses provide streamlined permitting for grid-connected demonstration arrays under 5 MW capacity. Pacific Northwest National Laboratory operates environmental monitoring protocols for device ecological interaction assessment.
Tidal Turbines Market Competitive Landscape
The competitive structure tilts toward integrated technology developers rather than component suppliers or pure project operators. Market participants segregate into three strategic archetypes: turbine-and-anchor system integrators, hydropower engineering heritage firms, and marine construction conglomerates diversifying into renewable energy. Consolidation pressure concentrates among demonstration-phase developers seeking operational track records for utility procurement qualification. Partnership formations between device manufacturers and offshore vessel operators address specialized installation asset scarcity.
Among European specialists, Nova Innovation Ltd and Orbital Marine Power Ltd occupy positions within the integrated system tier, while Andritz AG exemplifies the hydropower heritage archetype extending into marine applications. Hyundai Heavy Industries Group anchors the marine construction conglomerate segment, leveraging shipyard fabrication capacity for platform assembly. These three represent distinct competitive vectors: rapid-deployment modularity, large-diameter horizontal axis engineering, and heavy-lift manufacturing scale.
| Leading Market Players |
|---|
| Nova Innovation Ltd |
| Lockheed Martin Corp |
| Andritz AG |
| Sustainable Marine Energy Ltd |
| Hyundai Heavy Industries Group |
| Orbital Marine Power Ltd |
| Minesto AB |
| Oceana Energy Co |
| SIMEC Atlantis Energy Ltd |
| Others |
Pricing and Supply Chain Analysis
Subsea cable copper and rare-earth magnet feedstock trace from Chilean mining operations and Chinese processing facilities through Scottish and South Korean assembly plants into three-tier pricing structures across premium, standard, and economy levels for utility procurement tiers.
Pricing Analysis
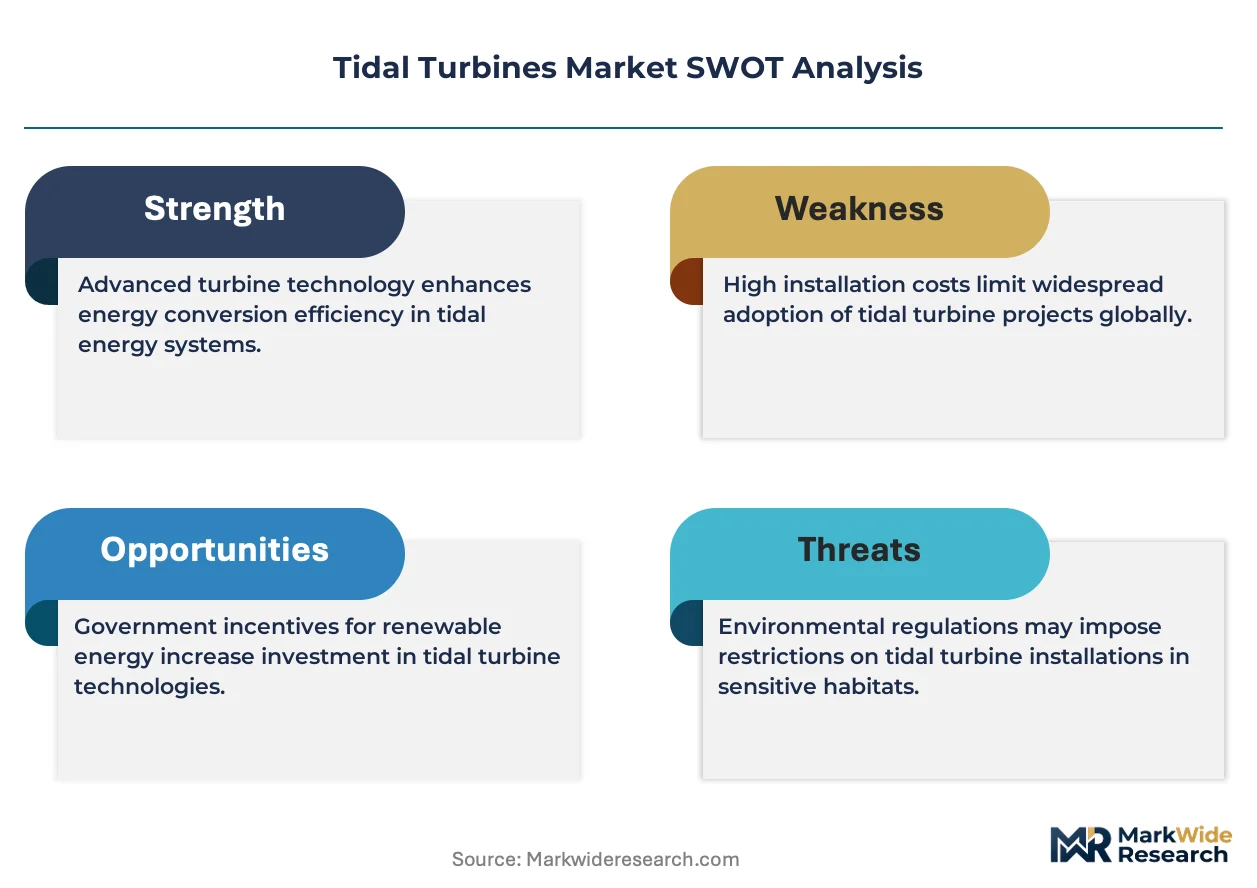
Cost-down pressure on floating platform configurations accelerates because EMEC certification timelines compress developer working capital cycles. Project-based long-term offtake contracts dominate utility procurement, with price differentiation resting on certification grade and after-sales service bundling. Independent power producers exhibit highest price sensitivity due to limited balance sheet capacity, while vertically integrated utilities absorb premium tiers for reduced operational risk.
Supply Chain Analysis
Marine electrical technician scarcity in Scottish and South Korean shipyard clusters constrains subsea cable termination throughput. Manufacturing concentrates in Scotland, South Korea, and France, drawing from neodymium magnet supply, composite blade materials, and high-grade steel forgings. Single-source vulnerability in rare-earth processing creates structural risk. Distribution runs through EPC contractors with captive offshore vessel fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating foundation architectures are displacing fixed-bottom systems as the dominant deployment paradigm, with direct-drive permanent magnet generators eliminating gearbox maintenance burdens that constrained earlier generation economics.
For Market Incumbents: Anticipate yaw mechanism reliability failures in bidirectional flow environments by accelerating field-replaceable power electronics development. EMEC load-testing protocol compression threatens demonstration-phase developers lacking operational track records. Prioritize certification investment in ANSM risk-proportionate assessment pathways to defend qualification timelines against emerging modular platform competitors.
For New Entrants and Emerging Players: Island community microgrids in Atlantic Canada and Scottish archipelagos present captive demand with limited incumbent penetration. Shallow water sites in Brittany's coastal channels offer lower certification barriers than Pentland Firth velocity corridors. Pursue synthetic offtake arrangements with industrial coastal consumers to bypass utility procurement gatekeeping.
For Investors and Strategic Acquirers: France's ANSM adaptive consenting implementation is the leading indicator that regulatory friction is shifting from environmental assessment duration toward device architecture risk classification. Five-to-ten year viability hinges on operational hour accumulation for bankability qualification. Target demonstration-phase developers with EMEC test berth access. Watch marine spatial planning allocation announcements in Bay of Fundy corridors as pipeline competition inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Restructuring | Merchant exposure with floor price guarantees attracts IPP capital into Nova Scotia development corridors. |
| Floating Platform Technology Licensing | Semi-submersible designs unlock Scotland's western channel depths beyond fixed-bottom economic limits. |
| Marine Electrical Technician Training Programs | Wet-mate connector expertise scarcity constrains installation timelines across North Sea ports. |
| Hybrid Wave-Tidal Convergence Development | Integrated platforms capture complementary energy profiles from co-located Brittany resources. |
| Backward Integration into Subsea Cable Manufacturing | Quimper and Brest harbor clusters anchor regional supply for ANSM-consented near-shore arrays. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tidal project developers, marine EPC contractors, utility planning officers, and EMEC certification specialists combined with bottom-up and top-down triangulation. Secondary sources included FERC pilot project licenses, Health Canada environmental assessment protocols, ANSM coastal consenting frameworks, and EU Green Deal delegated acts under revised Renewable Energy Directive.
Segment-level granularity modeled technology configurations, installation depth categories, end-user financing structures, and regional regulatory clusters across the projection horizon. CAGRs derived from installed capacity buildout trajectories, marine spatial planning allocation timelines, and power purchase agreement restructuring velocity. Forecast inputs incorporated vessel availability constraints and ecological monitoring phase durations specific to tidal stream development.
Revisions become necessary when marine spatial planning allocations shift, ecological impact thresholds tighten, or floating platform cost curves diverge from fixed-bottom learning rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
Solar Street Lighting Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Brazil Renewable Energy Market
Renewable Energy
China Wind Power Market
Renewable Energy
North America IoT in Renewable Energy Market