
 Egypt Renewable Energy Market | 2026-2036
Egypt Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Renewable Energy Market Analysis
Long-term power purchase agreements is consolidating as the dominant commercial mechanism in Egypt's renewable sector. ACWA Power leverages its experience with utility-scale solar and wind complexes to secure multi-decade contracts with the Egyptian Electricity Transmission Company. Elsewedy Electric anchors domestic manufacturing capacity for cables, transformers, and solar components, reducing import dependency for project developers. Infinity Power competes through integrated development, financing, and construction capabilities tailored to Egyptian regulatory conditions.
Egypt renewable energy encompasses electricity generation from solar photovoltaic, onshore wind, biomass combustion, and hydropower installations connected to the national grid or operated as captive power for industrial consumers. Solar dominates capacity additions, with utility-scale plants requiring minimum 50 MW thresholds to qualify for grid integration under current regulatory frameworks. Wind captures premium sites along the Red Sea coast where capacity factors exceed 45%, while biomass remains nascent limited by agricultural waste collection infrastructure. Application segments reveal power generation as the established revenue pool, though heating applications in industrial process steam show accelerating interest from food processing and textile manufacturers seeking fuel substitution.
The New and Renewable Energy Authority oversees project licensing and land allocation, while the Egyptian Electricity Regulatory Agency sets feed-in tariff tiers and grid access rules. Egypt's net metering scheme for commercial and industrial consumers shapes distributed solar demand, though regulatory uncertainty around tariff renegotiation timelines constrains long-term financing structures. Stakeholders must monitor upcoming amendments to the Electricity Law and the implementation trajectory of green hydrogen offtake agreements tied to renewable supply obligations.
Market Dynamics
Egypt's renewable energy sector is undergoing a fundamental transition as long-term power purchase agreements displace feed-in tariffs as the primary commercial mechanism, restructuring capital flows and developer risk allocation across utility-scale solar and wind installations.
Growth Catalysts
- Feed-in tariff framework:Egypt's tiered tariff structure under the New and Renewable Energy Authority continues to underwrite project bankability for utility-scale solar plants exceeding 50 MW thresholds, attracting international capital.
- Industrial off-taker demand:Cement and steel manufacturers are scaling captive renewable procurement to hedge against volatile natural gas pricing and meet corporate decarbonization commitments.
- Benban solar complex:Concentrated development in the Aswan governorate creates shared transmission infrastructure and operational learning curves that reduce per-MW development costs for subsequent phases.
Market Restraints
- Grid interconnection queues:The Egyptian Electricity Transmission Company faces capacity constraints integrating variable renewable output, creating multi-year delays for projects seeking connection permits.
- Foreign exchange exposure:Developer returns denominated in Egyptian pounds against dollar-denominated equipment and debt service expose margins to currency depreciation cycles.
- Agricultural waste logistics:Biomass generation remains constrained by fragmented collection infrastructure for rice straw and sugarcane bagasse, limiting feedstock security for combustion plants.
Strategic Opportunities
- Green hydrogen offtake:Renewable supply obligations tied to emerging hydrogen export agreements create anchored demand for additional wind and solar capacity in the Suez Canal Economic Zone.
- Net metering expansion:Commercial and industrial distributed solar installations remain underpenetrated outside Greater Cairo and Alexandria, presenting white space for rooftop and carport developers.
- Red Sea wind premium:Gulf of Suez sites exhibiting capacity factors above 45% offer generation economics competitive with regional gas-fired alternatives without carbon pricing.
Industry Challenges
- Grid code compliance:Projects must meet Egyptian Electricity Regulatory Agency frequency response and voltage ride-through standards requiring specialized inverter and control system engineering.
- Tariff renegotiation uncertainty:Ambiguity around timeline and process for feed-in tariff adjustments constrains long-term debt structuring and equity return modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Renewable Energy Market |
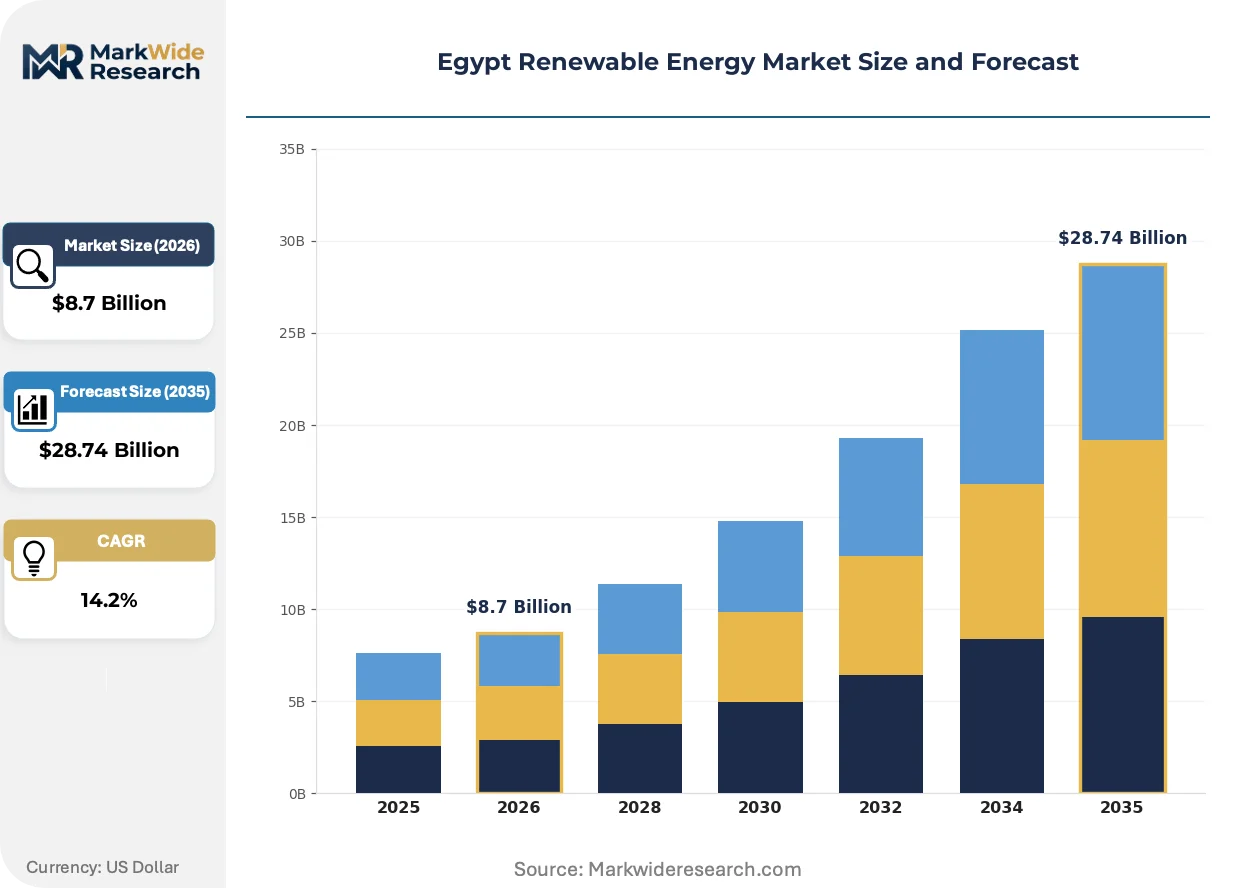
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Power Generation, Heating, Transportation, Agriculture End User: Residential, Commercial, Industrial, Government Service Type: Consulting, Installation, Maintenance, Energy Auditing |
| Companies Covered | ACWA Power, Infinity Power, TAQA Arabia, Vestas Wind Systems, Siemens Gamesa Renewable Energy, Elsewedy Electric, Gama Infrastructure, Acropol, Scatec ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Renewable Energy Market Emerging Trajectories
Bifacial photovoltaic modules and advanced inverter architectures are compressing levelized cost trajectories, while regulatory frameworks evolve to accommodate corporate renewable procurement and green hydrogen integration.
String inverter technology with 1500-volt DC architecture is absorbing market share from central inverter configurations in Egyptian utility-scale solar plants. EPC contractors favor distributed string topologies for reduced DC cabling costs and improved shade tolerance across Benban's sprawling desert arrays. This technology shift is absorbing maintenance complexity from plant operators by enabling granular fault isolation without full-string shutdowns.
Egypt's Electricity Law amendments under parliamentary review would enable bilateral contracting between renewable generators and qualified industrial consumers outside the single-buyer model. The New and Renewable Energy Authority is drafting implementing regulations for direct power purchase agreements that bypass Egyptian Electricity Holding Company intermediation. Large cement and aluminum producers are positioning to secure contracted renewable supply under this framework once promulgated.
Corporate renewable energy procurement is fragmenting traditional utility-centric demand patterns as multinational manufacturers establish Egyptian operations. Food processing and textile firms are negotiating sleeved power agreements with project developers, displacing historical reliance on state utility tariffs. This buyer-led contracting is most visible in the 10th of Ramadan and Sadat City industrial zones where European-owned facilities face Scope 2 emissions disclosure requirements.
Egypt Renewable Energy Market Segmentation
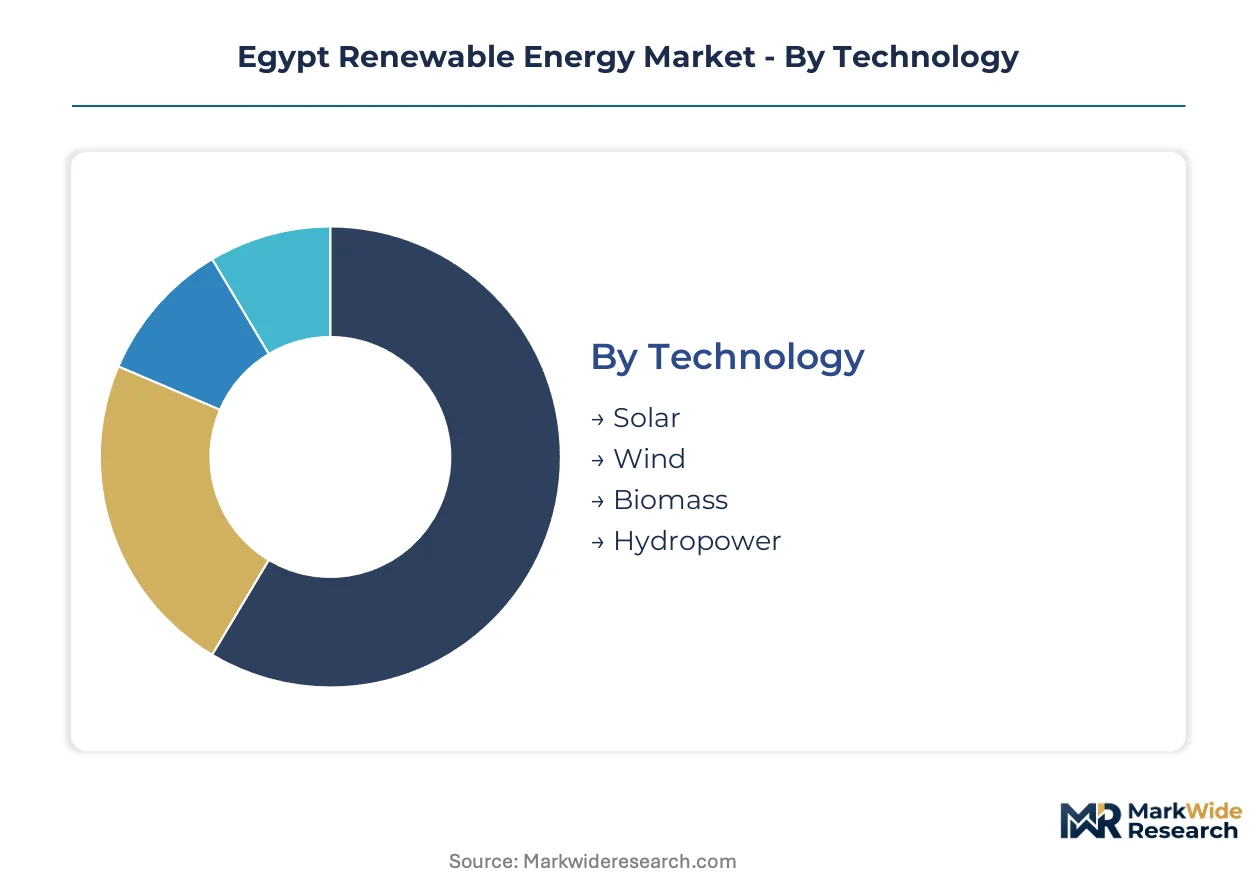
Technology choice in Egypt's renewable sector hinges on land availability, grid proximity, and offtaker creditworthiness rather than generation cost alone. Application patterns reveal divergent procurement logics between utility-scale exporters and captive industrial consumers. Service provider selection tracks project complexity and developer in-house capability gaps.
Technology:
Capital efficiency and resource quality determine technology selection for Egyptian developers bidding into competitive procurement rounds.
- Solar:Photovoltaic installations dominate capacity additions, with monocrystalline silicon modules and 1500-volt DC string inverters reducing balance-of-system costs at Benban and Kom Ombo sites. Utility-scale plants exceeding 50 MW thresholds secure priority grid access under New and Renewable Energy Authority licensing frameworks.
- Wind:Onshore turbines along the Gulf of Suez and Red Sea coast achieve capacity factors above 45%, outpacing solar generation economics without storage augmentation. Developments cluster near Ras Ghareb and Zaafarana where maritime wind regimes support 200-meter hub heights.
- Biomass:Agricultural residue combustion remains nascent, constrained by fragmented rice straw and sugarcane bagasse collection logistics in the Nile Delta governorates.
- Hydropower:Large-scale installations concentrate at the High Dam and Aswan reservoir, with mini-hydro additions limited by seasonal flow variability.
Volume sits with Solar; growth tilts toward Wind.
Application:
End-use requirements shape technology configuration and contracting structure across Egyptian renewable deployments.
- Power Generation:Grid-connected solar and wind plants supply the Egyptian Electricity Transmission Company under long-term power purchase agreements, with dispatch priority during daylight hours. Cement and steel manufacturers in 10th of Ramadan City increasingly procure sleeved renewable contracts to meet Scope 2 disclosure obligations.
- Heating:Industrial process steam applications attract food processing and textile firms in Sadat City seeking natural gas substitution, with solar thermal collectors and biomass boilers competing on delivered heat cost.
- Transportation:Electric vehicle charging infrastructure creates distributed demand for behind-the-meter solar in Greater Cairo and Alexandria, though grid integration standards remain under development.
- Agriculture:Solar-powered irrigation pumps expand in the Western Desert reclamation zones, supported by subsidized equipment finance through agricultural cooperatives.
Power Generation commands current deployment; Heating applications are expanding most quickly.
End User:
Customer scale and credit rating determine financing structure and technology scale for project developers.
- Industrial:Cement, aluminum, and chemical manufacturers anchor utility-scale demand through corporate power purchase agreements, leveraging balance sheets to secure dollar-denominated debt for 50 MW-plus installations. European-owned facilities in the Suez Canal Economic Zone drive procurement specifications tied to renewable energy certificate requirements.
- Commercial:Retail chains and hospitality operators in Cairo and Alexandria deploy rooftop solar under net metering arrangements, constrained by building ownership fragmentation and interconnection queue delays.
- Residential:Single-family installations remain limited by upfront capital requirements and weak net metering economics for sub-10 kW systems.
- Government:Public buildings and military installations procure through centralized tenders managed by the Ministry of Electricity and Renewable Energy, with local content mandates favoring domestic EPC contractors.
Industrial offtakers anchor revenue; Commercial distributed generation is gaining share fastest.
Service Type:
Project phase and developer capability gaps determine service procurement patterns across the Egyptian value chain.
- Installation:EPC contractors execute civil works, module mounting, and grid connection for utility-scale plants, with Egyptian firms capturing balance-of-plant scope and international suppliers providing turbine and inverter packages. ACWA Power and Elsewedy Electric compete on execution speed and local workforce deployment.
- Consulting:Technical advisory services support feasibility studies, grid code compliance documentation, and environmental impact assessments required for New and Renewable Energy Authority permitting.
- Maintenance:Operations and maintenance contracts span corrective repairs, module cleaning protocols, and performance ratio monitoring, with long-term service agreements increasingly bundled into initial EPC pricing.
- Energy Auditing:Industrial facility assessments identify efficiency improvements and renewable integration opportunities, typically preceding captive solar or biomass boiler investments.
Installation captures the largest service revenue pool; Energy Auditing shows the steepest expansion trajectory as industrial efficiency mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's renewable generation capacity concentrates in Upper Egypt and the Red Sea coast, while demand centers cluster around Cairo-Alexandria industrial corridors and the Suez Canal Economic Zone. This spatial mismatch drives transmission investment priorities and shapes developer site selection logic.
Benban Solar Complex
Utility-scale photovoltaic plants exceeding 1.8 GW aggregate capacity occupy desert land northwest of Aswan city. The New and Renewable Energy Authority allocated contiguous plots to enable shared 220 kV substation infrastructure. ACWA Power and Scatec ASA operate multiple phases here, leveraging operational learning curves to compress construction timelines for subsequent expansions.
Gulf of Suez Wind Corridor
Onshore wind developments cluster along the Ras Ghareb-Zaafarana coastline where maritime wind regimes support capacity factors above 45 percent. The Egyptian Electricity Transmission Company prioritizes grid reinforcement here to accommodate 250 MW-plus projects. Vestas Wind Systems and Siemens Gamesa Renewable Energy supply turbine packages for installations serving the Suez Canal Economic Zone.
Greater Cairo Industrial Zone
Cement and steel manufacturers in 10th of Ramadan City and Sadat City procure sleeved renewable contracts to meet Scope 2 emissions disclosure requirements. The Egyptian Electricity Regulatory Agency's net metering scheme shapes distributed solar demand among commercial and industrial consumers. TAQA Arabia competes here through integrated development, financing, and construction capabilities.
Suez Canal Economic Zone
Green hydrogen offtake agreements create anchored demand for additional wind and solar capacity serving ammonia and methanol export projects. The General Authority for Suez Canal Economic Zone coordinates land allocation for renewable supply obligations tied to hydrogen production concessions. Infinity Power positions integrated project capabilities to capture this emerging demand vector.
Nile Delta Biomass Zone
Agricultural residue combustion projects target rice straw and sugarcane bagasse feedstocks in Kafr El Sheikh and Dakahlia governorates. Fragmented collection infrastructure constrains feedstock security, limiting project scale below 25 MW. Elsewedy Electric explores equipment supply opportunities for pilot installations testing integrated harvesting and combustion logistics.
Egypt Renewable Energy Market Vendor Landscape
Capital-heavy asset owners compete with specialized EPC contractors and equipment suppliers across Egypt's renewable value chain. The market structure concentrates around three archetypes: integrated developers controlling project origination through operations, domestic manufacturers capturing balance-of-plant scope, and international turbine or module suppliers providing technology packages. Competitive dynamics center on securing long-term power purchase agreements with the Egyptian Electricity Transmission Company and positioning for green hydrogen offtake volumes in the Suez Canal Economic Zone.
Among integrated developers, ACWA Power exemplifies the utility-scale solar and wind complex operator securing multi-decade contracts. Elsewedy Electric anchors domestic manufacturing capacity for cables, transformers, and balance-of-system components. Infinity Power occupies a position bridging development, financing, and construction execution tailored to Egyptian regulatory conditions. These three represent distinct strategic postures: foreign capital deployment with operational experience, import substitution through local industrial capacity, and vertically integrated execution capability.
| Leading Market Players |
|---|
| ACWA Power |
| Infinity Power |
| TAQA Arabia |
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| Elsewedy Electric |
| Gama Infrastructure |
| Acropol |
| Scatec ASA |
| Others |
Supply Flow & Price Mechanics
Polysilicon price indices cascading from Chinese spot markets compress module costs through Egyptian value chains, forcing developers to recalibrate EPC bids against currency depreciation and import duty structures while tiering offerings across utility-scale, commercial, and industrial segments.
Pricing Analysis
Cost-down pressure on utility-scale solar accelerates because Chinese module oversupply and freight rate normalization compress landed equipment costs. Three-tier pricing structure across premium, standard, and economy levels separates gold-rated EPC contractors with O&M bundling from commodity installers competing on speed. Price differentiation hinges on local content certification under the New and Renewable Energy Authority framework and dollar-denominated debt access. Industrial offtakers exhibit highest price sensitivity due to natural gas hedge comparisons, while green hydrogen developers in the Suez Canal Economic Zone absorb premium pricing for bankable supply.
Supply Chain Analysis
Freight costs from Chinese ports through Suez Canal routes dominate landed module pricing, with Red Sea disruptions intermittently spiking container rates. Manufacturing concentrates in China, Vietnam, and Malaysia for cells and modules, while inverter supply clusters in Germany, China, and the United States. Egyptian developers draw from polysilicon, aluminum framing, and copper cabling inputs exposed to London Metal Exchange volatility. Single-source vulnerability sits with Chinese module suppliers commanding over 80 percent of procurement volumes. Distribution runs through Alexandria and Sokhna port customs clearance into developer warehouses and direct-to-site EPC logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's renewable sector functions as a vertical-integration race where developers securing captive EPC capability and equipment sourcing channels capture margin pools otherwise lost to currency volatility and import dependency.
For Market Incumbents: Lock in long-term power purchase agreement pipelines by anchoring transmission interconnection queues before grid capacity saturation. Prioritize backward integration into balance-of-system manufacturing to offset foreign exchange exposure on imported cables and transformers. Defend against emerging Saudi and Emirati developers by embedding local workforce training programs that satisfy New and Renewable Energy Authority labor content mandates. For New Entrants and Emerging Players: Industrial facility operators in 10th of Ramadan City represent the most penetrable channel partner type for behind-the-meter solar and process heat applications. Target food processing and textile manufacturers seeking natural gas substitution through solar thermal and biomass boiler integrations. Bypass saturated utility-scale procurement by positioning as net metering specialists for commercial rooftop portfolios in Greater Cairo and Alexandria. For Investors and Strategic Acquirers: The window for entry favors developers with integrated financing and construction capabilities positioned for Suez Canal Economic Zone hydrogen offtake obligations. Long-term viability rests on capturing renewable supply contracts tied to ammonia and methanol export projects with 15-20 year tenors. Monitor Egyptian Electricity Law amendment promulgation as the inflection signal enabling bilateral corporate power purchase agreements outside the single-buyer model.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Benban complex expansion leverages shared substation infrastructure to compress per-MW development costs for ACWA Power and Scatec ASA phases. |
| Power Purchase Agreement | Multi-decade contracts with Egyptian Electricity Transmission Company anchor project financeability against currency depreciation cycles. |
| Technology Licensing | 1500-volt string inverter architectures from Huawei and Sungrow reduce DC cabling costs across sprawling desert solar arrays. |
| Backward Integration into Manufacturing | Elsewedy Electric's cable and transformer production reduces import dependency and satisfies local content requirements for government tenders. |
| Green Certification Program | Renewable energy certificate eligibility positions European-owned Suez Canal facilities to meet Scope 2 emissions disclosure obligations. |
Methodological Framework
Multi-period observation of feed-in tariff tier adjustments, grid interconnection queue lengths, and module import volumes anchored the trend analysis, supplemented by interviews with utility planning officers at Egyptian Electricity Transmission Company, IPP project developers active in Benban and Gulf of Suez corridors, EPC contractors executing civil and electrical works, and grid operators managing frequency response standards. Secondary validation drew from New and Renewable Energy Authority licensing databases, Egyptian Electricity Regulatory Agency tariff filings, Suez Canal Economic Zone concession announcements, and customs import records for solar modules and wind turbine components. Bottom-up project pipeline aggregation triangulated against top-down capacity targets in the Integrated Sustainable Energy Strategy.
Segment-weighting across technology, application, end user, and service type dimensions shaped the analytical framework over the projection horizon. Solar photovoltaic, onshore wind, biomass combustion, and hydropower generation sources were modeled against power generation, heating, transportation, and agricultural end-uses. CAGRs were derived from capacity addition trajectories, tariff escalation assumptions, and industrial offtake contract pipelines. Forecast inputs incorporated green hydrogen offtake obligation timelines and Electricity Law amendment implementation probability.
Caveats apply where currency depreciation acceleration beyond historical bands, grid code compliance delays, or biomass feedstock logistics failures could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Europe Solar Tracker Market