
 Hungary Renewable Energy Market | 2026-2036
Hungary Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Renewable Energy Market Foresight
Capital-intensity divergence between integrated utilities and project developers is bifurcating competitive positioning across Hungary's renewable sector. MVM Group anchors its position through captive grid infrastructure and state-backed financing capacity. ALTEO Group differentiates via distributed generation assets and industrial offtake contracts. Solarpro Holding specializes in engineering-procurement-construction services for utility-scale photovoltaic installations.
Hungary renewable energy encompasses electricity and heat production from solar, wind, biomass, and hydropower resources, with photovoltaic modules typically rated at 400–700 Wp per panel and onshore wind turbines ranging 2–4 MW in domestic deployments. Solar photovoltaic leads capacity additions, while biogas technology occupies a stable niche in agricultural waste-to-energy applications. Industrial end users represent the fastest-growing demand pool, driven by corporate power purchase agreements and Scope 2 emissions targets.
Hungary's national energy regulator (MEKH) administers auction mechanisms and grid connection permits, while EU Green Deal alignment through REPowerEU shapes subsidy eligibility and technology-neutral tender design. The country's building energy codes and KÁT successor programs create compliance-driven retrofit demand across commercial property portfolios. Stakeholders must monitor auction price floors, grid curtailment protocols, and battery co-location requirements as the next investment cycle unfolds.
Market Dynamics
Industrial offtake contracts are redrawing competitive boundaries across Hungary's renewable sector, as corporate power purchase agreements displace traditional utility procurement for large-scale photovoltaic and biogas installations.
Growth Catalysts
- REPowerEU alignment:Hungary's auction mechanisms under the EU Green Deal accelerate technology-neutral tender participation, expanding eligible project categories beyond legacy KÁT feed-in structures.
- Corporate PPA expansion:Manufacturing and data center operators are contracting directly with renewable developers, bypassing regulated tariffs to secure Scope 2 emissions reductions.
- Pannonian Basin solar clustering:Irradiation levels above 1,200 kWh per square meter annually converge with existing transmission corridors, concentrating utility-scale photovoltaic development in the central Hungarian lowlands.
Market Restraints
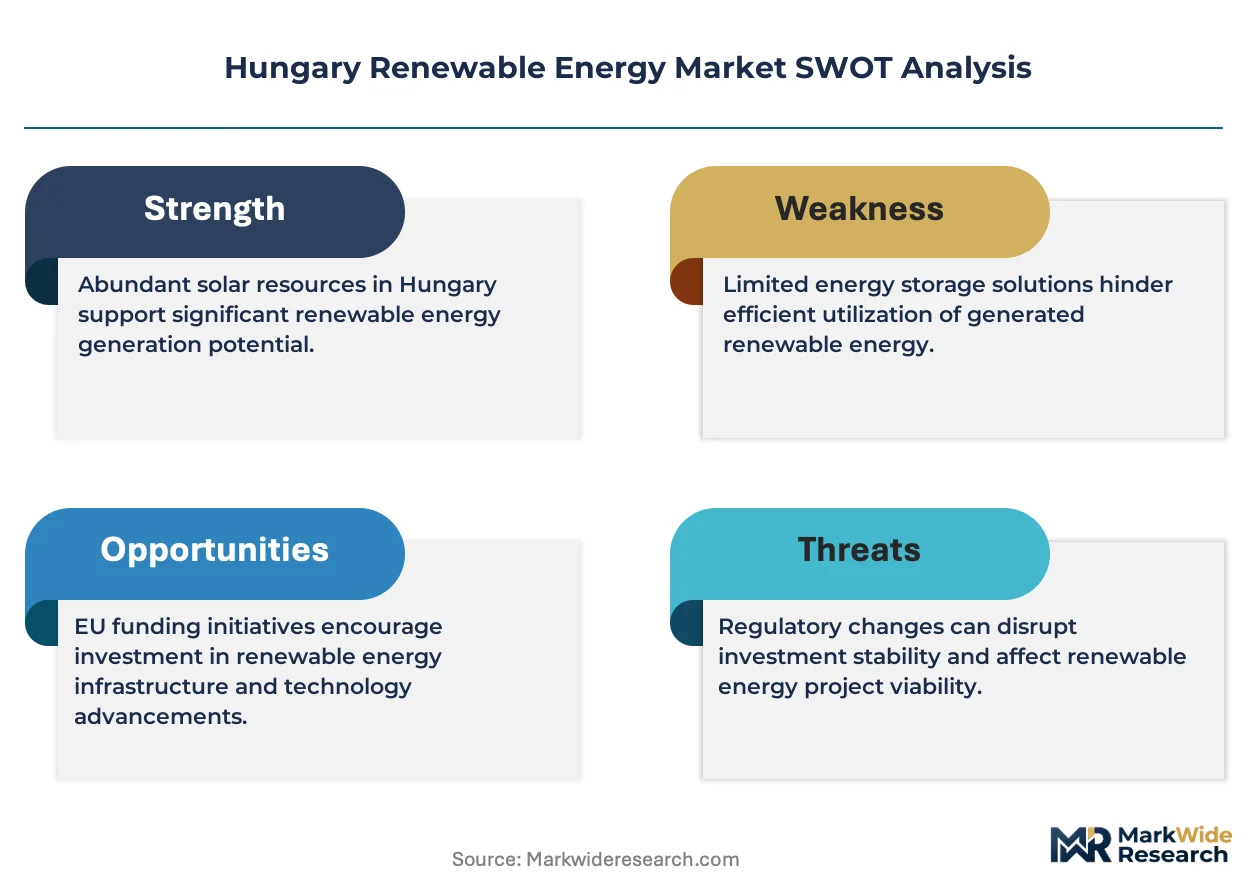
- Grid connection queuing:MEKH permitting timelines for new renewable interconnections extend 18-24 months, delaying project commissioning and capital recovery schedules.
- Domestic inverter supply concentration:Utility-scale solar projects depend on imported power electronics, exposing developers to semiconductor supply volatility and currency fluctuation risk.
- Biomass feedstock seasonality:Agricultural waste-to-energy facilities face raw material availability gaps during non-harvest periods, constraining annual capacity factors below baseload requirements.
Strategic Opportunities
- Battery co-location mandates:Emerging grid codes will require storage paired with new solar capacity, opening engineering-procurement-construction contracts for lithium-ion and flow battery integrators.
- Commercial building retrofits:Hungary's building energy codes create compliance-driven demand for rooftop photovoltaic and heat pump installations across Budapest and Debrecen office portfolios.
- Agrivoltaic pilot zones:Dual-use solar installations on agricultural land offer landowners supplementary revenue streams while preserving primary crop production in the Great Hungarian Plain.
Industry Challenges
- Grid curtailment protocols:Transmission system operators are implementing renewable generation dispatch limits during low-demand periods, forcing developers to absorb revenue uncertainty or invest in co-located storage.
- Skilled technician scarcity:Photovoltaic installation and wind turbine maintenance roles outpace vocational training output, compressing project execution timelines and elevating labor costs for specialized electrical work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Renewable Energy Market |
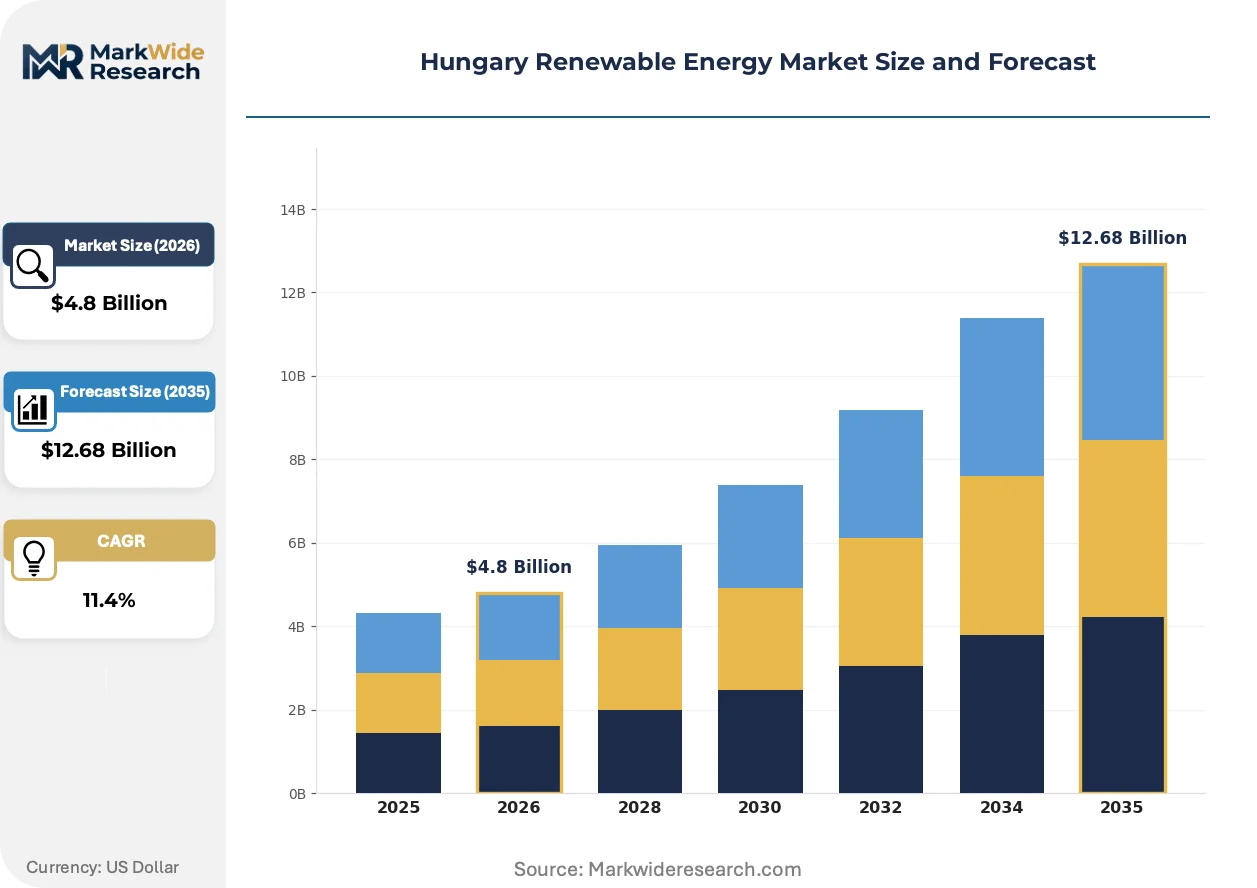
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Biomass, Hydropower Application: Power Generation, Heating, Transportation, Utilities Technology: Photovoltaic, Onshore Wind, Offshore Wind, Biogas End User: Residential, Commercial, Industrial, Government |
| Companies Covered | MET Group, ID Energy Group, MVM Group, Axpo Hungary, Statkraft Markets, ALTEO Group, Solarpro Holding, STS Group, E.ON Hungary, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Renewable Energy Market Shifts & Advancements
Technology convergence between generation assets and grid flexibility services is restructuring Hungary's renewable value chain, as standalone power plants evolve into integrated energy nodes.
Bifacial photovoltaic modules with tracking systems are fragmenting the utility-scale solar segment. Developers are deploying east-west single-axis trackers across the Pannonian Basin to flatten production curves and reduce midday peak exposure. Industrial offtakers are prioritizing these configurations for 24-hour consumption matching, compressing merchant price risk for project financiers.
EU Green Deal implementation through REPowerEU is tightening subsidy eligibility criteria. Hungary's national energy regulator is mandating domestic content thresholds and sustainability certification for auction participation. Photovoltaic developers are restructuring supply chains to incorporate European-manufactured modules, elevating procurement costs but securing tender price floor advantages.
Direct corporate contracting is displacing traditional utility intermediation for large renewable consumers. Automotive and battery manufacturing facilities in Győr and Debrecen are negotiating sleeved power purchase agreements with project developers. This channel shift concentrates creditworthy demand around a handful of industrial clusters, elevating developer selection criteria toward balance sheet strength and construction track record.
Hungary Renewable Energy Market Segmentation
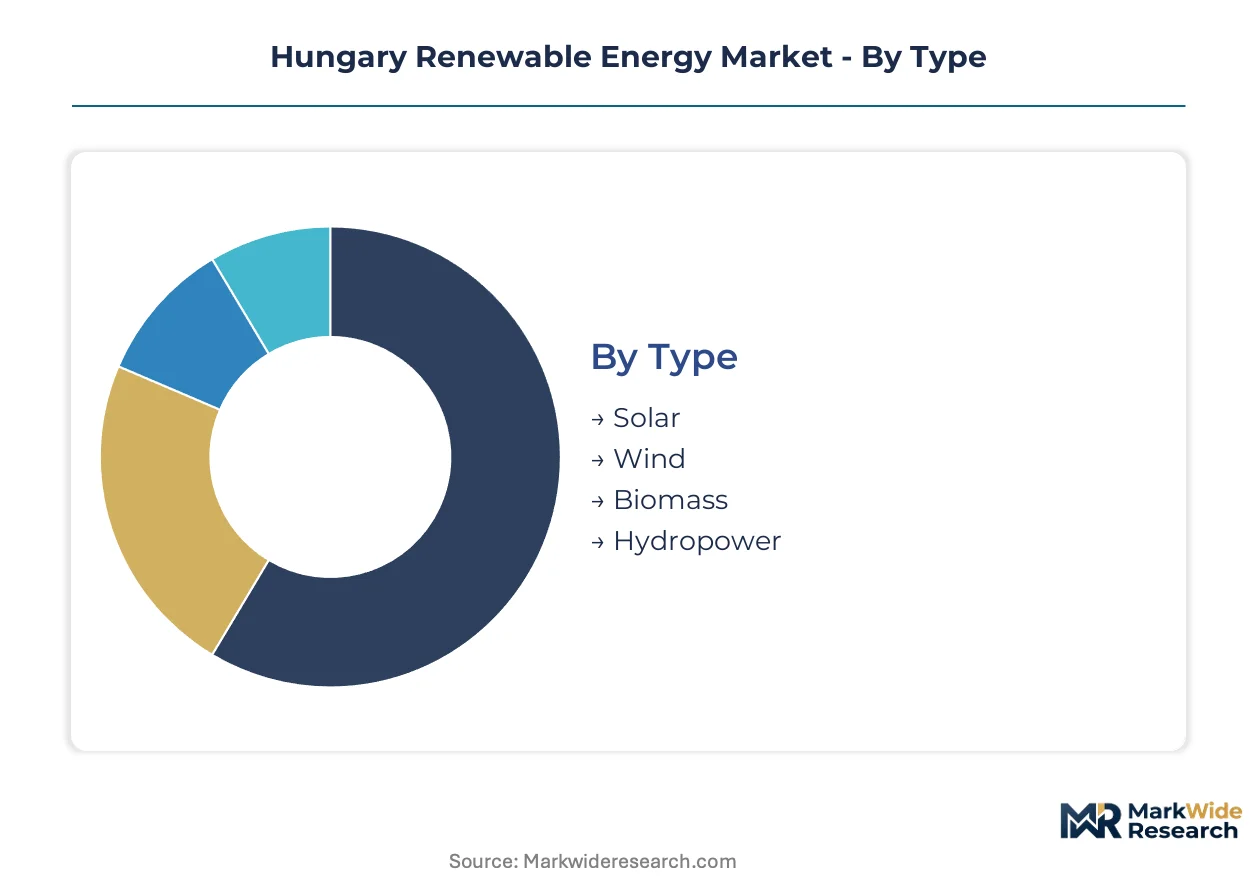
Segmentation of Hungary's renewable energy market reveals how regulatory mechanisms and resource endowments channel investment across distinct technology and customer categories. Understanding these divisions clarifies where auction eligibility rules, grid connection priorities, and subsidy structures create divergent commercial outcomes.
Type:
MEKH auction mechanisms differentiate eligible technologies through capacity banding and price floor adjustments, concentrating developer attention on segments with favorable tariff treatment.
- Solar:Photovoltaic installations dominate capacity additions across the Pannonian Basin corridor, where irradiation levels exceed 1,200 kWh per square meter annually. Utility-scale projects cluster around existing transmission infrastructure in central Hungarian lowlands, driven by corporate PPA demand from manufacturing facilities seeking Scope 2 emissions reductions.
- Wind:Onshore turbines ranging 2–4 MW operate primarily in the Northern Hungarian Mountains and Transdanubian hill regions with consistent wind resources. Project development has slowed relative to solar due to stricter environmental impact assessments and longer permitting timelines under nature protection regulations.
- Biomass:Agricultural waste-to-energy facilities process crop residues and animal manure through anaerobic digestion and combustion systems. Seasonal feedstock availability constrains annual capacity factors, limiting deployment to regions with concentrated livestock operations.
- Hydropower:Run-of-river installations along the Danube and Tisza river systems provide baseload renewable generation with minimal storage capability. Limited untapped sites restrict new capacity additions to small-scale retrofit projects.
Solar handles the majority of throughput; Wind is the fastest mover on share recovery as turbine technology improvements reopen marginal sites.
Application:
End-use configuration determines whether projects qualify for KÁT successor feed-in tariffs, premium corporate contracting, or merchant market exposure.
- Power Generation:Grid-connected renewable plants supply electricity to national transmission and distribution networks under regulated or market-based remuneration schemes. Industrial offtakers in Győr and Debrecen manufacturing clusters increasingly contract directly with developers, bypassing utility intermediation.
- Heating:District heating networks and building-level heat pumps utilize geothermal and biomass thermal energy, particularly in Budapest and regional cities with legacy cogeneration infrastructure. Building energy code compliance mandates drive retrofit demand across commercial property portfolios.
- Transportation:Biofuel production and electric vehicle charging infrastructure integration represent emerging demand channels. Renewable electricity procurement for fleet electrification is gaining traction among logistics operators.
- Utilities:Vertically integrated energy companies deploy renewable assets to meet portfolio decarbonization obligations and supply regulated customer segments. MVM Group anchors this channel through state-backed financing and captive grid infrastructure.
Power Generation commands the installed base; Transportation is expanding most quickly as fleet electrification accelerates.
Technology:
Engineering specifications and equipment sourcing requirements fragment the supply landscape, with domestic content thresholds increasingly influencing procurement decisions.
- Photovoltaic:Bifacial modules with 400–700 Wp ratings and single-axis tracking systems flatten production curves for industrial offtake matching. Developers face inverter supply concentration risks as utility-scale projects depend on imported power electronics.
- Onshore Wind:Turbine installations in the 2–4 MW range suit Hungary's moderate wind resource profile and grid connection constraints. Skilled technician scarcity compresses project execution timelines for specialized electrical and mechanical work.
- Offshore Wind:No operational capacity exists given Lake Balaton's limited fetch and depth constraints. Regulatory frameworks do not currently support marine renewable development.
- Biogas:Anaerobic digestion systems process agricultural organic waste into methane for electricity generation or grid injection. Facilities concentrate in the Great Hungarian Plain where livestock density ensures feedstock supply.
Photovoltaic carries the deployment volume; Biogas is gaining share fastest through agricultural sector integration.
End User:
Customer scale and creditworthiness determine project finance structures, with large industrial consumers commanding preferential developer attention.
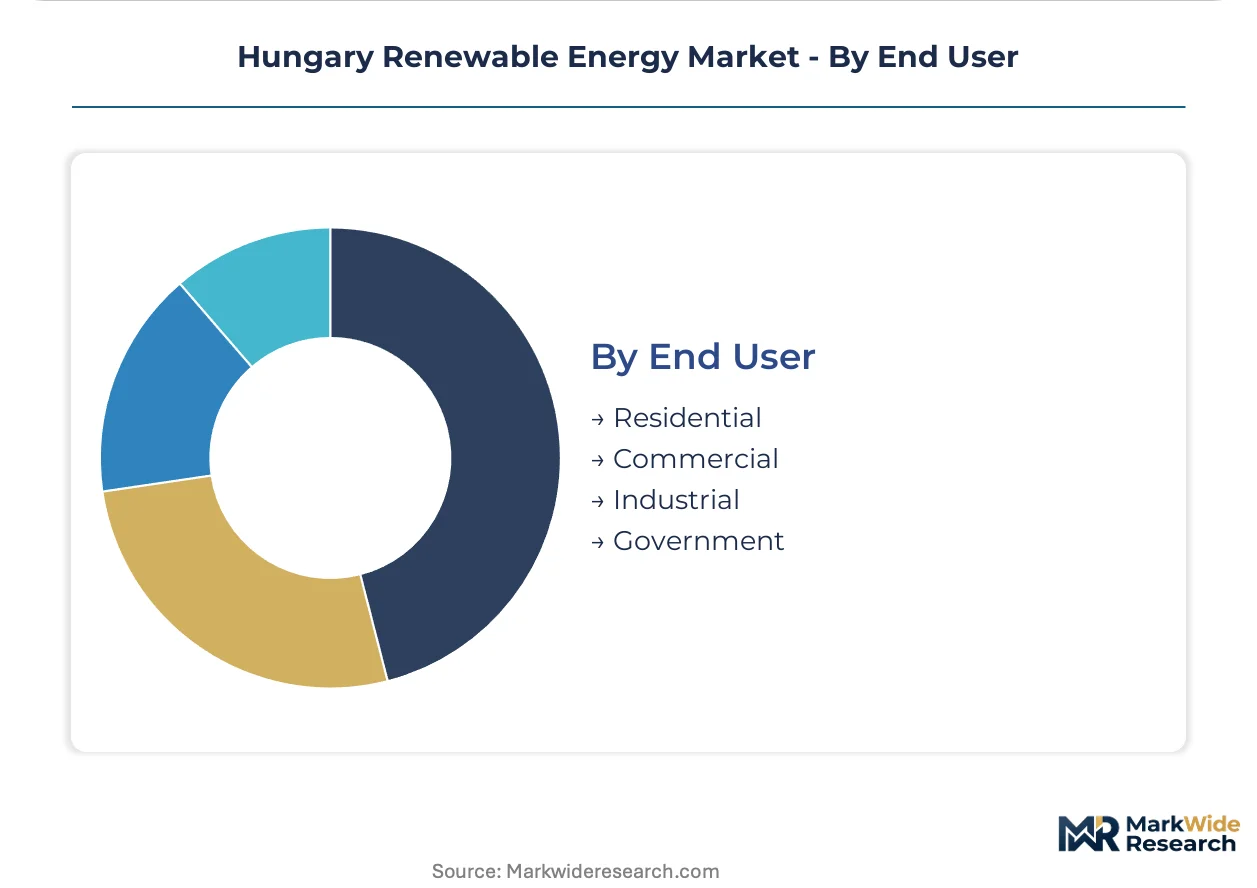
- Residential:Rooftop solar installations and heat pump retrofits respond to building energy code requirements and net metering provisions. Subsidy programs target owner-occupied housing in Budapest and major regional centers.
- Commercial:Office and retail portfolios pursue compliance-driven renewable procurement under tightening building performance standards. Budapest and Debrecen concentrate retrofit activity.
- Industrial:Manufacturing and data center operators negotiate sleeved power purchase agreements for 24-hour renewable supply matching. Automotive and battery facilities in Győr anchor this segment's expansion trajectory.
- Government:Public building portfolios and municipal utilities procure renewable electricity through centralized tender mechanisms. State-owned entities prioritize domestic content compliance in supplier selection.
Industrial end users handle the majority of new capacity contracting; Commercial is climbing the fastest as building code enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in the Pannonian Basin corridor exhibit low price elasticity for firm renewable supply, while residential rooftop segments remain highly sensitive to upfront capital costs and subsidy availability.
Central Hungary
The Budapest metropolitan area concentrates corporate power purchase agreement demand from data center and logistics operators seeking 24-hour renewable matching. MEKH auction mechanisms prioritize grid-connected solar projects in this zone, accelerating developer queue competition. Csepel and Soroksár industrial parks host the majority of sleeved PPA negotiations with automotive suppliers.
Western Transdanubia
Győr anchors Hungary's automotive manufacturing cluster, where battery and electric vehicle facilities drive baseload renewable procurement. The region's moderate wind resources in the Bakony foothills support hybrid solar-wind configurations for industrial offtakers. Local biomass facilities process agricultural residues from the Kisalföld grain belt.
Southern Great Plain
Szeged and Békéscsaba municipalities pursue district heating decarbonization through geothermal and biogas integration. Agrivoltaic pilot zones on the Great Hungarian Plain offer landowners dual revenue streams from solar generation and crop production. EU Green Deal rural development funds support these dual-use installations.
Northern Hungary
Miskolc and Eger industrial zones retrofit legacy manufacturing facilities with rooftop photovoltaic under tightening building energy codes. The Bükk and Mátra foothills retain untapped small hydro potential on tributary streams. Biogas plants concentrate around livestock operations in the Hernád and Sajó river valleys.
Lake Balaton Region
Tourism-dependent municipalities in Veszprém and Somogy counties deploy building-level heat pumps and solar thermal for hospitality sector compliance. Grid constraints limit utility-scale development, favoring distributed generation architectures. Balatonfüred and Siófok lead commercial property retrofit activity.
Hungary Renewable Energy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Hungary's renewable sector. State-backed integrated utilities command grid infrastructure and financing scale, while specialized developers compete on construction velocity and industrial offtake relationships. The competitive landscape fragments across three strategic archetypes: captive-grid utilities with balance-sheet depth, agile project developers with PPA execution capability, and engineering-procurement-construction specialists with installation track records. Dominant competitive moves include strategic partnerships for co-located storage integration and portfolio diversification into agrivoltaic and commercial retrofit segments.
Among Budapest-headquartered energy groups, MVM Group and ALTEO Group exemplify contrasting archetypes within the integrated-versus-distributed generation divide. MVM Group represents the state-anchored utility model with captive transmission access, while ALTEO Group occupies the independent power producer tier focused on industrial behind-the-meter solutions. Solarpro Holding sits within the specialized EPC contractor segment, engineering utility-scale photovoltaic installations without direct generation asset ownership.
| Leading Market Players |
|---|
| MET Group |
| ID Energy Group |
| MVM Group |
| Axpo Hungary |
| Statkraft Markets |
| ALTEO Group |
| Solarpro Holding |
| STS Group |
| E.ON Hungary |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month MEKH grid connection queues concentrate developer pricing power among incumbent utilities with captive transmission access, while project developers absorb capital lockup costs that compress margins on merchant-exposed installations. This lead-time asymmetry bifurcates the procurement landscape: integrated players command premium contract terms through balance-sheet depth, while independent developers face squeezed economics on equipment sourcing and construction financing.
Pricing Analysis
After-sales service contracts and long-term O&M agreements drive lifetime value for utility-scale solar assets, with EPC providers bundling performance guarantees into initial project pricing. Three-tier pricing structure across premium, standard, and economy levels separates integrated utilities with captive grid access from independent developers and specialized installation contractors. Cost compression in the independent developer tier is intensifying because semiconductor supply volatility elevates inverter procurement risk. Industrial offtakers in Győr and Debrecen exhibit the lowest price sensitivity, while residential rooftop segments remain highly responsive to upfront capital subsidies.
Supply Chain Analysis
China and Vietnam anchor photovoltaic module manufacturing, while Germany and the Netherlands concentrate inverter and power electronics production for Hungarian utility-scale deployments. Polysilicon wafers, lithium-ion battery cells, and single-axis tracking hardware constitute critical input dependencies. Single-source vulnerability in semiconductor-grade silicon exposes developers to supply disruption. Distribution runs through Budapest-based EPC contractors with direct relationships to Pannonian Basin project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's renewable sector faces substitution defense against grid-scale gas peakers and nuclear baseload extensions that could erode renewable capacity factor premiums. Incumbents must navigate this threat by securing structural advantages in interconnection queue positioning and offtake contract duration.
For Market Incumbents: Secure priority grid connection permits through MEKH pre-application engagement, locking in transmission capacity ahead of queue congestion. Deepen backward integration into battery co-location engineering to capture emerging storage mandate premiums. MVM Group's captive infrastructure model demonstrates how state-backed financing capacity neutralizes merchant price risk from competing baseload substitutes.
For New Entrants and Emerging Players: EU Green Deal sustainability certification fast-tracks auction eligibility under tightening domestic content thresholds, opening tender participation for supply chain restructured around European-manufactured modules. Target agrivoltaic pilot zones in the Great Hungarian Plain where dual-use installations face minimal incumbent saturation. Negotiate direct landowner revenue-sharing agreements that bypass traditional utility intermediation channels.
For Investors and Strategic Acquirers: Long-term, this sits as a contracted cashflow play because corporate PPA duration extension and REPowerEU subsidy visibility reduce merchant exposure across the analysis window. Acquisition targets should display industrial offtake contract depth with automotive or data center counterparties rather than pure development pipeline scale. The signal to watch is MEKH auction price floor adjustments that reveal regulator tolerance for developer margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid Connection Queue Positioning | Priority MEKH permits reduce interconnection delay risk for Pannonian Basin solar clusters. |
| Corporate PPA Execution | Direct contracting with Győr automotive facilities secures creditworthy offtake for project finance. |
| Battery Co-location Integration | Storage pairing with solar capacity satisfies emerging grid code mandates and curtailment protocols. |
| Domestic Content Compliance | European module sourcing secures auction price floor advantages under REPowerEU eligibility rules. |
| Agrivoltaic Pilot Development | Dual-use installations on Great Hungarian Plain farmland unlock EU rural development funding streams. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition modeling and top-down regulatory framework analysis were triangulated to reconcile segmentation outputs across fuel source, generation capacity tier, and regulatory framework dimensions.
Variance decomposition across technology segments and regional grid types structured the analytical framework over the projection horizon. CAGRs were derived from capacity deployment trajectories, auction participation rates, and corporate PPA contracting velocity. Modeled inputs included MEKH auction price floor adjustments, REPowerEU subsidy eligibility evolution, and battery co-location mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding commitment or accelerated nuclear capacity additions would require recalibration. Forecasts reflect assumptions on interconnection queue processing rates, semiconductor supply normalization, and industrial electricity demand growth. Recalibration cycles align with material shifts in MEKH regulatory protocols and REPowerEU implementation guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Solar Highway Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market