
 Drone Inspection Service for Renewable Energy Market | 2026-2036
Drone Inspection Service for Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Inspection Service for Renewable Energy Market Insights
Utility companies are gaining procurement share as the buyer base is bifurcating between large fleet operators and smaller independent power producers. SZ DJI Technology Co., Ltd. leverages manufacturing scale to dominate hardware supply for inspection fleets. SkySpecs, Inc. anchors its position through specialized autonomous flight software for wind turbine analytics. Cyberhawk Innovations Limited differentiates via integrated visual and thermal data delivery for offshore installations.
Drone inspection service for renewable energy deploys unmanned aerial vehicles equipped with LiDAR, thermal sensors, and high-resolution cameras to capture structural and performance data from wind turbines and solar arrays without manual climbing or shutdown. The primary purpose centers on reducing downtime, preventing catastrophic failures, and extending asset life through predictive maintenance scheduling. Aerial inspection services command the largest revenue share among service types due to recurring contractual demand from wind farm operators. Artificial Intelligence within the technology dimension represents the fastest-expanding segment as machine learning pipelines automate defect classification and prioritize repair workflows. Data analytics services capture concentrated margin pools by transforming raw imagery into actionable asset intelligence.
The FAA governs commercial drone operations in the United States through Part 107 certification requirements that dictate pilot qualifications and operational limitations for renewable site surveys. EASA in Europe enforces specific category frameworks for beyond-visual-line-of-sight flights over offshore wind platforms, directly shaping service provider capability investments. ISO 21384-3 provides unmanned aircraft system operational standards that influence insurance underwriting and client procurement criteria. Stakeholders must monitor evolving national aviation exemptions and harmonized EU-type certification pathways to secure competitive positioning in cross-border contract bidding.
Market Dynamics
Autonomous flight software is compressing inspection cycle times for wind turbine operators, forcing service providers to restructure pricing around defect-detection accuracy rather than flight hours logged. This technological inflection is redistributing margin from hardware suppliers to analytics platforms.
Growth Catalysts
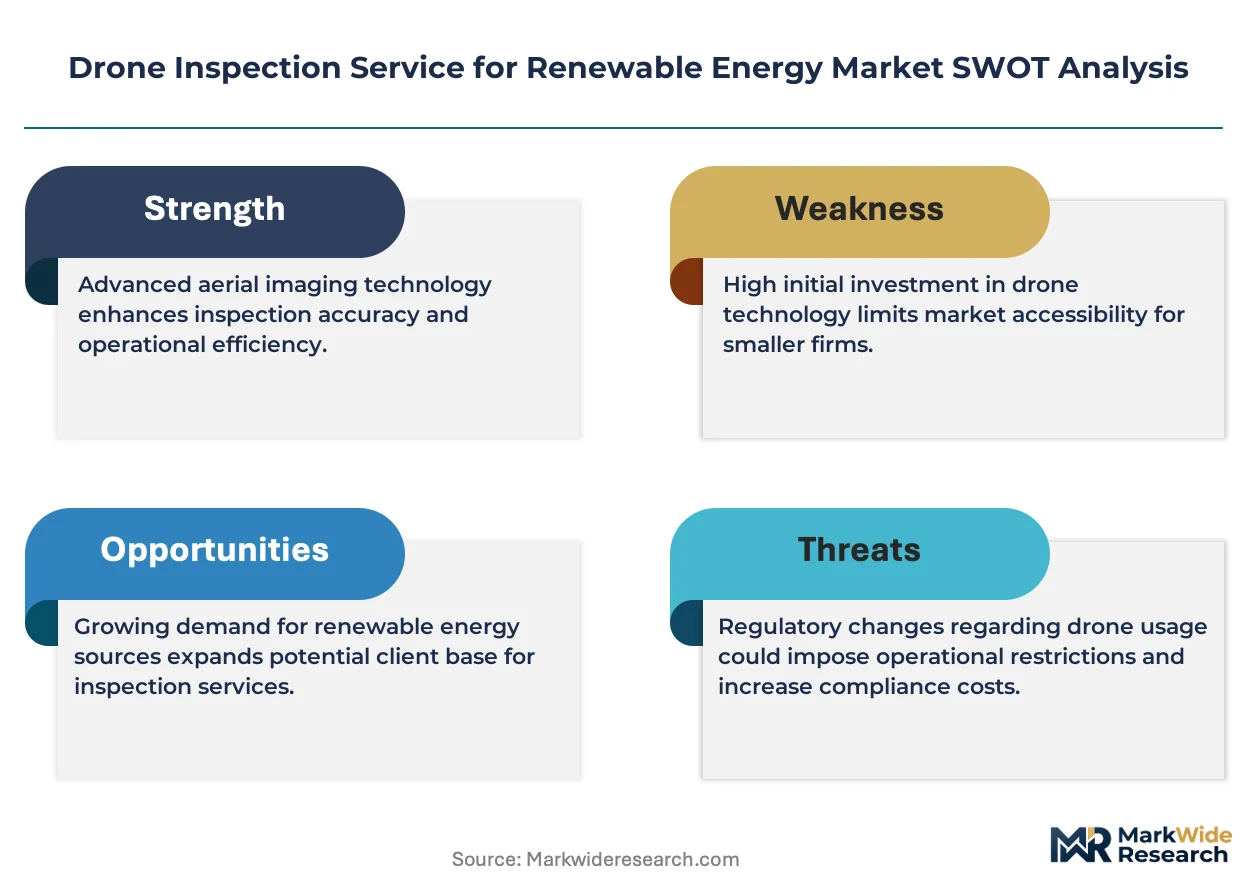
- EU Green Deal asset monitoring mandates:Stricter protocols for renewable infrastructure operators in Europe are mandating systematic blade and foundation assessments, creating recurring revenue pools for certified inspection contractors.
- Offshore wind buildout in Germany:Accelerated North Sea and Baltic Sea deployments require specialized beyond-visual-line-of-sight capabilities that terrestrial inspection models cannot replicate.
- Predictive maintenance scheduling:Machine learning pipelines now automate defect classification, enabling operators to prioritize repairs before catastrophic failures trigger downtime penalties.
Market Restraints
- Aviation certification complexity:EASA's specific category frameworks for offshore BVLOS flights impose capital-intensive capability investments that exclude smaller regional operators from bidding.
- Sensor hardware supply concentration:LiDAR and thermal imaging component sourcing clusters in East Asian manufacturing hubs, exposing service providers to input cost volatility and logistics bottlenecks.
- Manual rope-access substitution:Traditional climbing crews retain cost advantages for single-turbine spot repairs in markets with permissive labor regulations and limited automation incentives.
Strategic Opportunities
- Floating solar expansion in Asia-Pacific:Reservoir and coastal photovoltaic installations create demand for corrosion-resistant aerial platforms capable of operating over water surfaces without ground reference points.
- ISO 21384-3 harmonization:Emerging unmanned aircraft system operational standards are streamlining insurance underwriting criteria, reducing contract friction for cross-border service providers.
- AI-thermal sensor convergence:Real-time heat signature analysis during flight is opening subscription-based analytics revenue streams distinct from per-inspection fees.
Industry Challenges
- BVLOS pilot certification scarcity:Qualified operators for beyond-visual-line-of-sight offshore missions command wage premiums that compress field margins below 15 percent.
- Data integration with legacy SCADA systems:Wind farm operators operate heterogeneous equipment vintages, forcing inspection vendors to maintain multiple API compatibility layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Inspection Service for Renewable Energy Market |
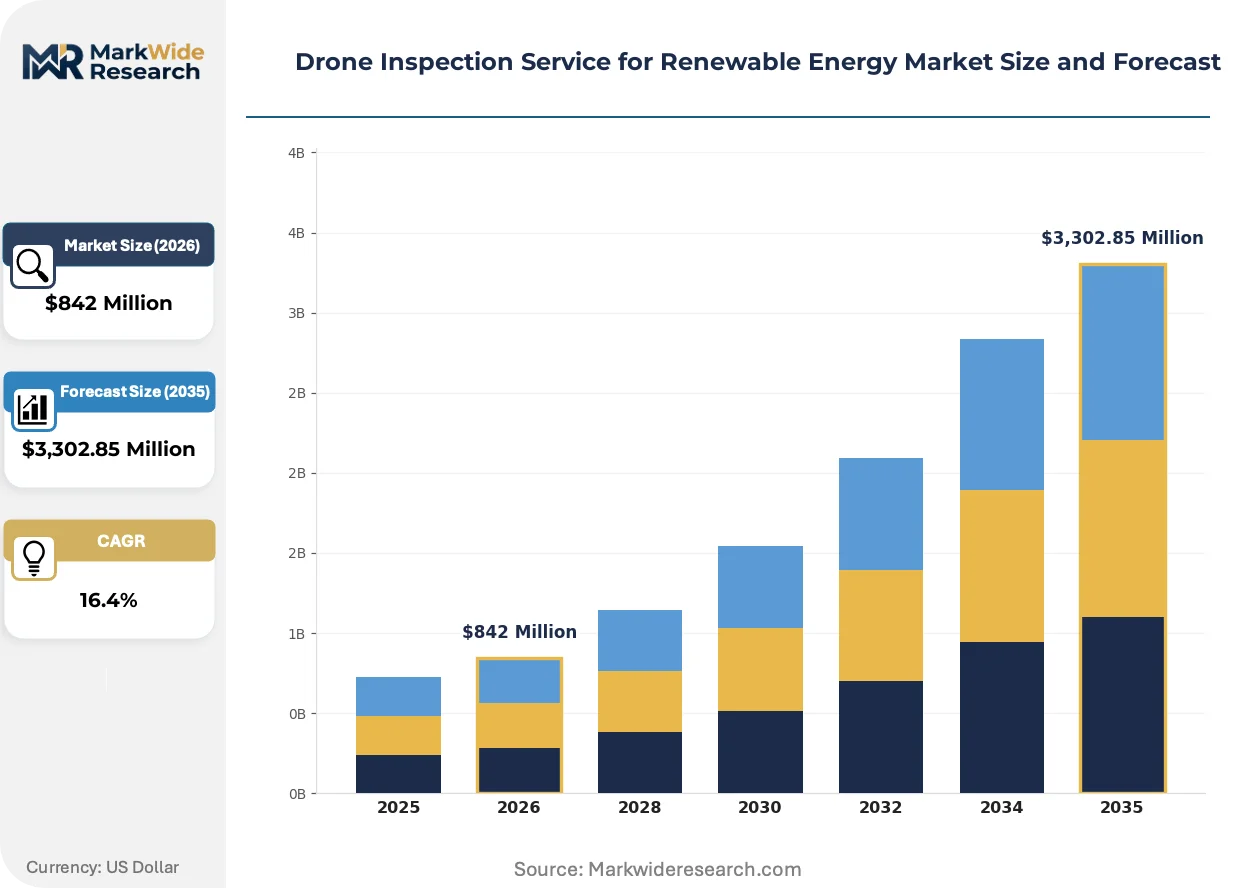
| Market Size in 2026 | $842 Million |
| Market Size in 2035 | $3,302.85 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Aerial Inspection, Thermal Imaging, Data Analytics, Visual Inspection Technology: LiDAR, UAV, Remote Sensing, Artificial Intelligence End User: Wind Farms, Solar Parks, Grid Operators, Utility Companies Application: Maintenance, Monitoring, Safety Assessments, Asset Management |
| Companies Covered | SZ DJI Technology Co., Ltd., SkySpecs, Inc., Cyberhawk Innovations Limited, Terra Drone Corporation, AeroVironment, Inc., Drone Volt Group, Raptor Maps, Inc., Percepto Ltd., Skylark Drones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Inspection Service for Renewable Energy Market Trends and Innovations
Edge-computing payloads are transforming how raw inspection data gets processed, eliminating the latency and bandwidth costs of cloud transmission for offshore wind assets. This architectural shift is redrawing competitive boundaries between hardware manufacturers and software analytics providers.
Autonomous blade-crawling drones equipped with ultrasonic thickness gauges are displacing manual rope-access technicians for leading-edge erosion assessments. Offshore wind operators in the North Sea are adopting these systems for scheduled maintenance windows. The technology is displacing time-based inspection contracts with condition-based service agreements priced per defect identified.
EASA's specific category framework for offshore wind platform overflight is mandating redundant communication links and detect-and-avoid systems for commercial BVLOS operations. Service providers must recertify fleets to maintain European contract eligibility. German and Danish operators are consolidating vendor panels to suppliers with pre-approved operational authorizations.
Utility procurement departments are unbundling inspection services from OEM maintenance contracts, creating direct RFP channels for specialized drone operators. Independent power producers are bypassing turbine manufacturers for blade analytics. This pattern concentrates in Germany where offshore wind farm ownership has fragmented among financial investors without captive service capabilities.
Drone Inspection Service for Renewable Energy Market Segmentation
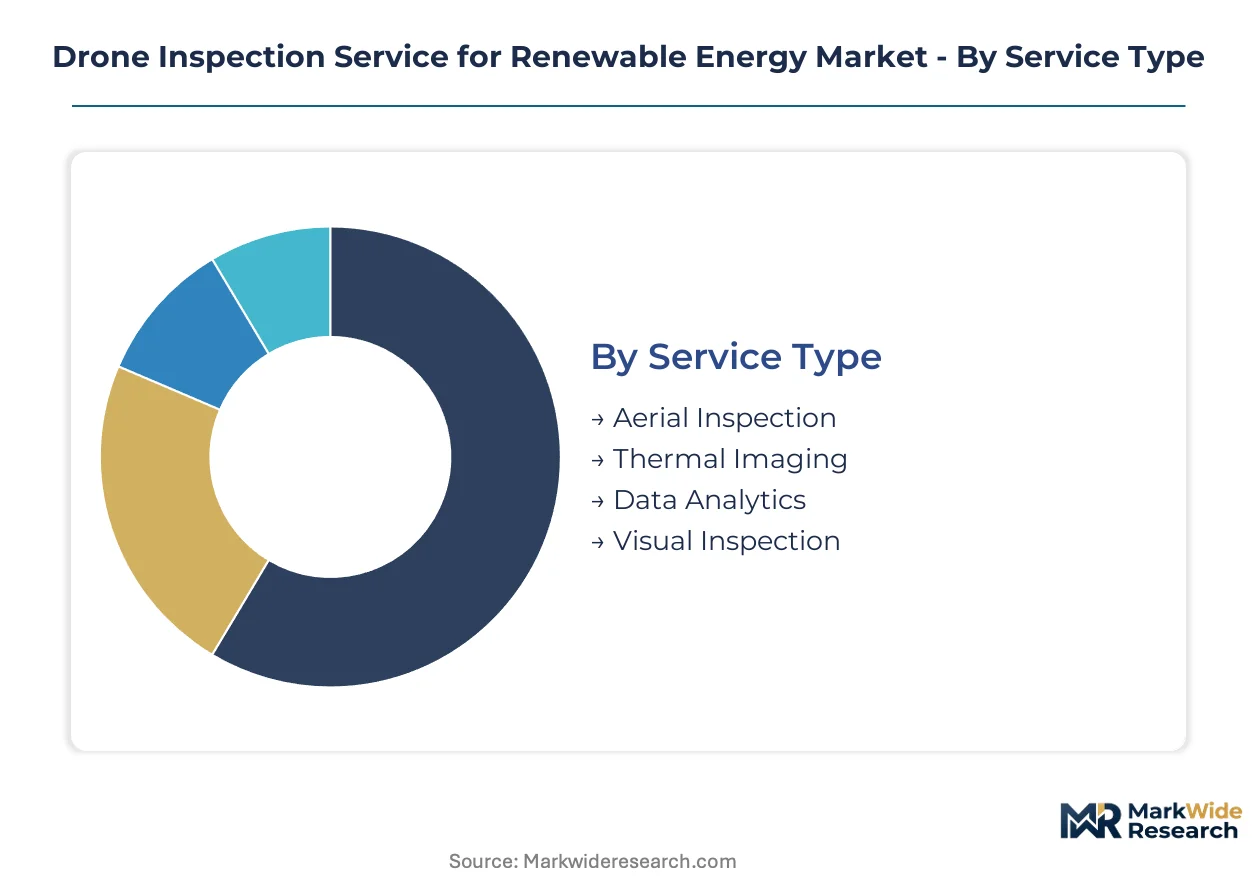
Service providers structure offerings around distinct capability bundles that match client operational profiles. Segment boundaries reflect divergent capital requirements, regulatory exposure, and margin architecture across the inspection value chain.
Service Type:
German and Danish operators drive export demand for specialized offshore capabilities, while domestic procurement concentrates on standardized terrestrial packages.
- Aerial Inspection:Recurring contractual arrangements with wind farm operators dominate revenue flows. North Sea deployments require beyond-visual-line-of-sight certifications that exclude smaller regional competitors from bidding.
- Data Analytics:Machine learning pipelines transform raw imagery into prioritized repair workflows. Utility procurement departments are unbundling these services from OEM maintenance contracts, creating direct RFP channels for specialized vendors.
- Thermal Imaging:Heat signature detection identifies blade delamination and electrical hotspots in photovoltaic arrays.
- Visual Inspection:High-resolution optical surveys remain cost-competitive for single-turbine spot assessments.
Aerial inspection holds the largest share; momentum sits with data analytics.
Technology:
Cost tiers separate capital-intensive hardware platforms from software-centric analytics layers with divergent scaling economics.
- Artificial Intelligence:Real-time defect classification algorithms compress inspection cycle times and automate prioritization. Edge-computing payloads are eliminating cloud transmission latency for offshore assets.
- LiDAR:Laser-based point cloud generation enables millimeter-precision blade deformation mapping. East Asian manufacturing concentration exposes service providers to input cost volatility and logistics bottlenecks.
- UAV:Multi-rotor and fixed-wing platforms carry sensor payloads across varying range and endurance requirements.
- Remote Sensing:Satellite and terrestrial data fusion supplements drone-captured intelligence for large-scale asset monitoring.
LiDAR anchors hardware procurement budgets; artificial intelligence is climbing the fastest.
End User:
Customer type determines contract structure, with utility procurement standardizing terms while independent producers negotiate bespoke service agreements.
- Wind Farms:Offshore operators in Germany mandate redundant communication links and detect-and-avoid systems for EASA compliance. Scheduled maintenance windows are displacing time-based contracts with condition-based pricing.
- Utility Companies:Centralized procurement departments consolidate vendor panels to suppliers with pre-approved operational authorizations. Fragmented ownership among financial investors without captive service capabilities accelerates third-party outsourcing.
- Solar Parks:Floating photovoltaic installations in Asia-Pacific create demand for corrosion-resistant aerial platforms.
- Grid Operators:Transmission infrastructure monitoring requires distinct regulatory clearance from generation asset inspection.
Wind farms command the dominant share; utility companies are gaining procurement momentum.
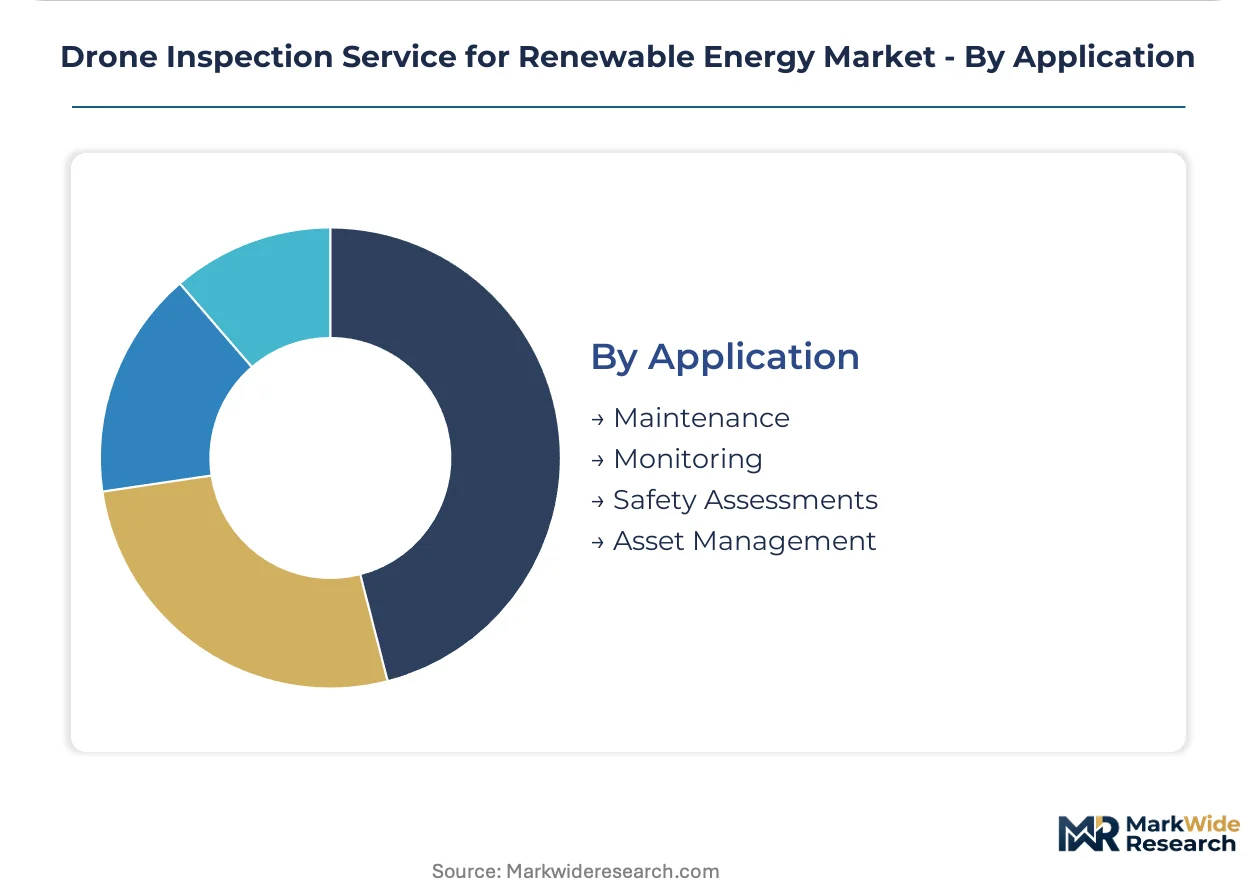
Application:
Maturity curves separate established reactive maintenance from emerging predictive models with divergent technology requirements.
- Maintenance:Autonomous blade-crawling drones equipped with ultrasonic thickness gauges displace manual rope-access technicians for leading-edge erosion assessments. Condition-based agreements now price per defect identified rather than flight hours logged.
- Monitoring:Continuous operational data streams integrate with legacy SCADA systems through multiple API compatibility layers. Heterogeneous equipment vintages force vendors to maintain complex integration stacks.
- Safety Assessments:Regulatory compliance documentation satisfies EU Green Deal asset monitoring mandates for systematic blade and foundation evaluations.
- Asset Management:Life-cycle extension strategies leverage inspection intelligence to optimize capital replacement timing.
Maintenance captures the largest application share; monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement departments concentrate buying power across fragmented renewable asset ownership, with German offshore wind operators and US independent power producers driving divergent service requirements. EASA and FAA regulatory frameworks shape capability investments differently across jurisdictions. Procurement patterns split between standardized terrestrial packages and specialized beyond-visual-line-of-sight offshore contracts.
United States
Independent power producers and utility procurement departments generate bifurcated demand for terrestrial and offshore inspection capabilities. FAA Part 107 certification requirements dictate pilot qualifications and operational limitations for renewable site surveys. Texas and California wind clusters anchor domestic procurement volumes, with Great Plains operators expanding autonomous flight software deployments.
Germany
Offshore wind buildout in the North Sea and Baltic Sea accelerates drone-based maintenance scheduling for turbine fleets. EU Green Deal asset monitoring mandates enforce systematic blade and foundation assessments through stricter protocols. Hamburg and Bremen harbor zones concentrate service provider headquarters with pre-approved EASA operational authorizations.
China
Dual carbon goals and utility-scale solar expansion drive procurement of aerial inspection programs across provincial grid operators. MIIT standards and GB unmanned aircraft system regulations shape domestic certification pathways. Yangtze River Delta manufacturing clusters supply LiDAR and thermal imaging components to regional service providers.
United Kingdom
Offshore wind farm ownership fragmentation among financial investors accelerates third-party outsourcing of blade analytics. Civil Aviation Authority BVLOS exemptions for North Sea platforms require redundant communication links and detect-and-avoid systems. Scottish coastal waters host concentrated floating wind pilot projects demanding corrosion-resistant aerial platforms.
Japan
METI renewable energy targets and offshore wind auction rounds stimulate demand for specialized inspection contractors. Class 1 unmanned aircraft operator certifications under Japan Civil Aviation Bureau regulations impose capability investments on market entrants. Kyushu and Hokkaido wind clusters drive terrestrial service procurement, with Chubu region suppliers developing typhoon-resistant platform designs.
Drone Inspection Service for Renewable Energy Market Competitive Landscape
Player mix skews toward hardware manufacturers with manufacturing scale advantages and specialized software providers with autonomous flight capabilities. Market structure shows tiered concentration, with integrated visual-thermal data specialists occupying mid-tier positions between commodity hardware and premium analytics platforms. Strategic archetypes include manufacturing-scale hardware suppliers, autonomous flight software specialists, and integrated data delivery operators. Competitive moves center on fleet recertification for EASA compliance and unbundling of analytics services from OEM maintenance contracts.
Within the manufacturing-scale tier, SZ DJI Technology Co., Ltd. anchors hardware supply for inspection fleets through its Shenzhen-based production base. SkySpecs, Inc. and Cyberhawk Innovations Limited exemplify divergent specialization strategies, with the former representing autonomous flight software capabilities for wind turbine analytics and the latter occupying integrated visual and thermal data delivery positioning for offshore installations. These three entities collectively illustrate how capability bundling separates procurement winners from commodity service providers.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| SkySpecs, Inc. |
| Cyberhawk Innovations Limited |
| Terra Drone Corporation |
| AeroVironment, Inc. |
| Drone Volt Group |
| Raptor Maps, Inc. |
| Percepto Ltd. |
| Skylark Drones |
| Others |
Pricing and Supply Chain Analysis
EASA's specific category framework for beyond-visual-line-of-sight offshore operations gates both supplier qualification and price differentiation simultaneously, forcing service providers to recertify fleets for European contract eligibility while enabling certified operators to command premium positioning against uncertified competitors.
Pricing Analysis
Next-generation autonomous flight software compresses inspection cycle times against legacy piloted services and emerging AI-native platforms. Pricing stratifies across premium, standard, and economy tiers based on EASA certification status and defect-detection accuracy guarantees. Cost compression in standard-tier aerial inspection is intensifying because autonomous software redistributes margin from hardware suppliers to analytics platforms. Independent power producers exhibit highest price sensitivity due to fragmented ownership without captive service capabilities, while German offshore wind operators prioritize certification compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites East Asian component flows for LiDAR and thermal imaging sensors that anchor hardware procurement budgets. Manufacturing concentration in China, South Korea, and Japan exposes service providers to input cost volatility and logistics bottlenecks. Sensor hardware supply draws from Yangtze River Delta production clusters, with single-source vulnerability concentrated in high-precision LiDAR modules. Distribution runs through direct OEM channels for fleet operators and specialized service integrators for independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data analytics services represent a service-attach opportunity expanding faster than hardware procurement, as utility procurement departments unbundle these offerings from OEM maintenance contracts and create direct RFP channels for specialized vendors.
For Market Incumbents: Shield market position by deepening backward integration into sensor hardware production to offset East Asian supply concentration, while accelerating EASA fleet recertification investments to exclude emerging regional competitors from German offshore bidding. Prioritize API compatibility layer development to capture heterogeneous SCADA integration contracts that smaller vendors cannot service. For New Entrants and Emerging Players: Predictive maintenance scheduling software gaps where incumbents under-serve create entry points for AI-native defect classification platforms. Floating solar installations in Asia-Pacific offer the most penetrable geography given corrosion-resistant platform demand and limited established vendor presence. Pursue direct utility procurement relationships bypassing turbine OEMs, leveraging condition-based pricing models priced per defect identified rather than flight hours logged. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive drone inspection units lacking standalone scale. Long-term viability hinges on software-analytics revenue mix exceeding hardware-dependent service contracts. Monitor BVLOS pilot certification scarcity as inflection indicator—wage premiums compressing field margins below sustainable thresholds signal consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Fleet Recertification | Maintains European contract eligibility for North Sea and Baltic Sea offshore operators. |
| Backward Integration into Sensor Hardware | Reduces exposure to East Asian LiDAR supply volatility and logistics bottlenecks. |
| AI-Native Defect Classification Platform | Captures analytics margin pools as machine learning pipelines automate prioritization workflows. |
| Floating Solar Capability Expansion | Addresses Asia-Pacific reservoir and coastal photovoltaic corrosion-resistant platform demand. |
| Direct Utility Procurement Channel | Bypasses turbine OEM maintenance contracts fragmented among financial investors without captive services. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement officers, wind farm operations directors, BVLOS-certified pilots, EASA regulatory consultants, and sensor hardware procurement leads, and refined through secondary validation against FAA Part 107 certification databases, EASA operational authorization registries, IEA renewable asset monitoring reports, and utility RFP documentation. Bottom-up service provider revenue estimates triangulated against top-down addressable market calculations across the analysis window.
Variance decomposition across service type, technology tier, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression-weighted technology adoption curves and regulatory mandate implementation timelines. Forecast inputs incorporated EASA specific category framework rollout assumptions and German offshore wind buildout commissioning schedules.
Forecasts assume regulatory continuity in EASA and FAA regimes; material policy shifts would require re-modeling. Revision becomes warranted when BVLOS pilot certification scarcity crosses thresholds that structurally exclude smaller operators from bidding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Wave Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Romania Wind Energy Market