
 Brazil Renewable Energy Market | 2026-2036
Brazil Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Renewable Energy Market Analysis
Northeast Brazil is fragmenting across multiple technology configurations as developers race to capture wind and solar resources. Eletrobras leverages its legacy hydro infrastructure to anchor grid stability services for intermittent renewables. CPFL Renováveis specializes in distributed solar generation for commercial off-takers in southeastern states. ENGIE Brasil Energia competes through onshore wind portfolios concentrated in Rio Grande do Norte and Bahia.
Brazil renewable energy encompasses electricity generation from solar PV, onshore wind, biomass combustion, and run-of-river hydro systems, typically converting primary energy through turbines, inverters, or anaerobic digesters into grid-compatible power at voltages from 220V to 500kV. Solar PV dominates new capacity additions due to module cost declines and high irradiance in the semi-arid zone. Onshore wind leads capacity factors among variable sources, while biomass sustains baseload supply through sugarcane bagasse and forestry residue. Grid-connected installations occupy the largest revenue pool, though off-grid and microgrid configurations are expanding fastest in remote Amazon communities.
ANEEL governs grid access tariffs and distributed generation compensation rules, while the Ministry of Mines and Energy administers auction mechanisms that determine long-term power supply contracts. The national biofuels policy and decarbonization credit frameworks shape investment allocation between biomass, wind, and solar developers. Stakeholders must monitor auction schedule changes and transmission bottleneck resolution in the Northeast corridor to time capital deployment effectively.
Market Dynamics
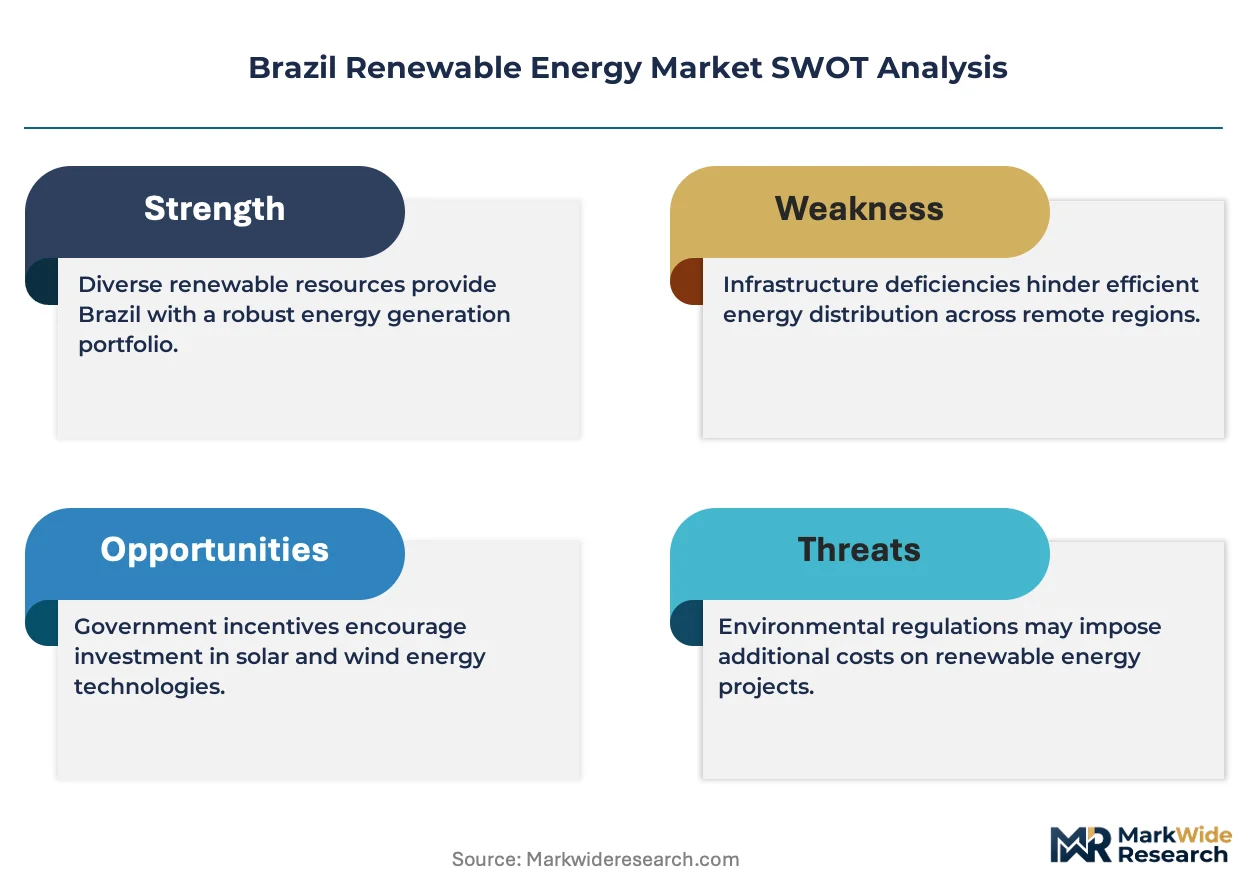
ANEEL's net metering revisions and distributed generation compensation rules are restructuring project economics faster than transmission expansion can absorb new capacity in the Northeast corridor.
Growth Catalysts
- Proinfa Incentive Framework:Brazil's renewable energy incentive program stabilizes long-term revenue streams for biomass and wind developers through guaranteed offtake contracts indexed to inflation.
- Industrial Mining Demand:Iron ore and steel producers in Minas Gerais and Pará are executing power purchase agreements for clean electricity to meet Scope 3 emissions targets.
- Semi-Arid Solar Irradiance:The Caatinga biome's 2,200+ annual sunshine hours attract utility-scale photovoltaic deployment financed by development banks.
Market Restraints
- Transmission Congestion:Grid bottlenecks between Rio Grande do Norte generation clusters and southeastern load centers force curtailment during peak wind seasons.
- Import Dependency:Solar module supply concentrates on Asian manufacturers, exposing developers to currency volatility and maritime freight cost swings.
- Biomass Feedstock Seasonality:Sugarcane bagasse availability collapses outside harvest windows, requiring thermal backup or storage investments.
Strategic Opportunities
- Amazon Microgrids:Remote riverine communities in Amazonas and Roraima states present off-grid solar-plus-storage deployments exempt from centralized interconnection queues.
- Green Hydrogen Integration:Port complexes in Pecém and Suape are positioning to electrolyze wind power for export-oriented ammonia and steel decarbonization.
- Agrivoltaics Expansion:Dual-use solar installations over soybean and coffee plantations in Mato Grosso and Minas Gerais unlock land efficiency premiums.
Industry Challenges
- Grid Code Compliance:ANEEL's updated voltage ride-through and frequency response requirements demand inverter retrofits on older wind farms.
- EPC Talent Scarcity:Specialized electrical technicians for 500kV substation commissioning command wage premiums that compress developer margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Renewable Energy Market |
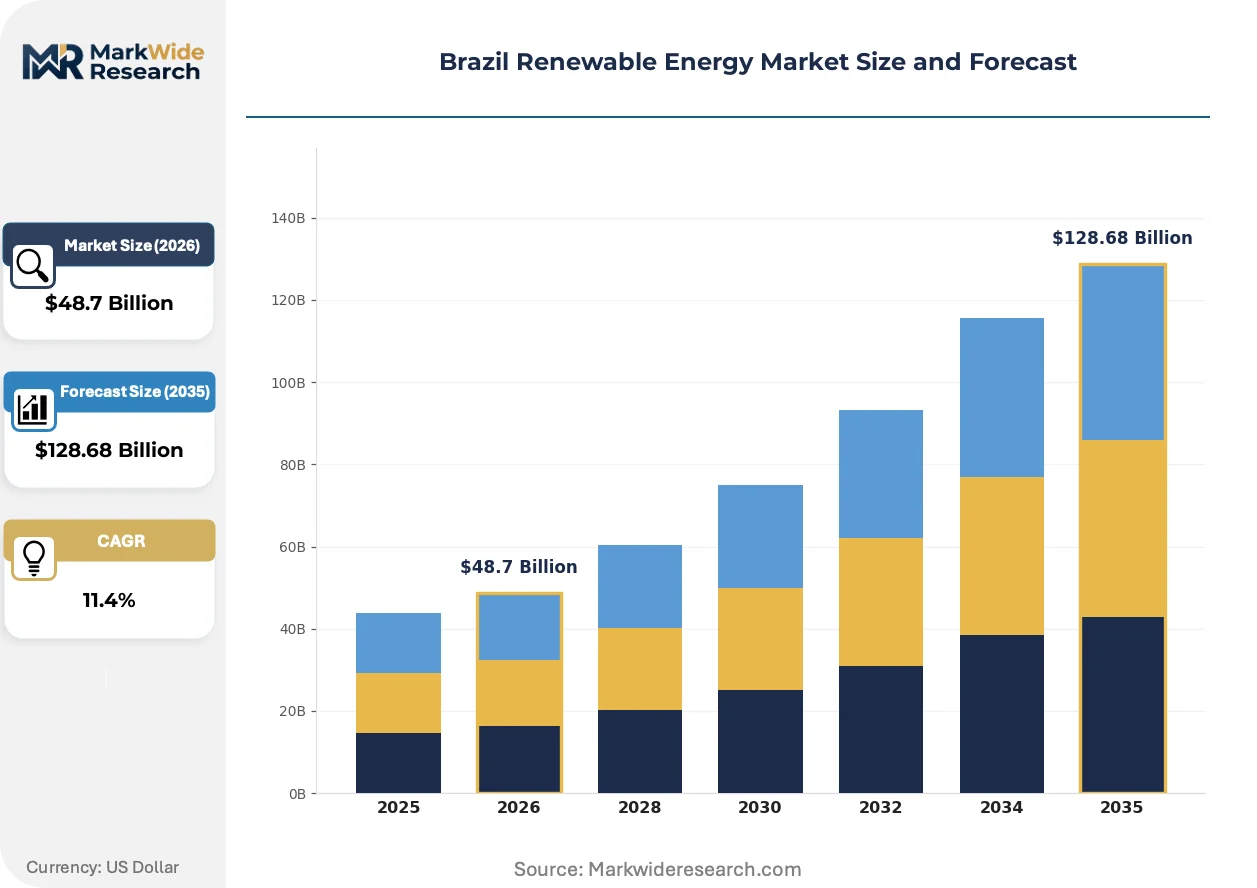
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Biomass, Hydro Technology: PV, Onshore Wind, Offshore Wind, Biogas End User: Residential, Commercial, Industrial, Utilities Installation: Grid-Connected, Off-Grid, Hybrid Systems, Microgrids |
| Companies Covered | Enel Green Power Brasil, Alupar Investimento, Eletrobras, CEMIG, Energisa, ENGIE Brasil Energia, CPFL Renováveis, Copel, Neoenergia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Renewable Energy Market Emerging Trajectories
Technology convergence and regulatory recalibration are compressing development timelines while fragmenting competitive advantage across hardware, software, and financing capabilities.
Bifacial solar modules with tracking systems is hybridizing project returns in the São Francisco River valley. Agribusiness cooperatives in Bahia and Pernambuco are deploying these configurations to maximize energy yield per hectare leased. The technology is hybridizing traditional fixed-tilt economics with agricultural land-use efficiency, forcing EPC contractors to integrate agronomic consulting into engineering workflows.
ANEEL's recent distributed generation compensation rulemaking is tightening grid access tariffs for systems above 75kW while expanding net metering eligibility for low-income consumers. The regulation compresses payback periods for residential rooftop installations in São Paulo's metropolitan zone. Commercial off-takers in Campinas and Sorocaba are accelerating lease-to-own structures to lock in grandfathered rates before scheduled tariff adjustments.
Corporate renewable energy procurement through virtual power purchase agreements is displacing traditional auction participation among multinational manufacturers. Food processing and pulp conglomerates in Santa Catarina and Paraná are negotiating sleeved contracts directly with wind farms in Rio Grande do Norte. This channel shift concentrates creditworthy offtaker pools while bypassing distribution utility intermediaries entirely.
Brazil Renewable Energy Market Segmentation
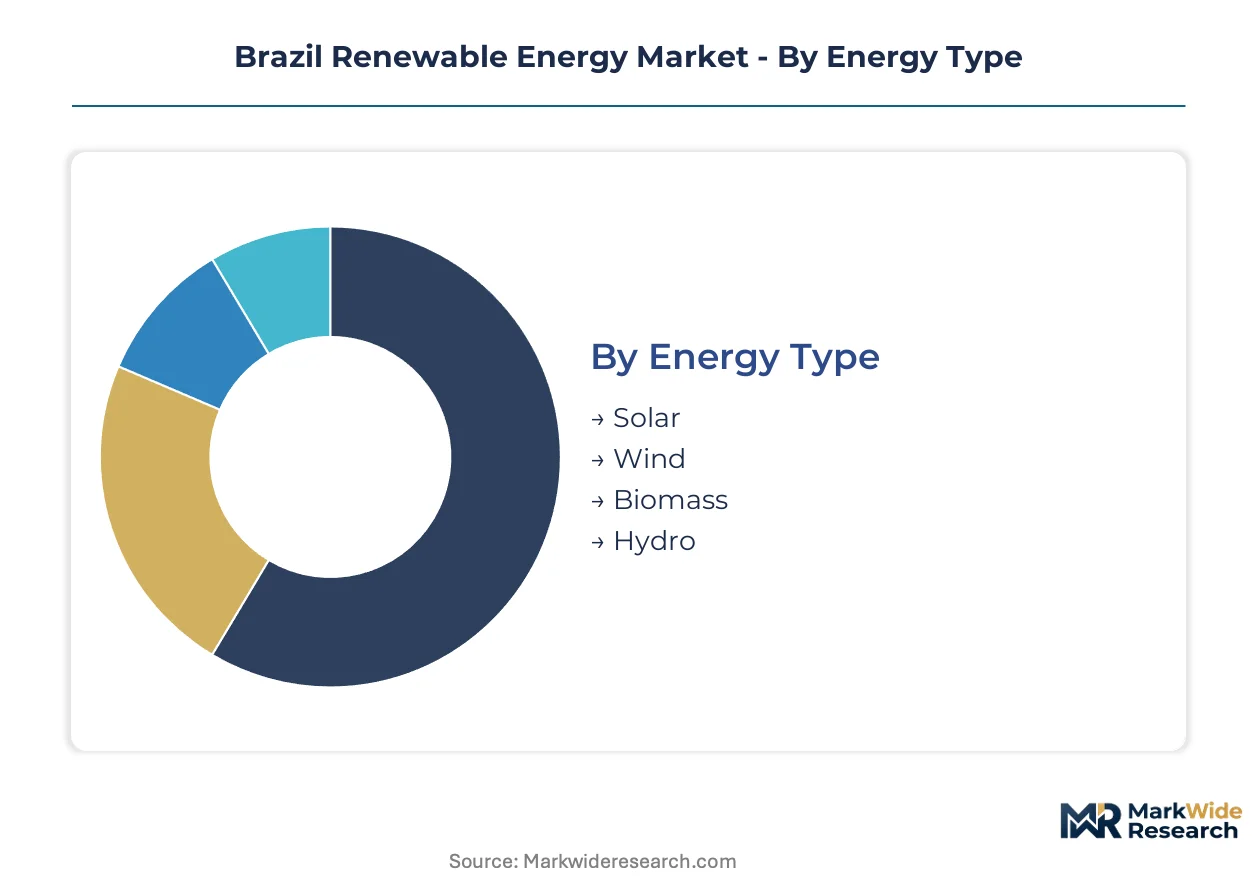
Brazil's renewable energy market fragments across four distinct category axes. Each dimension reveals divergent capital intensity profiles and regulatory exposure that shape developer strategy and investor allocation decisions.
Energy Type:
Mature baseload technologies coexist with emerging variable sources as ANEEL's auction mechanisms recalibrate revenue certainty across the spectrum.
- Solar:Photovoltaic conversion dominates new capacity additions, with crystalline silicon modules capturing high irradiance in the Northeast's semi-arid zone. Utility-scale projects in Piauí and Ceará attract development bank financing, though currency volatility on Asian module imports compresses margins.
- Wind:Onshore turbines deliver the highest capacity factors among variable sources, with concentrated development in Rio Grande do Norte and Bahia coastal corridors. Transmission congestion to southeastern load centers forces seasonal curtailment during peak generation months.
- Biomass:Bagasse-fired cogeneration sustains baseload supply through sugarcane harvest windows. São Paulo state mills integrate electricity sales with ethanol production, though feedstock seasonality requires thermal backup investments.
- Hydro:Run-of-river systems anchor grid stability services, leveraging Eletrobras legacy infrastructure for frequency regulation. Limited greenfield potential constrains expansion to small-scale projects in Amazon tributaries.
Solar handles the majority of throughput; wind is the fastest mover on share.
Technology:
Cost tier stratification separates bankable proven configurations from pre-commercial alternatives seeking demonstration scale.
- PV:Bifacial modules with single-axis tracking hybridize project returns in the São Francisco River valley. Agribusiness cooperatives in Bahia deploy these configurations to maximize energy yield per hectare leased.
- Onshore Wind:Turbines exceeding 4MW capacity factor optimize generation density in Rio Grande do Norte trade wind corridors. Specialized electrical technicians for 500kV substation commissioning command wage premiums that compress developer margins.
- Offshore Wind:Floating platform concepts remain pre-commercial, constrained by port infrastructure limitations and environmental licensing complexity in southeastern coastal zones.
- Biogas:Anaerobic digesters process agricultural residue and landfill methane for distributed generation. Pernambuco dairy cooperatives pilot captive power applications exempt from centralized interconnection queues.
PV commands the installed base; biogas is expanding most quickly in rural distributed applications.
End User:
Customer type determines contracting structure, creditworthiness thresholds, and exposure to regulated tariff adjustments.
- Residential:Rooftop systems below 75kW benefit from grandfathered net metering rates in São Paulo's metropolitan zone. ANEEL's recent rulemaking compresses payback periods for low-income consumers while tightening access tariffs for larger installations.
- Commercial:Campinas and Sorocaba off-takers accelerate lease-to-own structures to lock in distributed generation compensation before scheduled tariff adjustments. Shopping centers and logistics facilities prioritize behind-the-meter solar for demand charge management.
- Industrial:Iron ore and steel producers in Minas Gerais execute power purchase agreements for clean electricity to meet Scope 3 emissions targets. Mining operations in Pará negotiate sleeved contracts directly with wind farms, bypassing distribution utility intermediaries.
- Utilities:State-owned distributors procure through ANEEL-administered auctions, securing long-term supply contracts indexed to inflation. Transmission expansion lags behind Northeast generation clusters, forcing procurement discipline during peak wind seasons.
Industrial offtakers drive contract innovation; residential deployment is climbing the fastest on system count.
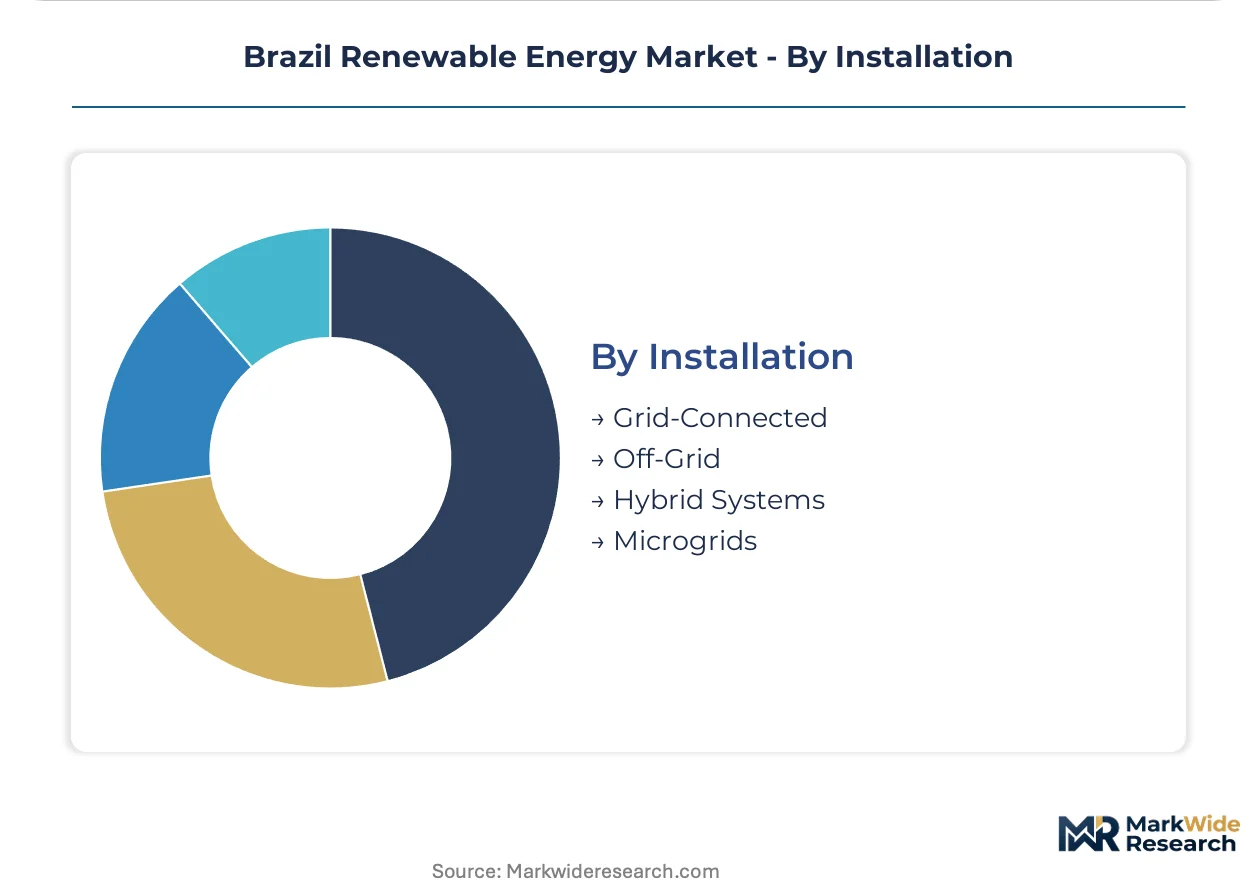
Installation:
Grid integration depth shapes capital requirements, regulatory jurisdiction, and operational autonomy.
- Grid-Connected:Utility-scale projects occupy the largest revenue pool, requiring ANEEL concession agreements and transmission access permits. Voltage ride-through and frequency response mandates demand inverter retrofits on older wind farms.
- Off-Grid:Remote Amazon communities in Amazonas and Roraima states present solar-plus-storage deployments exempt from centralized interconnection queues. Diesel displacement economics improve with battery cost declines.
- Hybrid Systems:Solar-wind-battery configurations optimize capacity utilization in resource-complementary locations. Port complexes in Pecém and Suape position to electrolyze wind power for green hydrogen export.
- Microgrids:Riverine settlements and indigenous territories deploy containerized generation with minigrid distribution. Federal subsidies under the Luz para Todos program reduce capital barriers in unelectrified areas.
Grid-connected installations handle the majority of throughput; microgrids are gaining share fastest in frontier regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Brazil's states diverge sharply between industrial mining corridors and agricultural zones, with each region deploying renewable technologies suited to local resource endowments and grid infrastructure maturity.
São Paulo
Industrial manufacturers and data centers in Campinas and Sorocaba execute distributed solar leases to manage demand charges. ANEEL's net metering revisions compress payback periods for commercial installations above 75kW. The metropolitan zone anchors southeast load growth that pulls power from distant Northeast wind clusters.
Minas Gerais
Iron ore and steel producers negotiate sleeved power purchase agreements to satisfy Scope 3 emissions targets. The state's sugarcane belt sustains bagasse-fired cogeneration through integrated ethanol-electricity mills. Belo Horizonte's industrial corridor concentrates corporate renewable procurement activity.
Rio Grande do Norte
Trade wind corridors deliver the highest onshore capacity factors among Brazilian states, attracting utility-scale turbine deployment. Transmission congestion to southeastern load centers forces seasonal curtailment during peak generation months. Natal's port infrastructure supports turbine component import logistics.
Bahia
Agribusiness cooperatives deploy bifacial solar with single-axis tracking across the São Francisco River valley to maximize energy yield per hectare leased. The state's coastal wind zones complement interior solar irradiance in hybrid project configurations. Salvador anchors transmission interconnection for Northeast generation exports.
Pará
Remote Amazon mining operations pioneer off-grid solar-plus-storage deployments exempt from centralized interconnection queues. Diesel displacement economics improve with battery cost declines in riverine communities. Belém's industrial zone explores green hydrogen integration for export-oriented ammonia production.
Brazil Renewable Energy Market Vendor Landscape
Capability concentration sits with legacy utility incumbents possessing grid access rights and concession experience; scale advantage sits with international developers deploying capital through auction mechanisms. The market structures around three tiers: state-owned hydro anchors, diversified renewable independents, and foreign-owned project specialists. Dominant competitive moves include portfolio diversification across solar-wind-biomass mixes and strategic partnerships to secure transmission interconnection priority.
Within the state-owned tier, Eletrobras leverages legacy hydro infrastructure to anchor grid stability services. Among diversified independents, CPFL Renováveis and ENGIE Brasil Energia exemplify contrasting geographic specializations—CPFL concentrates distributed solar in southeastern commercial markets while ENGIE occupies onshore wind positions in Rio Grande do Norte and Bahia coastal corridors. These three entities represent distinct competitive archetypes: concession-based incumbent, regional distributed specialist, and international utility-scale developer.
| Leading Market Players |
|---|
| Enel Green Power Brasil |
| Alupar Investimento |
| Eletrobras |
| CEMIG |
| Energisa |
| ENGIE Brasil Energia |
| CPFL Renováveis |
| Copel |
| Neoenergia |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Northeast wind turbine manufacturing is compressing EPC margins while simultaneously accelerating module procurement from Asian crystalline silicon suppliers. This utilization imbalance forces developers to absorb currency volatility on imported hardware or sacrifice project returns to secure domestic balance-of-plant contracts.
Pricing Analysis
Long-term offtake contracts through ANEEL-administered auctions dominate revenue structures, with inflation-indexed tariffs separating utility-scale wind from distributed solar economics. Price differentiation rests on interconnection priority and grandfathered net metering status, with commercial off-takers in São Paulo's metropolitan zone exhibiting highest sensitivity to tariff adjustments. Pricing pressure stems from transmission congestion discounts in Rio Grande do Norte, while industrial mining buyers in Minas Gerais show least price sensitivity due to Scope 3 compliance mandates.
Supply Chain Analysis
Contract manufacturing concentration for solar modules sits with Chinese, Vietnamese, and Malaysian foundries holding crystalline silicon wafer capacity. Brazil's developer ecosystem draws from polysilicon feedstocks, glass substrates, and aluminum framing components anchored in Asian production clusters. Single-source vulnerability on inverter electronics creates exposure to maritime freight bottlenecks through the Panama Canal. Distribution runs through domestic EPC contractors who integrate imported hardware with local civil works and grid interconnection services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's renewable energy sector is cycling through a capital deployment upswing as ANEEL auction schedules accelerate and transmission expansion in the Northeast corridor advances. This recovery phase rewards developers with secured interconnection rights and penalizes late entrants facing queue backlogs.
For Market Incumbents: Pre-empt margin erosion in utility-scale wind by securing captive module supply through backward integration into Asian manufacturing partnerships. Defend distributed generation positioning in São Paulo and Minas Gerais by accelerating lease-to-own structures before ANEEL's scheduled tariff adjustments compress grandfathered rate advantages.
For New Entrants and Emerging Players: Establish a beachhead in Amazon microgrid deployments exempt from centralized interconnection queues, where federal Luz para Todos subsidies reduce capital barriers. Target agrivoltaic configurations in Mato Grosso soybean plantations, leveraging dual-use land efficiency premiums to differentiate from commodity solar developers competing on irradiance alone.
For Investors and Strategic Acquirers: Capital is best deployed toward developers holding ANEEL concession agreements with approved environmental licenses in Rio Grande do Norte and Bahia coastal corridors. Long-term viability over the projection horizon hinges on transmission expansion timelines; monitor interconnection queue clearance rates as the inflection signal for capacity factor realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Industrial mining offtakers in Minas Gerais and Pará secure Scope 3 compliance through sleeved contracts bypassing utility intermediaries. |
| Transmission Interconnection Priority | ANEEL queue positioning in Northeast corridors determines seasonal curtailment exposure and capacity factor realization. |
| Agrivoltaic Project Development | Dual-use solar installations over Bahia and Pernambuco agricultural leases capture land efficiency premiums unavailable to conventional developers. |
| Green Hydrogen Integration | Port complexes in Pecém and Suape electrolyze wind power for export-oriented ammonia and steel decarbonization feedstocks. |
| Microgrid Deployment | Remote Amazon communities in Amazonas and Roraima deploy solar-plus-storage exempt from centralized grid access constraints. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with utility planning officers, IPP project developers, EPC contractors, and ANEEL regulatory staff; and secondary validation through EIA generation databases, IEA renewable energy reports, ANEEL auction result filings, and transmission expansion project registries. Bottom-up capacity addition modeling triangulated against top-down investment flow analysis from development bank disbursement records.
Forecast inputs incorporated project pipeline tracking across the analysis window, with segmentation modeling across fuel source, generation capacity tier, regulatory framework, and regional grid type. CAGRs were derived from auction schedule trajectories and interconnection queue clearance assumptions, stress-testing against module cost decline curves and currency volatility bands.
Stress conditions across transmission expansion delays, ANEEL tariff rulemaking revisions, and Asian supply chain disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of interconnection queue clearance rates and auction participation ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market