
 Switzerland Renewable Energy Market | 2026-2036
Switzerland Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Renewable Energy Market Analytics
Alpine reservoir operators is restructuring seasonal storage protocols to balance intermittent solar and wind influx across Switzerland's mountainous grid topology. Axpo Holding AG leverages its pumped-hydro fleet to anchor baseload reliability for industrial offtakers in northern cantons. BKW Energie AG sustains a dense network of run-of-river assets along the Aare basin. Repower AG specializes in cross-border renewable trading, competing for premium green tariffs with German and Italian buyers.
Switzerland renewable energy encompasses electricity generation from hydroelectric, solar, wind, and biomass resources, typically harnessed through photovoltaic arrays, turbine generators, or fuel cell systems with operational lifespans exceeding twenty-five years and carbon intensities below fifty grams per kilowatt-hour. These installations serve utilities, government facilities, residential buildings, and industrial enterprises seeking compliance with federal carbon-reduction mandates. Hydroelectric remains the dominant energy source, supplying the majority of Swiss renewable output from mature alpine infrastructure with limited greenfield expansion potential. Photovoltaic technology is accelerating fastest among technology types, driven by declining module costs and streamlined permitting for residential and commercial rooftop systems across the Swiss Plateau.
Swissmedic does not regulate this sector, but the Swiss Federal Office of Energy enforces the Energy Strategy 2050 framework mandating nuclear phase-out and renewable substitution targets, while the Federal Electricity Commission oversees grid access tariffs and interconnection standards for distributed generators. Cantonal building codes increasingly mandate solar-ready roofing for new construction, tightening product standards for photovoltaic mounting systems and inverters. Stakeholders must monitor forthcoming revisions to feed-in tariff structures and cross-border capacity allocation mechanisms as Switzerland deepens electricity market integration with the European Union.
Market Dynamics
The Swiss Federal Office of Energy enforces Energy Strategy 2050 mandates requiring nuclear phase-out completion by 2034, forcing immediate capital redeployment toward alpine hydroelectric refurbishment and distributed photovoltaic expansion across the Swiss Plateau.
Growth Catalysts
- Alpine reservoir modernization:Cantonal utilities are retrofitting seasonal pumped-hydro storage to buffer intermittent solar influx. Federal subsidies under the revised feed-in tariff mechanism accelerate project approvals.
- Energy Strategy 2050:The federal framework mandates renewable substitution targets that eliminate nuclear baseload. Industrial offtakers in Zurich and Basel cantons now contract directly with run-of-river operators.
- Photovoltaic module cost compression:Declining silicon prices and streamlined cantonal permitting enable rooftop installations at commercial and residential scale. Swiss Plateau municipalities lead deployment density.
Market Restraints
- Grid topology constraints:Mountainous terrain limits transmission capacity between alpine generation basins and northern industrial load centers. Reinforcement projects face decade-long environmental review timelines.
- Seasonal generation mismatch:Hydroelectric output peaks during spring snowmelt while heating demand concentrates in winter months. Storage arbitrage economics remain marginal without capacity market mechanisms.
- Limited greenfield hydro potential:Protected alpine watersheds under federal environmental law block new large-scale reservoir development. Expansion relies entirely on efficiency gains at existing assets.
Strategic Opportunities
- Cross-border capacity trading:Swissgrid integration with EU electricity markets enables premium green tariff exports to German industrial buyers. Repower AG and comparable traders arbitrage price differentials across Alpine transit corridors.
- Solar-ready building mandates:Revised cantonal building codes in Vaud, Geneva, and Zurich mandate photovoltaic-compatible roofing for new commercial construction. Mounting system and inverter suppliers capture specification lock-in.
- Alpine wind development:Emerging turbine technologies designed for high-altitude, low-temperature operation unlock previously uneconomic ridgeline sites. Valais and Graubünden cantons pilot test installations.
Industry Challenges
- Grid interconnection queues:Distributed generator backlogs at Federal Electricity Commission exceed thirty-six months in high-demand cantons. Project developers face carrying cost erosion during regulatory limbo.
- Alpine construction logistics:Seasonal access restrictions and helicopter-dependent heavy equipment transport inflate civil works costs for remote hydroelectric refurbishment. Specialized contractor capacity is fully committed through 2028.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Renewable Energy Market |
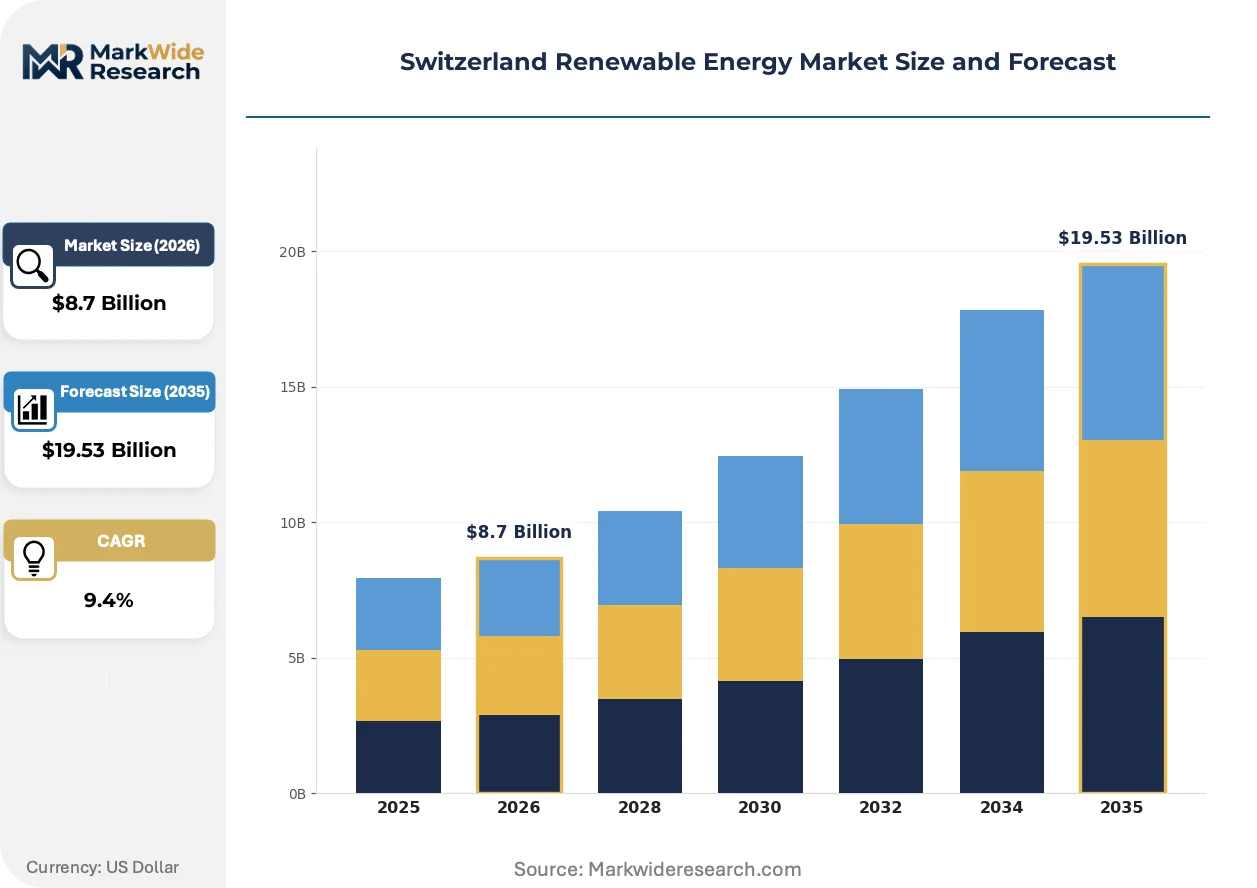
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Hydroelectric, Solar, Wind, Biomass Technology Type: Photovoltaic, Concentrated Solar Power, Turbines, Fuel Cells Installation Type: Utility Scale, Residential, Commercial, Off-Grid End User: Utilities, Government, Residential Users, Industrial Enterprises |
| Companies Covered | Repower AG, SGS Renewable Energy, Axpo Holding AG, PVsyst SA, Renergon International AG, BKW Energie AG, Romande Energie Holding SA, Entec AG Consulting & Engineering, Alpiq Holding AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Renewable Energy Market Evolving Landscape
Digitalization of Switzerland's mountainous grid infrastructure is compressing dispatch response times and enabling granular price signals that reshape how alpine utilities monetize flexibility assets.
Hybrid inverter architectures are unifying photovoltaic generation with behind-the-meter battery storage in single power conversion stages. Commercial building operators in Zurich and Geneva cantons are adopting these systems to minimize grid import during peak tariff windows. This technology convergence is unifying hardware procurement decisions that previously separated solar and storage vendors into consolidated supplier relationships.
The Federal Electricity Commission revised grid access tariff structures in 2024 to incorporate locational marginal pricing for distributed generators. Industrial offtakers now face real-time cost signals that reward consumption flexibility. Northern canton manufacturing facilities are responding by installing automated load-shedding systems that synchronize with alpine hydroelectric dispatch patterns.
Corporate power purchase agreements are displacing traditional utility tariffs among Swiss pharmaceutical and precision manufacturing clusters. Basel-Land chemical facilities now contract directly with Valais hydroelectric operators through fifteen-year fixed-price structures. This procurement evolution concentrates credit-worthy offtaker demand and fragments the historical utility monopoly over large-load customer relationships.
Switzerland Renewable Energy Market Segmentation
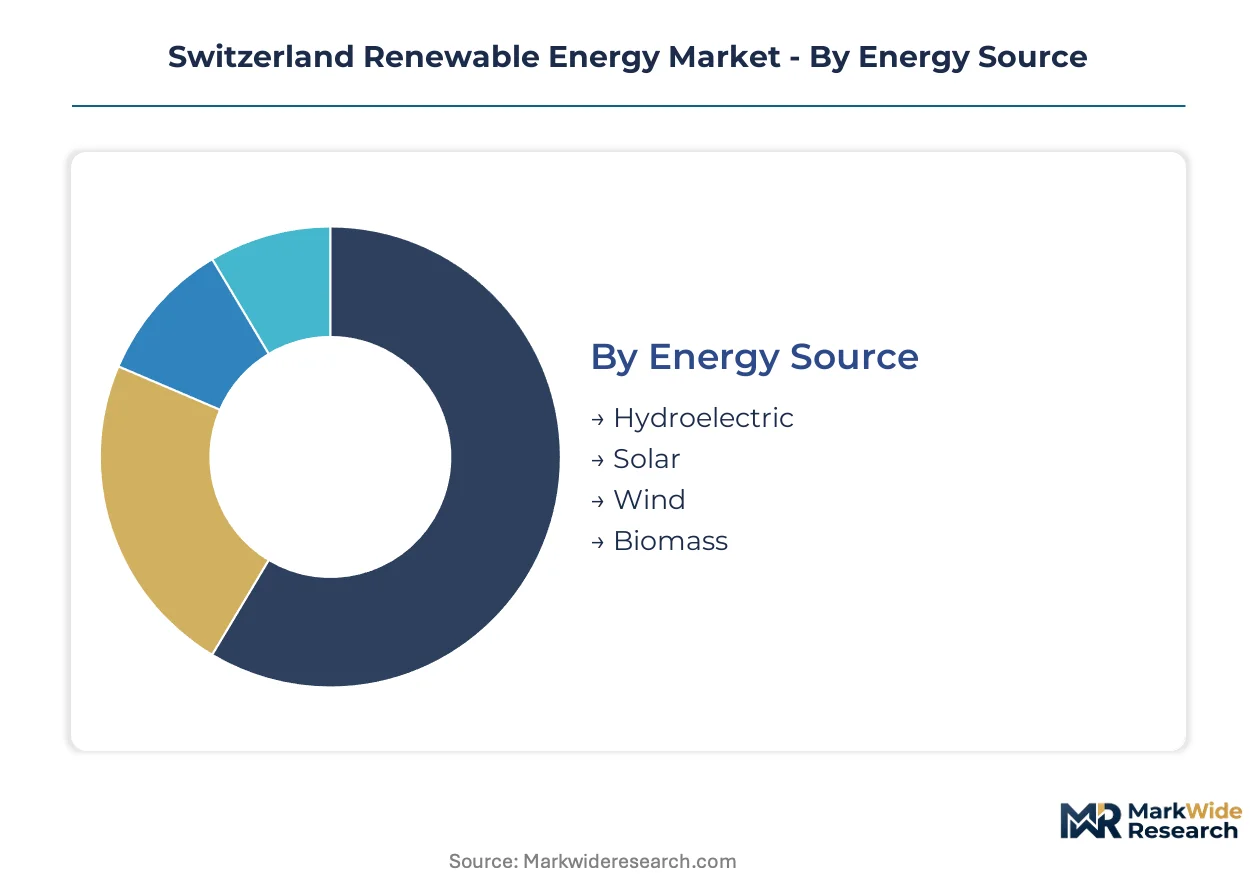
Switzerland's renewable energy market segments reveal divergent capital cycles and regulatory exposure across generation technologies. Understanding these partitions clarifies where alpine utilities deploy refurbishment budgets versus where distributed solar attracts new entrants.
Energy Source:
Upgrade timelines vary dramatically across Switzerland's generation mix, with mature hydroelectric assets requiring sustained reinvestment while emerging solar and wind technologies scale from smaller bases.
- Hydroelectric:Alpine reservoir and run-of-river installations constitute the foundational generation layer, with seasonal pumped-storage facilities providing grid-balancing services. Cantonal utilities in Valais and Graubünden concentrate refurbishment spending on turbine efficiency upgrades and digital control systems, driven by Energy Strategy 2050 mandates that preserve this baseload capacity through the nuclear phase-out.
- Solar:Photovoltaic arrays across the Swiss Plateau capture the steepest deployment acceleration, with rooftop and ground-mounted systems benefiting from streamlined permitting and module cost compression. Zurich and Geneva cantons lead installation density as commercial building operators seek tariff arbitrage against peak grid pricing.
- Wind:Ridgeline turbine installations remain nascent, constrained by alpine construction logistics and visual impact restrictions. Pilot projects in high-altitude zones test cold-climate turbine designs.
- Biomass:Agricultural and forestry waste-to-energy facilities supply distributed heat and power, primarily serving rural cantonal heating networks with limited expansion potential.
Volume placements concentrate in Hydroelectric; the faster expansion belongs to Solar.
Technology Type:
Cost tier differentiation separates mature mechanical systems from semiconductor-based power electronics, with hybrid architectures collapsing procurement categories that previously operated independently.
- Photovoltaic:Silicon-based modules dominate Swiss solar deployment, with monocrystalline panels capturing premium rooftop segments and polycrystalline alternatives serving utility-scale ground installations. Mounting system suppliers in Vaud and Basel-Land cantons integrate tracking mechanisms for alpine latitude optimization.
- Turbines:Francis and Pelton turbine configurations anchor hydroelectric refurbishment programs, with variable-speed drives replacing fixed-speed legacy equipment. Alpine contractors face fully committed capacity through 2028 for heavy transport and installation logistics.
- Concentrated Solar Power:Thermal collection systems remain absent from Swiss deployment due to limited direct normal irradiance at northern latitudes and mountainous terrain shading.
- Fuel Cells:Stationary hydrogen fuel cell installations pilot at industrial microgrid sites, with Basel chemical clusters testing proton exchange membrane systems for backup power applications.
Revenue concentration sits with Turbines given hydroelectric dominance; Photovoltaic gains share fastest as distributed generation scales.
Installation Type:
Customer type and project scale determine regulatory pathway complexity, with utility-scale developments facing Federal Electricity Commission interconnection queues while behind-meter installations bypass centralized approval.
- Residential:Rooftop photovoltaic systems under 100 kW capacity proliferate across Swiss Plateau municipalities, with streamlined cantonal permitting and net metering tariffs accelerating homeowner adoption. Zurich building codes now mandate solar-ready roofing for new construction.
- Commercial:Mid-scale rooftop and carport installations serve manufacturing facilities, hospitals, and retail properties seeking direct consumption offset. Basel-Land pharmaceutical campuses contract hybrid solar-plus-storage systems to minimize grid import during peak tariff windows.
- Utility Scale:Large photovoltaic parks and alpine hydroelectric refurbishment projects require Federal Electricity Commission grid access agreements, with interconnection backlogs exceeding thirty-six months in high-demand northern cantons.
- Off-Grid:Remote alpine lodges and telecommunications infrastructure deploy standalone solar-battery systems, with helicopter-dependent logistics inflating installed costs relative to grid-connected alternatives.
Project volume clusters in Utility Scale given hydroelectric refurbishment scale; Commercial segment climbs fastest as building-integrated solar mandates expand.
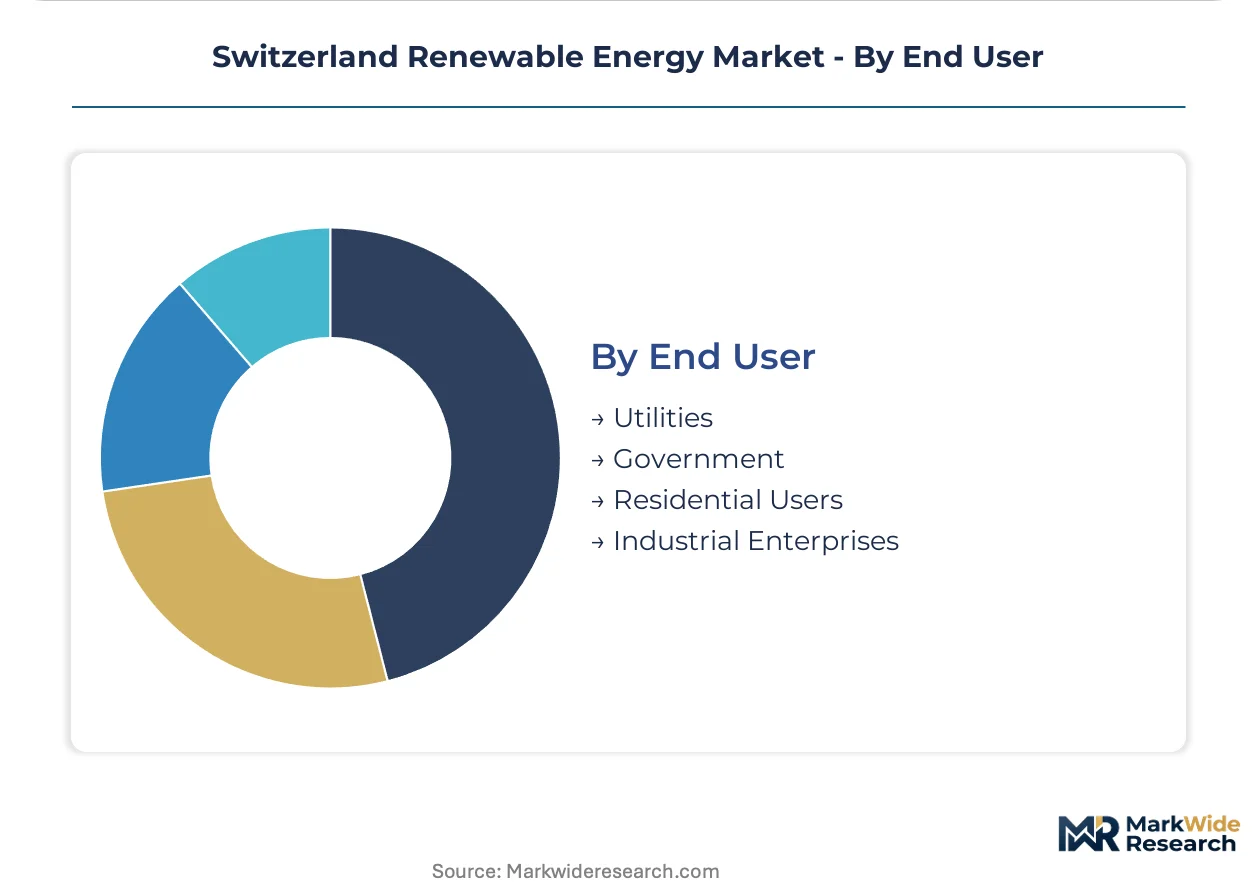
End User:
Procurement authority and credit quality segment the demand base, with industrial offtakers now bypassing traditional utility intermediaries through direct power purchase agreements.
- Industrial Enterprises:Basel chemical facilities and Zurich precision manufacturing clusters contract directly with alpine hydroelectric operators through fifteen-year fixed-price structures. Corporate procurement teams prioritize baseload renewable certificates for carbon disclosure compliance.
- Utilities:Cantonal and municipal utilities retain transmission and distribution functions while ceding generation ownership to specialized renewable developers. Axpo Holding AG and BKW Energie AG restructure asset portfolios toward flexibility services and trading optimization.
- Government:Federal and cantonal facilities procure renewable electricity through centralized tendering, with Defense Department and hospital networks specifying Swiss-origin guarantees of origin.
- Residential Users:Household consumers select green tariff products from retail suppliers, with limited price differentiation between renewable and conventional offerings dampening active switching behavior.
Contract value concentrates in Industrial Enterprises; Utilities segment expands most quickly as corporate procurement fragments traditional monopoly relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine topography and glacial hydrology anchor Switzerland's renewable resource base, with cantonal utilities leveraging elevation differentials for pumped-storage arbitrage while the Swiss Plateau captures solar irradiance for distributed generation expansion.
Zurich
Precision manufacturing clusters in Winterthur and Schlieren drive corporate power purchase agreements for baseload hydroelectric supply. The cantonal building code mandates solar-ready roofing for commercial new construction, accelerating photovoltaic specification lock-in. Zurich utilities retrofit urban substations to accommodate behind-meter battery inflows from hybrid solar-storage systems.
Geneva
International organization campuses and pharmaceutical headquarters procure Swiss-origin guarantees of origin for carbon disclosure compliance. The canton enforces net-zero building standards that elevate heat pump and photovoltaic penetration in residential construction. Carport solar installations at Cointrin airport logistics facilities demonstrate commercial-scale deployment density.
Valais
Alpine reservoir operators concentrate seasonal pumped-hydro refurbishment spending on turbine efficiency upgrades and digital control systems. The Federal Office of Energy channels federal subsidies toward this cantonal utility infrastructure to preserve baseload capacity through nuclear phase-out. Industrial offtakers in Martigny and Sion contract directly for fifteen-year fixed-price structures.
Basel-Land
Chemical facilities in Muttenz and Pratteln anchor demand for run-of-river hydroelectric supply from Aare basin operators. Cantonal permitting streamlines hybrid solar-plus-storage installations that minimize grid import during peak tariff windows. Basel utilities pilot proton exchange membrane fuel cells for industrial microgrid backup applications.
Vaud
Lausanne metropolitan building stock integrates photovoltaic arrays at accelerating density under revised solar-ready mandates. The cantonal energy office coordinates with Federal Electricity Commission on distributed generator interconnection standards. Alpine wind pilot projects in the Prealps test cold-climate turbine designs for ridgeline deployment.
Switzerland Renewable Energy Market Competitive Landscape
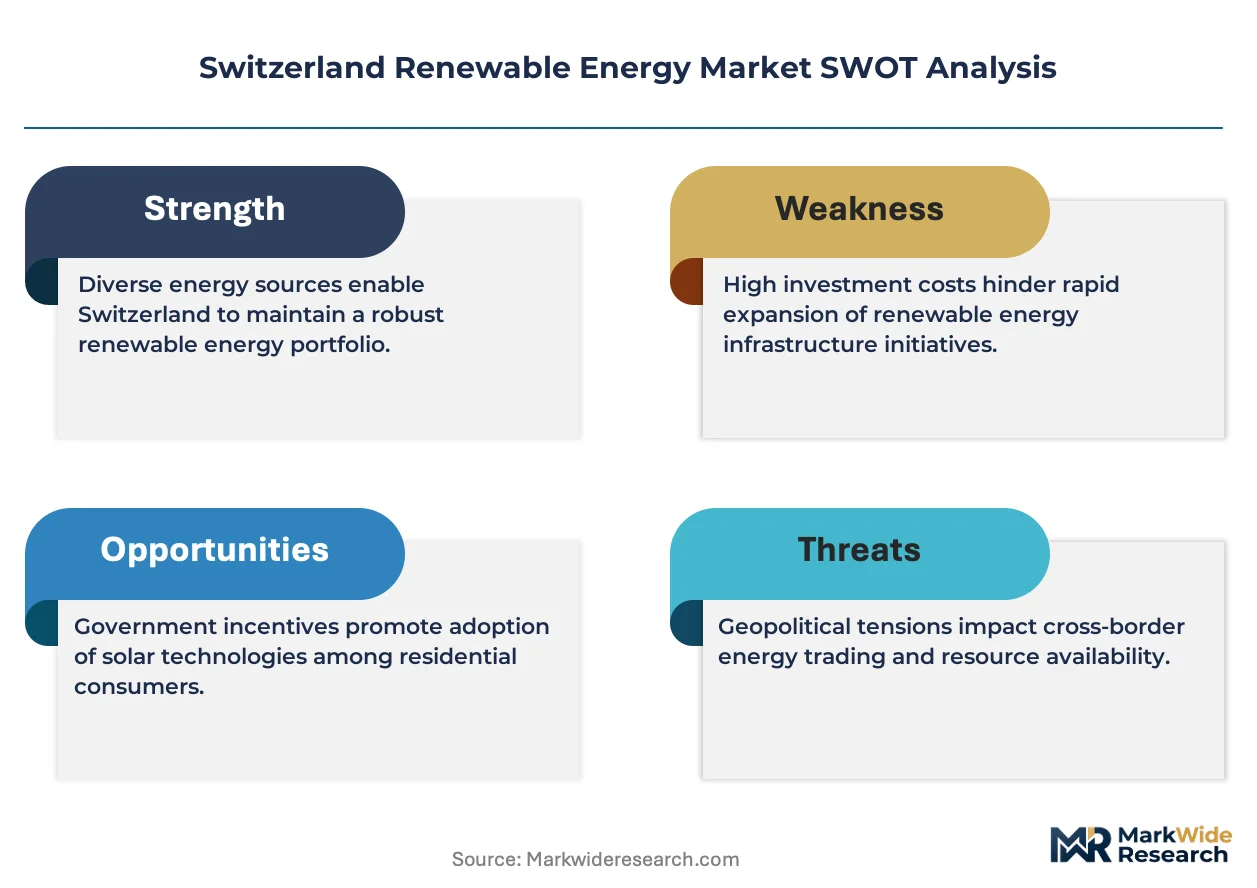
Global energy majors compete with regional champions across alpine hydroelectric refurbishment and cross-border trading optimization. The vendor base clusters around three functional tiers: cantonal utilities with captive generation assets, specialized renewable developers targeting distributed solar, and cross-border traders arbitraging price differentials. Two dominant competitive moves are reshaping positioning: portfolio restructuring toward flexibility services and direct corporate power purchase agreement origination that fragments traditional utility-customer relationships.
Within the integrated utility tier, Axpo Holding AG and BKW Energie AG exemplify asset-heavy positioning anchored by alpine hydroelectric fleets and run-of-river networks. Repower AG occupies a distinct archetype as a cross-border renewable trader, leveraging Swissgrid integration with EU electricity markets to capture premium green tariff exports. These three Swiss AG-structured entities represent divergent strategic responses to Energy Strategy 2050 mandates, with capital deployment concentrating on refurbishment efficiency, distributed generation origination, and trading optimization respectively.
| Leading Market Players |
|---|
| Repower AG |
| SGS Renewable Energy |
| Axpo Holding AG |
| PVsyst SA |
| Renergon International AG |
| BKW Energie AG |
| Romande Energie Holding SA |
| Entec AG Consulting & Engineering |
| Alpiq Holding AG |
| Others |
Value Network & Pricing Analysis
Warranty-bundling divergence between alpine hydroelectric refurbishment contracts and distributed solar installations manifests in both pricing structures and supplier selection criteria across Switzerland. Premium service tiers for turbine overhaul work incorporate multi-year performance guarantees from specialized alpine contractors, while photovoltaic procurement unbundles hardware from installation warranties to accelerate residential uptake under cantonal building mandates.
Pricing Analysis
Service-bundling configurations separate long-term performance contracts for alpine hydroelectric assets from transactional hardware sales in distributed solar markets. Project-based pricing dominates turbine refurbishment, with premium tiers commanding extended warranty coverage and guaranteed availability commitments from cantonal utilities. Price differentiation reflects certification grade under Federal Electricity Commission interconnection standards and geographic delivery costs to remote alpine sites. Cost compression in photovoltaic modules intensifies pricing pressure for residential installers as silicon supply expands. Industrial offtakers in Basel-Land chemical clusters demonstrate lowest price sensitivity, prioritizing fifteen-year baseload guarantees over per-kilowatt-hour optimization.
Supply Chain Analysis
Direct-to-utility channels handle alpine hydroelectric refurbishment demand, while distributor networks serve fragmented residential solar procurement across Swiss Plateau municipalities. Component manufacturing concentrates in Germany, China, and South Korea for photovoltaic modules and power electronics. Turbine refurbishment draws from specialized alpine contractor capacity in Switzerland and Austria. Raw material dependencies span silicon wafers, rare-earth magnets for generators, and high-grade steel for penstock systems. Single-source vulnerability persists for helicopter-dependent heavy transport to remote alpine reservoirs. Distribution runs through cantonal utility procurement offices for large-scale assets and electrical wholesalers for behind-meter installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around capital discipline as Federal Electricity Commission interconnection backlogs exceed thirty-six months and specialized alpine contractor capacity remains fully committed through 2028, forcing undercapitalized developers into distressed asset sales.
For Market Incumbents: Anchor baseload reliability positioning through selective pumped-hydro refurbishment investments in Valais and Graubünden cantons. Acquire distressed distributed solar portfolios from developers stalled in interconnection queues to consolidate Swiss Plateau market presence. Defend against emerging cross-border traders by locking fifteen-year corporate power purchase agreements with Basel-Land chemical facilities before Swissgrid integration deepens EU market access. For New Entrants and Emerging Players: Begin with commercial building-integrated solar mandates in Vaud and Zurich cantons where streamlined permitting accelerates deployment velocity. Target hybrid inverter and behind-meter battery storage configurations for pharmaceutical campuses seeking peak tariff arbitrage. Pursue direct EPC contracting relationships with cantonal energy offices rather than competing for utility-scale generation tenders dominated by established alpine operators. For Investors and Strategic Acquirers: Re-rating potential sits with specialized alpine contractors holding secured turbine refurbishment backlogs given Federal Office of Energy subsidy continuity through nuclear phase-out completion. Long-term viability favors asset-light trading and optimization platforms over capital-intensive generation ownership. Monitor Swissgrid cross-border capacity allocation mechanism revisions as the inflection signal for premium green tariff export economics.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate Power Purchase Agreement | Basel-Land chemical facilities bypass traditional utility intermediaries through direct fifteen-year fixed-price structures. |
| Alpine Reservoir Modernization | Cantonal utilities retrofit seasonal pumped-hydro storage to buffer intermittent solar influx under federal subsidy mechanisms. |
| Hybrid Solar-Plus-Storage Deployment | Commercial building operators in Zurich minimize grid import during peak Federal Electricity Commission tariff windows. |
| Cross-Border Capacity Trading | Repower AG and comparable traders arbitrage Swissgrid integration with EU electricity markets for premium green exports. |
| Solar-Ready Building Mandate Compliance | Vaud and Geneva cantons mandate photovoltaic-compatible roofing, capturing specification lock-in for mounting system suppliers. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings in this analysis. Primary fieldwork engaged cantonal energy office directors, alpine reservoir operators, and commercial building facility managers across Zurich, Geneva, Valais, Basel-Land, and Vaud. Secondary validation drew from Federal Office of Energy strategy documents, Federal Electricity Commission tariff filings, Swissgrid interconnection data, and cantonal building code revisions. Bottom-up project pipeline assessment triangulates against top-down macroeconomic indicators and regulatory mandate timelines.
Comparable-period anchoring to historical deployment trajectories from Energy Strategy 2050 implementation phases shapes the projection horizon. The analytical framework segments by energy source, technology type, installation scale, and end-user procurement authority across the modeling period. CAGRs derive from capacity addition run-rates, refurbishment spending patterns, and cross-border trade flow assumptions. Forecast inputs incorporate nuclear phase-out timeline adherence, photovoltaic module cost curves, and alpine contractor capacity utilization.
Underlying measurement precision varies by segment; utility-scale hydroelectric refurbishment carries tighter precision than emerging alpine wind pilots. Forecasts reflect assumptions regarding federal subsidy continuity, Swissgrid EU market integration pace, and cantonal building code enforcement consistency. Periodic stress-testing of base assumptions is recommended given regulatory revision risk and cross-border electricity market volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
In-Pipe Hydroelectric System Market