
 Net-Zero Energy Buildings Market | 2026-2036
Net-Zero Energy Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Net-Zero Energy Buildings Market Intelligence
LEED Zero certification is redrawing competitive boundaries for suppliers and integrators. Schneider Electric SE leverages its building management software stack to anchor large-scale commercial retrofits across North America and Europe. Siemens AG sustains R&D intensity in digital twin platforms that optimize HVAC-to-envelope coordination. Kingspan Group PLC dominates insulated panel systems, giving it upstream control over thermal performance specifications that gate zero-energy compliance.
Net-zero energy buildings are structures designed to produce as much energy as they consume annually, typically achieving this through high-performance envelopes with U-values below 0.15 W/m²K paired with on-site renewable generation and intelligent load management. The commercial segment leads absolute deployment because lease structures allow owners to recover efficiency investments through operating expense pass-throughs, while the residential category competes for policy attention as first-cost barriers persist for individual homeowners. Solar photovoltaic technology occupies the largest technology share due to modular scalability, though energy storage systems are the fastest-expanding category as grid-interactive requirements tighten.
The EU Green Deal and national building performance standards are compressing retrofit timelines across member states, while the EPA and FERC shape U.S. demand through emissions benchmarking rules and interconnection protocols for distributed generation. Japan's METI enforces stringent Top Runner standards that effectively mandate near-zero performance for new construction. Stakeholders must monitor how rapidly evolving grid-interactive building codes rewrite the technical and economic assumptions underlying current technology roadmaps.
Market Dynamics
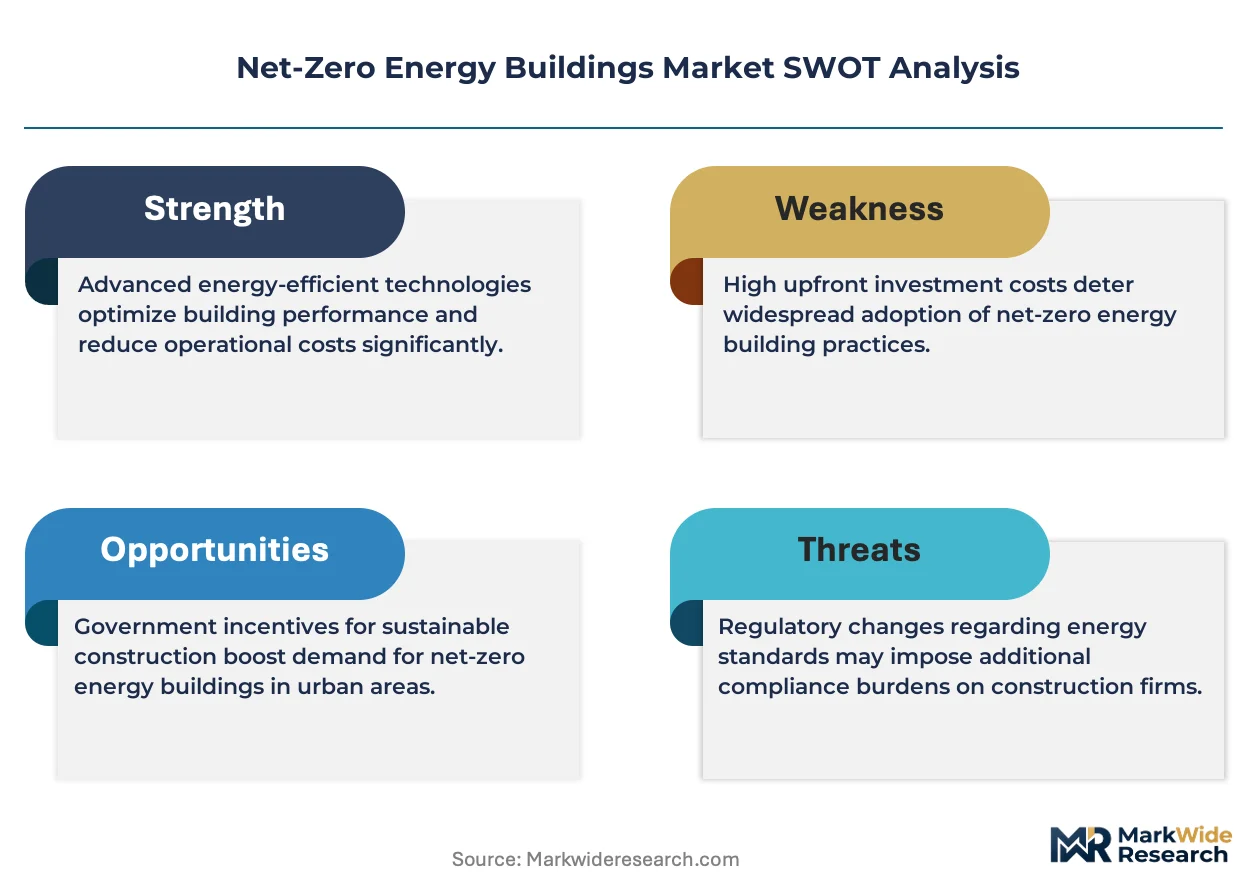
The EU Green Deal's building performance standards are compressing retrofit timelines across member states, forcing asset owners to accelerate deep renovation cycles and integrate on-site generation with envelope upgrades in single-project execution.
Growth Catalysts
- EnEV Regulatory Staircase:Germany's staged efficiency mandates ratchet minimum performance thresholds every three years, compelling commercial portfolios to front-load capital deployment ahead of compliance deadlines.
- Commercial Lease Structures:Triple-net and modified-gross agreements in North American office markets allow landlords to recover efficiency investments through operating expense pass-throughs, accelerating payback visibility.
- Photovoltaic Modularity:Rooftop and building-integrated solar systems scale without custom engineering, reducing project development timelines for mid-size commercial retrofits.
Market Restraints
- First-Cost Barriers:High-performance envelope assemblies with U-values below 0.15 W/m²K carry material premiums that individual residential buyers cannot amortize without subsidized financing.
- Grid Interconnection Queues:FERC jurisdictional delays for distributed generation interconnection protocols extend project commissioning timelines in U.S. metropolitan markets.
- Skill Scarcity:Certified Passive House trades and building energy modelers remain concentrated in Germany, Austria, and Switzerland, constraining project execution capacity elsewhere.
Strategic Opportunities
- KfW Efficiency Financing:Germany's subsidized loan and grant programs for deep renovation create replicable templates for public-private capital structures in underpenetrated Southern European markets.
- Grid-Interactive Buildings:Convergence of battery storage and demand-response software enables commercial assets to monetize flexibility services through wholesale market participation.
- Digital Twin Integration:Real-time HVAC-to-envelope coordination platforms reduce performance gaps between design intent and operational reality, opening recurring revenue streams for system integrators.
Industry Challenges
- Modeling Competency Gaps:Whole-building energy simulation requires specialized expertise in tools like EnergyPlus and IDA ICE that standard MEP firms rarely maintain in-house.
- Commissioning Timeline Compression:LEED Zero and comparable certifications demand twelve months of operational data, extending project closeout and delaying recognition in competitive leasing markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Net-Zero Energy Buildings Market |
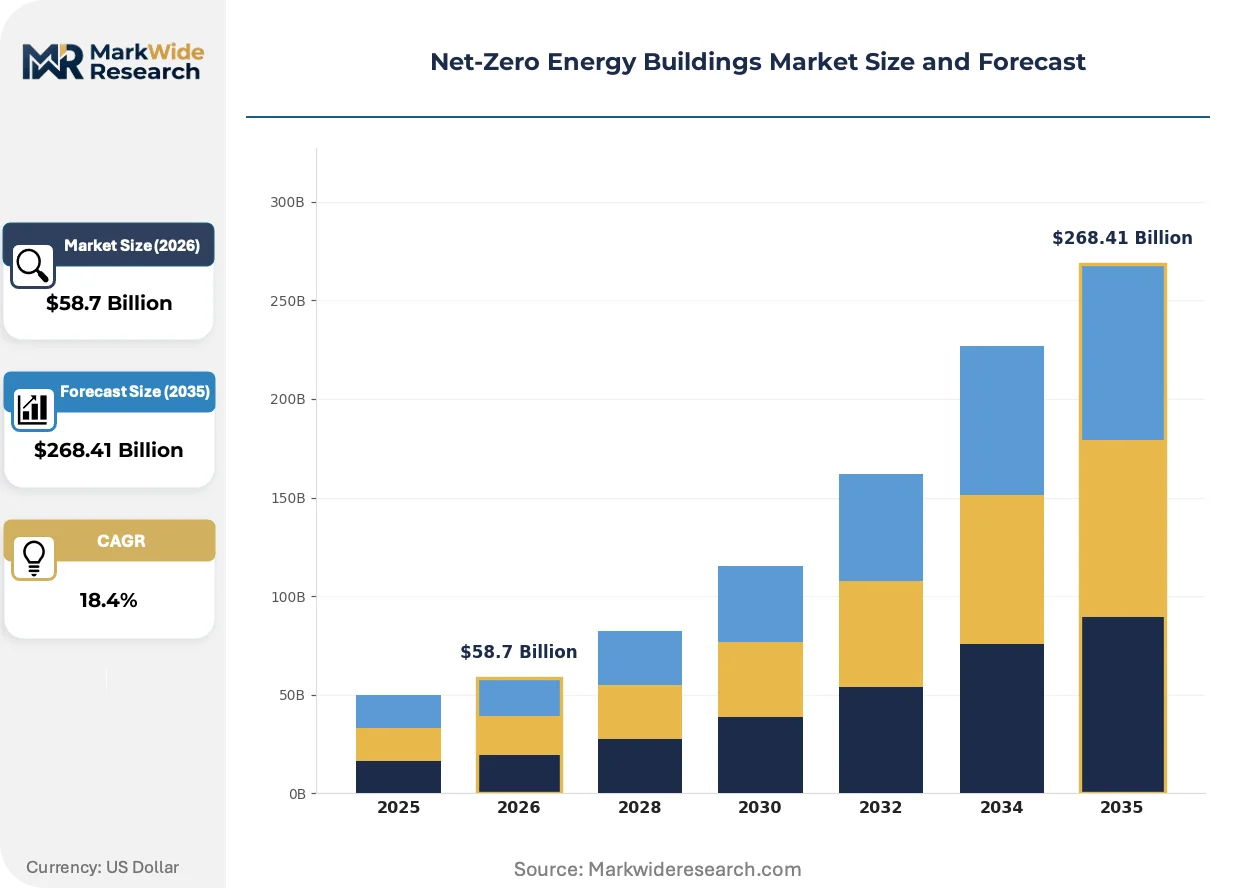
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $268.41 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Institutional, Industrial Technology: Solar Photovoltaic, Energy Storage Systems, Smart Thermostats, LED Lighting Energy Source: Renewable, Non-renewable, Hybrid, Grid-connected End User: Homeowners, Businesses, Government, Developers |
| Companies Covered | Schneider Electric SE, Siemens AG, Johnson Controls Inc., Daikin Industries Ltd., Kingspan Group PLC, General Electric Company, SunPower Corporation, Rockwool International A/S, Sage Electrochromics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Net-Zero Energy Buildings Market Strategic Shifts & Innovations
Building-integrated photovoltaics and phase-change materials are redrawing the boundary between envelope and generation functions, collapsing what were separate trades into unified performance specifications.
Vacuum-insulated panels are displacing conventional mineral wool and rigid foam in high-performance retrofits where floor-area ratio constraints prohibit thick wall assemblies. Japanese commercial developers facing METI Top Runner standards have adopted VIPs for curtain wall upgrades in dense urban cores. This material substitution is compressing thermal bridging calculations and forcing insulation contractors to certify installation protocols for pressure-sensitive edge seals.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is accelerating heat pump deployment with natural working fluids. Equipment manufacturers serving the German market have retooled production lines for propane and CO2 systems ahead of the 2030 ban threshold. Cold-climate commercial buildings in Scandinavia are now specifying ammonia chillers for district-connected properties, shifting specification authority from HVAC distributors to industrial refrigeration specialists.
Corporate occupiers are bundling energy performance guarantees into lease negotiations, transferring operational risk from landlords to engineering-procurement contractors. This contracting evolution is most visible in Netherlands and Denmark, where institutional investors face CSRD-mandated disclosure of Scope 3 building emissions. Engineering firms now underwrite multi-year savings performance, with penalties tied to actual metered consumption rather than modeled estimates.
Net-Zero Energy Buildings Market Segmentation
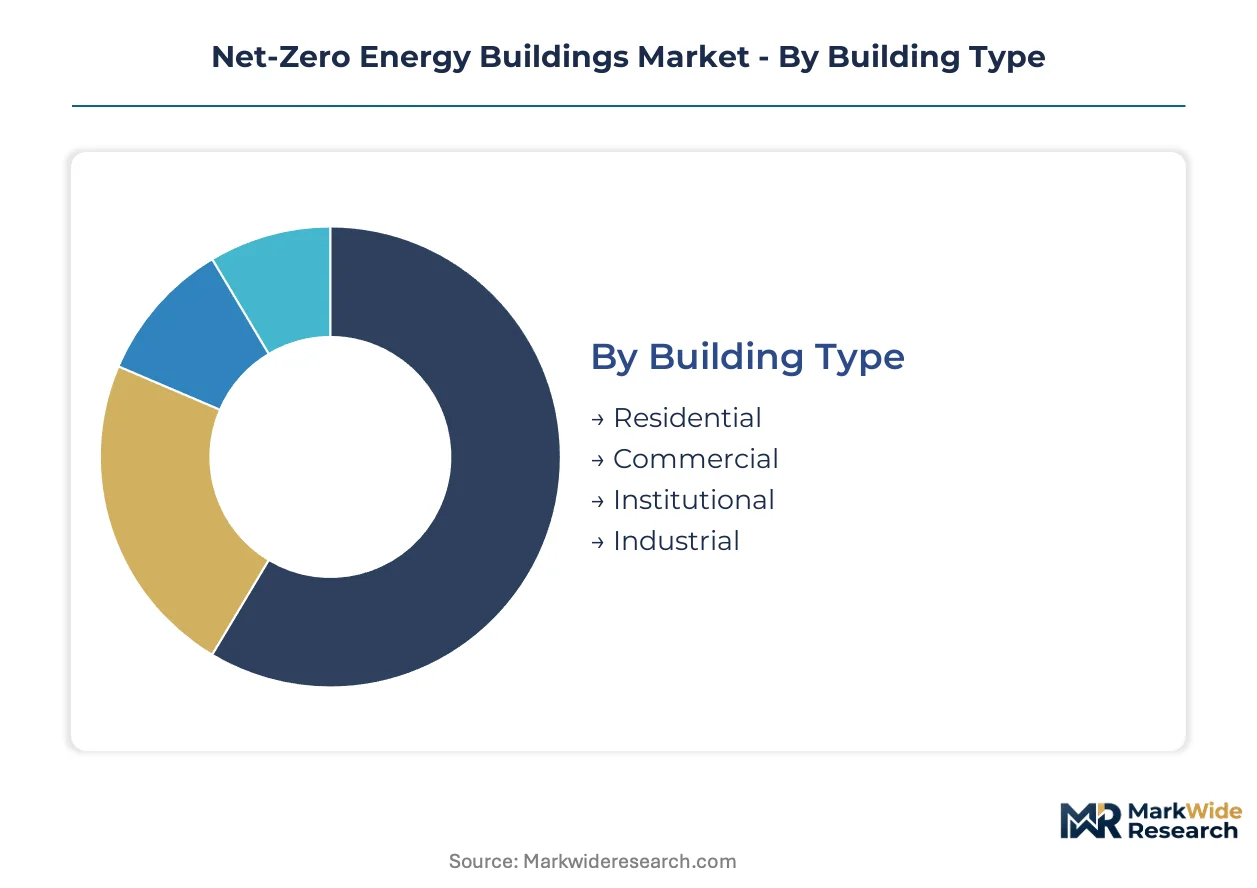
Segmentation in net-zero energy buildings reveals divergent capital recovery mechanisms across building types and technology stacks. Commercial assets leverage lease pass-throughs to amortize envelope investments, while residential deployment depends on subsidized financing instruments that vary sharply by national program design.
Building Type:
Domestic policy intensity shapes geographic concentration, with Germany and Japan driving commercial and institutional volumes through regulatory staircases while residential expansion remains export-led to subsidy-rich markets.
- Residential:Single-family and multi-family units achieve net-zero status through high-performance envelopes with U-values below 0.15 W/m²K paired with rooftop solar. First-cost barriers persist for individual homeowners outside subsidized financing markets like Germany's KfW program, compressing deployment in unsubsidized jurisdictions.
- Commercial:Office portfolios dominate absolute deployment volumes as triple-net lease structures allow landlords to recover efficiency investments through operating expense pass-throughs. The EU Green Deal's building performance standards are compressing retrofit timelines across member states, forcing asset owners to accelerate deep renovation cycles.
- Institutional:Schools, hospitals, and government facilities benefit from municipal bond financing and long asset holding periods that accommodate extended payback horizons.
- Industrial:Manufacturing and warehouse properties integrate net-zero specifications where corporate sustainability mandates override pure return thresholds.
Commercial commands the established base. The steepest expansion runs through institutional assets as CSRD disclosure requirements tighten across Europe.
Technology:
Cost tier differentiation separates modular, rapidly deployable systems from capital-intensive infrastructure requiring specialized commissioning.
- Solar Photovoltaic:Rooftop and building-integrated systems scale without custom engineering, reducing project development timelines for mid-size commercial retrofits. Photovoltaic modularity enables phased deployment that matches capital availability across project cycles.
- Energy Storage Systems:Battery systems paired with demand-response software enable commercial assets to monetize flexibility services through wholesale market participation. Grid-interactive requirements are tightening across FERC jurisdictions and EU member states, accelerating specification.
- Smart Thermostats:Occupancy-based climate control reduces HVAC loads in commercial and residential buildings with minimal installation complexity.
- LED Lighting:High-efficiency luminaires with daylight harvesting controls address base load reduction in all building categories.
Solar photovoltaic commands the established base. The steepest expansion runs through energy storage systems as grid-interactive building codes proliferate.
Energy Source:
Application context determines source selection, with urban density favoring grid-connected configurations and rural or campus settings enabling higher renewable penetration.
- Renewable:On-site solar, geothermal, and biomass systems satisfy annual energy balance requirements for certification schemes like LEED Zero. Japan's METI Top Runner standards effectively mandate near-zero performance for new construction, concentrating renewable specification in Japanese commercial development.
- Non-renewable:Natural gas and conventional grid electricity persist in retrofit projects where envelope upgrades precede generation additions.
- Hybrid:Combined renewable and conventional systems bridge capital constraints in phased renovation programs.
- Grid-connected:Net metering and virtual power purchase agreements allow buildings to claim renewable equivalence without on-site generation.
Grid-connected configurations command the established base. The steepest expansion runs through renewable systems as national building performance standards tighten.
End User:
Customer type dictates procurement sophistication, with institutional investors and developers deploying structured finance while homeowners navigate retail product markets.
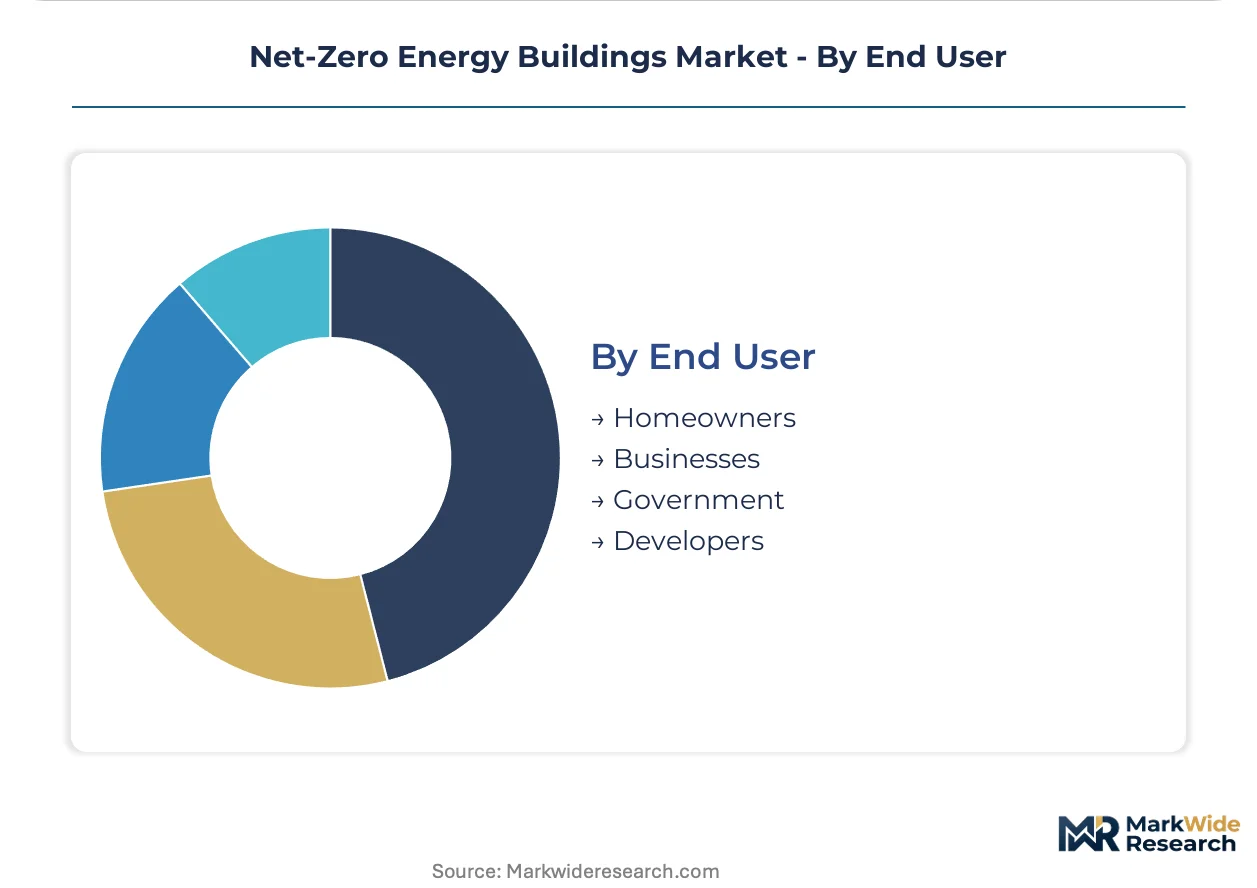
- Homeowners:Individual buyers depend on subsidized loan and grant programs to overcome first-cost barriers for high-performance envelope assemblies. Deployment concentrates in markets with replicable public-private capital structures.
- Businesses:Corporate occupiers bundle energy performance guarantees into lease negotiations, transferring operational risk from landlords to engineering-procurement contractors. This contracting evolution is most visible in Netherlands and Denmark under CSRD-mandated Scope 3 disclosure.
- Government:Public sector procurement leverages municipal and sovereign financing instruments with extended amortization horizons.
- Developers:Speculative builders incorporate net-zero specifications where competitive leasing markets reward certification with rent premiums or occupancy advantages.
Businesses command the established base. The steepest expansion runs through government procurement as EU member states front-load public building retrofits ahead of compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KfW efficiency financing program and EnEV regulatory staircase are compressing retrofit timelines across the EU, while Japan's METI Top Runner standards and U.S. FERC interconnection protocols are accelerating deployment in their respective markets.
United States
Commercial office portfolios in New York, Chicago, and San Francisco are accelerating adoption as triple-net lease structures allow landlords to recover efficiency investments through operating expense pass-throughs. The EPA's emissions benchmarking rules and FERC interconnection protocols for distributed generation shape demand, though grid interconnection queues extend project commissioning timelines in metropolitan markets.
Germany
The KfW efficiency financing program provides subsidized loans and grants for deep renovation, creating replicable templates for public-private capital structures. EnEV staged efficiency mandates ratchet minimum performance thresholds every three years, compelling commercial portfolios to front-load capital deployment ahead of compliance deadlines. Certified Passive House trades remain concentrated in Berlin, Munich, and Hamburg.
Japan
METI enforces stringent Top Runner standards that effectively mandate near-zero performance for new construction, concentrating renewable specification in Tokyo, Osaka, and Nagoya commercial development. Japanese commercial developers facing these standards have adopted vacuum-insulated panels for curtain wall upgrades in dense urban cores.
Netherlands
Corporate occupiers bundle energy performance guarantees into lease negotiations, transferring operational risk from landlords to engineering-procurement contractors. CSRD-mandated disclosure of Scope 3 building emissions drives institutional investor demand in Amsterdam and Rotterdam. Engineering firms underwrite multi-year savings performance with penalties tied to actual metered consumption.
United Kingdom
The UK building performance standards are compressing retrofit timelines, forcing asset owners in London, Manchester, and Birmingham to accelerate deep renovation cycles. Grid-interactive requirements are tightening, accelerating specification of battery systems paired with demand-response software that enables commercial assets to monetize flexibility services.
Net-Zero Energy Buildings Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with building management software stacks and specialized envelope material suppliers. The market structure favors entities with upstream control over thermal performance specifications that gate zero-energy compliance. Two strategic archetypes dominate: integrated building technology platforms and high-performance building material specialists. Competitive moves concentrate on strategic partnerships for grid-interactive building codes and portfolio diversification into digital twin platforms.
Within the integrated technology tier, Schneider Electric SE and Siemens AG exemplify platform-centric positioning. Schneider Electric SE leverages its building management software stack to anchor large-scale commercial retrofits. Siemens AG sustains R&D intensity in digital twin platforms that optimize HVAC-to-envelope coordination. Kingspan Group PLC represents the material-specialist archetype, with upstream control over thermal performance specifications.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| Johnson Controls Inc. |
| Daikin Industries Ltd. |
| Kingspan Group PLC |
| General Electric Company |
| SunPower Corporation |
| Rockwool International A/S |
| Sage Electrochromics Inc. |
| Others |
Cost & Logistics Intelligence
LEED Zero certification gates both supplier qualification and price differentiation simultaneously, forcing envelope contractors and system integrators to absorb compliance costs while tiering offerings around energy modeling accuracy and commissioning support.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with LEED Zero and Passive House Plus commanding material premiums over conventional high-performance builds. Project-based contracting dominates, with price differentiation resting on thermal modeling precision and after-sales energy guarantee duration. Cost compression in mid-tier commercial retrofits is intensifying because photovoltaic module commoditization has collapsed installer margins. Individual homeowners exhibit the highest price sensitivity, while institutional investors with CSRD disclosure obligations show the least.
Supply Chain Analysis
Germany and Austria anchor high-performance envelope manufacturing, with vacuum-insulated panel production concentrated in Bavarian industrial clusters. Critical inputs include photovoltaic silicon wafers, phase-change material compounds, and natural refrigerant heat pump compressors. Single-source vulnerability runs through Chinese battery cell supply for building-integrated storage systems. Distribution runs through specialized engineering-procurement contractors rather than conventional construction material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as building performance standards create switching costs that lock asset owners into certified supplier networks for multi-decade retrofit cycles.
For Market Incumbents: Consolidate control over digital twin platforms and certified installer networks before emerging HVAC-to-envelope coordination specialists capture specification authority. Acquire regional engineering-procurement contractors in Netherlands and Denmark where CSRD disclosure obligations are accelerating performance-guarantee contracting. Backward integration into vacuum-insulated panel production reduces exposure to German-Austrian supply concentration. For New Entrants and Emerging Players: Lead with grid-interactive building software targeting mid-size commercial portfolios in Southern European markets where KfW-style financing templates remain underdeveloped. Spain and Italy present the most penetrable geographies for demand-response platform deployment. Partner with established envelope contractors to bypass the certified Passive House trades bottleneck. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core building technology units amid portfolio restructuring. Long-term viability hinges on exposure to regulatory staircase jurisdictions rather than discretionary green building markets. Monitor FERC interconnection queue clearance rates as the inflection indicator for distributed generation deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens AG and Schneider Electric SE anchor HVAC-envelope coordination software that reduces performance gaps. |
| Backward Integration into VIP Manufacturing | Kingspan Group PLC secures upstream control over thermal specifications that gate zero-energy compliance. |
| Grid-Interactive Building Certification | FERC protocols and EU member state codes enable wholesale market participation for battery-stored flexibility. |
| Performance Guarantee Underwriting | Engineering-procurement contractors in Netherlands assume operational risk from landlords under CSRD pressure. |
| Natural Refrigerant Heat Pump Deployment | EU F-Gas Regulation phasedown forces equipment retooling for propane and CO2 systems ahead of ban thresholds. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with building energy modelers, EPC contractors, and institutional asset managers, alongside secondary validation through EU building performance directive filings, KfW program disbursement records, and FERC interconnection queue databases. Bottom-up project pipeline tracking triangulated against top-down regulatory mandate analysis.
Across the analysis window, forecasts model building type, technology stack, and energy source segmentation with regional regulatory framework as an overlay dimension. CAGRs derive from scenario-weighted deployment curves incorporating compliance deadline clustering and financing program renewal cycles. Key inputs include EnEV staircase milestone dates and METI Top Runner standard refresh intervals.
Forecasts assume regulatory continuity in EU Green Deal implementation and FERC distributed generation protocols; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in national building performance standard adoptions and grid-interactive code proliferations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
Botswana Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Philippines Power Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Tunisia Renewable Energy Market