
 Hybrid Solar Wind Diesel Market | 2026-2036
Hybrid Solar Wind Diesel Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Solar Wind Diesel Market Intelligence
Skilled microgrid engineers is rotating toward distributed energy integration as utilities and independent power producers race to commission hybrid plants in frontier markets. Vestas Wind Systems leverages its turbine control software heritage to anchor hybrid control architecture design. Siemens Gamesa Renewable Energy competes through integrated power curve optimization across variable renewable inputs. Schneider Electric controls electrical balance-of-plant components that synchronize diesel ramp rates with solar and wind intermittency.
Hybrid solar wind diesel systems combine photovoltaic arrays, wind turbines, and compression-ignition generators through a unified power management platform, typically incorporating battery storage with two to eight hours of autonomy to bridge generation gaps. These configurations serve remote industrial loads, islanded communities, and weak-grid extensions where single-source renewables fail to guarantee dispatchable capacity. Standalone systems dominate current deployment volumes across mining and telecom tower applications where grid extension remains uneconomic. Microgrids represent the fastest-expanding system category as governments and development finance institutions prioritize electrification clusters over individual household connections. Grid-connected hybrid installations occupy the mature margin pool where established utilities seek renewable compliance without sacrificing spinning reserve.
FERC Order 2222 in the United States enables aggregated distributed resources to participate in wholesale markets, directly expanding revenue stacking for hybrid plant operators. India's CEA grid codes and the MNRE hybrid policy framework mandate renewable purchase obligations that explicitly recognize multi-source configurations. ISO 8528-1 and IEC 61400-25 standards govern diesel generator transient response and wind turbine communication protocols, respectively, shaping equipment interoperability requirements. Stakeholders must monitor evolving capacity market rules and carbon border adjustment mechanisms to determine whether hybrid diesel retains cost advantage against battery-dominated alternatives in remote power applications.
Market Dynamics
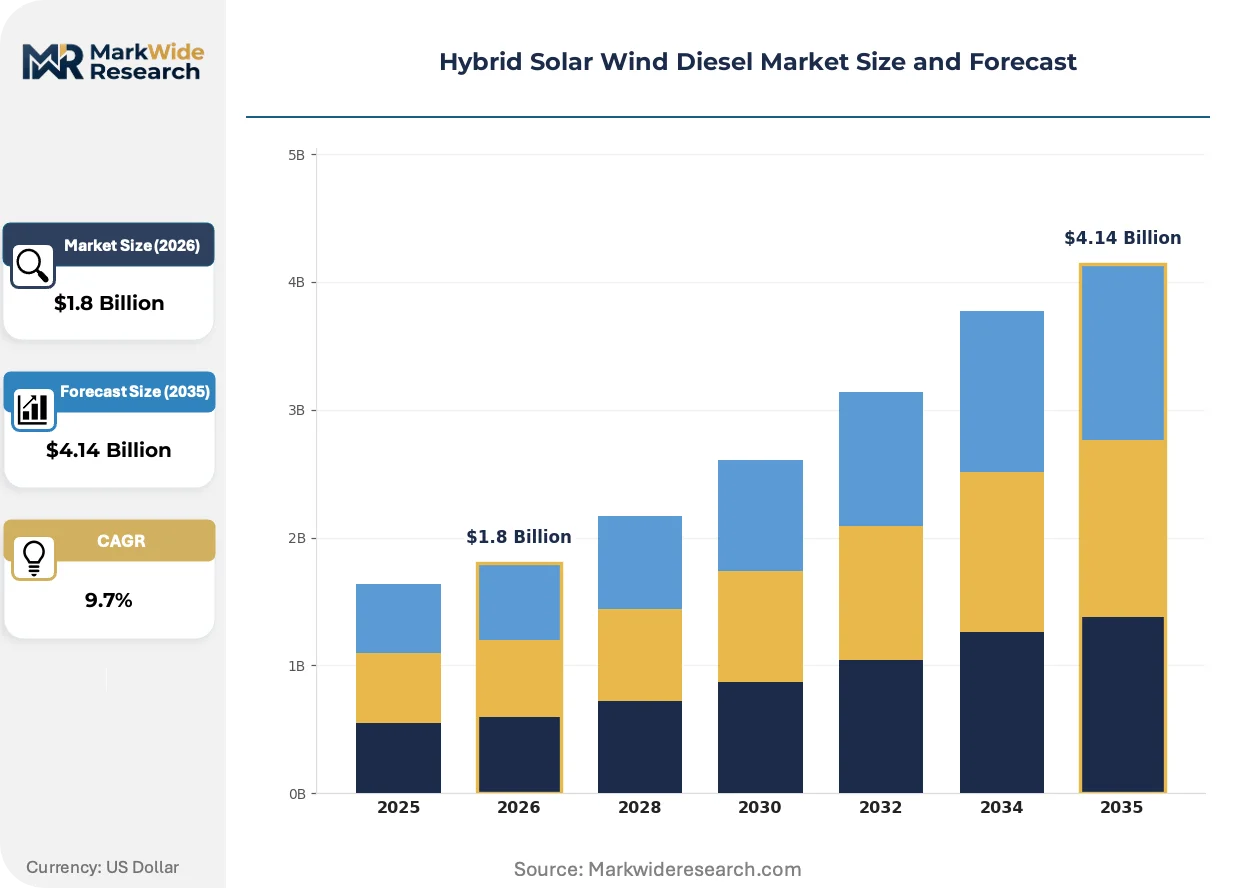
Diesel price volatility at remote mining sites is compressing payback periods for hybrid renewable integration, while India's MNRE hybrid policy framework and FERC Order 2222 in the United States reshape dispatch economics and market participation rules for multi-source power plants.
Growth Catalysts
- India's MNRE Hybrid Policy:Mandates renewable purchase obligations that explicitly recognize solar-wind-diesel configurations, accelerating utility-scale deployment across Rajasthan and Gujarat.
- Telecom tower electrification:Tower operators across sub-Saharan Africa adopt standalone hybrid systems to eliminate diesel logistics costs and generator maintenance burdens.
- Lithium-ion cost curves:Battery pack prices falling below critical thresholds enable two-to-eight hour autonomy configurations that bridge renewable generation gaps economically.
Market Restraints
- Diesel fuel cost volatility:Remote site operators face unpredictable operating expenditure swings that complicate hybrid system ROI calculations and financing structures.
- Skilled engineer scarcity:Distributed energy integration expertise concentrates in European and North American labor markets, creating deployment bottlenecks in frontier African and South Asian sites.
- Battery-dominated substitution:Pure solar-plus-storage configurations gain traction as battery duration extends, threatening diesel's role in longer-autonomy applications.
Strategic Opportunities
- Sub-Saharan electrification clusters:Development finance institutions prioritize microgrid deployments over individual household connections, opening multi-megawatt project pipelines in Kenya, Nigeria, and Tanzania.
- Grid-connected hybrid compliance:Established utilities in the United States leverage FERC Order 2222 aggregation rules to stack wholesale market revenues with renewable energy credit streams.
- Control software convergence:Integration of turbine control heritage with photovoltaic forecasting algorithms enables unified power management platforms that optimize across variable inputs.
Industry Challenges
- Microgrid engineer talent gaps:Utilities and independent power producers compete for scarce distributed energy integration specialists capable of commissioning complex hybrid architectures.
- Interoperability certification timelines:ISO 8528-1 diesel generator transient response testing and IEC 61400-25 wind turbine protocol compliance create extended equipment qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Solar Wind Diesel Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar Power, Wind Energy, Diesel Generators, Hybrid Systems Application: Industrial, Residential, Commercial, Off-Grid System Type: Standalone Systems, Grid-Connected Systems, Microgrids, Distributed Generation End User: Utilities, Enterprises, Households, Governments |
| Companies Covered | SMA Solar Technology, Canadian Solar, Vestas Wind Systems, Enphase Energy, Schneider Electric, General Electric, NextEra Energy, Acciona Energy, Siemens Gamesa Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Solar Wind Diesel Market Strategic Shifts & Innovations
Power electronics and control architectures are converging to enable tighter synchronization between variable renewable sources and compression-ignition backup, compressing commissioning timelines and expanding dispatchable capacity from hybrid configurations.
Containerized battery energy storage systems with integrated inverters and thermal management are miniaturizing balance-of-plant footprints for remote industrial sites. Mining operators in Western Australia and Chilean Atacama deploy these pre-integrated units to slash civil works and installation labor. The technology is compressing project development cycles from eighteen months to under six months for standardized configurations.
India's CEA technical standards for grid-connected renewables mandate frequency response capabilities and reactive power support that hybrid plants must demonstrate before commercial operation. These requirements force diesel generator manufacturers to upgrade governor controls and excitation systems. Developers respond by procuring certified equipment packages that pre-qualify for state utility tenders.
Power purchase agreement structures are unbundling energy and capacity payments to reflect hybrid plants' dual value streams. Mining offtakers in remote jurisdictions now negotiate take-or-pay clauses for renewable energy while reserving diesel capacity charges for reliability guarantees. This shift is most pronounced in South African and Peruvian mining corridors where grid instability drives premium pricing for spinning reserve.
Hybrid Solar Wind Diesel Market Segmentation
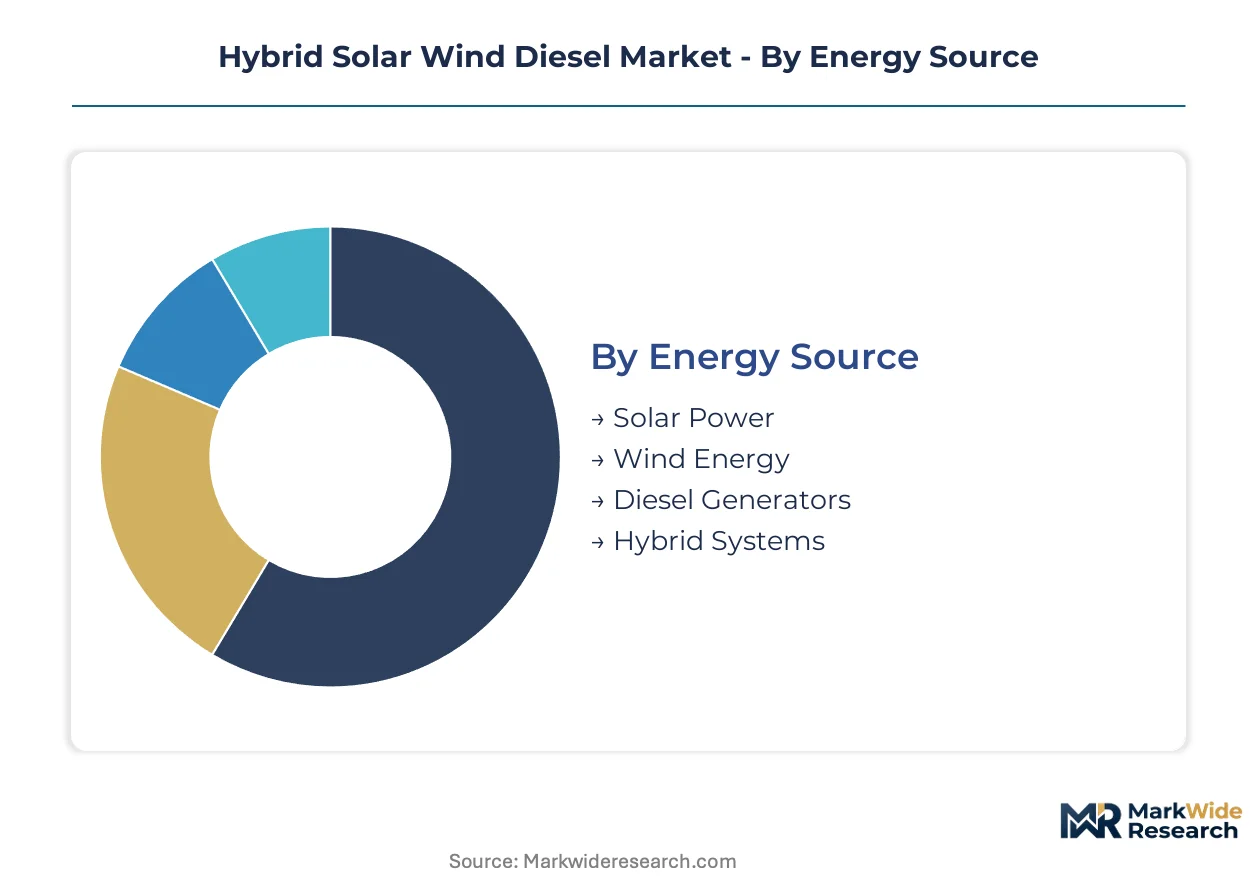
Segmentation in hybrid solar wind diesel markets reveals how regulatory frameworks and deployment economics fragment across energy source combinations, system architectures, and end-user procurement patterns. Each dimension carries distinct certification requirements and financing structures that shape vendor positioning.
Energy Source:
Regulatory differentiation across energy source combinations determines equipment certification pathways and grid interconnection eligibility under national renewable purchase obligation schemes.
- Solar Power:Photovoltaic arrays dominate capital allocation in hybrid configurations due to modular scalability and declining module costs. Indian CEA technical standards mandate frequency response capabilities that solar inverters must demonstrate before state utility tender qualification.
- Wind Energy:Turbine control systems anchor hybrid power management architecture through variable pitch regulation and power curve optimization. Deployment concentrates in Rajasthan and Gujarat corridor where MNRE hybrid policy recognizes wind-solar-diesel configurations for renewable purchase obligations.
- Diesel Generators:Compression-ignition units provide spinning reserve and bridge renewable generation gaps through governor-controlled transient response per ISO 8528-1 certification requirements.
- Hybrid Systems:Unified power management platforms integrate multi-source inputs through containerized battery energy storage with two-to-eight hour autonomy configurations.
Hybrid systems handle the majority of throughput; solar power is the fastest mover on share as module costs compress and CEA certification pathways mature.
Application:
Cost tier differentiation separates capital-intensive industrial deployments from distributed residential and commercial configurations with divergent balance-of-plant requirements.
- Industrial:Mining operations in Western Australia and Chilean Atacama deploy multi-megawatt hybrid plants to eliminate remote fuel logistics costs. Containerized battery systems compress project development cycles from eighteen months to under six months for standardized configurations.
- Off-Grid:Telecom tower operators across sub-Saharan Africa adopt standalone hybrid systems to eliminate diesel logistics and generator maintenance burdens in weak-grid corridors.
- Commercial:Islanded resorts and remote facilities procure hybrid configurations where grid extension remains uneconomic.
- Residential:Individual household connections yield to microgrid cluster prioritization by development finance institutions in Kenya, Nigeria, and Tanzania.
Industrial applications absorb the largest capital flows; off-grid deployment is expanding most quickly as tower electrification mandates accelerate across African markets.
System Type:
Volume concentration varies by system architecture maturity, with standalone configurations dominating current deployment and microgrids capturing development finance institution prioritization.
- Standalone Systems:Pre-integrated containerized units serve mining and telecom tower applications where grid extension remains uneconomic and civil works minimization drives procurement decisions.
- Microgrids:Clustered electrification configurations represent the fastest-expanding category as governments and DFIs prioritize multi-megawatt project pipelines over individual household connections in sub-Saharan Africa.
- Grid-Connected Systems:Established utilities in the United States leverage FERC Order 2222 aggregation rules to participate in wholesale markets with renewable compliance and spinning reserve.
- Distributed Generation:Behind-the-meter hybrid plants serve weak-grid extensions where centralized transmission infrastructure cannot guarantee reliability.
Standalone systems handle the majority of throughput; microgrids are climbing the fastest as electrification cluster financing displaces individual connection programs.
End User:
Customer type segmentation reflects divergent procurement authority, with utilities commanding tender-scale volumes and enterprises driving remote industrial deployment.
- Utilities:State power corporations in Rajasthan and Gujarat issue renewable purchase obligation-compliant tenders under MNRE hybrid policy frameworks that explicitly recognize multi-source configurations.
- Enterprises:Mining operators negotiate unbundled power purchase agreements separating energy payments from diesel capacity charges for reliability guarantees in South African and Peruvian corridors.
- Governments:Rural electrification agencies in Kenya, Nigeria, and Tanzania channel development finance into microgrid deployment pipelines.
- Households:Individual consumers access hybrid power through microgrid membership rather than direct system ownership as cluster models dominate.
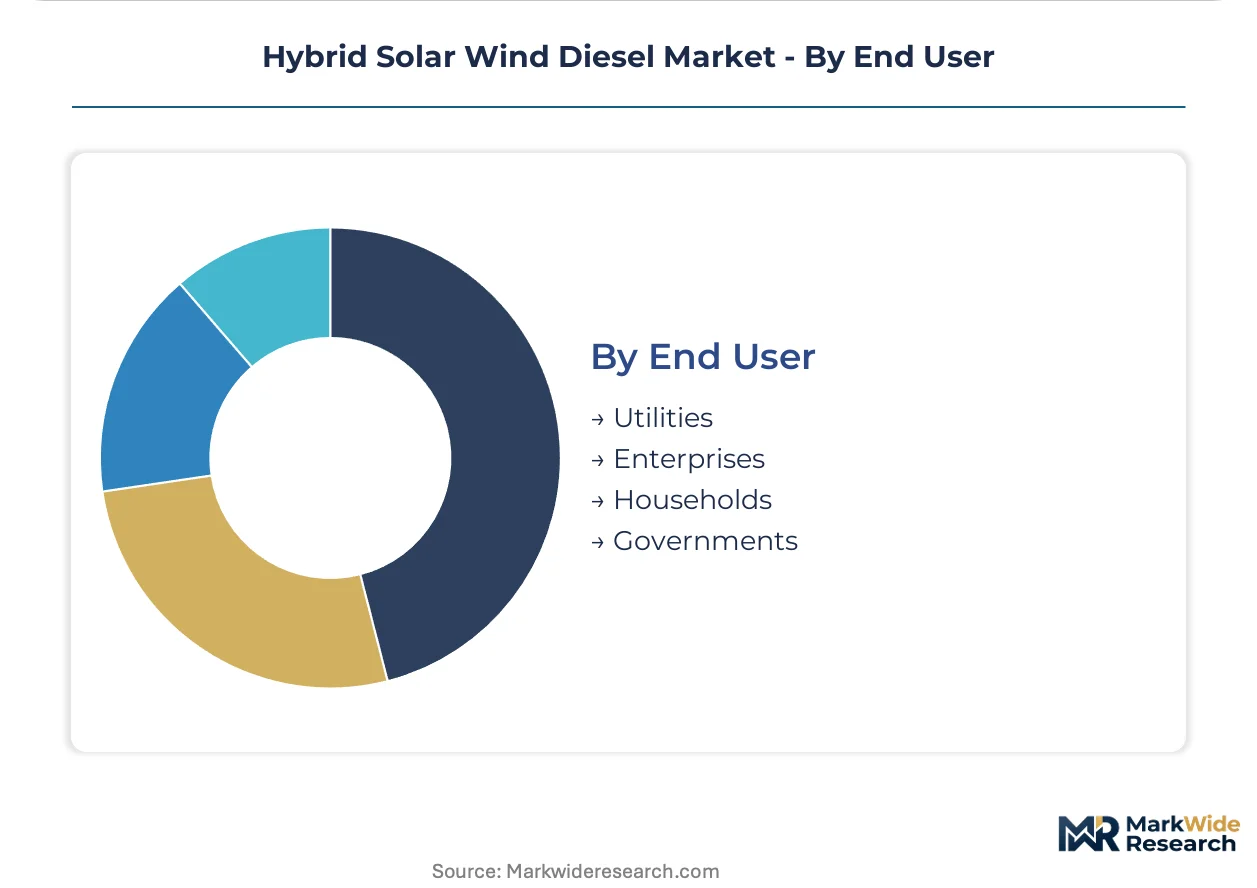
Utilities handle the majority of throughput; enterprises are gaining share fastest as mining sector procurement accelerates in remote jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MNRE's hybrid policy framework anchors India's position as the dominant deployment geography, with state-level renewable purchase obligations in Rajasthan and Gujarat compressing project timelines. Sub-Saharan Africa's off-grid corridor and Australia's remote mining belt follow as concentrated demand centers.
India
Rajasthan and Gujarat host utility-scale hybrid plants under MNRE mandates that recognize solar-wind-diesel configurations for renewable purchase obligations. CEA technical standards require frequency response capabilities and reactive power support before commercial operation. The Barmer-Jaisalmer solar-wind zone sees multi-megawatt commissioning as state power corporations issue obligation-compliant tenders.
Australia
Western Australia's Pilbara and Goldfields regions deploy containerized hybrid systems to eliminate diesel logistics costs at remote iron ore and gold operations. The Australian Energy Market Operator's remote area power system standards govern microgrid interconnection and dispatch protocols. Mining operators in the Eastern Goldfields compress project development cycles from eighteen months to under six months using pre-integrated battery units.
Kenya
Telecom tower electrification drives standalone hybrid adoption across the Rift Valley and Northeastern Province where grid extension remains uneconomic. Kenya Power and Lighting Company's rural electrification master plan prioritizes microgrid clusters over individual household connections. Lake Turkana wind-solar hybrid corridors anchor development finance institution pipelines for pastoral community electrification.
Chile
Atacama Desert mining operations deploy multi-megawatt hybrid plants to offset diesel price volatility at copper and lithium extraction sites. The Ministry of Energy's distributed generation law enables behind-the-meter renewable integration with simplified interconnection procedures. Antofagasta and Calama industrial clusters negotiate unbundled power purchase agreements separating renewable energy payments from diesel capacity charges.
United States
FERC Order 2222 aggregation rules enable hybrid plant operators in Texas and California to stack wholesale market revenues with renewable energy credit streams. ERCOT and CAISO market reforms recognize distributed resources as dispatchable capacity. West Texas oilfield operators and Central Valley agricultural processors commission grid-connected configurations for compliance without sacrificing spinning reserve.
Hybrid Solar Wind Diesel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the hybrid solar wind diesel market. Turbine manufacturers with control software heritage and electrical infrastructure conglomerates with balance-of-plant expertise occupy distinct competitive positions. Strategic archetypes include renewable turbine specialists, power electronics integrators, and industrial automation conglomerates. Dominant competitive moves center on control architecture convergence and pre-integrated containerized system offerings that compress commissioning timelines.
Within the turbine heritage tier, Vestas Wind Systems and Siemens Gamesa Renewable Energy exemplify players leveraging variable pitch regulation and power curve optimization capabilities into unified hybrid management platforms. Schneider Electric occupies a position among electrical infrastructure specialists, anchoring balance-of-plant synchronization between diesel ramp rates and renewable intermittency. These three companies represent how distinct engineering lineages converge on hybrid control architecture design.
| Leading Market Players |
|---|
| SMA Solar Technology |
| Canadian Solar |
| Vestas Wind Systems |
| Enphase Energy |
| Schneider Electric |
| General Electric |
| NextEra Energy |
| Acciona Energy |
| Siemens Gamesa Renewable Energy |
| Others |
Cost & Logistics Intelligence
Eighteen-month lead times for certified diesel generator packages concentrate pricing power with ISO 8528-1 accredited manufacturers in Germany and Japan, compressing margins for EPC contractors bidding remote mining projects in Western Australia and Chile. Containerized battery energy storage systems with integrated inverters are collapsing this dynamic by standardizing procurement cycles and enabling direct manufacturer-to-site distribution.
Pricing Analysis
Price spreads between Indian CEA-certified and non-certified hybrid configurations exceed 15% at utility tender scale, with Rajasthan and Gujarat state power corporations mandating frequency response capabilities that filter out uncertified equipment. Three-tier pricing structure across premium, standard, and economy levels tracks module efficiency grades and governor control sophistication. Cost compression in mid-tier configurations is intensifying because Chinese inverter manufacturers are penetrating African telecom tower markets with pre-integrated units. Mining operators in the Atacama and Pilbara regions exhibit lowest price sensitivity due to diesel logistics cost avoidance, while rural electrification agencies in Kenya and Tanzania face hardest budget constraints.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production, while Germany and the United States concentrate precision diesel generator manufacturing. Hybrid system assembly draws from Taiwanese power electronics, Australian iron ore site engineering expertise, and Indian module fabrication. Single-source vulnerability concentrates in battery management system semiconductors where foundry capacity rests on Taiwanese wafer output. Distribution runs through EPC contractors with established African logistics networks for sub-Saharan deployments, and direct OEM relationships for Australian mining majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against pure solar-plus-storage substitution as battery duration extends beyond four-hour autonomy thresholds, eroding diesel's reliability premium in remote power applications.
For Market Incumbents: Secure backward integration into containerized battery assembly to compress balance-of-plant costs and accelerate project delivery timelines. Anchor control software development through turbine heritage platforms that unify photovoltaic forecasting with diesel governor response. Battery-dominated substitution threatens longer-autonomy positioning unless incumbents demonstrate sub-100ms transient response certification.
For New Entrants and Emerging Players: Lead with telecom tower electrification in sub-Saharan Africa's weak-grid corridor, where standardized 10-50kW configurations eliminate diesel logistics burdens for tower operators. Kenya Power and Lighting Company's microgrid cluster prioritization opens multi-megawatt pipelines without requiring utility-scale certification depth. Partner with development finance institutions for concessional financing structures that incumbent EPCs cannot match.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant hybrid microgrid capabilities accumulated through mining sector service contracts. Long-term viability hinges on control architecture convergence that sustains margin differentiation as hardware commoditizes. Watch FERC Order 2222 implementation velocity in Texas and California as signal for wholesale market participation economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Containerized System Integration | Pre-integrated battery units slash Western Australian mining project cycles from eighteen months to under six. |
| CEA Certification Investment | MNRE-mandated frequency response capabilities unlock Rajasthan and Gujarat state utility tender participation. |
| Control Software Convergence | Turbine heritage platforms unify photovoltaic forecasting with diesel governor synchronization for dispatch optimization. |
| DFI Partnership Structuring | Development finance institution relationships secure concessional capital for Kenya and Nigeria microgrid pipelines. |
| African Logistics Network Buildout | Established last-mile capabilities in sub-Saharan weak-grid corridors create tender qualification barriers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FERC filings, IEA renewable integration reports, and Indian CEA technical standards documentation. Utility planning officers, independent power producer project developers, EPC contractors with African deployment experience, and diesel generator manufacturer application engineers provided structured input. Bottom-up project pipeline aggregation across the Barmer-Jaisalmer corridor, Pilbara mining belt, and Lake Turkana wind zone triangulates against top-down market sizing from equipment shipment data.
Segmentation dimensions modeled span energy source combination, system architecture type, end-user procurement authority, and regional regulatory framework cluster. CAGRs derive from installed capacity buildout trajectories and capital cost evolution across the projection horizon. Forecast inputs incorporate lithium-ion pack price curves, diesel fuel logistics cost indices for remote mining sites, and MNRE policy implementation timelines.
Forecasts assume regulatory continuity in India's renewable purchase obligation regime and FERC Order 2222 aggregation rules; material policy shifts would require re-modeling. Battery chemistry substitution risk and carbon border adjustment mechanism introduction represent primary forecast revision triggers. Recalibration cycles align with material shifts in lithium-ion cost curves and African electrification financing commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
PV Water Heater Market
Renewable Energy
Solar Drying System Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Ocean Power Market
Renewable Energy
In-Pipe Hydroelectric System Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Solar Chair Market
Renewable Energy
Poland Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market