
 Solar Farm Market | 2026-2036
Solar Farm Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Farm Market Intelligence
India's western desert belt is narrowing the cost gap between imported and domestically manufactured photovoltaic modules. NextEra Energy leverages its vertically integrated development platform to control project timelines from origination through grid connection. First Solar anchors US thin-film production with a cadmium telluride supply chain that sidesteps polysilicon price volatility. Canadian Solar competes on module efficiency gains while sustaining manufacturing presence across Southeast Asia.
A solar farm denotes a ground-mounted photovoltaic installation exceeding one megawatt in rated capacity, typically deploying crystalline silicon or thin-film modules on single-axis or fixed-tilt racking systems to convert solar irradiance into alternating current for wholesale power markets. Utility-scale product types dominate capital deployment due to economies in permitting and transmission infrastructure, while community solar segments attract smaller investors through subscription models that bypass rooftop ownership. Bifacial technology segments capture reflected albedo energy from desert or snow-covered terrain, lifting energy yield per hectare and improving land-use economics for developers.
The US Internal Revenue Service administers IRA production and investment tax credits that reshape project finance structures, while India's Ministry of New and Renewable Energy enforces domestic content requirements through the Approved List of Models and Manufacturers. The EU Green Deal's REPowerEU targets accelerate permitting timelines for solar parks exceeding one hundred megawatts. Stakeholders must track interconnection queue reform and tariff escalation clauses as grid congestion becomes the binding constraint on project returns.
Market Dynamics
Grid interconnection queue congestion is compressing project timelines and redirecting developer capital toward markets with streamlined permitting frameworks. The IRA production tax credit structure is collapsing the cost premium between domestic and imported module assembly, accelerating capital redeployment.
Growth Catalysts
- Domestic Content Incentives:The US Inflation Reduction Act production tax credits reward projects sourcing modules from qualified domestic facilities, redirecting procurement toward thin-film and crystalline silicon assembly plants in Ohio and Alabama.
- India's Approved List of Models and Manufacturers:India's Ministry of New and Renewable Energy mandates ALMM compliance for government-backed tenders, creating captive demand for domestic cell and module production in Rajasthan and Tamil Nadu.
- Bifacial Technology Maturation:Utility-scale developers in desert and snow-albedo regions deploy double-glass bifacial modules to capture reflected irradiance, lifting energy yield per hectare and improving land-use economics.
Market Restraints
- Polysilicon Price Volatility:Metallurgical-grade silicon refining capacity concentrates in Xinjiang and Yunnan provinces, exposing crystalline silicon module assemblers to input cost swings and supply disruption risk.
- Grid Interconnection Bottlenecks:Regional transmission organizations in Texas and California maintain interconnection queues exceeding three years, freezing capital deployment and compressing project IRRs for developers awaiting study completion.
- Land Use Conflicts:Utility-scale array siting in agricultural regions triggers opposition from farming cooperatives and water rights holders, extending permitting timelines and inflating legal contingency reserves.
Strategic Opportunities
- Agrivoltaics Expansion:Dual-use installations combining sheep grazing or shade-tolerant crops with elevated photovoltaic arrays unlock marginal land in Spain and Italy previously excluded from renewable development.
- Community Solar Subscription Models:Virtual net metering frameworks in Minnesota and Massachusetts enable residential and commercial tenants to purchase output from off-site arrays without rooftop ownership, democratizing clean energy access.
- Green Hydrogen offtake Contracts:Electrolyzer developers in Western Australia and Chile sign long-term power purchase agreements with solar farms, creating baseload demand for curtailed midday generation.
Industry Challenges
- Electrical Engineering Talent Scarcity:High-voltage substation design and grid integration expertise concentrates among aging utility workforces, forcing developers to compete for limited EPC contractors capable of delivering transmission-ready projects.
- Module Recycling Infrastructure Gaps:End-of-life crystalline silicon panels accumulate in regional landfills as specialized glass-separation and silver-recovery facilities remain undercapitalized relative to deployment volumes.
- Weather-Related Construction Delays:Monsoon patterns in Gujarat and cyclone exposure in Queensland compress installation windows, requiring accelerated EPC schedules and inflated labor premiums during dry seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Farm Market |
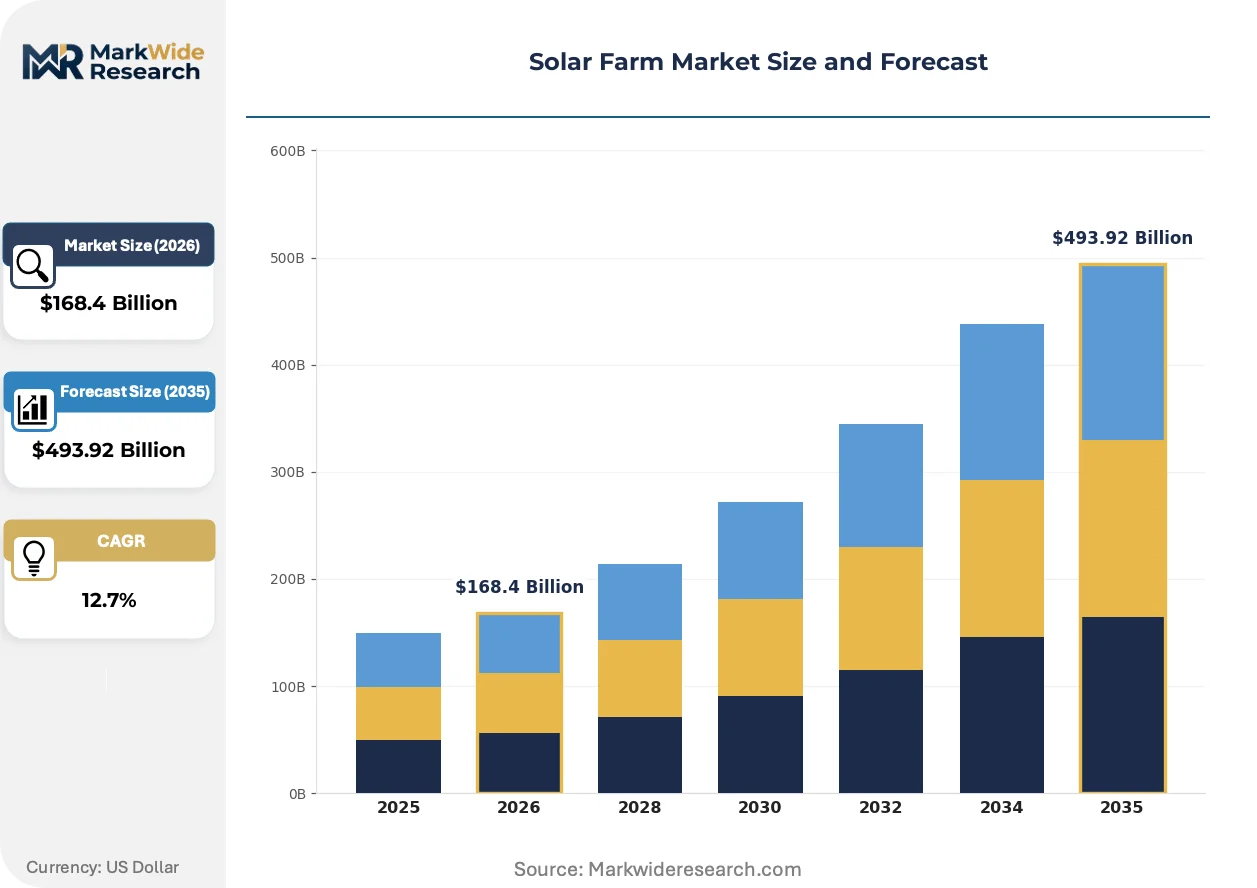
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $493.92 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Product Type: Utility-Scale, Community Solar, Rooftop, Hybrid Application: Power Generation, Energy Storage, Grid Management, Off-Grid Solutions End User: Power Utilities, Commercial Entities, Agricultural Sector, Residential Users |
| Companies Covered | NextEra Energy, Invenergy, EDF Renewables North America, Cypress Creek Renewables, First Solar, Canadian Solar, 8minute, Hanwha Qcells, JinkoSolar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Farm Market Strategic Shifts & Innovations
Module efficiency gains and racking automation are compressing balance-of-system costs while policy frameworks accelerate permitting for utility-scale arrays. Developers now optimize for energy density and grid flexibility rather than pure capex minimization.
TOPCon cell architecture is collapsing the efficiency gap between monocrystalline PERC and heterojunction designs. Chinese module manufacturers JinkoSolar and LONGi Solar have converted gigawatt-scale lines to tunnel oxide passivated contact cells, delivering 25%+ conversion efficiency at mass-production yields. This technology is collapsing the premium pricing power of legacy PERC suppliers and forcing rapid fab retooling across Southeast Asian contract manufacturers.
The EU Green Deal's REPowerEU targets compress permitting timelines for solar parks exceeding one hundred megawatts, mandating approval within twelve months for projects in designated renewable acceleration zones. Member states including Spain and Greece have transposed this directive into national law, triggering land-rush activity in Extremadura and Thessaly. Developers are responding by front-loading environmental impact assessments and pre-securing grid connection agreements before site control finalization.
Corporate offtakers now demand hourly matching of renewable generation against consumption rather than annual volumetric contracts, reshaping procurement specifications for solar-plus-storage configurations. Data center operators in Virginia and hyperscale cloud providers in Frankfurt specify DC-coupled battery systems with four-hour duration to firm midday peaks. This pattern is most visible in deregulated wholesale markets where time-of-use price spreads justify storage capex premiums.
Solar Farm Market Segmentation
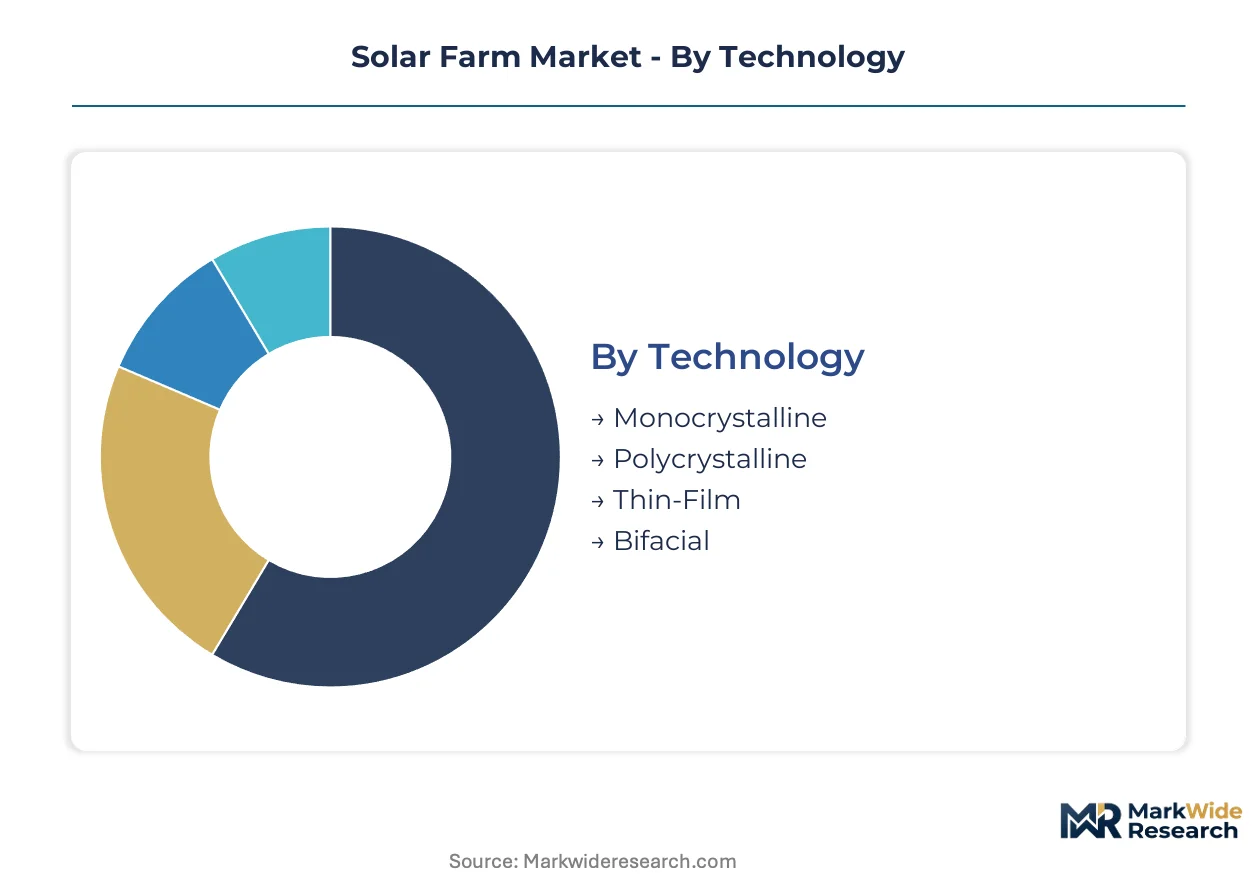
Technology choices dictate capital intensity and energy yield trajectories for solar farm developers. Product type and application configurations determine grid interconnection strategies and revenue model structures across wholesale and distributed markets.
Technology:
Mature crystalline architectures compete against emerging high-efficiency formats as module manufacturers retool production lines.
- Monocrystalline:Single-crystal silicon ingots deliver the highest conversion efficiency among mass-produced photovoltaic cells. Power utilities in India and the United States specify monocrystalline modules for gigawatt-scale parks where land constraints elevate energy density requirements. PERC and TOPCon cell architectures dominate this segment as manufacturers phase out legacy lines.
- Thin-Film:Cadmium telluride and copper indium gallium selenide layers deposit onto glass substrates, enabling low-temperature coefficient performance. First Solar's Ohio manufacturing complex supplies utility-scale developers seeking domestic content qualification under IRA production tax credits. Thin-film sidesteps polysilicon supply chain concentration in Xinjiang.
- Polycrystalline:Multi-crystal silicon wafers offer lower manufacturing cost at reduced efficiency. Southeast Asian contract manufacturers maintain polycrystalline capacity for price-sensitive emerging markets.
- Bifacial:Double-glass constructions capture reflected albedo irradiance from desert or snow terrain.
Monocrystalline retains volume leadership; bifacial holds the steepest expansion curve.
Product Type:
Project scale determines permitting complexity and offtake contract structures across wholesale power markets.
- Utility-Scale:Ground-mounted arrays exceeding 100 megawatts connect directly to high-voltage transmission infrastructure. Developers in Rajasthan and Gujarat negotiate long-term power purchase agreements with state distribution companies under India's central government tenders. These projects concentrate capital deployment due to economies in environmental review and grid interconnection.
- Community Solar:Shared arrays enable subscription-based participation without rooftop ownership. Virtual net metering frameworks in Minnesota and Massachusetts allow commercial tenants and residential renters to purchase output from off-site facilities. This segment attracts smaller investors through democratized clean energy access models.
- Rooftop:Building-integrated and mounted systems serve distributed generation demand.
- Hybrid:Co-located solar-plus-storage configurations firm intermittent generation.
Utility-scale commands capital deployment; community solar is climbing the fastest.
Application:
Functional use cases segment by grid integration depth and revenue mechanism.
- Power Generation:Bulk electricity production for wholesale market participation. Solar Energy Corporation of India tenders gigawatt-scale parks in western desert states where irradiance levels exceed 2,000 kilowatt-hours per square meter annually. Merchant and contracted offtake structures compete for developer preference.
- Energy Storage:DC-coupled battery systems store midday generation for evening dispatch. Data center operators in Virginia specify four-hour duration lithium-ion configurations to meet hourly matching requirements against consumption profiles.
- Grid Management:Ancillary services provision including frequency regulation and voltage support.
- Off-Grid Solutions:Remote power supply for unelectrified regions.
Power generation retains volume leadership; energy storage shows the steepest expansion curve.
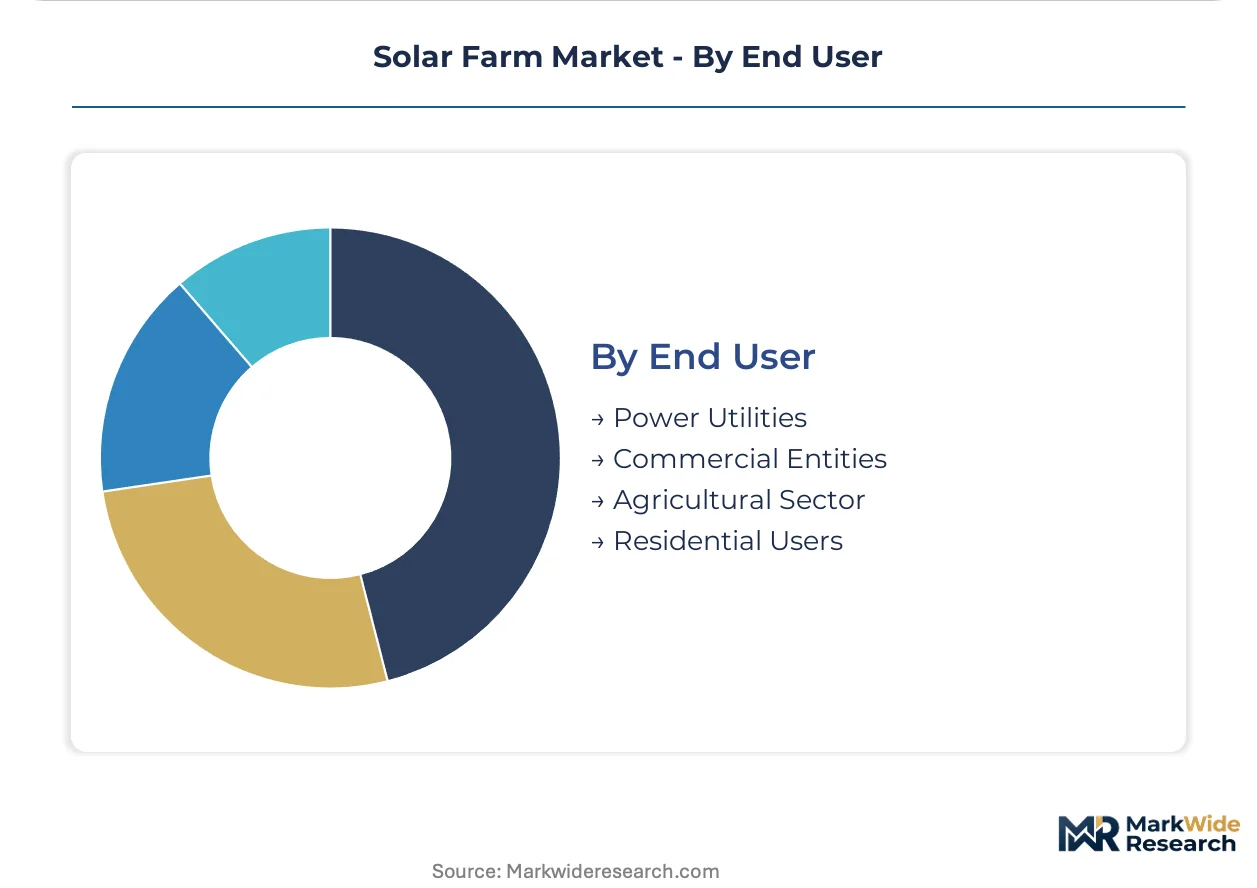
End User:
Customer categories differ in procurement scale and counterparty risk profiles.
- Power Utilities:Vertically integrated and independent power producers deploy utility-scale capacity. NextEra Energy controls project timelines from origination through grid connection using in-house development platforms. These entities negotiate interconnection agreements with regional transmission organizations.
- Commercial Entities:Corporate offtakers procure renewable energy certificates and physical power. Hyperscale cloud providers in Frankfurt specify solar-plus-storage configurations to meet hourly matching requirements against data center consumption.
- Agricultural Sector:Farming cooperatives host agrivoltaic installations combining sheep grazing with elevated arrays.
- Residential Users:Individual households participate through rooftop ownership or community solar subscription.
Power utilities retain volume leadership; commercial entities are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Internal Revenue Service anchors the dominant geography through production tax credit administration that redirects capital toward domestic module assembly. Grid interconnection queues exceed three years in Texas and California, compressing project timelines and redirecting developer capital toward markets with streamlined permitting.
United States
Utility-scale developers in Texas and California face interconnection queues exceeding three years, freezing capital deployment. The Internal Revenue Service administers IRA production tax credits that reshape project finance structures. Ohio and Alabama host thin-film and crystalline silicon assembly plants qualifying for domestic content incentives.
India
The Solar Energy Corporation of India tenders gigawatt-scale parks in Rajasthan and Gujarat where irradiance exceeds 2,000 kilowatt-hours per square meter annually. The Ministry of New and Renewable Energy enforces domestic content requirements through the Approved List of Models and Manufacturers. Manufacturing clusters in Rajasthan and Tamil Nadu supply ALMM-compliant cells and modules for government-backed tenders.
China
Metallurgical-grade silicon refining capacity concentrates in Xinjiang and Yunnan provinces, exposing module assemblers to input cost swings. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate utility-scale deployment in western provinces. JinkoSolar and LONGi Solar operate gigawatt-scale TOPCon cell lines delivering 25%+ conversion efficiency.
Germany
Corporate offtakers in Frankfurt specify solar-plus-storage configurations with four-hour duration to meet hourly matching requirements. The EU Green Deal's REPowerEU targets compress permitting timelines for solar parks exceeding one hundred megawatts. Bavaria and North Rhine-Westphalia host data center operators procuring renewable energy certificates and physical power.
Australia
Electrolyzer developers in Western Australia sign long-term power purchase agreements with solar farms, creating baseload demand for curtailed midday generation. The national renewable energy regulator streamlines approval processes for utility-scale arrays. Queensland faces cyclone exposure that compresses installation windows, requiring accelerated EPC schedules during dry seasons.
Solar Farm Market Key Industry Players
Vertically integrated developers and specialized module manufacturers split the market based on capital intensity and technology control. The structure concentrates around tiered archetypes: utility-scale project developers with in-house origination platforms, thin-film specialists with captive supply chains, and crystalline silicon assemblers competing on efficiency gains. Dominant competitive moves include backward integration into polysilicon refining and strategic partnerships for grid interconnection queue positioning.
Among US-based developers, NextEra Energy exemplifies the vertically integrated archetype with control over project timelines from origination through grid connection. First Solar anchors the thin-film specialist tier with cadmium telluride production that sidesteps polysilicon price volatility. Canadian Solar occupies a position within the crystalline silicon efficiency-focused segment, sustaining manufacturing presence across Southeast Asian contract networks.
| Leading Market Players |
|---|
| NextEra Energy |
| Invenergy |
| EDF Renewables North America |
| Cypress Creek Renewables |
| First Solar |
| Canadian Solar |
| 8minute |
| Hanwha Qcells |
| JinkoSolar |
| Others |
Cost & Logistics Intelligence
Polysilicon price volatility concentrated in Xinjiang and Yunnan provinces dictates both module cost tier spreads and the geographic reshaping of crystalline silicon supply chains toward Southeast Asian contract manufacturers seeking tariff insulation.
Pricing Analysis
Domestic module assembly in Ohio and Alabama commands premiums over Southeast Asian imports due to IRA production tax credit qualification. Price differentiation hinges on domestic content certification status and bifacial technology tiering. Cost compression in standard monocrystalline lines is intensifying as TOPCon capacity expansions flood the market. Utility-scale power utilities exhibit lowest price sensitivity; distributed commercial installers face margin pressure from interconnection delays.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for crystalline silicon module assemblers. Metallurgical-grade silicon refining concentrates in Xinjiang, Yunnan, and Inner Mongolia; cell and module assembly has migrated to Vietnam, Thailand, and Malaysia. The supply chain rests on polysilicon ingots, silver metallization paste, and aluminum framing. Distribution runs through utility-scale EPC contractors and independent power developer procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar farm development is approaching a platform-economics inflection as hourly matching requirements and storage co-location standards create interoperability layers between generation assets and corporate offtake systems.
For Market Incumbents: Entrench queue positioning advantages by pre-securing interconnection agreements before site control finalization in Texas and California. Deepen backward integration into domestic module assembly to capture IRA domestic content incentives. Counter emerging thin-film specialists by accelerating TOPCon efficiency roadmaps. For New Entrants and Emerging Players: Agrivoltaic installations in Spain and Italy represent the most penetrable entry point for developers lacking legacy queue positions. Community solar subscription platforms in Minnesota and Massachusetts offer software-enabled customer acquisition angles. Pursue virtual net metering regulatory expertise as the primary go-to-market wedge. For Investors and Strategic Acquirers: Grid interconnection specialist firms with FERC study completion track records present the highest-conviction acquisition archetype. Long-term viability across the analysis window depends on exposure to reforming regional transmission organization queue processes. Watch for interconnection cluster study batching announcements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Module Assembly Scale-Up | Captures IRA production tax credits and insulates against Section 201 tariff exposure. |
| Grid Interconnection Queue Positioning | Pre-secures FERC study completion timelines in ERCOT and CAISO territories. |
| Solar-Plus-Storage Configuration | Meets corporate hourly matching requirements from data center operators in Virginia. |
| Agrivoltaic Development Partnership | Unlocks marginal land in Extremadura and Thessaly through dual-use zoning. |
| TOPCon Technology Licensing | Accelerates conversion efficiency gains above 25% for utility-scale deployments. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through EIA generation data, IEA renewable reports, FERC interconnection filings, and project development databases. Bottom-up capacity build-up triangulated against top-down policy target aggregation.
Forecast inputs considered module cost trajectories, interconnection queue reform timelines, and corporate PPA procurement intensity across the projection horizon. Segmentation dimensions modeled include technology architecture, project scale tier, regulatory framework, and regional grid congestion profile. CAGRs derived from installed capacity ramp rates and capital redeployment patterns.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments or trade policy stringency would shift the trajectory. Forecasts reflect assumptions on IRA credit continuity and transmission buildout schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Hybrid Power System Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
North America Solar Tracker Market