
 Middle East Renewable Energy Market | 2026-2036
Middle East Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Renewable Energy Market Outlook
Utility-scale battery integration with photovoltaic arrays is rewriting dispatch economics for Middle Eastern grid operators. ACWA Power anchors its competitive position through captive project development across Saudi Arabia, Jordan, and Morocco. Masdar leverages its Abu Dhabi headquarters to control early-stage greenfield site access across multiple Gulf markets. Elsewedy Electric sustains manufacturing scale through its integrated solar module and cable production facilities in Egypt and Saudi Arabia.
The Middle East renewable energy sector encompasses electricity generation from solar irradiation, wind kinetic energy, biomass combustion, and geothermal heat, with photovoltaic systems typically deployed at 600-1500 volts DC before inversion to grid-frequency AC. Solar dominates installed capacity across the region due to irradiance levels exceeding 2000 kWh per square meter annually in Gulf Cooperation Council territories. Concentrated solar power with molten salt thermal storage captures premium offtake contracts where evening dispatch commands higher tariff structures. Offshore wind remains nascent but holds structural potential along Egypt's Red Sea coast and Saudi Arabia's Gulf of Aqaba shoreline.
Saudi Arabia's National Renewable Energy Program and the UAE's Net Zero by 2050 strategic initiative shape procurement mandates and local content requirements for developers. The Emirates Water and Electricity Company and the Saudi Power Procurement Company enforce competitive bidding frameworks that compress levelized cost thresholds while mandating domestic supply chain participation. Grid codes issued by national regulators in Abu Dhabi and Riyadh define frequency response and reactive power standards that equipment suppliers must satisfy for interconnection approval. Stakeholders must track hydrogen offtake agreement progress and green ammonia export corridor financing as these adjacent demand streams will reshape renewable capacity planning timelines.
Market Dynamics
Utility-scale battery integration with photovoltaic arrays is rewriting dispatch economics for Middle Eastern grid operators. ACWA Power anchors its competitive position through captive project development across Saudi Arabia, Jordan, and Morocco. Masdar leverages its Abu Dhabi headquarters to control early-stage greenfield site access across multiple Gulf markets. Elsewedy Electric sustains manufacturing scale through its integrated solar module and cable production facilities in Egypt and Saudi Arabia.
Growth Catalysts
- Saudi Arabia's National Renewable Energy Program:Mandates gigawatt-scale solar procurement with domestic content requirements, redirecting capital toward local manufacturing capacity.
- Green hydrogen offtake agreements:Industrial buyers in shipping and chemicals are signing long-term purchase contracts that anchor financing for new renewable capacity.
- Concentrated solar power with molten salt storage:Captures premium evening dispatch tariffs where grid operators value firm renewable output over intermittent generation.
Market Restraints
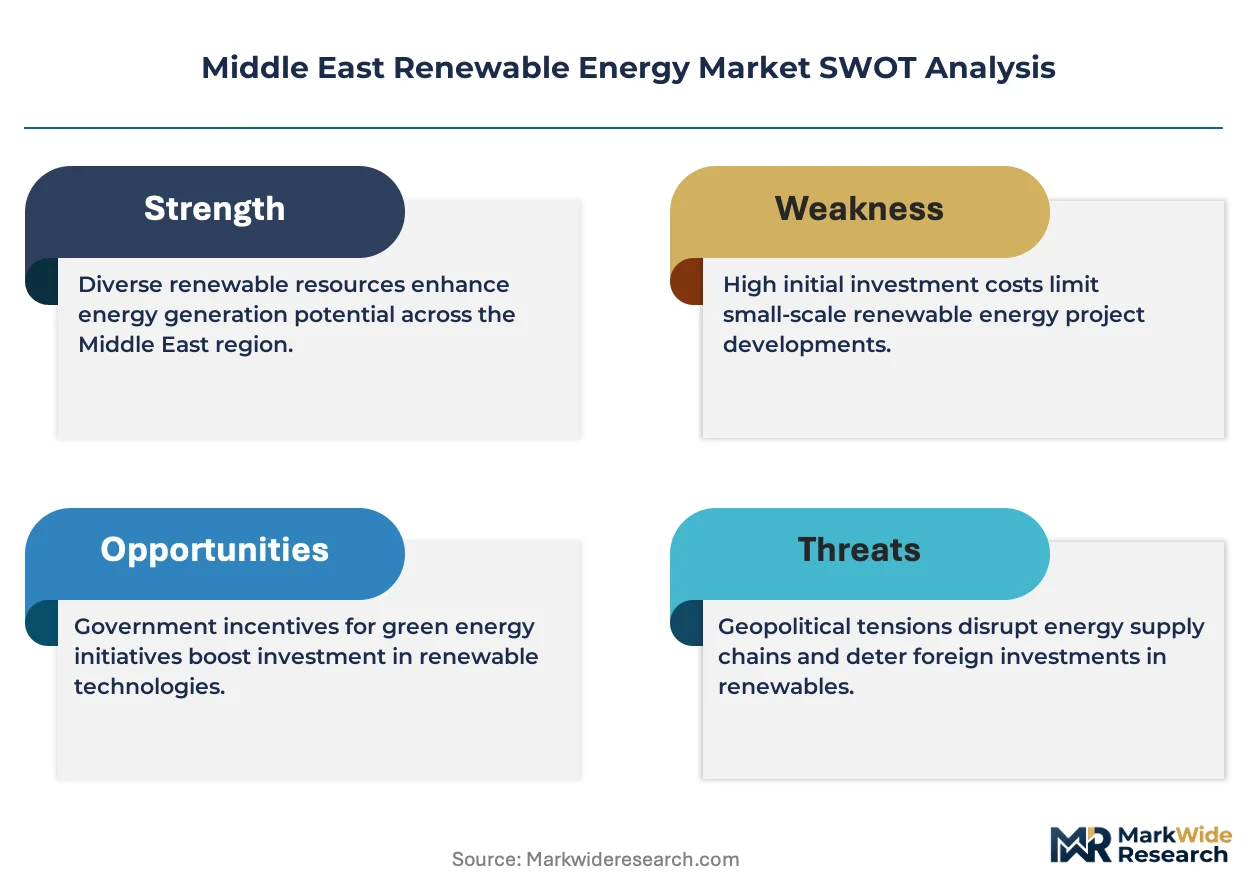
- Polysilicon supply concentration:Chinese polysilicon refiners control over 80 percent of upstream material, exposing project developers to input cost volatility and trade policy friction.
- Limited grid interconnection capacity:Transmission infrastructure in Saudi Arabia's Empty Quarter and Egypt's Western Desert lags behind generation site development timelines.
- Water scarcity for thermal plant cooling:Concentrated solar power facilities in the Gulf face operational constraints from freshwater availability and desalination energy overhead.
Strategic Opportunities
- Green ammonia export corridors:Port infrastructure at Yanbu and Jebel Ali is being reconfigured for hydrogen-derived fuel loading, creating captive demand for electrolyzer-linked renewable projects.
- Egypt's Red Sea offshore wind:Unpenetrated coastline with consistent wind resource offers first-mover positioning before grid connection frameworks mature.
- Distributed commercial solar:Net metering reforms in Dubai and Riyadh are unlocking rooftop deployment for industrial estates and logistics parks previously dependent on central procurement.
Industry Challenges
- Grid code compliance timelines:Frequency response and reactive power standards issued by regulators in Abu Dhabi and Riyadh require equipment recertification that delays project commissioning.
- EPC contractor capacity constraints:Specialized engineering talent for utility-scale solar-wind hybrid integration is concentrated among a limited pool of regional developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Renewable Energy Market |
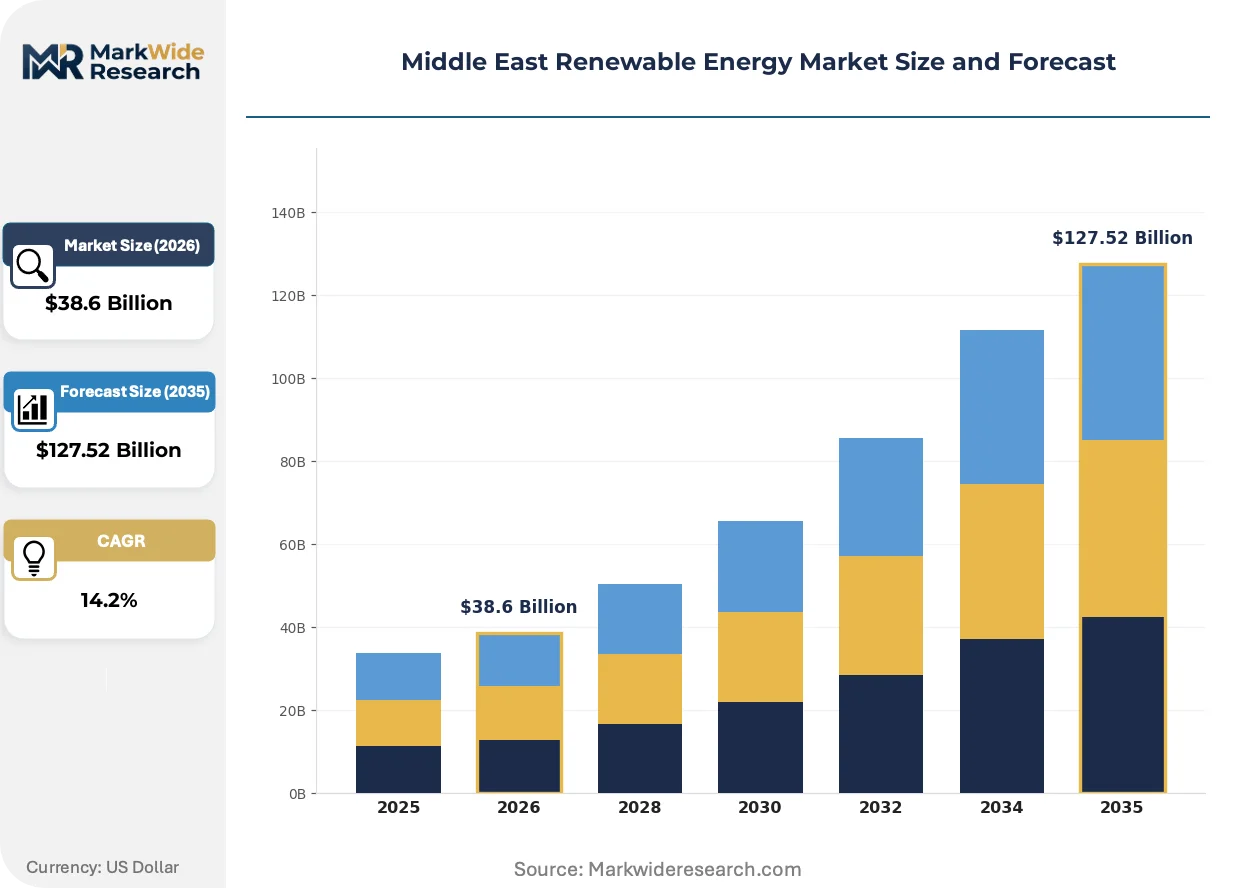
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Geothermal Technology Type: Photovoltaic, Concentrated Solar Power, Offshore Wind, Hydropower End User: Utilities, Industrial, Commercial, Residential Application: Power Generation, Heating, Transportation, Energy Storage |
| Companies Covered | SunPower Corporation, AMEA Power, ACWA Power, Elsewedy Electric, SirajPower, Masdar, Alfanar, GE Vernova, First Solar, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Renewable Energy Market Strategic Shifts
Technology convergence and procurement model evolution are restructuring how renewable capacity reaches offtake agreements in the Middle East. Developers are bundling generation assets with storage and hydrogen production to capture premium contract structures. Regulatory frameworks are codifying these integrated project formats into standard interconnection procedures.
Bifacial photovoltaic modules with tracking systems is hybridizing plant design standards across the region. Saudi Power Procurement Company now specifies bifacial technology in gigawatt-scale tenders, compressing levelized cost thresholds by capturing reflected irradiance from desert surfaces. The structural consequence is displacement of fixed-tilt monofacial designs in new procurement rounds.
The UAE's Net Zero by 2050 strategic initiative and Saudi Arabia's Green Initiative are mandating carbon intensity disclosures for imported equipment. Industrial buyers must document supply chain emissions to qualify for preferential offtake terms. Manufacturers with verified low-carbon polysilicon sourcing are securing interconnection priority in competitive bidding rounds.
Long-term power purchase agreements are fragmenting into shorter tenors with merchant price exposure. Industrial offtakers in aluminum smelting and desalination are negotiating 10-year contracts with renewable energy certificates unbundled from physical delivery. This shift is most visible in Dubai, where Emirates Water and Electricity Company pilots split-contract structures for commercial and industrial segments.
Middle East Renewable Energy Market Segmentation
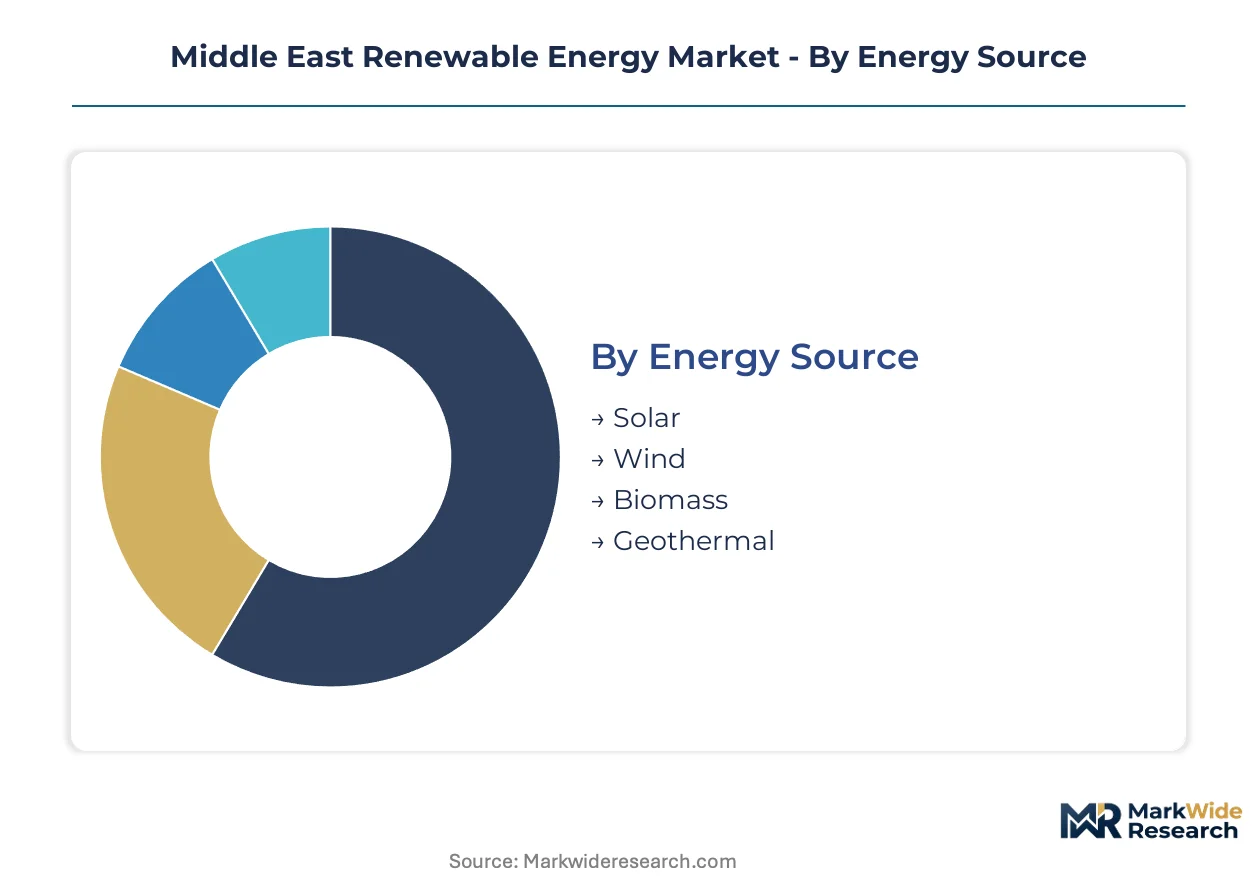
Segmentation reveals how capital allocation priorities differ across energy sources, technology formats, and customer types in Middle Eastern markets. Procurement cycles vary dramatically between utility-scale solar auctions and distributed commercial installations.
Energy Source:
Solar projects turn over fastest with 18-24 month development cycles, while geothermal and biomass face decade-long resource assessment timelines before financial close.
- Solar:Photovoltaic and concentrated solar thermal systems capture irradiance exceeding 2000 kWh per square meter annually across Gulf Cooperation Council territories. Saudi Arabia's National Renewable Energy Program and the UAE's Al Dhafra development anchor gigawatt-scale procurement.
- Wind:Onshore installations in Egypt's Gulf of Suez and nascent offshore exploration along Saudi Arabia's Red Sea coastline require longer permitting cycles due to aviation and marine coordination requirements.
- Biomass:Agricultural residue and municipal waste-to-energy projects concentrate in Egypt's Nile Delta where feedstock logistics reduce collection costs.
- Geothermal:Western Saudi Arabia's volcanic fields and Jordan's Dead Sea Rift hold untapped thermal gradients but lack transmission infrastructure for commercial development.
Solar dominates installed base. Wind is where expansion concentrates.
Technology Type:
Cost tiers separate mature photovoltaic deployment from capital-intensive concentrated solar power with molten salt storage.
- Photovoltaic:Bifacial modules with single-axis tracking now command premium tariffs in Saudi Power Procurement Company tenders by capturing reflected desert irradiance. ACWA Power and Masdar anchor manufacturing partnerships across Saudi Arabia and the UAE.
- Concentrated Solar Power:Molten salt thermal storage enables evening dispatch commanding tariff premiums where grid operators value firm output. Dubai's Mohammed bin Rashid Al Maktoum Solar Park integrates parabolic trough technology with storage.
- Offshore Wind:Egypt's Red Sea coastline offers consistent wind resource but awaits grid connection frameworks and port infrastructure for turbine installation.
- Hydropower:Limited to existing installations in Turkey and Iran with minimal new capacity planned across Gulf markets due to water scarcity constraints.
Photovoltaic commands deployment volume. Concentrated solar power captures margin expansion.
End User:
Customer type determines contract structure complexity from regulated utility procurement to merchant exposure in commercial segments.
- Utilities:Emirates Water and Electricity Company and Saudi Power Procurement Company enforce competitive bidding with local content mandates. Procurement frameworks compress levelized cost thresholds while mandating domestic supply chain participation.
- Industrial:Aluminum smelters and desalination plants negotiate shorter-tenor contracts with renewable energy certificates unbundled from physical delivery.
- Commercial:Net metering reforms in Dubai and Riyadh unlock rooftop deployment for logistics parks and industrial estates.
- Residential:Distributed solar penetration remains limited by financing access and grid interconnection queue delays across Gulf markets.
Utilities anchor procurement volume. Industrial offtakers drive contract innovation.
Application:
Application scope spans electrons to molecules as green hydrogen redefines renewable asset valuation.
- Power Generation:Utility-scale solar-wind hybrid integration dominates capacity additions with battery storage co-location rewriting dispatch economics for grid operators.
- Heating:Concentrated solar thermal for industrial process heat concentrates in Jordan's phosphate processing and Saudi Arabia's desalination pre-treatment.
- Transportation:Green hydrogen offtake agreements from shipping and chemicals sectors anchor electrolyzer-linked renewable project financing at Yanbu and Jebel Ali.
- Energy Storage:Lithium-ion battery integration with photovoltaic arrays captures arbitrage value as frequency response standards issued by regulators in Abu Dhabi and Riyadh create new revenue streams.
Power generation dominates capital deployment. Transportation applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Green hydrogen export corridors from Saudi Arabia and the UAE are redirecting equipment flows toward European and East Asian industrial buyers, establishing the Gulf as a primary node in renewable-derived fuel trade networks.
Saudi Arabia
Gigawatt-scale solar procurement under the National Renewable Energy Program drives module demand, while the Saudi Power Procurement Company enforces competitive bidding with domestic content mandates. The Green Initiative establishes carbon intensity disclosure requirements for imported equipment. NEOM Northwest anchors electrolyzer-linked renewable developments targeting ammonia export to Northwest European ports.
United Arab Emirates
Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park developments concentrate photovoltaic deployment at scale, with Emirates Water and Electricity Company piloting split-contract structures for commercial segments. The Net Zero by 2050 strategic initiative mandates supply chain emissions documentation. Abu Dhabi headquarters Masdar's control over early-stage greenfield site access across multiple Gulf markets.
Egypt
Agricultural residue and municipal waste-to-energy projects cluster in the Nile Delta where feedstock logistics reduce collection costs, while the Gulf of Suez hosts established onshore wind installations. The central electricity regulator enforces grid code compliance timelines that require equipment recertification. Red Sea coastline exploration for offshore wind awaits grid connection frameworks and port infrastructure for turbine installation.
Jordan
Phosphate processing facilities in the Dead Sea Rift deploy concentrated solar thermal for industrial process heat, leveraging consistent irradiance levels. The national renewable energy framework supports captive project development by regional developers. ACWA Power anchors competitive positioning through integrated development across the kingdom's solar-wind hybrid sites.
Morocco
Noor Ouarzazate Solar Complex established concentrated solar power with molten salt storage as a viable evening dispatch technology, commanding premium tariffs where grid operators value firm output. The national utility enforces local content participation in procurement rounds. Integrated solar module and cable production facilities in Tangier and Casablanca sustain manufacturing scale for regional export.
Middle East Renewable Energy Market Competitive Environment
Channel-controlling players compete with product-specialist players for procurement influence across Middle Eastern renewable energy markets. The vendor base clusters around three tiers: integrated developers with captive project pipelines, state-affiliated entities controlling site access, and equipment manufacturers with regional production footprints. Strategic archetypes include utility-scale project aggregators, green hydrogen offtake enablers, and module-cable integrated producers. Dominant competitive moves encompass strategic partnerships for electrolyzer-linked developments and geographic expansion through manufacturing joint ventures.
Within the integrated developer tier, ACWA Power and Masdar exemplify channel-control strategies through captive project origination across multiple jurisdictions. Elsewedy Electric occupies a position among equipment-integrated specialists, leveraging in-house production capabilities across Egypt and Saudi Arabia. These three entities represent distinct competitive archetypes: ACWA Power as a project aggregator with regional reach, Masdar as a state-affiliated site-access controller, and Elsewedy Electric as a manufacturing-scale specialist with backward integration into module and cable production.
| Leading Market Players |
|---|
| SunPower Corporation |
| AMEA Power |
| ACWA Power |
| Elsewedy Electric |
| SirajPower |
| Masdar |
| Alfanar |
| GE Vernova |
| First Solar |
| Others |
Value Chain & Pricing Dynamics
Chinese polysilicon refiners controlling over four-fifths of upstream material concentrate margin capture at the ingot-wafer stage, forcing project developers in Saudi Arabia and the UAE to absorb input volatility through long-term offtake renegotiation clauses.
Pricing Analysis
Bifacial photovoltaic modules with single-axis tracking command tariff premiums against fixed-tilt monofacial designs in Saudi Power Procurement Company tenders. Pricing stratifies across premium tracking-bifacial, standard fixed-tilt, and economy direct-current systems without grid-forming inverters. Cost compression in economy tiers intensifies as Chinese module manufacturers flood Gulf markets with undifferentiated product. Utility offtakers exhibit lowest price sensitivity due to mandated procurement quotas, while commercial rooftop developers face acute margin pressure from interconnection queue delays.
Supply Chain Analysis
US export controls on semiconductor manufacturing equipment constrain inverter and power electronics flows to Middle Eastern project developers, forcing reliance on Chinese and European suppliers for grid-forming technology. Manufacturing gravity centers on China for polysilicon and cells, Southeast Asia for module assembly, and Germany for string inverters. Raw material dependencies span high-purity silicon metal, silver paste for cell metallization, and lithium salts for co-located battery storage. Single-source vulnerability concentrates in polysilicon refining where Xinjiang-based capacity dominates. Distribution runs through Dubai's Jebel Ali port for Gulf markets and Suez Canal corridors for North African projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in green hydrogen offtake verticals where electrolyzer-linked renewable projects outrun standardized utility procurement, creating niche positioning for developers bundling molecules with electrons.
For Market Incumbents: Pre-empt margin erosion in photovoltaic EPC by anchoring captive electrolyzer partnerships at Yanbu and NEOM before green ammonia export corridors mature. ACWA Power and Masdar should deepen backward integration into polysilicon sourcing through offtake agreements with non-Chinese refiners. The priority lever rests on controlling early-stage site access for hybrid solar-wind-storage configurations that command premium tariffs. For New Entrants and Emerging Players: Build out distributed commercial solar capabilities in Riyadh and Dubai industrial estates where net metering reforms outpace utility-scale auction timelines. Egypt's Red Sea offshore wind offers the most penetrable geography given absent incumbent site control. Target phosphate processing facilities in Jordan's Dead Sea Rift with concentrated solar thermal for industrial process heat, bypassing saturated photovoltaic procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrolyzer-linked renewable developments as green hydrogen offtake agreements lengthen project finance tenors. Long-term viability favors developers with verified low-carbon equipment sourcing securing interconnection priority under Saudi and UAE carbon disclosure mandates. Acquisition targets should display integrated module-cable manufacturing or captive greenfield site pipelines. The signal to watch is hydrogen offtake agreement execution at Northwest European ports forcing capacity allocation decisions at Gulf project sites.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Linked Renewable Capacity Buildout | NEOM and Yanbu developments anchor green ammonia export corridors to Rotterdam and Hamburg terminals. |
| Bifacial Module Technology Licensing | Saudi Power Procurement Company mandates tracking systems capturing reflected desert irradiance in gigawatt tenders. |
| Long-Term Polysilicon Supply Agreement | Non-Chinese sourcing secures interconnection priority under Saudi Green Initiative carbon disclosure rules. |
| Grid-Scale Battery Integration Partnership | Frequency response standards from Abu Dhabi and Riyadh regulators create new revenue streams for co-located storage. |
| Green Certification Program Alignment | UAE Net Zero by 2050 initiative mandates supply chain emissions documentation for preferential offtake terms. |
Study Parameters
Operator-level perspectives from utility planning officers at Emirates Water and Electricity Company, IPP project developers at ACWA Power and Masdar, EPC contractors specializing in solar-wind hybrid integration, and grid operators in Abu Dhabi and Riyadh anchored the qualitative base. Secondary validation drew from IEA renewable energy market reports, EIA international energy data, FERC interconnection filings, and project development databases tracking Middle Eastern capacity additions. Bottom-up project-level aggregation triangulated against top-down national target assessments.
Scenario-bracketing framed demand trajectories across the projection horizon, modeling energy source segmentation between solar, wind, and hydrogen-linked applications alongside technology type tiers from fixed-tilt photovoltaic to concentrated solar power with molten salt storage. End-user segmentation captured utility procurement, industrial offtake, and commercial distributed deployment patterns. CAGRs derived from capacity installation run-rates against national renewable program targets, with green hydrogen offtake agreement timelines and electrolyzer cost curves as critical forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-affiliated developers securing exclusive greenfield site access would shift outcomes. Material shifts in Chinese polysilicon trade policy or EU carbon border adjustment implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Rectenna Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Russian Federation Renewable Energy Market