
 Solar Boat Market | 2026-2036
Solar Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Boat Market Outlook
The premium-hybrid specification tier is collapsing the cost gap between conventional diesel yachts and fully electric alternatives. Silent Yachts leverages integrated solar-electric architecture to dominate long-range cruising segments. Sunreef Yachts sustains R&D intensity across custom multihull designs. Candela differentiates through hydrofoil efficiency gains that extend range per kilowatt-hour.
A solar boat converts photovoltaic energy into electric propulsion through onboard panel arrays, battery banks, and motor controllers, typically achieving 4-8 kW peak output per square meter of deck-mounted cells for leisure and commercial waterborne transit. Catamarans lead installed capacity due to expansive deck surface area, while ferries represent the fastest-growing end user category as municipal operators decarbonize harbor transit. Battery storage technology concentrates margin pools through cell chemistry optimization and thermal management systems.
The EU Green Deal and F-Gas Regulation shape hull insulation and refrigerant standards for European builders, while the US Coast Guard and EPA govern emissions compliance and safety certification for vessels entering American waters. The International Maritime Organization's greenhouse gas strategy adds cross-border pressure on commercial fleet operators. Stakeholders must weigh certification timelines against battery supply commitments when scaling production.
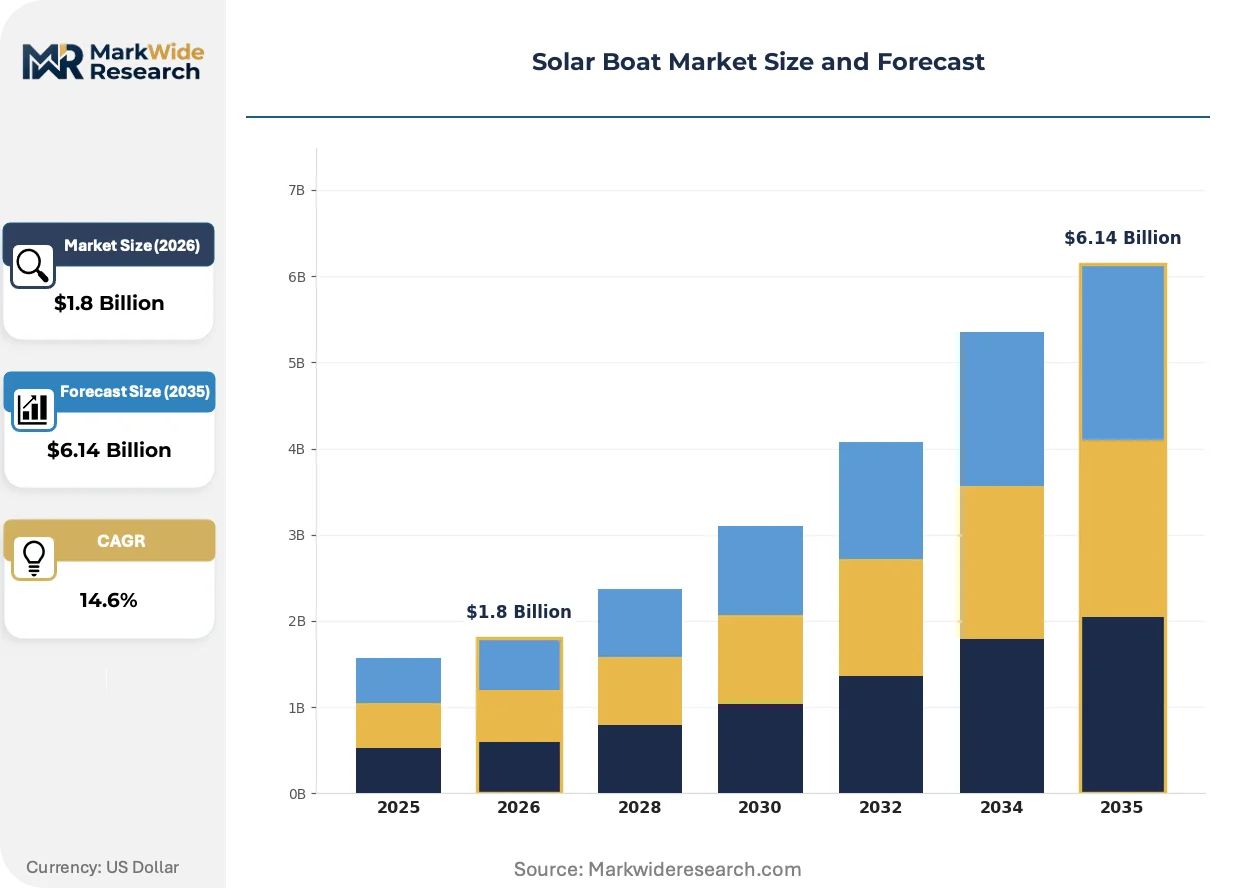
Market Dynamics
The EU Green Deal's marine emissions mandates are compressing diesel fleet replacement timelines while photovoltaic cell efficiency gains above twenty-three percent are reshaping hull-integrated power architectures for leisure and commercial operators alike.
Growth Catalysts
- EU Green Deal marine standards:Tightening harbor emissions ceilings in Barcelona, Marseille, and Venice are forcing municipal ferry operators to electrify procurement specifications before 2030 deadlines.
- Photovoltaic efficiency breakthroughs:Perovskite-silicon tandem cells are pushing deck-mounted array output toward nine kilowatts peak per square meter, extending daily cruising range for catamaran platforms.
- German manufacturing concentration:Frauscher Bootswerft and Torqeedo GmbH anchor a Bavarian supply cluster that shortens battery-to-hull integration cycles for Mediterranean buyers.
Market Restraints
- Lithium-ion cell cost volatility:Cathode material price swings for nickel-manganese-cobalt chemistry are compressing margin pools for hull-integrated battery system integrators.
- Battery supply concentration:East Asian cell manufacturers control seventy percent of maritime-certified lithium iron phosphate capacity, creating procurement bottlenecks for European boatbuilders.
- Energy density ceiling:Current solid-state prototypes remain below four hundred watt-hours per kilogram, limiting range for displacement-hull commercial vessels against diesel equivalents.
Strategic Opportunities
- Greek island ferry networks:Short-hop routes between Piraeus and Cyclades ports suit solar-electric range profiles while EU cohesion funds subsidize zero-emission fleet conversion.
- Hydrofoil-electric convergence:Candela's computer-stabilized foil systems reduce drag coefficients by eighty percent, enabling smaller battery packs for equivalent range in premium leisure segments.
- F-Gas Regulation retrofit demand:Existing refrigerated cargo vessels must replace hydrofluorocarbon systems, creating electrical infrastructure upgrade paths compatible with solar auxiliary power.
Industry Challenges
- Marine electrical certification timelines:US Coast Guard and Bureau Veritas testing protocols for high-voltage DC distribution add fourteen to eighteen months to new hull platform launches.
- Composite hull workforce scarcity:Vacuum-infused carbon fiber lamination skills concentrate in Austrian and Italian yards, constraining production scaling for Nordic and Baltic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Boat Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catamarans, Sailboats, Yachts, Ferries End User: Leisure, Commercial, Government, Research Technology: Photovoltaic, Hybrid, Wind-assisted, Battery Storage Size: Small, Medium, Large, Extra Large |
| Companies Covered | Silent Yachts, Sunreef Yachts, Greenline Yachts, Candela, SolarWave, Aqua superPower, Frauscher Bootswerft, Navalt Solar & Electric Boats, Torqeedo GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Boat Market Strategic Shifts
Hydrofoil stabilization algorithms and solid-state battery thermal management are converging to extend solar-electric range envelopes beyond coastal cruising into offshore leisure segments previously reserved for diesel displacement hulls.
Perovskite photovoltaic overlays are displacing rigid silicon arrays on curved deck surfaces. Sunreef Yachts and Silent Yachts have adopted flexible tandem-cell laminates for custom multihull superstructures. The technology is displacing conventional rigid panel mounting systems that compromised aerodynamic profiles and usable deck space.
The EU F-Gas Regulation's phase-down schedule for hydrofluorocarbon refrigerants is forcing refrigerated cargo vessel operators to specify electric compressor systems compatible with solar auxiliary power. Shipyards in the Netherlands and Denmark are retooling hull insulation specifications to meet ECHA-certified thermal performance thresholds. Mediterranean short-sea shipping routes show the fastest compliance-driven retrofit activity.
Leisure buyers now specify integrated energy management platforms as standard rather than optional equipment. Torqeedo's Deep Blue integration and Oceanvolt's ServoProp systems are displacing standalone motor-and-battery packages that required custom hull engineering. Croatian and Turkish charter fleets demonstrate the sharpest preference compression toward turnkey solar-electric architectures with smartphone-based monitoring interfaces.
Solar Boat Market Segmentation
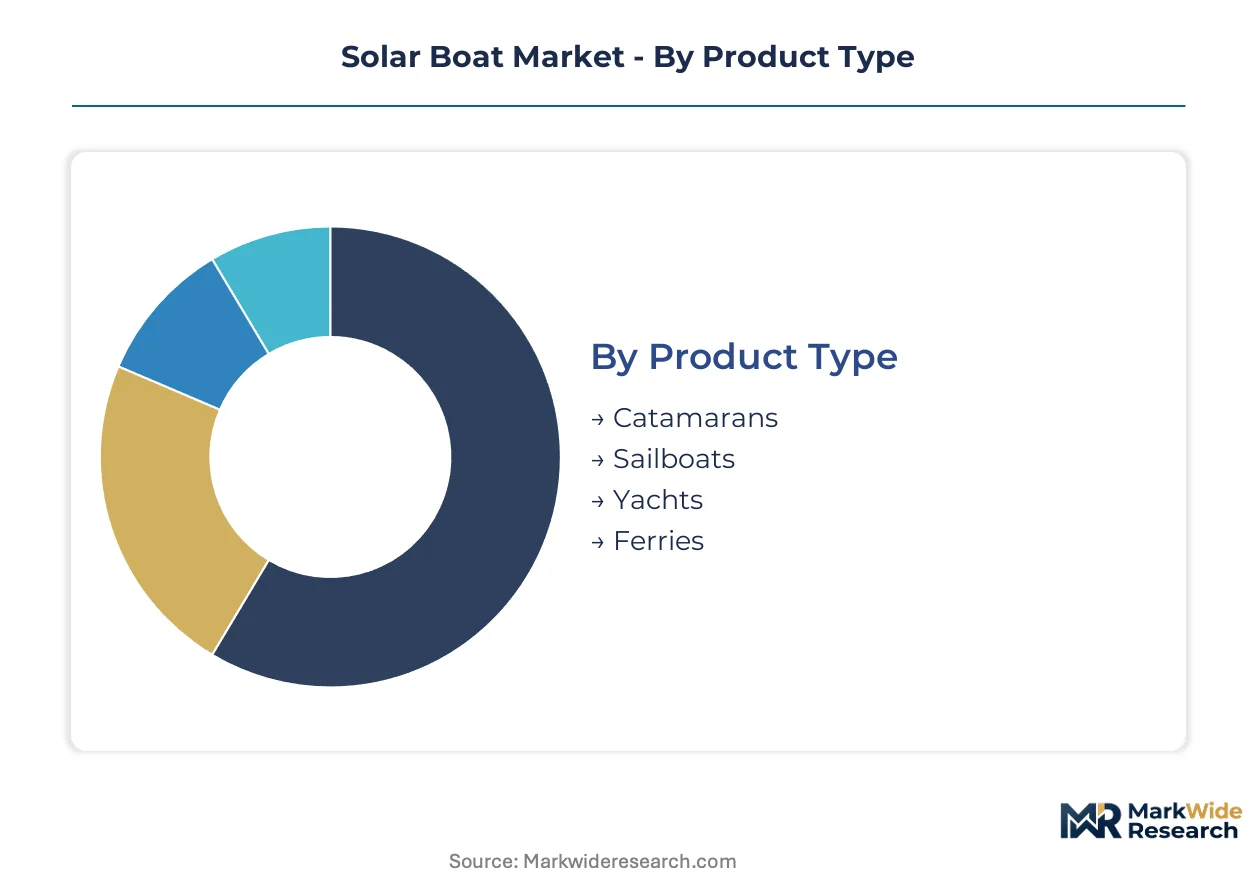
Solar boat segmentation reveals how hull architecture, propulsion integration, and operational duty cycles reshape procurement specifications across Mediterranean harbors and Baltic coastal networks. Regulatory tiering under the EU Green Deal and US Coast Guard electrical certification protocols creates divergent margin pools by segment.
Product Type:
EU harbor emissions mandates in Barcelona, Marseille, and Venice differentiate procurement timelines by hull configuration and deck surface availability for photovoltaic arrays.
- Catamarans:Twin-hull platforms maximize deck area for panel mounting, achieving 4-8 kW peak output per square meter on horizontal surfaces. Greek island ferry operators and Croatian charter fleets specify catamarans for short-hop routes where solar-electric range profiles align with EU cohesion fund subsidies.
- Ferries:Municipal operators in coastal Germany and the Netherlands face compressed replacement deadlines under tightening emissions ceilings. Deck-integrated perovskite-silicon tandem cells are extending daily operational range for displacement-hull harbor transit vessels.
- Sailboats:Auxiliary electric propulsion systems with flexible panel laminates suit leisure buyers prioritizing traditional rigging with supplemental solar range.
- Yachts:Custom multihull superstructures from Bavarian and Austrian yards integrate battery-to-hull architectures for premium long-range cruising specifications.
Catamarans handle the majority of throughput; ferries are the fastest mover on share.
End User:
Cost tiering separates turnkey integrated platforms from standalone component procurement across customer categories.
- Commercial:Municipal ferry operators and short-sea shipping lines specify marine-certified lithium iron phosphate systems with fourteen-to-eighteen-month certification timelines under Bureau Veritas and US Coast Guard protocols.
- Leisure:Croatian and Turkish charter fleets demonstrate preference compression toward smartphone-monitored solar-electric architectures with integrated energy management platforms.
- Government:EU-funded island networks and research patrol vessels require F-Gas Regulation-compliant refrigerated cargo systems with solar auxiliary power compatibility.
- Research:Oceanographic platforms prioritize silent propulsion and extended station-keeping endurance for acoustic monitoring applications.
Commercial operators dominate procurement volume; leisure buyers are expanding most quickly as charter fleet electrification accelerates.
Technology:
Application requirements dictate propulsion architecture selection between pure photovoltaic, hybrid fossil-electric, and wind-assisted configurations.
- Photovoltaic:Deck-mounted rigid silicon arrays and flexible perovskite overlays convert incident radiation to DC propulsion power. Sunreef Yachts and Silent Yachts have adopted tandem-cell laminates for curved multihull superstructures.
- Hybrid:Diesel-electric architectures bridge range limitations for displacement-hull commercial vessels where battery energy density remains below solid-state thresholds.
- Battery Storage:Cell chemistry optimization and thermal management systems concentrate margin pools for hull-integrated system integrators facing East Asian supply concentration.
- Wind-assisted:Rotor sail and kite systems supplement photovoltaic output on long-range routes with favorable prevailing wind patterns.
Photovoltaic systems anchor installed base; battery storage technology is gaining share fastest through cell certification advances.
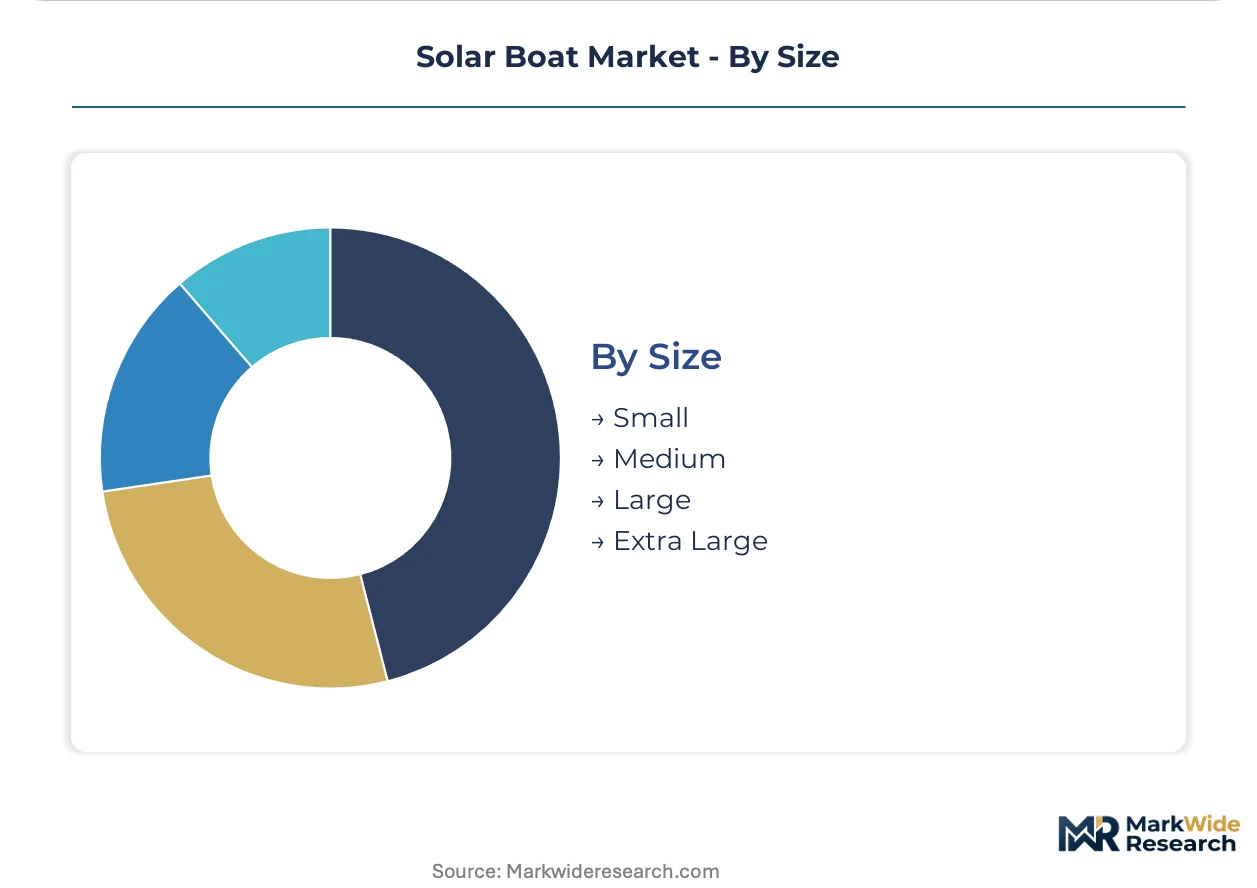
Size:
Supply concentration in Austrian and Italian composite yards constrains production scaling for extra-large hull platforms requiring vacuum-infused carbon fiber lamination expertise.
- Medium:Coastal patrol and harbor ferry specifications concentrate procurement in this bracket, balancing panel surface area against maneuverability constraints in constrained waterways.
- Large:Inter-island ferry routes and extended-range leisure cruising drive demand for battery banks exceeding 500 kWh capacity with high-voltage DC distribution architectures.
- Small:Day-cruising dinghies and marina shuttle vessels utilize portable panel arrays with modular lithium iron phosphate packs.
- Extra Large:Offshore platforms and research vessels face extended certification timelines due to electrical system complexity and structural load requirements.
Medium hulls carry the heaviest procurement volume; large platforms show the steepest expansion trajectory as range requirements extend beyond coastal cruising envelopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavarian manufacturing clusters anchor hull-integrated battery system production. Mediterranean harbor operators face compressed electrification timelines under EU emissions mandates. Asian cell suppliers control maritime-certified battery capacity.
Germany
Municipal ferry procurement specifications and leisure yacht demand concentrate in Bavarian and northern coastal regions. The EU Green Deal's marine emissions standards force diesel fleet replacement by 2030. Frauscher Bootswerft and Torqeedo GmbH anchor a Bavarian supply cluster that shortens battery-to-hull integration cycles.
France
Marseille harbor transit electrification and Riviera leisure cruising specifications drive procurement volume. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in refrigerated cargo systems. Shipyards along the Mediterranean coast retool hull insulation specifications to meet ECHA-certified thermal performance thresholds.
Netherlands
Harbor ferry operators and short-sea shipping lines face tightening emissions ceilings in Rotterdam and Amsterdam ports. Bureau Veritas electrical certification protocols govern high-voltage DC distribution testing timelines. Dutch shipyards specialize in displacement-hull harbor transit vessels with deck-integrated photovoltaic arrays.
Greece
Island ferry networks between Piraeus and Cyclades ports suit solar-electric range profiles for short-hop routes. EU cohesion funds subsidize zero-emission fleet conversion for municipal operators. Croatian and Turkish charter fleets demonstrate preference compression toward turnkey solar-electric architectures with smartphone monitoring.
United States
Leisure cruising operators in Florida and California specify integrated energy management platforms as standard equipment. US Coast Guard electrical certification protocols add fourteen to eighteen months to new hull platform launches. EPA emissions compliance requirements govern vessels entering American waters from international routes.
Solar Boat Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across hull architecture and propulsion integration. The vendor base separates into integrated platform specialists, component system suppliers, and hybrid architecture providers. Strategic archetypes include turnkey solar-electric yacht builders, marine-certified battery system integrators, and hydrofoil efficiency specialists. Competitive moves concentrate on battery supply partnerships and hull certification acceleration.
Among European-based fabricators, Silent Yachts and Sunreef Yachts occupy positions within the integrated platform tier, exemplifying turnkey solar-electric architecture for premium leisure segments. Candela represents the hydrofoil efficiency archetype, anchoring computer-stabilized foil system development. Torqeedo GmbH sits within the component system supplier tier, providing marine-certified propulsion integration for third-party hull builders.
| Leading Market Players |
|---|
| Silent Yachts |
| Sunreef Yachts |
| Greenline Yachts |
| Candela |
| SolarWave |
| Aqua superPower |
| Frauscher Bootswerft |
| Navalt Solar & Electric Boats |
| Torqeedo GmbH |
| Others |
Value Chain & Pricing Dynamics
Perovskite-silicon tandem cell adoption is displacing rigid silicon arrays across Mediterranean and Baltic yards, simultaneously shifting procurement geography toward German-Austrian integration specialists and compressing panel cost premiums against conventional marine diesel systems.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across harbor ferry and leisure yacht specifications. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-compliant refrigerated cargo conversions from basic harbor transit vessels and research patrol platforms. Certification grade under Bureau Veritas and US Coast Guard protocols drives price differentiation alongside battery chemistry tier and thermal management sophistication. Cost compression in standard-tier displacement hulls is intensifying because East Asian cell manufacturers control maritime-certified lithium iron phosphate capacity. Municipal ferry operators in coastal Germany and the Netherlands exhibit highest price sensitivity, while custom multihull leisure buyers in Croatia and Turkey absorb premium positioning for integrated energy management platforms.
Supply Chain Analysis
China, South Korea, and Japan anchor maritime-certified lithium iron phosphate cell production for hull-integrated battery systems. German and Austrian yards draw from East Asian cathode material streams and domestic carbon fiber lamination expertise for vacuum-infused composite hulls. Single-source vulnerability concentrates in East Asian cell manufacturers controlling seventy percent of certified capacity. Distribution runs through Bavarian integration clusters serving Mediterranean buyers and Dutch shipyards specializing in displacement-hull harbor transit vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
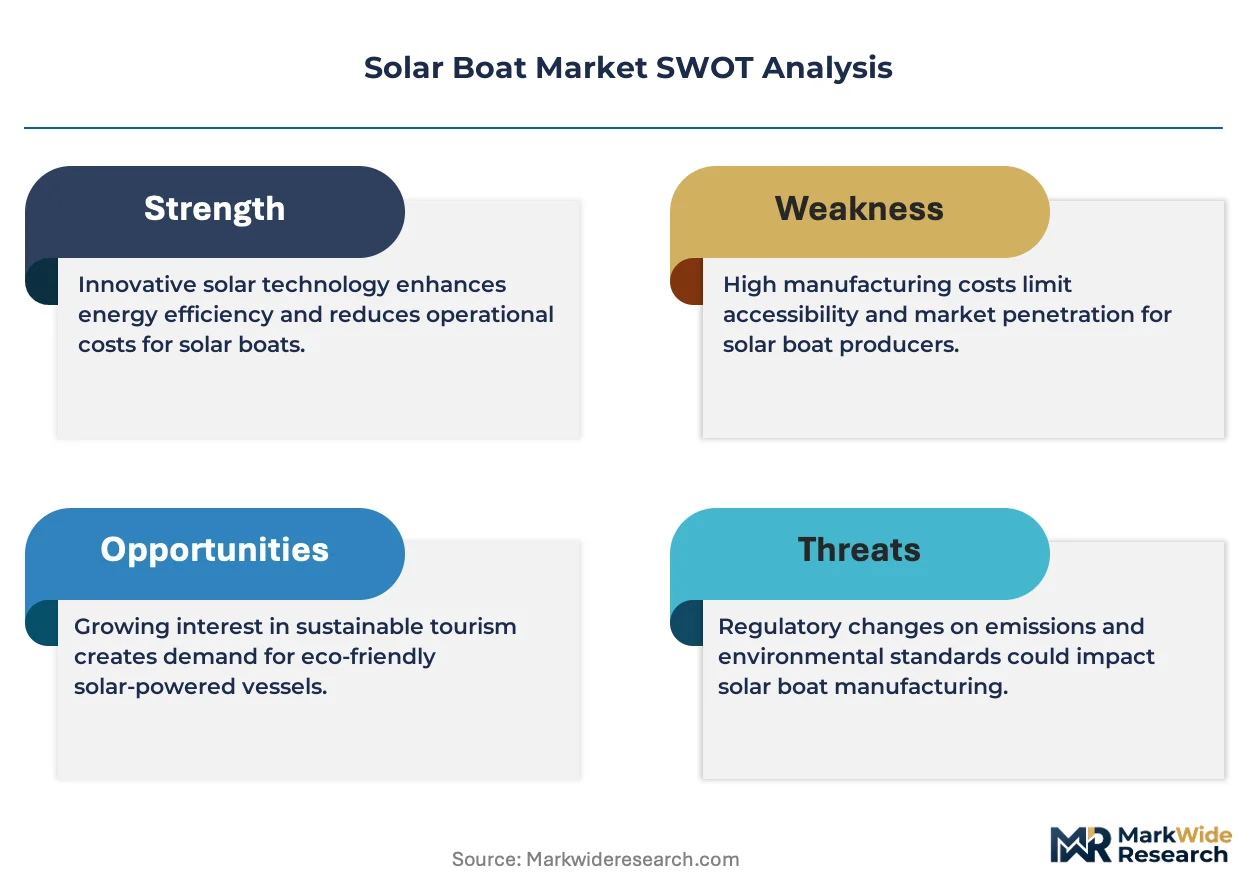
Solar boat incumbents must defend against diesel-electric hybrid architectures that bridge range limitations while regulatory timelines compress, eroding the pure solar-electric value proposition for commercial displacement-hull operators.
For Market Incumbents: Compound battery supply partnerships with East Asian cell manufacturers to secure maritime-certified lithium iron phosphate allocation against procurement bottlenecks. Deepen backward integration into thermal management system design to capture margin pools concentrated in hull-integrated architectures. Accelerate Bureau Veritas and US Coast Guard certification pipelines to compress fourteen-to-eighteen-month testing timelines that delay platform launches.
For New Entrants and Emerging Players: Smartphone-based monitoring interface gaps in Croatian and Turkish charter fleets create entry points for turnkey solar-electric platform specialists. Greek island ferry networks between Piraeus and Cyclades ports represent the most penetrable geography, with EU cohesion funds subsidizing zero-emission fleet conversion. Target municipal operators with subscription-based energy management platforms that displace standalone motor-and-battery packages requiring custom hull engineering.
For Investors and Strategic Acquirers: The market sits at a technology-convergence phase that favors hydrofoil efficiency specialists and integrated platform architects over component system suppliers. Long-term viability across the next decade hinges on solid-state battery thermal management breakthroughs and perovskite cell durability in marine environments. Watch Candela's computer-stabilized foil system licensing activity as the inflection signal for hydrofoil-electric convergence adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Partnership | East Asian cell manufacturer agreements secure maritime-certified lithium iron phosphate allocation against procurement bottlenecks. |
| Certification Pipeline Acceleration | Bureau Veritas and US Coast Guard protocol streamlining compresses fourteen-to-eighteen-month high-voltage DC distribution testing timelines. |
| Hydrofoil System Licensing | Candela's computer-stabilized foil technology transfer extends range per kilowatt-hour for premium leisure displacement. |
| Perovskite Cell Integration | Tandem-cell laminate adoption on curved multihull superstructures displaces rigid panel mounting systems compromising deck space. |
| Turnkey Platform Launch | Integrated energy management systems with smartphone monitoring displace standalone motor-and-battery packages in Croatian and Turkish charter fleets. |
Study Parameters
Desk research of customs trade data, EU regulatory filings, and maritime certification databases preceded structured interviews with Bavarian hull integration engineers, East Asian cell manufacturer account managers, Mediterranean ferry procurement officers, and Croatian charter fleet operators. Primary fieldwork with composite lamination specialists in Austrian and Italian yards validated secondary assumptions on production scaling constraints. Bottom-up vessel deployment counts across Greek island networks and top-down market sizing triangulated volume estimates.
Variance decomposition across photovoltaic efficiency trajectories, battery chemistry cost curves, and regulatory deadline schedules shaped the analytical framework over the projection horizon. Segmentation modeling incorporated hull architecture, propulsion integration technology, operational duty cycle, and regional emissions enforcement intensity. CAGRs derived from fitted adoption curves against EU Green Deal mandate timelines, with solid-state battery energy density thresholds and perovskite cell degradation rates as key forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal marine standards and US Coast Guard electrical certification protocols; material policy shifts would require re-modeling. Supply concentration in East Asian cell manufacturing and composite workforce scarcity in Austrian-Italian yards represent specific revision risks. Recalibration cycles align with material shifts in photovoltaic efficiency breakthroughs and F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
PV Water Heater Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
China Wind Power Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Solar Autoclave Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Uzbekistan Renewable Energy Market