
 Mobile Fuel Delivery Market | 2026-2036
Mobile Fuel Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Fuel Delivery Market Foresight
The price-performance boundary between premium scheduled fleet services and commodity on-demand consumer refueling is hardening. Booster Fuels leverages its captive corporate campus relationships to sustain pricing power in the commercial segment. EzFill anchors its position through dense metropolitan zone coverage, while CAFU competes aggressively on delivery speed in the Gulf states.
Mobile fuel delivery denotes the transport of refined petroleum products or alternative fuels directly to end-user vehicles or equipment via specialized tank trucks, vans, or portable containment systems, typically governed by DOT hazmat certification and NFPA 30 flammable liquids standards. The service eliminates intermediary fuel station infrastructure by enabling direct-to-asset dispensing for fleets, generators, and agricultural machinery. On-demand delivery now leads consumer acquisition metrics but scheduled delivery commands superior unit economics and retention rates among fleet accounts. Emergency delivery occupies a narrow but high-margin niche serving critical infrastructure operators during supply disruptions.
The US DOT Pipeline and Hazardous Materials Safety Administration enforces tank vehicle specifications and driver certification requirements that directly shape fleet capital deployment decisions. EPA Tier 4 emissions standards for non-road engines and OSHA Process Safety Management rules further constrain operational protocols and equipment configurations. Stakeholders must monitor evolving state-level carbon intensity scoring for transport fuels, as California's LCFS and similar programs in Oregon and Washington will progressively advantage lower-carbon delivery models over conventional diesel provisioning.
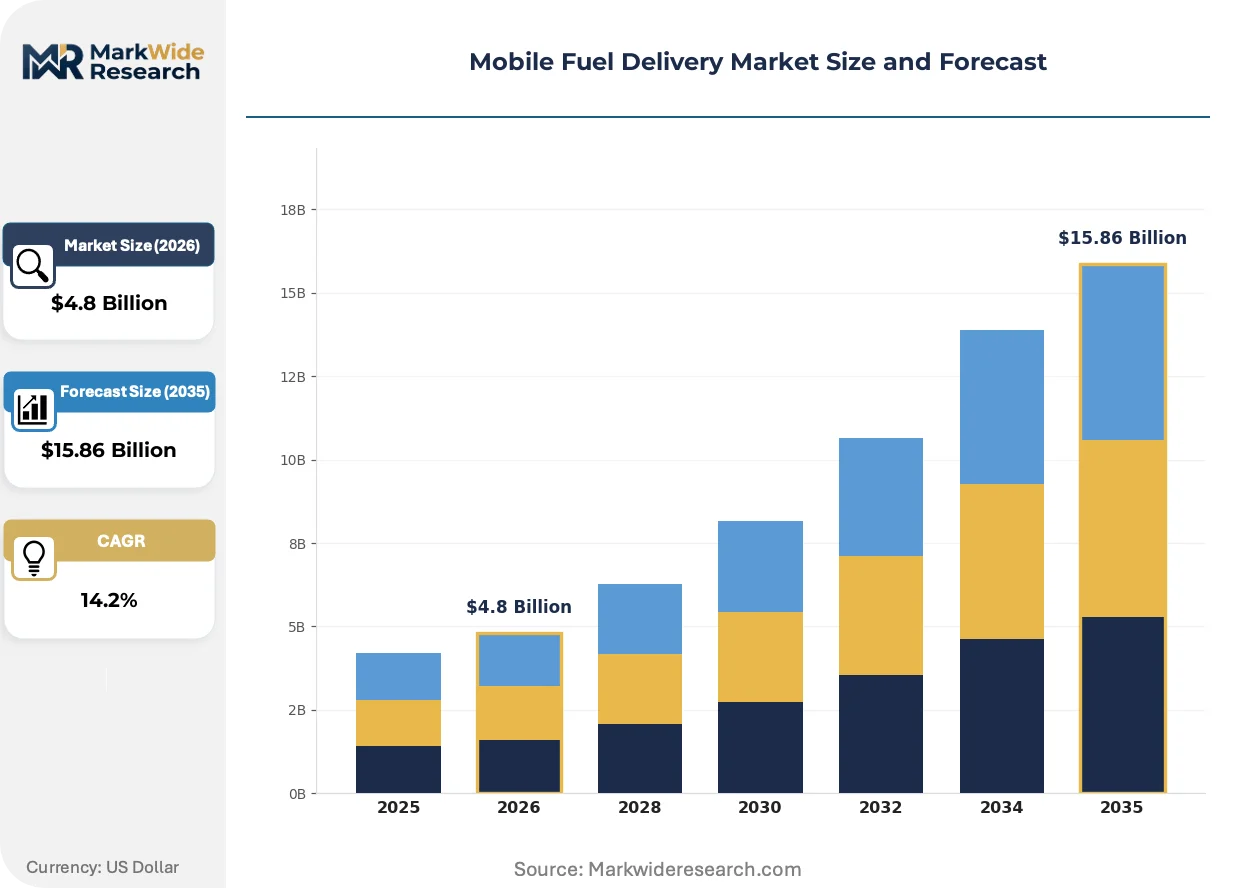
Market Dynamics
Fleet operators are consolidating refueling spend under single-vendor contracts that bundle scheduled delivery with telematics integration, compressing the addressable market for spot-market providers and rewarding operators with captive route density.
Growth Catalysts
- EPA Transport Refrigeration Unit Standards:California's CARB mandates for cold-chain emissions are forcing logistics operators to eliminate diesel idling at distribution centers, creating pull for on-site mobile refueling of electric refrigeration units.
- Congestion Pricing Corridors:Urban toll zones in Los Angeles, San Francisco, and New York City are penalizing unnecessary vehicle miles traveled, making station-based refueling trips cost-prohibitive for commercial fleets.
- Telematics Integration:Real-time fuel-level monitoring via OEM-embedded sensors is enabling predictive dispatch algorithms that optimize tanker routing and reduce deadhead miles for delivery providers.
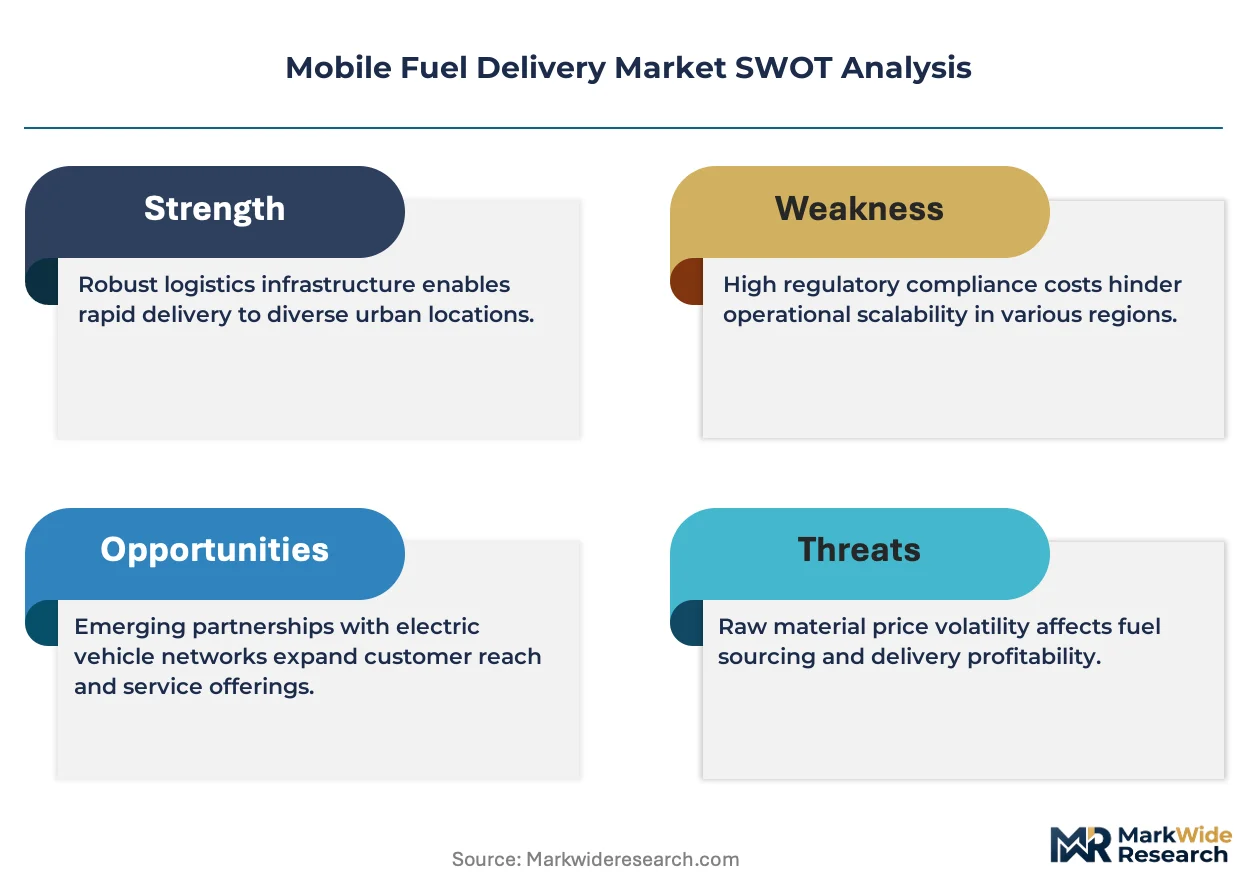
Market Restraints
- Specialized Driver Certification Scarcity:DOT hazmat endorsement requirements and CDL tank vehicle restrictions limit the eligible labor pool, inflating wage premiums for qualified operators in competitive metro markets.
- Insurance Concentration Risk:Commercial auto and pollution liability coverage for fuel transport is underwritten by a narrow cohort of specialty carriers, exposing operators to rate volatility following any significant incident.
- Station Infrastructure Sunk Costs:Existing retail fuel networks represent decades of depreciated capital, creating price-floor pressure that mobile services struggle to undercut without density-driven route efficiency.
Strategic Opportunities
- Renewable Diesel Provisioning:California's LCFS credit generation creates margin expansion for operators delivering RD100 or R99 to fleets seeking Scope 3 emissions reductions without vehicle modification.
- Generator Backup Fuel Contracts:Data centers and healthcare facilities are outsourcing emergency diesel reserves to mobile providers, replacing on-site tank ownership with just-in-time delivery guarantees.
- Off-Road Equipment Servicing:Construction and agriculture machinery operating in remote or restricted-access sites represent an underserved segment with limited competition from retail fuel networks.
Industry Challenges
- NFPA 30 Compliance Complexity:Local fire marshals interpret flammable liquids storage codes inconsistently across jurisdictions, forcing operators to maintain multiple equipment configurations and permitting strategies.
- Route Optimization Talent Gap:The intersection of logistics software, hazmat routing restrictions, and dynamic demand forecasting requires skill sets scarce in traditional fuel distribution or conventional last-mile delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Fuel Delivery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Delivery, Scheduled Delivery, On-Demand Delivery, Bulk Delivery Vehicle Type: Fuel Tank Trucks, Vans, Motorcycles, Portable Tanks Delivery Channel: Direct Sales, Online Booking, Partnerships, Mobile App Customer Segment: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | EzFill, MyPetrolPump, Booster Fuels, Fuelster, Gaston, Filld, CAFU, InstaFuel, Yoshi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Fuel Delivery Market Shifts & Advancements
Digitization is compressing the gap between fuel consumption signals and delivery dispatch, enabling service models that treat refueling as a managed utility rather than a transactional purchase.
Autonomous tanker technology is expanding into controlled-access environments such as corporate campuses and distribution yards, where geofenced operations eliminate public-road regulatory barriers. Early deployments by mining and port operators are validating remote-monitoring protocols before highway autonomy clears federal review. The structural consequence is a bifurcation between premium autonomous-enabled contracts and conventional driver-dependent services.
California's LCFS and the parallel programs emerging in Oregon and Washington are advantaging lower-carbon delivery models over conventional diesel provisioning. Fleet operators now embed carbon intensity scoring into vendor selection criteria, redirecting volume toward providers with verified renewable supply chains. The commercial segment is responding fastest, as enterprise sustainability disclosures under CSRD and SEC climate rules cascade through supply chain procurement.
Consolidated fuel management platforms are displacing fragmented point solutions that previously required fleet managers to reconcile multiple vendor invoices and consumption reports. Large logistics operators now mandate API-level integration between telematics, fuel delivery, and enterprise resource planning systems. This procurement consolidation is most visible among national fleet operators with centralized procurement functions, where single-source contracts now cover both fuel supply and consumption analytics.
Mobile Fuel Delivery Market Segmentation
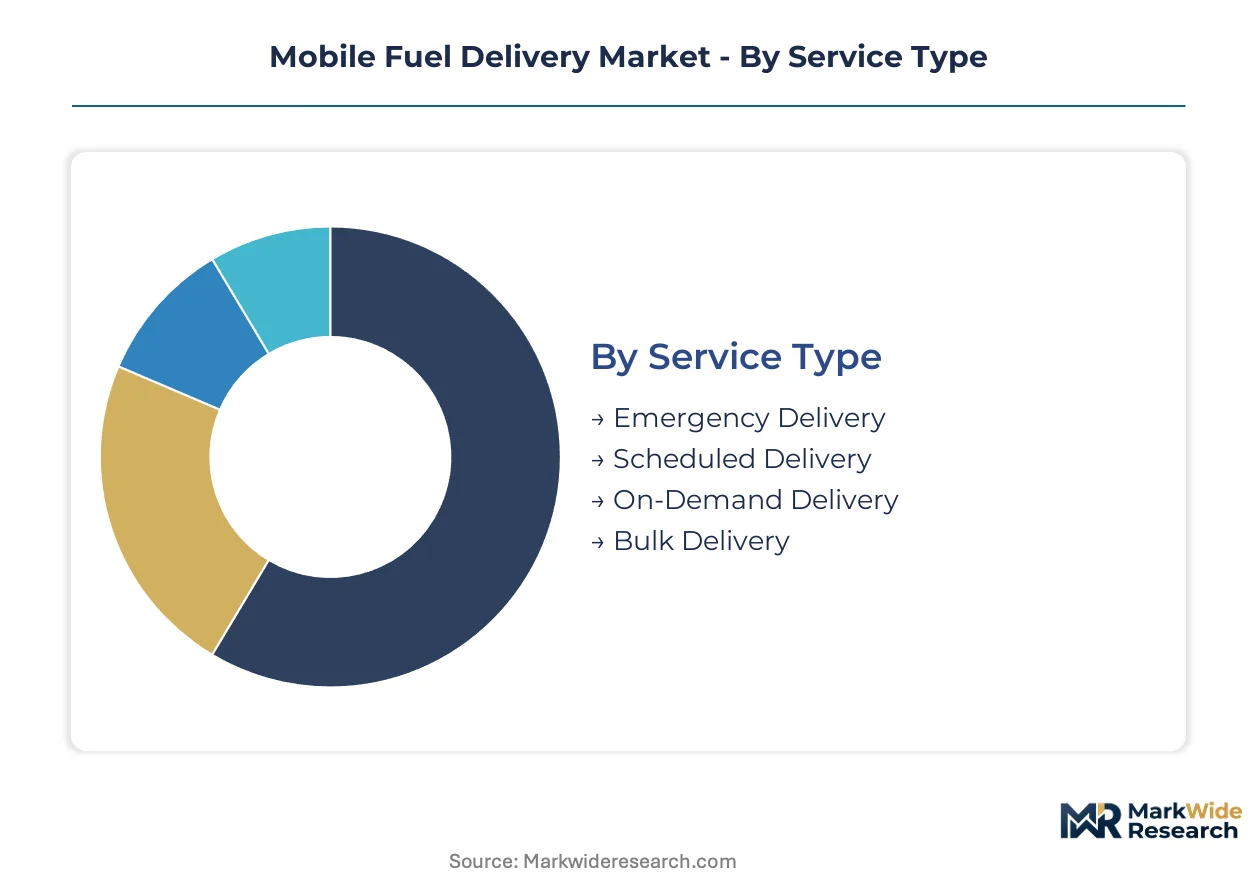
Mobile fuel delivery operators configure service portfolios around vehicle utilization patterns and customer procurement sophistication. Segmentation reveals where route density economics favor scheduled contracts versus spot-market dispatch, and which equipment investments align with regulatory constraints across customer types.
Service Type:
Fleet procurement cycles now favor subscription-based fuel management over transactional purchasing, reshaping how providers allocate tanker assets between predictable routes and dynamic demand.
- Scheduled Delivery:Recurring refueling contracts tied to telematics integration and fixed dispatch windows. Fleet operators in California's urban corridors consolidate spend under these arrangements to eliminate station visits and capture LCFS credit aggregation. This segment commands superior unit economics through captive route density and multi-year contract structures.
- On-Demand Delivery:Consumer-facing dispatch triggered by mobile application requests, typically for passenger vehicles in metropolitan zones. Demand concentrates where congestion pricing penalizes station trips, though margin compression from driver wage premiums limits profitability without autonomous routing.
- Emergency Delivery:Critical infrastructure provisioning during supply disruptions or natural disasters. Data centers and healthcare facilities outsource diesel reserves to mobile providers under just-in-time guarantee contracts, replacing on-site tank ownership.
- Bulk Delivery:High-volume provisioning for industrial generators, agricultural machinery, and construction equipment operating in restricted-access sites. NFPA 30 compliance complexity varies by jurisdiction, forcing equipment configuration adjustments.
Scheduled Delivery sits at the top of the volume ranking, with On-Demand Delivery climbing the fastest as telematics-enabled predictive dispatch matures.
Vehicle Type:
Capital deployment for mobile fuel delivery fleets hinges on DOT hazmat certification tiers and the trade-off between payload capacity and urban maneuverability.
- Fuel Tank Trucks:DOT-certified tank vehicles carrying refined petroleum products under CDL tank vehicle restrictions. These assets dominate commercial fleet contracts where volume thresholds justify dedicated routes, though driver scarcity inflates operating costs in competitive metro markets.
- Vans:Light-duty vehicles with portable containment systems for residential and small commercial accounts. Demand clusters in dense metropolitan zones where parking constraints and fire marshal permitting favor smaller equipment footprints.
- Motorcycles:Two-wheeled delivery units for last-mile consumer refueling in high-congestion corridors. Limited payload restricts service to premium fuel grades or alternative fuels with higher energy density.
- Portable Tanks:Temporary containment systems for off-road equipment servicing at construction and agricultural sites. OSHA Process Safety Management rules constrain deployment protocols, creating compliance-driven equipment specification variance.
Fuel Tank Trucks anchor fleet investment by revenue contribution, with Vans expanding most quickly as urban congestion pricing spreads.
Delivery Channel:
Customer acquisition economics diverge sharply between enterprise procurement functions and individual consumer decision-making, forcing channel strategy specialization.
- Direct Sales:Enterprise account development through dedicated fleet managers and centralized procurement negotiations. National logistics operators mandate API-level integration between telematics and fuel delivery systems, consolidating vendor relationships.
- Mobile App:Consumer-facing digital interfaces enabling on-demand dispatch and payment processing. User acquisition costs concentrate in metropolitan markets where station-based refueling friction is highest.
- Online Booking:Web-based scheduling platforms for small commercial accounts without dedicated fleet management software. This channel bridges enterprise procurement sophistication and consumer convenience expectations.
- Partnerships:Embedded service offerings through property management platforms, automotive dealerships, and fleet management providers. Corporate campus relationships sustain pricing power through captive access arrangements.
Direct Sales captures the largest contract value, with Mobile App channels showing steepest expansion trajectory as consumer awareness builds.
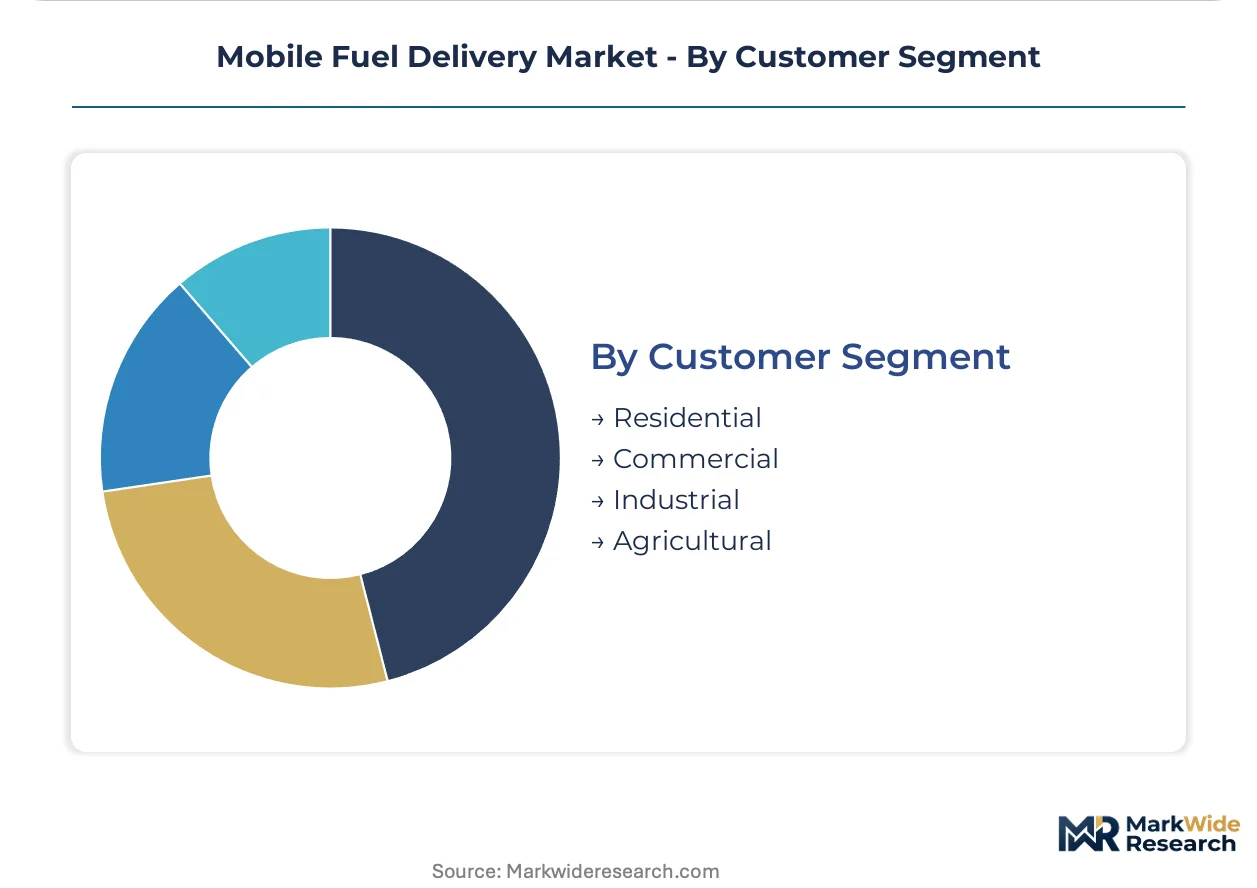
Customer Segment:
End-use differentiation determines regulatory exposure, with EPA Tier 4 emissions standards and California CARB mandates creating divergent compliance burdens across customer types.
- Commercial:Fleet operators seeking to eliminate downtime from station visits and embed carbon intensity scoring into vendor selection. Enterprise sustainability disclosures under CSRD and SEC climate rules cascade through supply chain procurement, redirecting volume toward verified renewable supply chains.
- Industrial:Manufacturing facilities, data centers, and critical infrastructure operators requiring backup fuel reserves. Insurance concentration risk for fuel transport creates procurement preference for operators with established specialty carrier relationships.
- Agricultural:Farm machinery and irrigation equipment operating in remote sites with limited retail fuel network coverage. Seasonal demand patterns require flexible asset allocation strategies from delivery providers.
- Residential:Individual vehicle owners in urban corridors where convenience premiums outweigh station price advantages. This segment shows highest churn and lowest lifetime value without subscription conversion.
Commercial accounts dominate revenue concentration, with Industrial procurement expanding most quickly as emergency outsourcing replaces on-site tank ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified hazmat drivers and logistics software specialists cluster in metropolitan corridors where congestion pricing and emissions mandates converge. California's urban zones anchor North American deployment density. European operators navigate REACH chemical safety protocols alongside national fire marshal jurisdictions.
United States
Fleet consolidation under single-vendor contracts drives demand in Los Angeles and San Francisco corridors. The EPA's transport refrigeration unit standards compel cold-chain operators to eliminate diesel idling through on-site mobile refueling. Texas construction corridors expand off-road equipment servicing as Permian Basin activity sustains bulk delivery contracts.
Canada
Telematics-integrated fleet management penetrates Ontario's Golden Horseshoe logistics networks. Transport Canada maintains equivalency with DOT hazmat certification while provincial fire codes vary across Quebec and British Columbia. Vancouver's congestion pricing pilots mirror California policy, pulling demand toward scheduled delivery models.
Germany
Industrial generator backup contracts concentrate in Frankfurt's data center cluster and Bavarian manufacturing zones. The country's national chemical regulator enforces flammable liquids storage standards that exceed baseline EU requirements. Hamburg port operators test autonomous tanker protocols in geofenced container yards.
United Arab Emirates
Corporate campus relationships anchor premium scheduled services in Dubai's business districts. MOHAP oversees occupational safety frameworks that intersect with fuel transport protocols. Abu Dhabi's industrial free zones attract mobile providers serving remote construction and agricultural machinery without retail fuel infrastructure.
India
On-demand consumer applications penetrate Bengaluru and Mumbai where station congestion wastes commercial driver hours. BIS certification requirements for petroleum product handling create compliance barriers for new entrants. Gujarat's industrial corridors sustain bulk delivery contracts for manufacturing backup generators.
Mobile Fuel Delivery Market Competitive Landscape
Capital-heavy tank truck operators compete with asset-light platform orchestrators for route density and customer acquisition. The vendor base splits between fleet-integrated subscription providers and spot-market consumer dispatchers. Three archetypes dominate: telematics-integrated fleet specialists, metropolitan zone coverage aggregators, and emergency infrastructure contractors. Consolidation pressure favors multi-year contract holders with captive route density, while autonomous technology licensing reshapes capital deployment timelines.
Within the fleet-integrated tier, Booster Fuels and EzFill exemplify divergent geographic concentration strategies. Booster Fuels anchors corporate campus relationships through captive access arrangements. EzFill occupies dense metropolitan zone coverage positions. CAFU sits within the speed-optimized Gulf states vector. These three represent how pricing power, coverage density, and delivery velocity trade off across competitive positioning.
| Leading Market Players |
|---|
| EzFill |
| MyPetrolPump |
| Booster Fuels |
| Fuelster |
| Gaston |
| Filld |
| CAFU |
| InstaFuel |
| Yoshi |
| Others |
Supply & Pricing Matrix
DOT-certified driver wages cascade through service tiers as the dominant cost input, with wage premiums for hazmat endorsements compressing margins in on-demand dispatch while scheduled fleet contracts absorb these costs through multi-year pricing structures anchored in California's urban corridors.
Pricing Analysis
Bundled subscription services separate from unbundled spot-market transactions across the pricing architecture. Three-tier pricing structure across premium scheduled fleet, standard commercial on-demand, and economy consumer dispatch levels reflects certification grade and telematics integration depth. Cost compression in the consumer tier intensifies because driver wage premiums outpace route density gains, while fleet procurement functions show lowest price sensitivity due to downtime avoidance value.
Supply Chain Analysis
Single-source vulnerability sits with specialty insurance carriers underwriting commercial auto and pollution liability coverage for fuel transport operations. Equipment manufacturing draws from US tank vehicle fabricators, German precision pumping systems, and Chinese telematics hardware suppliers. Tariff exposure on steel tank components and electronic control units creates margin volatility. Distribution runs through captive route density networks in metropolitan zones rather than dispersed retail infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion rests on renewable diesel credit arbitrage under California's LCFS and the shift from transactional dispatch toward subscription-based fleet management contracts with embedded telematics.
For Market Incumbents:Lock in captive route density through multi-year fleet contracts bundling scheduled delivery with API-level telematics integration. Secure backward integration into renewable diesel supply chains to capture LCFS credit aggregation. Autonomous tanker licensing in geofenced corporate campuses defends against driver scarcity pressures.
For New Entrants and Emerging Players:Launch via emergency diesel reserve contracts for data centers and healthcare facilities replacing on-site tank ownership. Target off-road construction and agricultural equipment servicing in Permian Basin corridors and remote industrial zones where retail fuel infrastructure is absent. Lead with just-in-time delivery guarantees rather than price competition.
For Investors and Strategic Acquirers:Consolidation pressure builds where operators lack captive route density or telematics integration capabilities. Viability over the medium-term horizon favors multi-year contract holders with verified renewable supply chains and established specialty carrier relationships. Watch CARB mandate expansion into other states as the inflection signal for geographic platform rollup.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Partnership | API-level connectivity with OEM fuel sensors enables predictive dispatch algorithms that reduce deadhead miles. |
| Renewable Diesel Supply Agreement | Verified RD100 or R99 sourcing generates LCFS credit margins for fleet customers seeking Scope 3 reductions. |
| Autonomous Tanker Pilot Program | Geofenced campus deployments validate remote-monitoring protocols before federal highway autonomy clearance. |
| Emergency Reserve Contracting | Just-in-time diesel guarantees for data centers replace capital-intensive on-site tank ownership with service revenue. |
| Hazmat Certification Pipeline Investment | Proprietary driver training programs reduce wage premiums and turnover in competitive metro markets. |
Research Methodology
Bottom-up fleet operator modeling reconciled against top-down tank vehicle deployment tracking forms the analytical core. Primary interviews with fleet procurement directors, DOT compliance officers, telematics platform engineers, and specialty insurance underwriters combined with secondary validation against EPA enforcement data, CARB credit transaction registries, DOT hazmat incident reports, and SEC filings from fuel logistics operators. Triangulation across supply-side asset counts and demand-side consumption signals calibrated segment-level projections.
Input-output matrices map fuel consumption signals through dispatch algorithms to tanker utilization rates across the projection horizon. Segmentation dimensions include service type, vehicle class, delivery channel, and customer regulatory exposure tier. CAGRs derive from logistic diffusion curves fitted to telematics penetration rates and LCFS credit price trajectories. Forecast inputs incorporate driver certification pipeline constraints and autonomous technology readiness timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden CARB mandate expansion or specialty insurance market contraction. Projections reflect assumptions about congestion pricing spread, renewable diesel supply elasticity, and hazmat driver wage trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
South Korea LNG Bunkering Market
Fuels
Bituminous Coal Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Smart Gas Solutions Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Global Steam Coal Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Aviation Fuel Market
Fuels
Smart Gas Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Liquefied Helium Tanks Market
Fuels
Turbine Drip Oil Market
Fuels
Coal Briquettes Market