
 Renewable Naphtha Market | 2026-2036
Renewable Naphtha Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Naphtha Market Outlook
Hydroprocessing of waste fats and oils into paraffinic streams is tilting the technology stack toward drop-in compatibility with conventional naphtha crackers. Neste Oyj leverages its Singapore and Rotterdam refining footprint to sustain multi-feedstock operations across palm fatty acid distillate and used cooking oil supply chains. Eni SpA anchors Mediterranean production through its Porto Marghera and Gela biorefineries, converting vegetable oils into circular feedstock for European petrochemical buyers. Shell plc competes through integrated trading desks that source certified sustainable feedstock and control offtake agreements with polymer producers seeking mass-balance chain-of-custody certification.
Renewable naphtha denotes a paraffinic liquid hydrocarbon stream derived from biomass, waste, or synthetic pathways, with carbon chain distributions typically spanning C5-C12 and hydrogen content exceeding 14% by weight, serving primarily as a steam cracker feedstock to produce ethylene, propylene, and aromatics for downstream chemical synthesis. Hydroprocessing dominates current production routes due to operational familiarity with existing refinery assets and lower capital intensity relative to emerging gasification or pyrolysis platforms. Petrochemical feedstock applications command the largest value pool today, though fuel additive blending for road and marine transport exhibits faster growth as refiners seek compliance with renewable fuel obligations across regulated jurisdictions.
The EU Green Deal and its embedded Renewable Energy Directive framework shape demand through binding sub-targets for advanced biofuels and recycled carbon fuels, while ECHA administers REACH compliance for chemical intermediates derived from novel feedstock pathways. California's Low Carbon Fuel Standard and the EPA's Renewable Fuel Standard create parallel compliance pull in North America, though feedstock traceability requirements under both programs constrain market access for uncertified supply. Stakeholders must monitor evolving lifecycle assessment methodologies and book-and-claim certification systems that will determine which production routes achieve premium pricing versus commoditization.
Market Dynamics
Hydroprocessing of waste fats and oils into paraffinic streams is consolidating the technology stack around drop-in compatibility with conventional naphtha crackers. This feedstock flexibility is redrawing competitive boundaries between integrated refiners and standalone biorefinery operators.
Growth Catalysts
- EU Green Deal emissions trading system:Chemical manufacturers in Germany and the Netherlands are expanding renewable naphtha offtake for steam cracker feedstock to manage carbon credit exposure under tightening EU ETS caps.
- Used cooking oil supply chains:Multi-feedstock hydroprocessing platforms are unlocking geographic supply diversification beyond traditional vegetable oil dependence, reducing feedstock cost volatility.
- Marine transport fuel blending:Refiners seeking compliance with IMO 2030 carbon intensity targets are redirecting renewable naphtha volumes toward bunker fuel additives, creating parallel demand pools.
Market Restraints
- Feedstock traceability requirements:California's Low Carbon Fuel Standard and EPA Renewable Fuel Standard constrain market access for uncertified supply, excluding smaller collectors lacking ISCC or RSB chain-of-custody systems.
- Palm fatty acid distillate concentration:Southeast Asian supply dominance creates geographic risk exposure for European crackers dependent on Rotterdam and Singapore refining nodes.
- Pyrolysis platform economics:Capital intensity of emerging gasification and pyrolysis routes remains prohibitive relative to hydroprocessing retrofits, delaying technology diversification.
Strategic Opportunities
- Mass-balance certification systems:Polymer producers seeking circular feedstock claims are driving demand for book-and-claim chain-of-custody models that separate physical flows from sustainability attributes.
- Recycled carbon fuels mandate:EU Renewable Energy Directive sub-targets for non-biological recycled fuels are opening regulatory space for synthetic naphtha pathways using captured carbon feedstocks.
- Steam cracker co-processing:Petrochemical operators in Belgium and France are testing higher renewable naphtha blend ratios in existing crackers, expanding addressable volume without newbuild infrastructure.
Industry Challenges
- REACH compliance timelines:ECHA administration of novel feedstock pathways for chemical intermediates creates registration bottlenecks that delay commercialization of emerging production routes.
- Lifecycle assessment methodology divergence:Inconsistent carbon accounting standards across EU, California, and voluntary certification bodies complicate cross-border trade and premium pricing realization.
- Hydroprocessing catalyst supply:Specialized hydrotreating catalyst manufacturing concentrates among limited suppliers, creating procurement risk for biorefinery expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Naphtha Market |
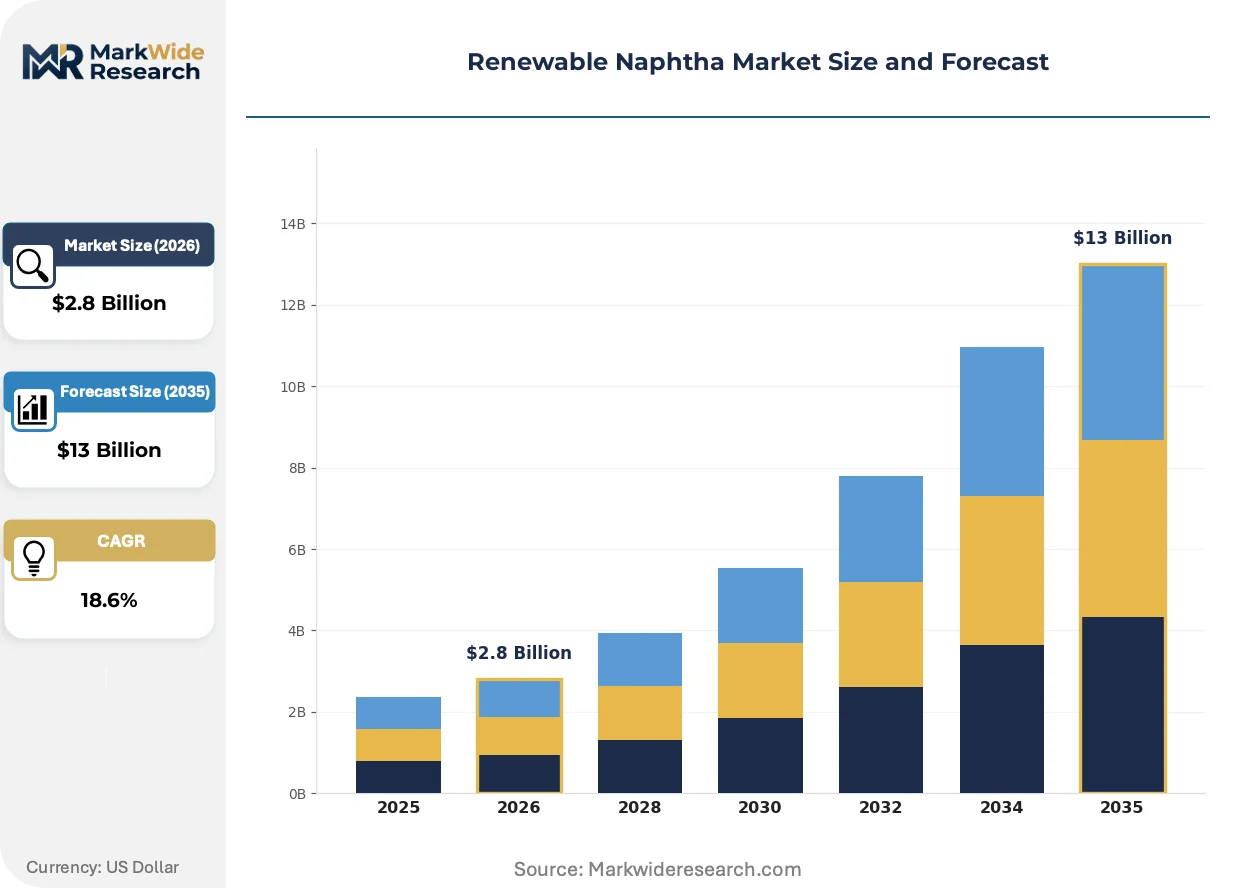
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Naphtha, Synthetic Naphtha, Blended Naphtha, Hydrocarbon Naphtha End User: Transportation, Industrial Fuels, Chemical Manufacturing, Power Generation Application: Fuel Additives, Solvents, Petrochemical Feedstock, Coatings Technology: Fermentation, Gasification, Hydroprocessing, Pyrolysis |
| Companies Covered | Eni SpA, Chevron Renewable Energy Group, Neste Oyj, Galp Energia, Preem AB, TotalEnergies SE, UPM Biofuels, Honeywell UOP, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Naphtha Market Strategic Shifts
Digital traceability systems are penetrating renewable naphtha supply chains, compressing verification timelines and enabling real-time carbon intensity scoring. These platforms are reconfiguring how refiners, traders, and polymer producers coordinate compliance documentation.
Blockchain-enabled mass-balance tracking is digitizing chain-of-custody verification from feedstock collection through steam cracker intake. Neste and trading counterparties are deploying these systems to reduce audit costs and accelerate premium pricing realization for certified sustainable volumes. The technology is compressing documentation cycles from quarterly to real-time, reshaping working capital requirements across the value chain.
EU AI Act risk classification requirements are extending into chemical manufacturing process optimization, affecting how biorefineries deploy machine learning for yield prediction and quality control. Automated hydroprocessing control systems face new transparency and human-oversight mandates that increase compliance engineering costs. Mediterranean operators are responding by segregating EU-bound production lines from export volumes to contain regulatory scope.
Polymer brand owners are consolidating supplier relationships around integrated offtake agreements that bundle feedstock supply with mass-balance certification. This concentration is displacing spot-market procurement for volume-covered renewable naphtha, compressing trader margins and favoring refiners with captive sustainability verification infrastructure. German automotive and packaging converters are driving this consolidation through scope 3 emissions reduction targets.
Renewable Naphtha Market Segmentation
Renewable naphtha's value chain fragmentation demands precise segmentation to map how feedstock pathways, conversion technologies, and end-use specifications intersect. Each dimension reveals distinct margin structures and regulatory exposure profiles that determine competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with bio-naphtha requiring sustained certification support and synthetic pathways demanding continuous carbon accounting verification.
- Bio-Naphtha:Derived from hydrotreated vegetable oils and waste fats with paraffinic C5-C12 chain distributions optimized for steam cracker compatibility. German chemical manufacturers under EU ETS pressure are expanding offtake agreements for this grade to secure mass-balance certification for scope 3 reporting.
- Synthetic Naphtha:Produced via Fischer-Tropsch synthesis or power-to-liquid routes using captured carbon and renewable hydrogen feedstocks. Momentum concentrates in the Netherlands where Rotterdam refining clusters test co-processing with conventional naphtha streams for polymer producers.
- Blended Naphtha:Physical mixtures of renewable and fossil-derived streams enabling gradual decarbonization without infrastructure overhaul. Maritime fuel suppliers in Singapore leverage this grade for IMO 2030 compliance without engine modifications.
- Hydrocarbon Naphtha:Purified paraffinic streams meeting stringent aromatics specifications for high-performance chemical synthesis. Italian petrochemical buyers at Porto Marghera and Gela biorefineries prioritize this grade for polyethylene production.
Bio-naphtha holds the largest share; momentum sits with synthetic naphtha as EU Renewable Energy Directive sub-targets for recycled carbon fuels expand addressable volume.
End User:
Cost tier stratification separates premium chemical feedstock buyers from compliance-driven fuel blenders, with industrial fuel applications occupying a contested middle ground.
- Transportation:Road and marine fuel blenders seeking renewable fuel obligation compliance drive volume through California LCFS and EPA RFS pathways. Used cooking oil supply chains concentrate in this segment due to lower carbon intensity scores relative to virgin vegetable oils.
- Chemical Manufacturing:Steam cracker operators producing ethylene, propylene, and aromatics for downstream polymer synthesis. Belgian and French petrochemical clusters are testing higher renewable naphtha blend ratios without newbuild infrastructure investment.
- Industrial Fuels:Process heat and boiler applications in cement, steel, and paper industries transitioning from natural gas. This segment faces margin compression from competing biomethane and hydrogen alternatives.
- Power Generation:Peaking plant operators and district heating utilities seeking dispatchable renewable fuel. Limited penetration due to cost disadvantage versus biomass pellets and renewable natural gas.
Chemical manufacturing commands premium pricing; transportation is expanding most quickly as marine bunker fuel regulations tighten.
Application:
Volume concentration in petrochemical feedstock applications masks faster growth in fuel additives as refiners redirect hydroprocessing output toward compliance pools.
- Petrochemical Feedstock:Dominant value pool serving ethylene crackers and aromatics complexes with C5-C12 paraffinic streams. German automotive and packaging converters drive demand through scope 3 emissions reduction targets and mass-balance certification requirements.
- Fuel Additives:Blending components for diesel, gasoline, and marine bunker fuels to meet renewable content mandates. IMO 2030 carbon intensity targets are redirecting renewable naphtha volumes from chemical to fuel applications.
- Solvents:Industrial degreasing, extraction, and cleaning applications requiring low-aromatic hydrocarbon streams. REACH compliance timelines under ECHA administration constrain novel feedstock pathway commercialization.
- Coatings:Paint, varnish, and adhesive formulations utilizing renewable naphtha as carrier solvents and resin precursors. Niche positioning due to competition with bio-based alcohols and esters.
Petrochemical feedstock holds the largest share; fuel additives are climbing the fastest as regulatory compliance obligations multiply across jurisdictions.
Technology:
Supply concentration in hydroprocessing reflects capital efficiency advantages, though pyrolysis and gasification platforms attract development capital for waste feedstock flexibility.
- Hydroprocessing:Catalytic hydrotreating of fats, oils, and greases into paraffinic streams using existing refinery infrastructure. Neste's Singapore and Rotterdam operations demonstrate multi-feedstock capability across palm fatty acid distillate and used cooking oil supply chains.
- Pyrolysis:Thermal decomposition of biomass and plastic waste into liquid hydrocarbons requiring upgrading to naphtha specifications. Capital intensity remains prohibitive relative to hydroprocessing retrofits, delaying commercial scale-up.
- Gasification:High-temperature conversion of solid biomass or waste into synthesis gas for Fischer-Tropsch synthesis. Eni SpA's Mediterranean biorefineries explore this route for agricultural residue valorization.
- Fermentation:Biological conversion of sugars to hydrocarbon intermediates with subsequent upgrading to naphtha range molecules. Limited deployment due to feedstock competition with food and biochemical markets.
Hydroprocessing holds the largest share; pyrolysis is gaining share fastest as waste plastic feedstock availability expands and carbon accounting methodologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical buyers in Germany and the Netherlands dominate procurement volumes, while Singapore and Rotterdam serve as the primary refining nodes for multi-feedstock hydroprocessing operations.
Germany
Steam cracker operators in Ludwigshafen and Cologne-Godorf are expanding renewable naphtha offtake to manage carbon credit exposure under tightening EU ETS caps. The EU Green Deal's emissions trading system penalizes fossil-derived feedstock intensity. Chemical manufacturers in the Rhine-Ruhr cluster are testing higher blend ratios in existing crackers without newbuild infrastructure.
Netherlands
Rotterdam refining hubs leverage deepwater access to process palm fatty acid distillate and used cooking oil from Southeast Asian supply chains. REACH compliance timelines under ECHA administration regulate novel feedstock pathways for chemical intermediates. Port operators and polymer producers are piloting mass-balance certification systems that separate physical flows from sustainability attributes.
Singapore
Maritime fuel suppliers are redirecting renewable naphtha volumes toward bunker fuel additives to meet IMO 2030 carbon intensity targets. The city-state's trading infrastructure enables real-time carbon intensity scoring for certified sustainable volumes. Refinery retrofits along Jurong Island support multi-feedstock hydroprocessing platforms with drop-in compatibility for conventional crackers.
Italy
Eni SpA anchors Mediterranean production through Porto Marghera and Gela biorefineries, converting vegetable oils into circular feedstock for European petrochemical buyers. The EU Renewable Energy Directive's sub-targets for advanced biofuels create compliance pull for Italian chemical manufacturers. Petrochemical buyers prioritize hydrocarbon naphtha grades meeting stringent aromatics specifications for polyethylene production.
United States
California's Low Carbon Fuel Standard and the EPA's Renewable Fuel Standard constrain market access for uncertified supply, favoring collectors with ISCC or RSB chain-of-custody systems. Used cooking oil supply chains concentrate in the Midwest and Southeast due to lower carbon intensity scores relative to virgin vegetable oils. Gulf Coast refiners are evaluating hydroprocessing retrofits to capture renewable fuel obligation premiums across regulated jurisdictions.
Renewable Naphtha Market Competitive Environment
Channel-controlling players compete with product-specialist players across renewable naphtha value chains. Integrated energy majors leverage trading desks and offtake agreements to secure polymer producer relationships, while standalone biorefinery operators compete on feedstock flexibility and certification infrastructure. Three archetypes dominate: hydroprocessing specialists with multi-feedstock platforms, integrated traders controlling mass-balance chain-of-custody systems, and technology licensors supplying catalytic upgrading systems. Capacity expansion and strategic partnerships represent the dominant competitive moves, with operators seeking to lock in long-term supply agreements ahead of regulatory mandate tightening.
Within the integrated energy major tier, Shell plc and TotalEnergies SE exemplify channel-controlling strategies through captive trading infrastructure and sustainability verification systems. Neste Oyj occupies a distinctive position as a hydroprocessing specialist with geographic diversification across Singapore and Rotterdam refining nodes. These three entities anchor competitive dynamics by setting certification standards and pricing benchmarks that shape procurement decisions across German automotive and packaging converters.
| Leading Market Players |
|---|
| Eni SpA |
| Chevron Renewable Energy Group |
| Neste Oyj |
| Galp Energia |
| Preem AB |
| TotalEnergies SE |
| UPM Biofuels |
| Honeywell UOP |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
Rotterdam refinery undercapacity is tightening supply availability for European petrochemical buyers, forcing German chemical manufacturers to accept longer contract terms and premium indexation clauses to secure renewable naphtha volumes. This utilization squeeze simultaneously empowers Singapore-based suppliers to enforce stricter payment terms while compelling buyers to build strategic inventory buffers against allocation risk.
Pricing Analysis
Cost-plus contracts with palm fatty acid distillate indexation dominate renewable naphtha procurement, linking prices to Rotterdam spot benchmarks plus sustainability certification premiums. Three-tier pricing structure across ISCC-EU certified, RSB-certified, and uncertified grades creates differentiation based on chain-of-custody rigor and carbon intensity scores. Pricing pressure stems from used cooking oil feedstock competition as marine fuel blenders bid for the same waste oil pools. Small independent collectors exhibit highest price sensitivity due to working capital constraints, while integrated polymer producers with mass-balance systems absorb premiums for scope 3 reporting compliance.
Supply Chain Analysis
Export-control regimes on hydroprocessing catalyst technology limit equipment flows to unlicensed biorefinery operators, constraining capacity expansion outside established licensing networks. Supply concentrates in Singapore, the Netherlands, and Italy where Neste, Shell, and Eni operate multi-feedstock platforms. Feedstock dependencies span Southeast Asian palm fatty acid distillate, European used cooking oil networks, and Mediterranean vegetable oil streams. Single-source vulnerability runs through Rotterdam refining nodes that process 60% of EU-imported waste fats. Distribution runs through integrated trading desks controlling mass-balance certification documentation and long-term offtake agreements with polymer producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with EU Green Deal compliance infrastructure creating switching costs that lock in incumbent relationships and deter new entrant disruption.
For Market Incumbents: Build certification moats through captive ISCC-EU and RSB auditing infrastructure that smaller competitors cannot replicate cost-effectively. Expand hydroprocessing capacity in Rotterdam and Singapore to capture used cooking oil supply chain consolidation. Defend against pyrolysis technology disruption by securing exclusive feedstock agreements with waste management aggregators before novel routes achieve scale. For New Entrants and Emerging Players: US Gulf Coast underpenetration offers white-space opportunity as California LCFS and EPA RFS compliance pools expand faster than domestic hydroprocessing capacity. Target Midwest used cooking oil collectors lacking chain-of-custody systems as acquisition candidates to shortcut certification timelines. Enter through toll-processing partnerships with existing refiners rather than greenfield construction to bypass capital intensity barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refiners with long-term offtake agreements and captive trading infrastructure that insulates against spot price volatility. Five-to-ten year viability favors operators with backward integration into waste oil collection networks rather than feedstock-dependent pure-plays. Monitor EU Renewable Energy Directive sub-target revisions for recycled carbon fuels as the signal indicating synthetic naphtha pathway premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Rotterdam and Singapore hub additions secure multi-feedstock flexibility for EU ETS compliance demand. |
| Backward Integration | Captive used cooking oil collection networks reduce feedstock cost volatility and certification risk exposure. |
| Mass-Balance Certification Investment | ISCC-EU and RSB infrastructure enables premium pricing realization from German automotive and packaging converters. |
| Long-term Supply Agreement | Polymer producer offtake contracts lock in volume coverage and displace spot-market procurement dependence. |
| Joint Venture | Partnerships with waste management aggregators preempt pyrolysis competitors from securing plastic waste feedstocks. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with biorefinery operations managers, petrochemical procurement leads, sustainability certification auditors, and marine fuel trading desks; and secondary validation through EU ETS registry data, ISCC certification databases, EPA RFS compliance reports, and customs trade flows for palm fatty acid distillate and used cooking oil. Bottom-up capacity modeling across Singapore, Rotterdam, and Mediterranean refining nodes was triangulated against top-down demand estimates from German and Dutch steam cracker operators.
Forecast inputs considered feedstock availability constraints, regulatory mandate tightening trajectories, and technology cost curves across hydroprocessing, pyrolysis, and gasification platforms. Segmentation dimensions modeled include product type tier, end-use application, conversion technology, and regional regulatory framework. CAGRs were derived from capacity expansion announcements, offtake agreement volumes, and compliance obligation schedules across the projection horizon. Carbon accounting methodology evolution and book-and-claim system adoption rates served as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated energy majors to vertically control waste oil collection networks would shift outcomes. Material shifts in EU Renewable Energy Directive sub-target allocations or California LCFS carbon intensity benchmark revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Malaysia Renewable Energy Market