
 South Africa Solar Energy Market | 2026-2036
South Africa Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Solar Energy Market Outlook
The South African solar market is shifting between premium engineered solutions and commodity hardware as procurement teams face divergent risk appetites. ENGIE SA leverages its global EPC expertise to dominate utility-scale tenders with integrated project delivery. SOLA anchors the commercial and industrial segment through behind-the-meter installations for mining and manufacturing clients. Canadian Solar Inc. competes on module cost, sustaining volume flows into distributed generation channels.
South Africa solar energy encompasses photovoltaic and concentrated thermal systems that convert sunlight into electricity through semiconductor junctions or heat transfer fluids, with crystalline silicon modules achieving conversion efficiencies above 21 percent in field conditions. The technology serves grid stabilization, rural electrification, and corporate decarbonization objectives across a supply-constrained power system. Photovoltaic panels occupy the largest revenue pool as import tariffs and local content rules protect domestic assembly lines. Battery storage represents the fastest-expanding category as load-shedding drives hybrid installation uptake. Grid-tied systems retain structural dominance, though off-grid and hybrid configurations are capturing margin from energy security premiums.
South Africa's energy regulator, NERSA, governs licensing thresholds and wheeling frameworks that determine project scale economics, while the Department of Mineral Resources and Energy administers the REIPPPP auction rounds. SABS certification requirements for module durability and inverter grid compliance create non-tariff barriers that filter supplier entry. Stakeholders must track Eskom's transmission backlog and municipal wheeling agreements as these infrastructure variables determine project bankability ahead of procurement cycles.
Market Dynamics
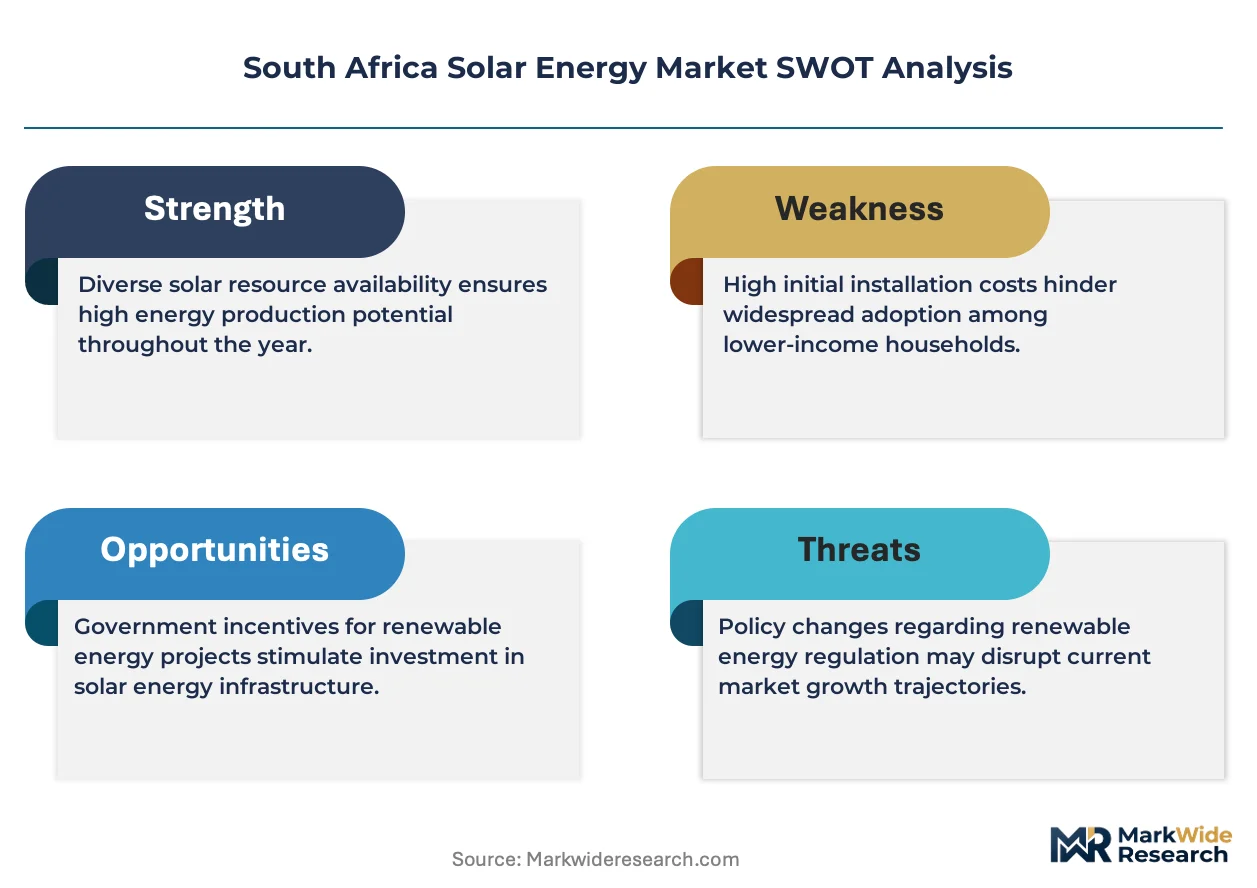
Eskom's transmission backlog and municipal wheeling bottlenecks are forcing developers to restructure project timelines around infrastructure readiness rather than pure irradiance economics.
Growth Catalysts
- REIPPPP Auction Rounds:The Department of Mineral Resources and Energy's competitive bidding framework guarantees long-term power purchase agreements that de-risk utility-scale capital deployment.
- Mining Sector Decarbonization:Anglo American Platinum and Sibanye-Stillwater are procuring behind-the-meter solar to secure baseload against load-shedding disruptions.
- Bifacial Module Technology:Albedo capture from South Africa's high-reflectivity terrain boosts yield per hectare in Northern Cape ground-mount installations.
Market Restraints
- Import Tariff Volatility:Southern African Customs Union duties on Chinese crystalline silicon modules create input cost unpredictability for EPC contractors.
- Grid Connection Queues:Eskom's 5-year transmission expansion backlog delays commercial operation dates for projects already holding land and permits.
- Local Content Thresholds:SABS certification and domestic assembly mandates inflate hardware costs above pure import parity.
Strategic Opportunities
- Municipal Wheeling Liberalization:Johannesburg and Cape Town pilot programs allow private generators to sell across distribution networks.
- Agrivoltaic Convergence:Dual-use solar arrays above Northern Cape vineyards and livestock operations unlock marginal land productivity.
- Battery Hybridization:Lithium-ion storage paired with PV captures arbitrage value from Eskom's time-of-use tariff restructuring.
Industry Challenges
- Grid Code Compliance Timelines:NERSA's inverter certification backlog stretches equipment approval to 14 months.
- Skilled EPC Labor Scarcity:High-voltage substation commissioning engineers command 40% wage premiums above regional benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Solar Energy Market |
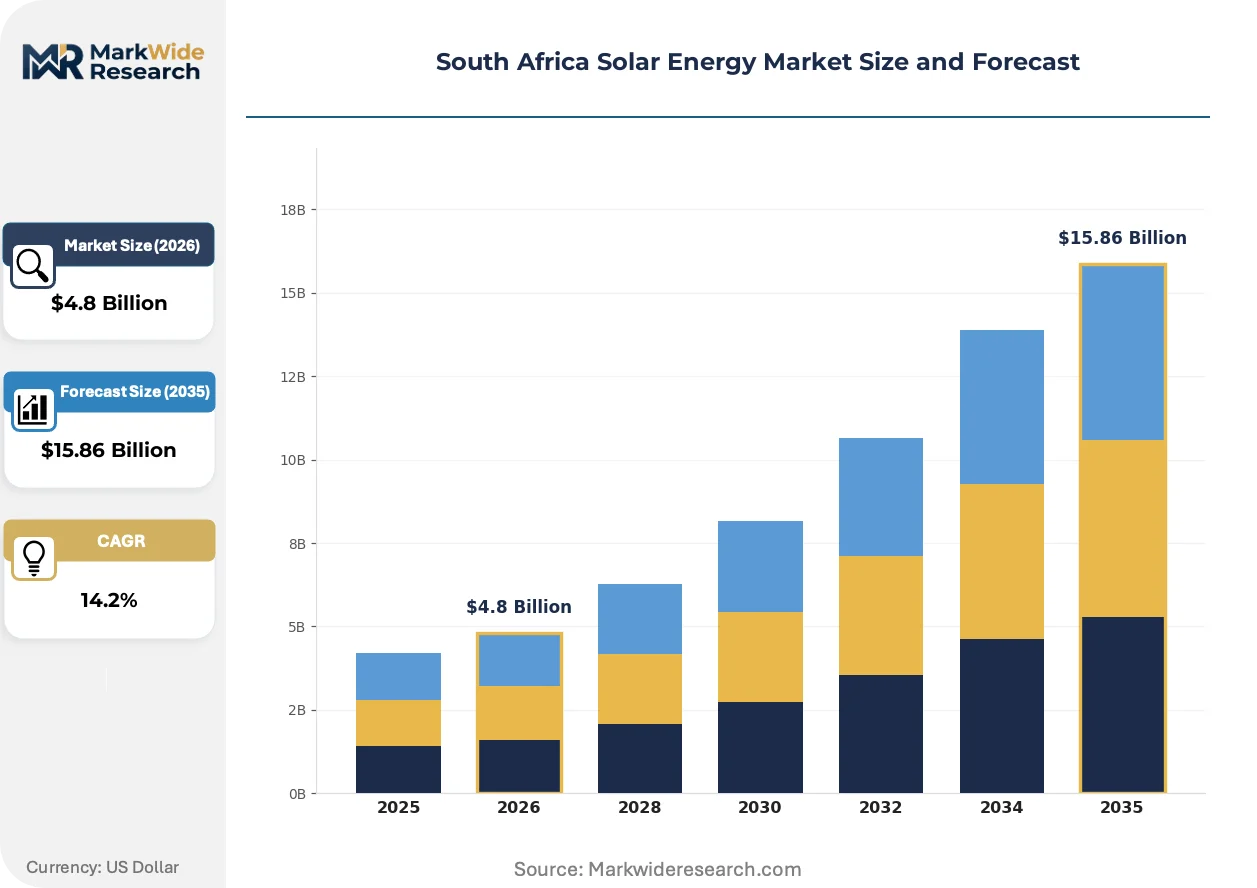
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Battery Storage, Mounting Systems End User: Residential, Commercial, Industrial, Government Installation Type: Grid-Tied, Off-Grid, Hybrid, Standalone Technology: Thin-Film, Crystalline Silicon, Bifacial, Concentrated Solar Power |
| Companies Covered | ENGIE SA, SOLA, ARTsolar Pty Ltd, JinkoSolar Holding Co. Ltd., Renenergy Ltd, Canadian Solar Inc., Scatec, Juwi Renewable Energies (Pty) Ltd, Enel Spa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Solar Energy Market Strategic Shifts
Technology trajectories in South African solar are compressing installation timelines while policy experiments reshape who can generate and trade electricity.
Containerized battery energy storage systems are modularizing behind-the-meter deployments for mining houses. Anglo American's Mogalakwena platinum complex adopted skid-mounted lithium units that cut commissioning from 18 months to 90 days. This modular architecture is compressing vendor qualification cycles and allowing procurement teams to phase capacity additions against load-shedding severity.
NERSA's 2023 licensing threshold revision exempts sub-100 MW generators from generation licenses, slashing regulatory overhead for commercial and industrial projects. The exemption shifts compliance burden to municipal connection approvals, creating uneven implementation across metros. Developers now prioritize Johannesburg and eThekwini where wheeling frameworks are operational over smaller municipalities with untested processes.
Power purchase agreement tenors are shortening as offtakers resist 20-year commitments amid technology cost uncertainty. Mining procurement teams now negotiate 7-year contracts with reopener clauses tied to module price indices. This behavioral shift is visible in the Northern Cape, where renewable developers face compressed debt tenors and elevated equity returns to compensate for refinancing risk.
South Africa Solar Energy Market Segmentation
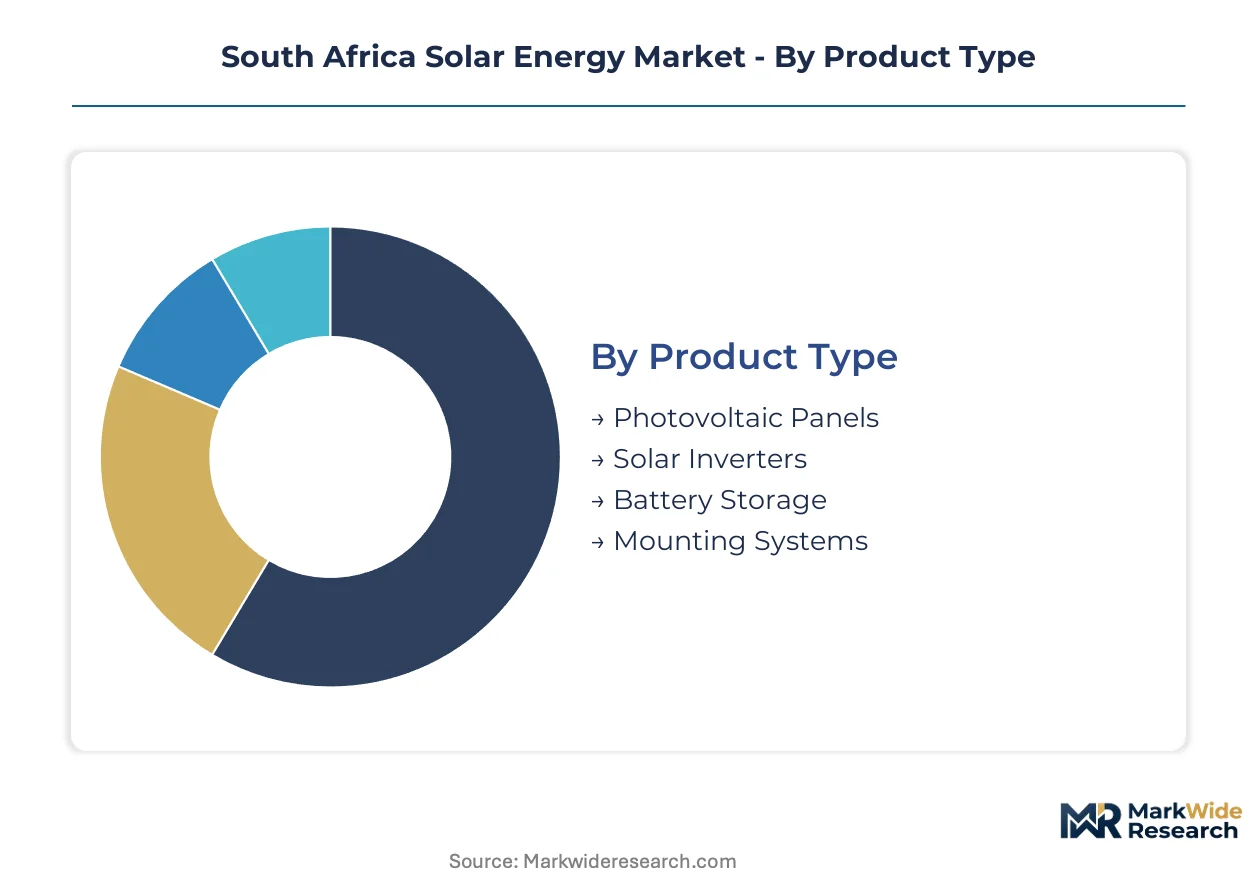
South Africa's solar market fragments across hardware categories, customer types, and system architectures that each carry distinct margin profiles and regulatory exposures. Procurement teams navigate these layers to match risk tolerance against load-shedding severity and grid access timelines.
Product Type:
Capital allocation priorities differ sharply between generation assets and balance-of-system components, with procurement teams weighing upfront module costs against lifecycle inverter reliability and storage arbitrage value.
- Photovoltaic Panels:Crystalline silicon modules dominate utility-scale and distributed installations, with domestic assembly lines protected by Southern African Customs Union tariffs. Northern Cape ground-mount projects absorb the largest volume flows as developers exploit high irradiance and flat terrain for single-axis tracking arrays.
- Solar Inverters:String and central inverter architectures convert DC generation to grid-compliant AC output, with NERSA certification timelines stretching equipment approval to 14 months. Commercial and industrial behind-the-meter sites drive demand for three-phase string units that minimize downtime during load-shedding events.
- Battery Storage:Lithium-ion systems paired with PV capture time-of-use arbitrage under Eskom's restructuring tariffs.
- Mounting Systems:Single-axis trackers and fixed-tilt racking anchor Northern Cape utility-scale deployments, with galvanized steel structures resisting corrosion in high-UV environments.
Volume sits with Photovoltaic Panels; growth tilts toward Battery Storage as hybrid installations displace pure grid-tied configurations.
End User:
Customer segments separate by scale economics and offtake certainty, with mining houses offering bankable demand against municipal and residential payment risk.
- Residential:Rooftop systems under 10 kW address suburban load-shedding exposure, with financing constraints limiting penetration to affluent metros. Cape Town and Johannesburg municipalities with operational wheeling frameworks attract installer concentration.
- Commercial:Office and retail installations prioritize payback periods under five years, with landlords splitting savings through green lease clauses.
- Industrial:Anglo American Platinum and Sibanye-Stillwater procure behind-the-meter solar to secure baseload against grid instability, driving the steepest expansion trajectory in the end-user stack.
- Government:Public buildings and rural electrification programs lag procurement cycles due to fiscal constraints and tender complexity.
Industrial offtakers command the tightest EPC margins; Commercial sites offer the most scalable project development pipeline.
Installation Type:
System architecture choice reflects grid access quality and diesel backup economics, with hybrid configurations capturing premium pricing from energy security demand.
- Grid-Tied:Pure export systems without storage retain structural dominance in Northern Cape utility-scale developments where transmission availability permits, though Eskom's connection queue delays commercial operation dates.
- Off-Grid:Standalone diesel-PV hybrids serve remote mining camps and agricultural operations beyond distribution network reach, with high levelized costs accepted for reliability.
- Hybrid:Grid-connected PV-plus-storage installations are gaining share fastest as mining houses and manufacturers prioritize uninterrupted operations.
- Standalone:Mini-grids for rural electrification depend on development finance and municipal concession structures with limited private capital deployment.
Grid-Tied retains installed base dominance; Hybrid configurations climb the fastest as load-shedding frequency reshapes procurement specifications.
Technology:
Cell architecture and thermal system choices trade efficiency against cost and local supply chain maturity, with bifacial modules exploiting South Africa's high-albedo terrain.
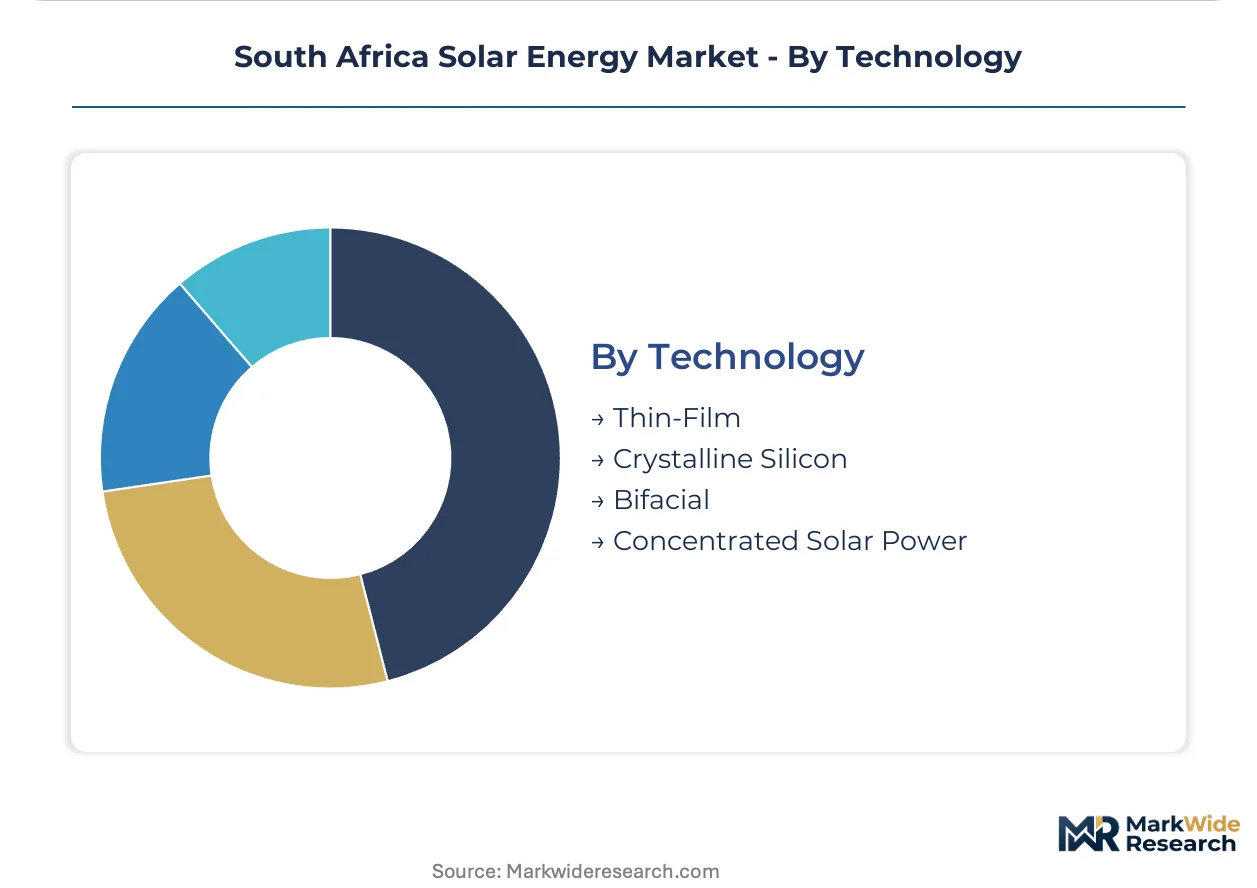
- Thin-Film:Cadmium telluride and CIGS technologies occupy niche utility-scale applications where temperature coefficient advantages offset lower conversion efficiency, with limited domestic manufacturing presence.
- Crystalline Silicon:Monocrystalline PERC and TOPCon cells achieve field efficiencies above 21 percent, anchoring both distributed and utility-scale procurement as the cost benchmark technology.
- Bifacial:Double-glass modules capturing rear-side albedo boost yield per hectare in Northern Cape ground-mount installations, with developers accepting 10-15 percent hardware premiums for 8-12 percent energy gains.
- Concentrated Solar Power:Molten salt tower and parabolic trough systems with thermal storage offer dispatchable renewable output, though high capital intensity and water requirements constrain greenfield development.
Crystalline Silicon captures procurement volume; Bifacial architectures expand most quickly as Northern Cape developers optimize land productivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northern Cape province anchors South Africa's solar deployment through its 6.5 kWh/m² daily irradiance and expansive flat terrain. Developers concentrate procurement teams in Upington and De Aar to exploit transmission corridor proximity and municipal wheeling readiness.
Gauteng
Johannesburg's commercial hubs drive behind-the-meter installations for mining headquarters and manufacturing plants. The City of Johannesburg's wheeling pilot allows private generators to sell across its distribution network. Sandton and Midrand host EPC contractor clusters serving industrial offtakers seeking 7-year PPA tenors with price reopeners.
Western Cape
Cape Town's municipal wheeling framework attracts commercial solar developers targeting retail and office load profiles. The Western Cape Government's Green Economy Strategy mandates public building retrofits. Atlantis Special Economic Zone concentrates module assembly lines protected by SACU local content thresholds.
KwaZulu-Natal
Durban's port infrastructure positions the province as a gateway for imported inverters and battery components. Richards Bay industrial zone hosts Anglo American's decarbonization procurement for smelter operations. eThekwini Municipality's wheeling regulations lag Johannesburg, delaying C&I project timelines.
Mpumalanga
The coal belt's grid instability accelerates mining house solar procurement for platinum and chrome operations. Eskom's Komati power station repurposing creates land availability for utility-scale hybrid projects. Middelburg and Witbank host logistics clusters serving Northern Cape EPC mobilization.
South Africa Solar Energy Market Competitive Environment
Premium-margin players sit above commodity-margin players across engineering integration depth and offtake relationship durability. The market structures into three tiers: global EPC integrators with captive project pipelines, regional specialists mining municipal wheeling arbitrage, and hardware traders competing on module cost. Consolidation pressures concentrate among mid-scale developers facing refinancing risk on compressed PPA tenors. Dominant competitive moves include backward integration into captive module supply and strategic partnerships with mining houses for behind-the-meter anchor demand.
Within the integrated EPC tier, ENGIE SA exemplifies premium positioning through global project delivery capabilities. SOLA anchors the regional specialist archetype with concentrated exposure to commercial and industrial wheeling frameworks. Canadian Solar Inc. occupies the scale-driven commodity position, feeding volume into distributed generation channels through cost-competitive crystalline silicon supply.
| Leading Market Players |
|---|
| ENGIE SA |
| SOLA |
| ARTsolar Pty Ltd |
| JinkoSolar Holding Co. Ltd. |
| Renenergy Ltd |
| Canadian Solar Inc. |
| Scatec |
| Juwi Renewable Energies (Pty) Ltd |
| Enel Spa |
| Others |
Value Chain & Pricing Dynamics
Mining house procurement teams dominate South African solar demand, locking in long-term power purchase agreements that anchor value-based pricing around energy security outcomes rather than hardware commoditization. This buyer concentration forces suppliers to bundle uptime guarantees and wheeling facilitation into project economics, compressing pure equipment margins while elevating integrated service premiums.
Pricing Analysis
Value-based pricing tied to load-shedding avoidance anchors commercial and industrial procurement, with mining houses paying premiums for guaranteed baseload continuity. Price differentiation rests on NERSA certification tier and after-sales service bundling, with grid-code-compliant inverters commanding hardware premiums. Cost compression in crystalline silicon modules is intensifying because Chinese import competition and SACU tariff volatility squeeze EPC contractor margins. Residential segments exhibit highest price sensitivity, while industrial offtakers prioritize reliability over unit economics.
Supply Chain Analysis
Warehouse-distribution layers concentrate around Durban port infrastructure and Johannesburg logistics corridors, creating hub-and-spoke patterns for inverter and battery component inland movement. Module supply draws from China, Vietnam, and domestic Atlantis SEZ assembly lines. Polysilicon, lithium carbonate, and galvanized steel anchor raw material dependencies. Single-source vulnerability in lithium-ion cell supply creates structural risk. Distribution runs through EPC contractor-controlled project sites with limited third-party wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's solar market operates as a cost-of-compliance story where NERSA's 14-month inverter certification backlog constructs a regulatory moat favoring incumbents with established testing relationships and dedicated regulatory affairs capacity.
For Market Incumbents: Deploy captive module supply agreements to buffer SACU tariff volatility and secure crystalline silicon volume commitments against Chinese import competition. Deepen municipal wheeling partnerships in Johannesburg and eThekwini to lock in commercial and industrial pipeline visibility before smaller metros operationalize connection frameworks. Threat substitution from containerized battery modularization demands accelerated EPC labor training programs to maintain commissioning speed advantages. For New Entrants and Emerging Players: Bifacial module technology paired with agrivoltaic land-use models offers a technology-first wedge into Northern Cape vineyard and livestock operations seeking dual-revenue streams. Target municipal wheeling pilot programs in secondary metros with untested processes, where regulatory overhead lags Johannesburg but irradiance economics remain compelling. Go-to-market positioning as hybrid system specialists captures energy security premiums from manufacturing clients facing intensifying load-shedding frequency. For Investors and Strategic Acquirers: The window for entry favors EPC contractors with operational wheeling frameworks and mining house relationships that survived compressed PPA tenor restructuring. Long-term viability hinges on exposure to behind-the-meter industrial demand rather than utility-scale auction dependency. Acquisition targets should demonstrate NERSA certification track records and high-voltage substation commissioning capabilities. Signal to watch: Eskom transmission backlog resolution timelines and their impact on commercial operation date certainty for grid-tied projects.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Module Assembly | Atlantis SEZ captive production shields EPC margins from SACU tariff volatility on Chinese imports. |
| Municipal Wheeling Partnership | Johannesburg pilot program access unlocks commercial and industrial revenue streams beyond pure export. |
| Hybrid System Certification Investment | NERSA grid-code pre-approval compresses project development timelines for mining house procurement cycles. |
| Agrivoltaic Land Lease Structure | Northern Cape dual-use arrangements optimize land productivity while securing long-term site control. |
| EPC Labor Training Program | High-voltage substation commissioning capacity addresses skilled engineer scarcity commanding wage premiums. |
Study Parameters
Document review covered EIA electricity statistics, IEA renewable energy reports, NERSA licensing registers, and Eskom transmission planning disclosures, complemented by interviews with IPP project developers, EPC contractors, mining house energy procurement officers, and municipal distribution planners. Secondary validation drew from REIPPPP auction documentation, SABS certification databases, and customs import records. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated for consistency.
Historical capacity installation patterns were cross-referenced against panel input from industry stakeholders to anchor growth trajectory assumptions across the analysis window. Segmentation modeling incorporated technology type, end-user vertical, system architecture, and provincial regulatory framework dimensions. CAGRs were derived from slope analysis of year-over-year deployment trends adjusted for transmission infrastructure readiness constraints. Forecast inputs included Eskom load-shedding severity indices and municipal wheeling liberalization schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REIPPPP auction frequency or prolonged transmission expansion delays. Outputs reflect documented assumptions around irradiance economics, tariff structures, and regulatory timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Solar Farm Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Solar EPC Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Global Green Energy Market