
 Jack-Up Rigs Market | 2026-2036
Jack-Up Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Jack-Up Rigs Market Analysis
Modular jack-up packages bundled with integrated well-intervention stacks is repositioning contractor procurement economics. Noble Corporation leverages its high-specification fleet to anchor premium day-rate positions in harsh-environment markets. Borr Drilling competes through standardized newbuild designs that sustain capital efficiency across multiple water depths. Shelf Drilling Ltd. specializes in legacy asset refurbishment, extending operational life for marginal field developments.
A jack-up rig is a mobile offshore drilling platform with retractable legs that penetrate the seabed to elevate the hull above wave action, typically operating in water depths up to 400 feet with cantilever systems supporting drilling loads exceeding one million pounds. Its primary purpose is to provide a stable, cost-effective drilling and workover platform for shallow to medium-depth offshore hydrocarbon fields. Independent leg designs dominate the active fleet due to superior soil penetration adaptability across varying seabed conditions, while high-specification units command the strongest margin pools as operators prioritize harsh-environment capability and simultaneous operations. The workover application segment shows structural momentum as brownfield asset management intensifies across mature offshore provinces.
The American Bureau of Shipping and DNV classification societies enforce hull structural integrity and station-keeping standards that shape fleet renewal timelines and retirement decisions. The EPA and IMO MARPOL Annex VI frameworks regulate engine emissions and ballast water treatment, forcing engine room retrofits that filter through to contractor capital allocation. Stakeholders must monitor regulatory compliance cost trajectories against day-rate recovery potential as the fleet bifurcates between specification tiers.
Market Dynamics
IMO MARPOL Annex VI carbon intensity regulations are forcing simultaneous engine retrofits and hull upgrades across the contracted fleet, compressing contractor cash flow cycles while operators demand higher specification assets for harsh-environment deployment.
Growth Catalysts
- Brownfield workover intensity:Mature offshore provinces in the Middle East and North Sea require extensive well intervention, driving demand for cantilever-equipped jack-up units capable of simultaneous drilling and production operations.
- IMO 2023 carbon intensity indicators:Compliance deadlines for existing vessels accelerate fleet renewal decisions, favoring modern high-specification rigs with hybrid power systems and optimized hull designs.
- Standardized modular packages:Integrated well-intervention stacks bundled with drilling equipment reduce mobilization time and enable faster field development cycles in marginal basin economics.
Market Restraints
- Specialized steel plate scarcity:High-yield hull-grade steel production concentrates in South Korean and Japanese mills, creating input cost volatility and extending newbuild delivery timelines.
- Leg penetration limitations:Independent leg designs face technical constraints in carbonate seabed formations prevalent in the Eastern Mediterranean and Red Sea regions.
- Classification society backlog:American Bureau of Shipping and DNV hull recertification queues delay return-to-service timelines for refurbished legacy assets.
Strategic Opportunities
- Offshore wind turbine installation:Jack-up units with modified cantilever systems are capturing demand from floating offshore wind developers in the North Sea and Baltic Sea markets.
- Middle East long-term programs:Saudi Aramco and ADNOC sustained drilling commitments create predictable utilization visibility for contractors with regional presence.
- Hybrid-electric retrofits:Battery-hybrid power systems combined with shore power connectivity enable emissions reduction compliance while opening premium day-rate tiers.
Industry Challenges
- Marine warranty surveyor shortages:Qualified specialists for jack-up leg penetration analysis and preload procedures face capacity constraints, extending site assessment timelines.
- Legacy control system integration:Digital automation upgrades on 1990s-era rigs require bespoke engineering to interface with original programmable logic controller architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jack-Up Rigs Market |
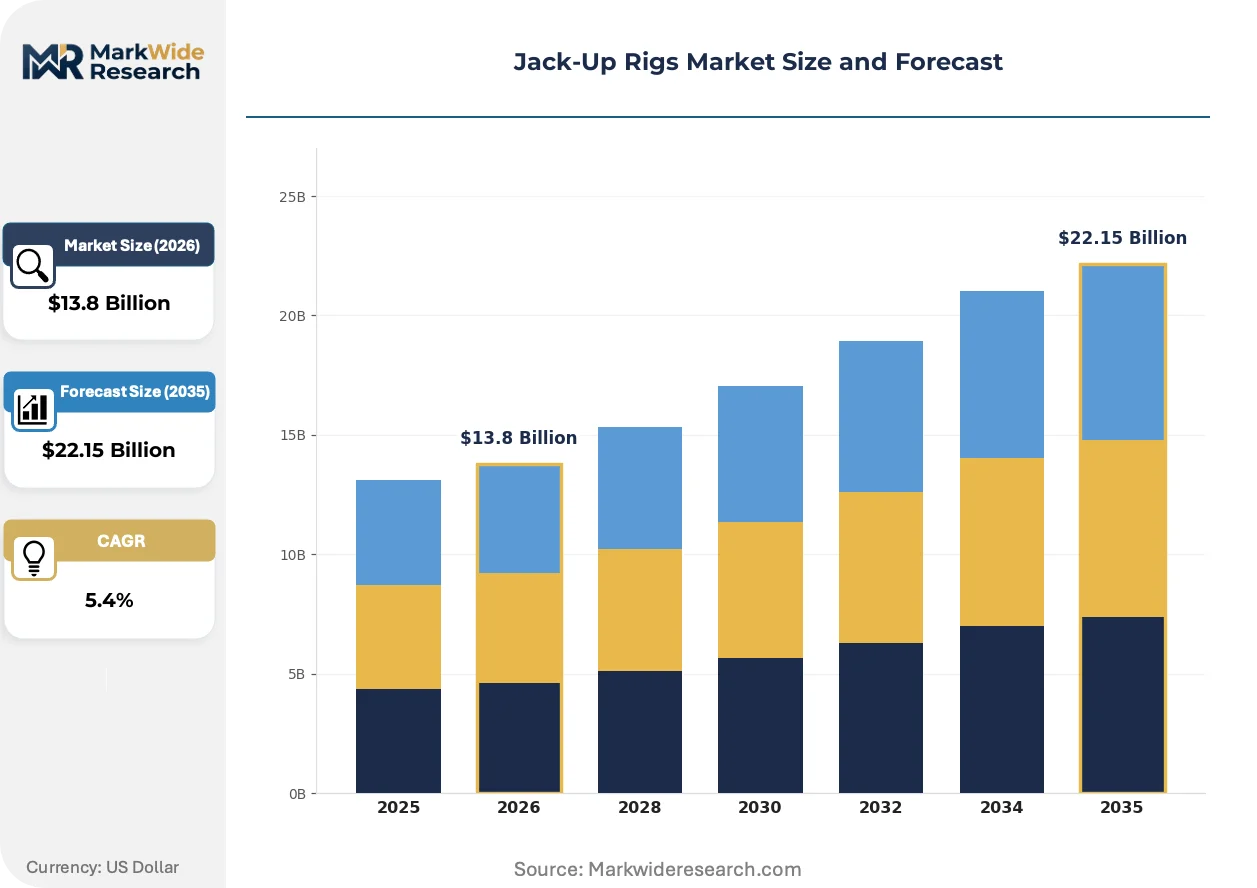
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Independent Legs, Multi-Purpose, Self-Elevating, High-Specification Applications: Exploration, Development, Production, Workover End User: Oil & Gas Companies, Offshore Contractors, Integrated Operators, Service Providers Installation: Onshore, Nearshore, Offshore, Dismantled |
| Companies Covered | Noble Corporation, China Oilfield Services Limited, Transocean Ltd., Borr Drilling, ENSCO Inc., Valaris, Shelf Drilling Ltd., Maersk Drilling AS, Seadrill Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jack-Up Rigs Market Emerging Trajectories
Digital twin technology and predictive maintenance systems are redefining asset utilization models, while regulatory emissions frameworks compress the operational window for legacy diesel-mechanical power plants.
Variable frequency drive systems with active harmonic filtering are overtaking traditional direct-on-line motor starting configurations in newbuild jack-up designs. Offshore contractors in the North Sea and harsh-environment North Atlantic markets are specifying these systems for dynamic positioning support vessels and crane operations. The technology is overtaking fixed-speed alternatives by enabling fuel consumption optimization across varying load profiles while reducing mechanical wear on critical rotating equipment.
EPA Tier 4 and IMO Tier III emission standards for non-road mobile machinery are mandating selective catalytic reduction and exhaust gas recirculation systems on auxiliary generators. Engine room retrofit programs absorb 12-18 month drydock periods, removing capacity from active drilling markets. Contractors with early-mover compliance positions in the US Gulf of Mexico and Norwegian Continental Shelf are capturing preference from operators with net-zero commitments.
Integrated service contracts bundling drilling, completion, and intervention scope are displacing standalone day-rate arrangements in mature basin procurement. National oil companies in Saudi Arabia and the UAE are consolidating vendor relationships to reduce interface risk and improve capital efficiency. This concentration is most visible in the Middle East, where long-term framework agreements now cover 60-70% of contracted jack-up demand.
Jack-Up Rigs Market Segmentation
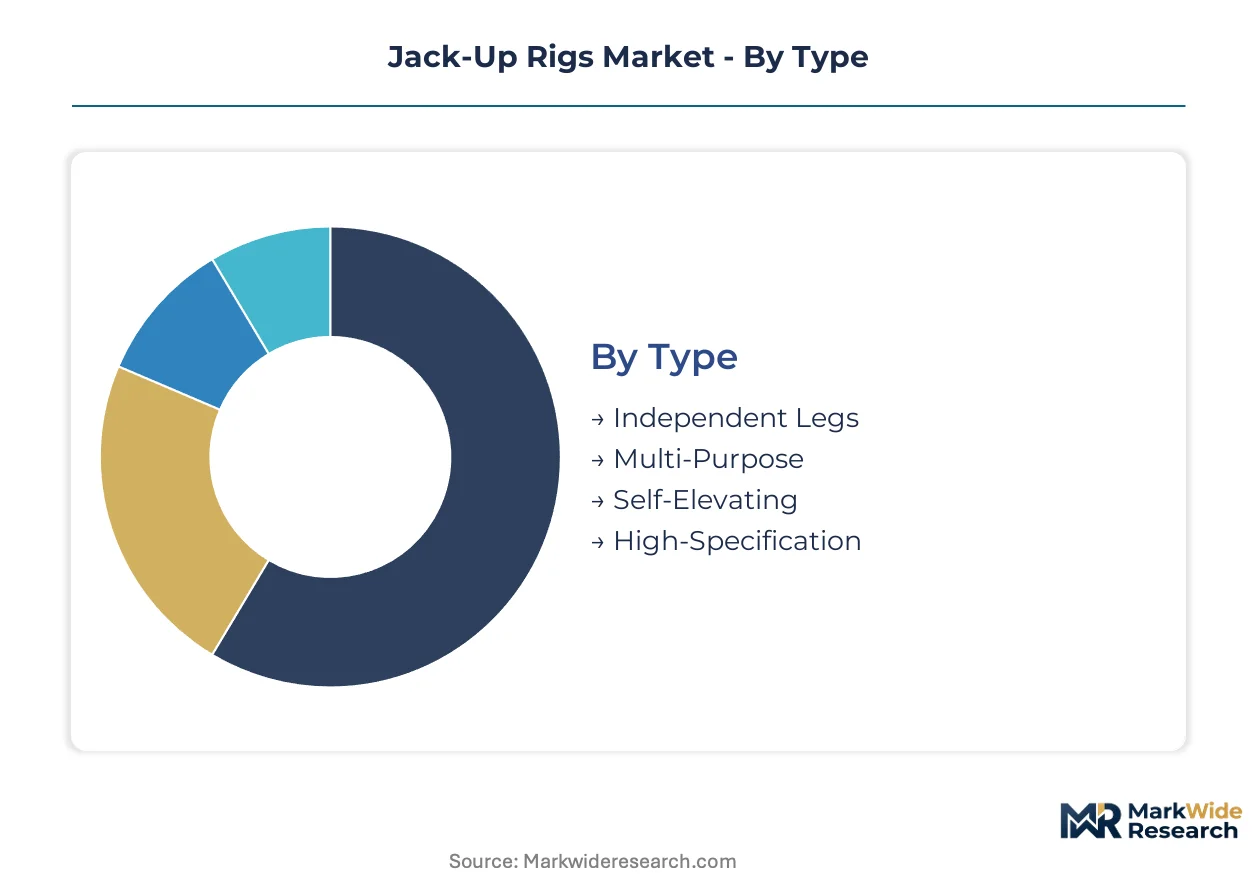
Jack-up rig procurement decisions hinge on water depth capability, soil conditions, and operational intensity. Fleet segmentation reveals how contractor economics bifurcate between premium high-specification units and refurbished legacy assets serving marginal fields.
Type:
Supply concentration for advanced leg systems and cantilever packages centers on South Korean and Singaporean fabrication yards.
- Independent Legs:Retractable leg designs penetrate varying seabed compositions through individual jacking systems. Demand concentrates in the Middle East, where carbonate formations and unconsolidated sediments require adaptive penetration capability for sustained drilling programs.
- High-Specification:Units rated for harsh-environment deployment feature enhanced station-keeping and simultaneous operations capability. North Sea and Norwegian Continental Shelf operators specify these assets for winterized operations, paying premium day rates for reliability in extreme wave states.
- Multi-Purpose:Configurable deck layouts accommodate drilling, completion, and intervention modules.
- Self-Elevating:Mat-supported designs suit uniform soft-bottom conditions in Gulf of Mexico shelf operations.
Independent Legs absorbs the bulk of installed capacity; High-Specification is expanding most quickly.
Applications:
Operational intensity varies sharply across the field lifecycle, with late-stage activities commanding different rig configurations than greenfield exploration.
- Workover:Well intervention and recompletion operations demand cantilever-equipped units capable of accessing production platforms without disrupting ongoing extraction. Mature North Sea and Middle East brownfields drive fleet allocation toward workover-capable assets as reservoir management priorities shift.
- Development:Batch drilling programs for field installation require high-utilization, long-stay deployments. Saudi Aramco and ADNOC framework agreements anchor development drilling demand with multi-year contract visibility.
- Exploration:Wildcat drilling in frontier basins favors rapidly mobilizing standard-specification units.
- Production:Extended well testing and early production systems integration occupy a niche segment.
Development commands the largest share of contracted days; Workover is gaining share fastest.
End User:
Procurement authority determines contract structure complexity and risk allocation between operators and drilling contractors.
- Offshore Contractors:Noble Corporation, Borr Drilling, and Shelf Drilling Ltd. own and operate the majority of marketed jack-up capacity. These entities bear capital deployment risk while capturing day-rate spreads through operational efficiency and fleet standardization.
- Oil & Gas Companies:National oil companies and international majors specify technical requirements and charter rigs on term contracts. Saudi Aramco and ADNOC sustain the largest contracted fleets through direct operator procurement.
- Integrated Operators:Vertically balanced majors internalize drilling decisions within asset development teams.
- Service Providers:Specialized well intervention companies charter rigs for plug-and-abandonment campaigns.
Offshore Contractors hold the dominant fleet ownership position; Oil & Gas Companies are tightening direct procurement control.
Installation:
Water depth and regulatory jurisdiction dictate hull design certification and mobilization logistics.
- Offshore:Open-water deployment beyond territorial limits requires full classification society certification and flag-state compliance. Units operating in EPA-regulated US waters and IMO-governed international zones face overlapping emissions and safety mandates.
- Nearshore:Coastal and estuarine operations in water depths below 200 feet suit lower-specification mat-supported designs. Gulf of Mexico and Southeast Asian nearshore fields concentrate this segment.
- Onshore:Yard-based maintenance and pre-commissioning activities occupy a small support segment.
- Dismantled:End-of-life rigs await recycling or conversion at specialist facilities.
Offshore absorbs the bulk of active fleet utilization; Nearshore is climbing the fastest as marginal field development intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jack-up rig fabrication concentrates in South Korean and Singaporean shipyards, while operational demand clusters around Middle Eastern and North Sea hydrocarbon provinces. This production-consumption divide shapes fleet deployment patterns and day-rate differentials across basins.
Saudi Arabia
Saudi Aramco sustains the world's largest contracted jack-up fleet through multi-year development drilling programs in the Arabian Gulf. The country's national oil company enforces stringent local content requirements under the IKTVA program, mandating domestic fabrication partnerships for hull components. Dammam's King Salman Energy Park anchors rig maintenance and module integration activities serving offshore fields.
United States
Gulf of Mexico shelf operators deploy mat-supported jack-ups for shallow-water workover campaigns in water depths below 200 feet. EPA Tier 4 emission standards and Bureau of Safety and Environmental Enforcement drilling regulations drive engine retrofit investments across the contracted fleet. Houston's Energy Corridor concentrates drilling contractor headquarters and marine warranty surveyor capacity for pre-load analysis.
Norway
North Sea harsh-environment operations demand winterized high-specification units rated for extreme wave states and simultaneous operations. The Norwegian Maritime Authority enforces strict station-keeping and hull integrity standards that accelerate legacy asset retirement timelines. Stavanger's offshore engineering cluster supports classification society certification and hybrid-electric retrofit engineering for regional contractors.
China
State-owned oilfield services operators expand domestic jack-up capacity for South China Sea development drilling in contested waters. The Ministry of Industry and Information Technology oversees shipyard certification under GB standards for hull structural steel fabrication. Shanghai and Dalian shipyards concentrate newbuild construction for both domestic deployment and export markets.
United Arab Emirates
ADNOC's long-term framework agreements create predictable utilization visibility for contractors operating in shallow Arabian Gulf fields. The country's national oil company mandates IMO MARPOL Annex VI compliance for all chartered assets, favoring modern rigs with selective catalytic reduction systems. Dubai Maritime City supports rig refurbishment and classification society survey activities for regional fleet renewal.
Jack-Up Rigs Market Vendor Landscape
The competitive structure tilts toward asset-heavy offshore contractors bearing capital deployment risk against day-rate volatility. Fleet ownership concentrates among publicly traded drilling companies with access to secured debt markets for newbuild financing. Three archetypes dominate: high-specification harsh-environment specialists, standardized fleet operators optimizing capital efficiency, and legacy asset refurbishers serving marginal field economics. Competitive moves center on portfolio diversification into offshore wind installation and strategic partnerships with national oil companies for long-term utilization visibility.
Among premium-tier contractors, Noble Corporation occupies a position exemplifying high-specification harsh-environment capability. Borr Drilling represents the standardized newbuild archetype with designs targeting capital efficiency across multiple water depths. Shelf Drilling Ltd. anchors the legacy asset refurbishment segment, extending operational life for brownfield workover demand.
| Leading Market Players |
|---|
| Noble Corporation |
| China Oilfield Services Limited |
| Transocean Ltd. |
| Borr Drilling |
| ENSCO Inc. |
| Valaris |
| Shelf Drilling Ltd. |
| Maersk Drilling AS |
| Seadrill Limited |
| Others |
Supply Flow & Price Mechanics
Hybrid-electric propulsion retrofits and high-yield hull steel sourcing are simultaneously compressing contractor capital cycles and concentrating fabrication leverage among South Korean and Singaporean yards. These dual pressures reshape how day-rate premiums flow through to specification-tier differentiation and input cost pass-through mechanics.
Pricing Analysis
Margin tightening in the legacy fleet tier reflects IMO MARPOL Annex VI compliance deadlines forcing simultaneous engine room and hull upgrades. Contract-based long-term offtake structures dominate Middle East national oil company procurement, with price differentiation hinging on harsh-environment certification grade and simultaneous operations capability. Cost-down pressure on standard-specification units accelerates because carbon intensity regulations compress operational windows for diesel-mechanical power plants. National oil companies with net-zero commitments show least price sensitivity, while independent operators in marginal Gulf of Mexico shelf fields exhibit highest.
Supply Chain Analysis
Heavy-lift vessel freight costs from South Korean and Singaporean fabrication yards to Middle East and North Sea deployment sites absorb significant mobilization budgets. Geographic supply concentration centers on South Korea, Singapore, and China for jack-up leg systems, cantilever packages, and hull modules. Raw material dependencies draw from Japanese and South Korean mills for high-yield hull-grade steel plate, combined with German and Norwegian suppliers for jacking system hydraulics. Single-source vulnerability concentrates in specialized marine warranty surveyor capacity for leg penetration analysis. Distribution runs through offshore contractor fleet ownership with term charter arrangements to national oil companies and international majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over high-yield steel sourcing and hybrid-electric retrofit engineering determines margin capture against regulatory compliance timelines.
For Market Incumbents: Deploy captive maintenance yard capacity in the Middle East to secure IKTVA and local content compliance positions against emerging Chinese state-owned competitors. Anchor long-term framework agreements with Saudi Aramco and ADNOC before hybrid-electric retrofit mandates harden specification requirements. Prioritize classification society pre-certification for harsh-environment winterization to defend premium day-rate tiers. For New Entrants and Emerging Players: Battery-hybrid power system integration offers the most penetrable wedge against legacy diesel-mechanical fleets facing IMO carbon intensity deadlines. Target offshore wind turbine installation conversions in the North Sea and Baltic Sea where modified cantilever jack-ups face limited specialized competition. Pursue joint engineering partnerships with established marine warranty surveyors to bypass preload analysis capacity constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in national oil company portfolio rationalizations and distressed legacy asset conversions. Long-term viability favors contractors with demonstrated harsh-environment operational records and early IMO compliance positions. Monitor classification society hull recertification backlogs as an inflection indicator for available fleet supply tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Retrofit Program | Battery-hybrid power systems enable IMO MARPOL Annex VI compliance while opening premium day-rate tiers with net-zero committed operators. |
| Offshore Wind Conversion | Modified cantilever jack-ups capture demand from floating wind developers in North Sea and Baltic Sea installation markets. |
| Long-Term Framework Agreement | Multi-year Saudi Aramco and ADNOC contracts provide utilization visibility against day-rate volatility in spot markets. |
| Captive Yard Capacity Buildout | King Salman Energy Park and Dubai Maritime City maintenance facilities secure IKTVA compliance and reduce mobilization costs. |
| Classification Society Pre-Certification | Early ABS and DNV hull recertification positions avoid queue delays and accelerate return-to-service timelines. |
Methodological Framework
Multi-period observation of fleet utilization rates, day-rate movements, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with offshore drilling contractor fleet managers, national oil company procurement officers, marine warranty surveyors, and classification society surveyors. Secondary validation drew from American Bureau of Shipping and DNV classification records, IMO MARPOL Annex VI compliance databases, SEC filings from publicly traded drilling contractors, and customs data for high-yield hull steel trade flows. Bottom-up rig-by-rig supply modeling and top-down hydrocarbon demand projections provided triangulation.
The input-output matrix framework connected water depth capability, soil condition adaptability, and operational intensity specifications to contracted day-rate realizations across the projection horizon. Segmentation dimensions modeled include leg design type, specification tier, application lifecycle stage, end-user procurement authority, and installation water depth regime. CAGRs were derived from regression analysis against historical fleet deployment patterns and forward regulatory compliance deadlines, incorporating jack-up newbuild delivery schedules and legacy asset retirement curves.
Several conditions sit outside the modeled scope, including unannounced national oil company drilling program cancellations, abrupt classification society rule changes, and geopolitical disruptions to South Korean or Singaporean fabrication yard operations. Forecasts reflect documented assumptions about IMO enforcement consistency and carbon credit valuation trajectories. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market