
 Modular Sub-Station Market | 2026-2036
Modular Sub-Station Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Sub-Station Market Foresight
Aftermarket service revenue is rewriting profit expectations across the modular substation value chain. Siemens AG leverages its digital service platform to capture recurring diagnostics contracts. ABB Ltd anchors its position through predictive maintenance software bundled with hardware shipments. Eaton Corporation Plc differentiates by extending warranty coverage into operational lifecycle management.
A modular substation is a pre-assembled, factory-tested power distribution unit housed in a transportable enclosure, typically rated from low voltage through extra high voltage classes, designed for rapid site deployment with minimal civil works. The primary purpose is to deliver reliable grid connectivity for utilities, industrial facilities, and remote generation assets where conventional build times prove prohibitive. Containerized sub-stations occupy the premium tier due to plug-and-play standardization and reduced commissioning risk. Mobile sub-stations serve emergency restoration and seasonal peak loads, while compact sub-stations penetrate dense urban corridors where land constraints dominate site selection.
Grid operators in Germany face KBA transport certification and EU F-Gas Regulation compliance for insulating medium selection. The US Federal Energy Regulatory Commission and state public utility commissions mandate reliability standards that favor factory-tested modular architectures over field-built alternatives. India's Central Electricity Authority enforces technical standards for voltage class and fault tolerance that shape local procurement specifications. Stakeholders must monitor evolving SF6 phase-out timelines and corresponding dielectric medium transitions to preserve product qualification across key jurisdictions.
Market Dynamics
The EU F-Gas Regulation is compressing dielectric medium transitions across the modular substation supply chain, forcing manufacturers to requalify gas-insulated designs ahead of sulfur hexafluoride phase-out deadlines.
Growth Catalysts
- Rural electrification mandates:India's Central Electricity Authority technical standards accelerate procurement for renewable energy parks and village grid extensions, compressing deployment timelines from years to months.
- SF6 restrictions:The EU F-Gas Regulation creates immediate pull for gas-insulated alternatives with lower global warming potential across European transmission networks.
- Containerized architecture:Factory-tested, plug-and-play standardization reduces commissioning risk for utilities facing land constraints and skilled labor shortages.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings compress margin visibility for enclosure and busbar fabricators, particularly in Asian supply chains.
- Specialized transformer core concentration:Grain-oriented electrical steel supply concentrates among a handful of integrated mills, creating bottleneck risk for high-efficiency ratings.
- Transport dimensional limits:German KBA certification and analogous road regulations constrain maximum unit size, fragmenting extra-high-voltage designs into multiple containers.
Strategic Opportunities
- Offshore wind integration:Floating platform substations require marine-rated containerized units with corrosion-resistant enclosures, opening premium specification tiers.
- Digital twin bundling:Predictive maintenance software layered onto hardware shipments captures recurring revenue streams from reliability-critical industrial buyers.
- Data center power densification:Hyperscale facilities in Northern Virginia and Frankfurt seek rapid-deploy medium-voltage infrastructure with 12-week delivery guarantees.
Industry Challenges
- Dielectric medium requalification:Transitioning from SF6 to fluoronitrile or vacuum interrupter technologies demands extended type-testing cycles with notified bodies.
- High-voltage test bay scarcity:Factory acceptance testing for extra-high-voltage classes faces capacity constraints at independent laboratories, stretching lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Sub-Station Market |
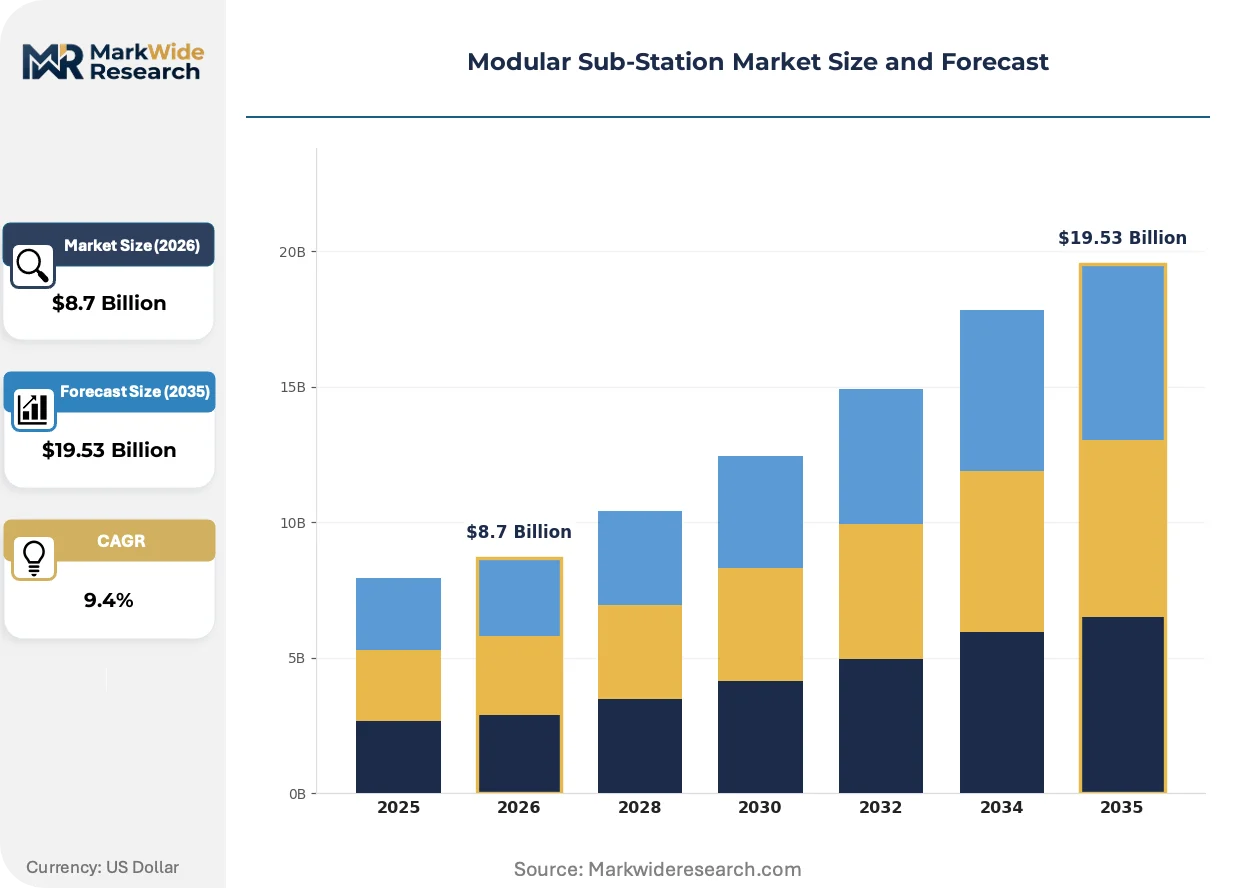
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containerized Sub-Station, Mobile Sub-Station, Compact Sub-Station, Outdoor Sub-Station Installation: Onshore, Offshore, Urban, Rural Power Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage End User: Utilities, Manufacturing, Renewable Energy, Mining |
| Companies Covered | ABB Ltd, Siemens AG, Eaton Corporation Plc, General Electric, Schneider Electric, CG Power and Industrial Solutions Ltd, Bharat Heavy Electricals Limited, SPX Transformer Solutions, Skema S.P.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Sub-Station Market Shifts & Advancements
Insulating medium chemistry and digital instrumentation layers are reshaping modular substation architectures, compressing commissioning windows while elevating lifecycle analytics capabilities.
Gas-insulated switchgear is migrating from sulfur hexafluoride to fluoronitrile blends and vacuum interrupter technologies as primary dielectric mediums. European transmission operators and renewable developers are adopting these alternatives at accelerating pace to preempt regulatory non-compliance. This migration from legacy gas chemistry is compressing product development cycles and forcing parallel qualification tracks across multiple voltage classes.
The EU F-Gas Regulation mandates progressive sulfur hexafluoride phase-down with reporting thresholds tightening through 2030. Manufacturers must redesign gas-insulated compartments, seals, and monitoring systems to accommodate lower-global-warming-potential alternatives. Containerized substations destined for German and French grids face the most acute redesign pressure, with KBA transport certification now contingent on updated material safety documentation.
Utility buyers are unbundling hardware procurement from long-term service contracts, creating discrete purchasing events for diagnostics and predictive maintenance. Equipment vendors respond with platform-based subscription offerings that displace traditional warranty extensions. This pattern concentrates in Southeast Asian markets where state utilities face budget fragmentation across fiscal years.
Modular Sub-Station Market Segmentation
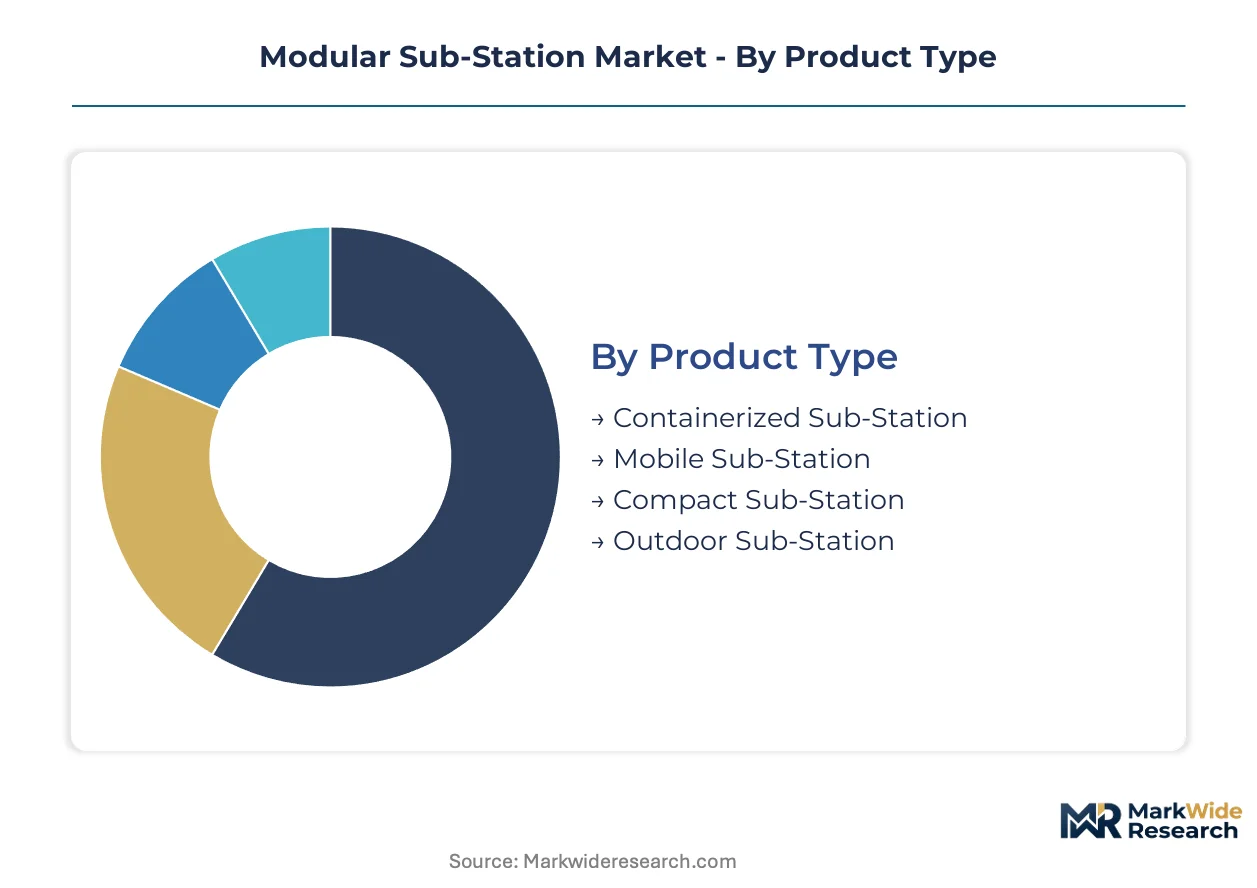
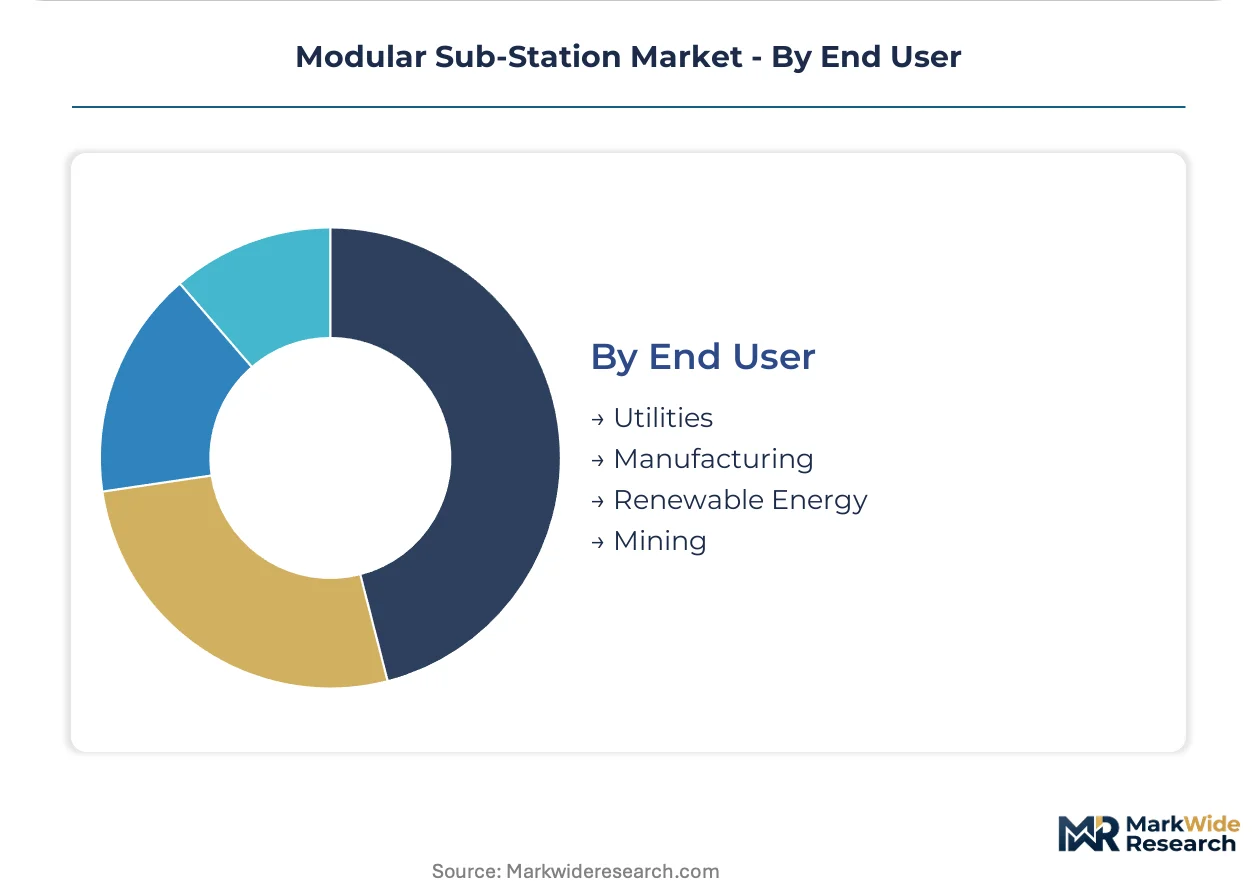
Modular substation procurement patterns diverge sharply across deployment contexts, with transport certification limits and dielectric medium regulations fragmenting product specifications. Segment boundaries reflect tension between factory standardization and site-specific electrical requirements.
Product Type:
Cost tier stratification separates premium containerized architectures from mobile emergency units and compact urban installations.
- Containerized Sub-Station:Fully enclosed, factory-tested units with integrated switchgear and transformer assemblies housed in ISO-standard shipping containers. Demand concentrates in German transmission networks where KBA transport certification and EU F-Gas Regulation compliance create qualification barriers for non-standardized suppliers.
- Mobile Sub-Station:Trailer-mounted or skid-based configurations designed for emergency restoration and seasonal peak shaving. Procurement accelerates across Indian state utilities facing monsoon-induced grid disruptions and cyclone corridor exposure.
- Compact Sub-Station:Space-optimized designs for dense urban corridors with minimal footprint requirements.
- Outdoor Sub-Station:Open-air configurations for industrial sites with available land and lower environmental protection needs.
Containerized Sub-Station holds installed capacity. Mobile Sub-Station is rotating up the share rankings.
Installation:
Application environment dictates enclosure specifications, corrosion resistance, and civil works intensity.
- Onshore:Standard ground-mounted deployments across industrial zones and utility yards with conventional foundation requirements. Manufacturing clusters in Northern Virginia and Frankfurt generate concentrated demand for rapid-deploy medium-voltage infrastructure with 12-week delivery guarantees.
- Offshore:Marine-rated containerized units with salt-resistant coatings and platform-integrated anchoring systems. Floating wind developments in the North Sea and Baltic Sea drive premium specification tiers for corrosion-resistant switchgear enclosures.
- Urban:Underground or pad-mounted configurations for dense metropolitan corridors with severe land constraints.
- Rural:Simplified civil works for village grid extensions and agricultural electrification programs.
Onshore dominates current deployment volumes. Offshore is gaining share fastest among specification tiers.
Power Rating:
Voltage class determines dielectric medium selection, transport dimensional limits, and testing bay requirements.
- Medium Voltage:1kV to 52kV ratings serving distribution networks and industrial interconnections. Renewable energy parks in India and Southeast Asia compress procurement timelines from years to months for rapid-grid-connection assets.
- Extra High Voltage:345kV and above classes requiring fragmented multi-container transport due to German KBA dimensional constraints and analogous road regulations.
- Low Voltage:Sub-1kV configurations for localized distribution and small-scale commercial applications.
- High Voltage:72.5kV to 245kV ratings for sub-transmission and bulk power transfer.
Medium Voltage holds installed capacity. Extra High Voltage is climbing the fastest among voltage tiers.
End User:
Customer type shapes procurement structure, service contract bundling, and lifecycle management expectations.
- Utilities:State and private grid operators with standardized technical specifications and fragmented budget cycles. Southeast Asian state utilities increasingly unbundle hardware from long-term diagnostics contracts, creating discrete purchasing events.
- Renewable Energy:Wind and solar developers requiring rapid-deployment infrastructure for remote generation assets. EU F-Gas Regulation compliance pressures accelerate adoption of fluoronitrile-based switchgear across European renewable integration projects.
- Manufacturing:Industrial facilities with reliability-critical power requirements and predictive maintenance software demand.
- Mining:Remote extraction operations with mobile substation needs and harsh environmental exposure.
Utilities hold installed capacity. Renewable Energy is expanding most quickly among end-use categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Indian utilities prioritize lowest capital expenditure for rural electrification. German transmission operators absorb premium pricing for KBA-certified containerized units with F-Gas-compliant dielectric mediums.
United States
Data center power densification in Northern Virginia and hyperscale clusters around Dallas-Fort Worth compress delivery timelines to 12-week guarantees. FERC reliability standards favor factory-tested modular architectures over field-built alternatives. Northern Virginia's Loudoun County hosts the densest concentration of rapid-deploy medium-voltage infrastructure procurement.
Germany
Offshore wind integration in the North Sea and Baltic Sea drives marine-rated containerized specifications with corrosion-resistant enclosures. KBA transport certification and EU F-Gas Regulation compliance create dual qualification barriers for insulating medium selection. Hamburg and Bremerhaven anchor the premium-tier fabrication cluster for floating platform substations.
India
Rural electrification programs and renewable energy parks in Rajasthan and Gujarat demand rapid-deployment infrastructure with compressed grid connection timelines. Central Electricity Authority technical standards enforce voltage class and fault tolerance specifications that shape local procurement. Tamil Nadu's wind corridor and Karnataka's solar parks concentrate mobile substation demand for monsoon resilience.
China
Dual carbon goals accelerate grid modernization investments with factory-standardized plug-and-play architectures. MIIT efficiency mandates and GB standards for electrical equipment shape dielectric medium transitions. Yangtze River Delta manufacturing clusters around Shanghai supply containerized enclosures for domestic and Southeast Asian utility buyers.
Southeast Asia
State utilities in Vietnam and Thailand unbundle hardware procurement from long-term diagnostics contracts, creating discrete purchasing events across fragmented fiscal years. Containerized units compress grid expansion timelines where skilled labor shortages constrain conventional construction. Bangkok and Ho Chi Minh City concentrate procurement for urban densification and industrial zone electrification.
Modular Sub-Station Market Competitive Landscape
Capability concentration sits with integrated electrical equipment conglomerates; scale advantage sits with regional transformer specialists and enclosure fabricators. The market structures around three tiers: global technology licensors with digital service platforms, national champions with utility relationships, and specialized container fabricators with transport certification expertise. Dominant competitive moves include strategic partnerships for offshore wind integration and portfolio diversification into predictive maintenance software.
Within the global technology tier, ABB Ltd and Siemens AG exemplify platform-based service bundling. Eaton Corporation Plc occupies a position emphasizing operational lifecycle management. Among Asia-Pacific fabricators, Bharat Heavy Electricals Limited anchors state-utility procurement channels. These named entities represent archetype positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Eaton Corporation Plc |
| General Electric |
| Schneider Electric |
| CG Power and Industrial Solutions Ltd |
| Bharat Heavy Electricals Limited |
| SPX Transformer Solutions |
| Skema S.P.A |
Supply & Pricing Matrix
Grain-oriented electrical steel mills in Japan and South Korea anchor transformer core supply, concentrating margin capture with integrated producers while enclosure fabricators in China and India compete on volume scale. This upstream concentration shifts value downstream toward digital service platforms and transport-certified system integrators who bundle hardware with recurring diagnostics contracts.
Pricing Analysis
Aftermarket service revenue tiers now drive lifetime value more than unit sales, with predictive maintenance subscriptions and extended warranty coverage capturing recurring income streams. Three-tier pricing structure across premium KBA-certified containerized units, standard onshore configurations, and economy-grade mobile substations reflects certification grade and geographic delivery cost differentiation. Pricing pressure stems from copper and aluminum price volatility compressing margin visibility for Asian supply chain participants. Indian state utilities exhibit highest price sensitivity for rural electrification programs, while German transmission operators absorb premium pricing for F-Gas-compliant insulating mediums.
Supply Chain Analysis
Export-control regimes on high-grade electrical steel and advanced switchgear components constrain technology flows from Japanese and South Korean mills into certain end-markets. Manufacturing concentrates in China for enclosure fabrication, Germany for transport-certified system integration, and India for mobile substation assembly serving domestic and Southeast Asian demand. Raw material dependencies center on grain-oriented electrical steel, copper busbar stock, and fluoronitrile dielectric mediums. Single-source vulnerability runs through specialized transformer core suppliers. Distribution runs through direct utility procurement channels and EPC contractor bundling for industrial and renewable energy projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of high-voltage test bay capacity and EU F-Gas Regulation requalification expertise is concentrating competitive advantage among notified-body-aligned manufacturers with parallel certification tracks across multiple voltage classes.
For Market Incumbents: Pre-empt dielectric medium transition bottlenecks by accelerating fluoronitrile and vacuum interrupter qualification ahead of sulfur hexafluoride phase-out deadlines. Secure captive capacity at independent high-voltage test laboratories to compress factory acceptance testing lead times. Vertical integration into grain-oriented electrical steel sourcing mitigates transformer core supply concentration risk from Japanese and South Korean mill dependency. For New Entrants and Emerging Players: Southeast Asian state utilities present underpenetrated demand for unbundled diagnostics and predictive maintenance software separate from hardware procurement. Vietnam and Thailand's fragmented fiscal year budgeting creates discrete purchasing event opportunities for subscription-based service platforms. Target containerized substation demand from floating offshore wind developers in the North Sea and Baltic Sea seeking marine-rated corrosion-resistant specifications. For Investors and Strategic Acquirers: Capital is best deployed toward regional transformer specialists with transport certification expertise and established utility relationships in high-growth procurement zones. Long-term viability favors fabricators with backward integration into enclosure production and digital service platform capabilities. Watch for inflection signals in EU F-Gas Regulation enforcement intensity and corresponding dielectric medium transition acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Dielectric Medium Requalification | Accelerates fluoronitrile and vacuum interrupter certification ahead of EU F-Gas phase-out deadlines. |
| High-Voltage Test Bay Capacity Expansion | Captures scarce factory acceptance testing resources for extra-high-voltage class modular substations. |
| Digital Twin Platform Development | Bundles predictive maintenance software with hardware shipments for recurring utility revenue streams. |
| Offshore Wind Integration Partnership | Opens premium specification tiers for marine-rated containerized units in North Sea developments. |
| Grain-Oriented Electrical Steel Sourcing | Reduces transformer core supply vulnerability from concentrated Japanese and South Korean mill dependency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of utility procurement databases, FERC and CEA regulatory filings, and customs trade data for electrical equipment imports. Primary interviews engaged utility planning officers, EPC contractor procurement leads, modular substation OEM product managers, and aftermarket service directors. Secondary validation drew from SEC 10-K disclosures, EU F-Gas Regulation implementation reports, and IEA grid modernization datasets. Bottom-up unit shipment estimates triangulate against top-down addressable market sizing across voltage class and installation type segments.
Forecast inputs incorporate utility capital expenditure plans, renewable energy park development pipelines, and data center power densification timelines across the projection horizon. Segmentation modeling spans product type, installation environment, power rating tier, and end-user category with regional regulatory framework overlays. CAGRs derive from regression analysis of historical procurement patterns against projected infrastructure investment cycles. Industry-specific inputs include offshore wind capacity additions and rural electrification program deployment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese enclosure fabricators or accelerated EU F-Gas enforcement would shift outcomes. Material shifts in grain-oriented electrical steel trade flows or high-voltage test bay capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Substation Grounding System Market