
 Wind Turbine Blades Market | 2026-2036
Wind Turbine Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Blades Market Intelligence
Modular blade platforms paired with segmented logistics is restructuring how developers configure turbine supply contracts. Siemens Gamesa Renewable Energy leverages integrated blade-turbine design to capture offshore contracts, while TPI Composites sustains third-party manufacturing scale across multiple OEM programs. LM Wind Power anchors European blade engineering through its Denmark-based technology center, and Vestas Wind Systems controls in-house blade production to protect turbine margin pools.
Wind turbine blades are aerodynamic structures typically fabricated from fiberglass-reinforced epoxy or carbon fiber composites, spanning 40 to 120 meters in length, designed to convert kinetic wind energy into rotational mechanical force for electricity generation. The primary industrial purpose is maximizing energy capture efficiency while withstanding cyclic fatigue loads across 20- to 25-year operational lifespans. Fiberglass dominates current production volumes due to cost efficiency at scale, though carbon fiber is displacing conventional materials in extra-large offshore blades where stiffness-to-weight ratios determine performance. Utilities represent the largest end-user segment by installed capacity, while independent power producers are concentrating procurement in medium and large blade classes for merchant wind projects.
The EU Green Deal and F-Gas Regulation are tightening embodied carbon standards for blade manufacturing across European supply chains, while China's MIIT enforces GB standards on composite material recycling and blade decommissioning protocols. The US EPA coordinates with FAA on turbine height clearances that indirectly constrain maximum blade lengths for onshore installations. Stakeholders must monitor evolving extended producer responsibility frameworks and recycling infrastructure buildout as blade waste volumes accumulate from first-generation wind farms reaching end-of-life.
Market Dynamics
Rotor diameter scaling beyond 220 meters is compressing blade supply chains into a handful of composite manufacturing clusters capable of handling single-piece structures exceeding 120 meters, forcing developers to renegotiate logistics contracts and factory gate arrangements.
Growth Catalysts
- EU Green Deal domestic content mandates:European renewable auctions now require minimum local blade sourcing percentages, redirecting capital toward Iberian and Baltic manufacturing greenfields.
- Carbon fiber stiffness-to-weight gains:Extra-large offshore blade designs exploit advanced composite properties to reduce mass while maintaining aerodynamic performance under cyclic fatigue.
- China's state-backed wind bases:Multi-gigawatt procurement clusters in Inner Mongolia and coastal provinces generate concentrated demand for 90-meter-plus blade classes.
Market Restraints
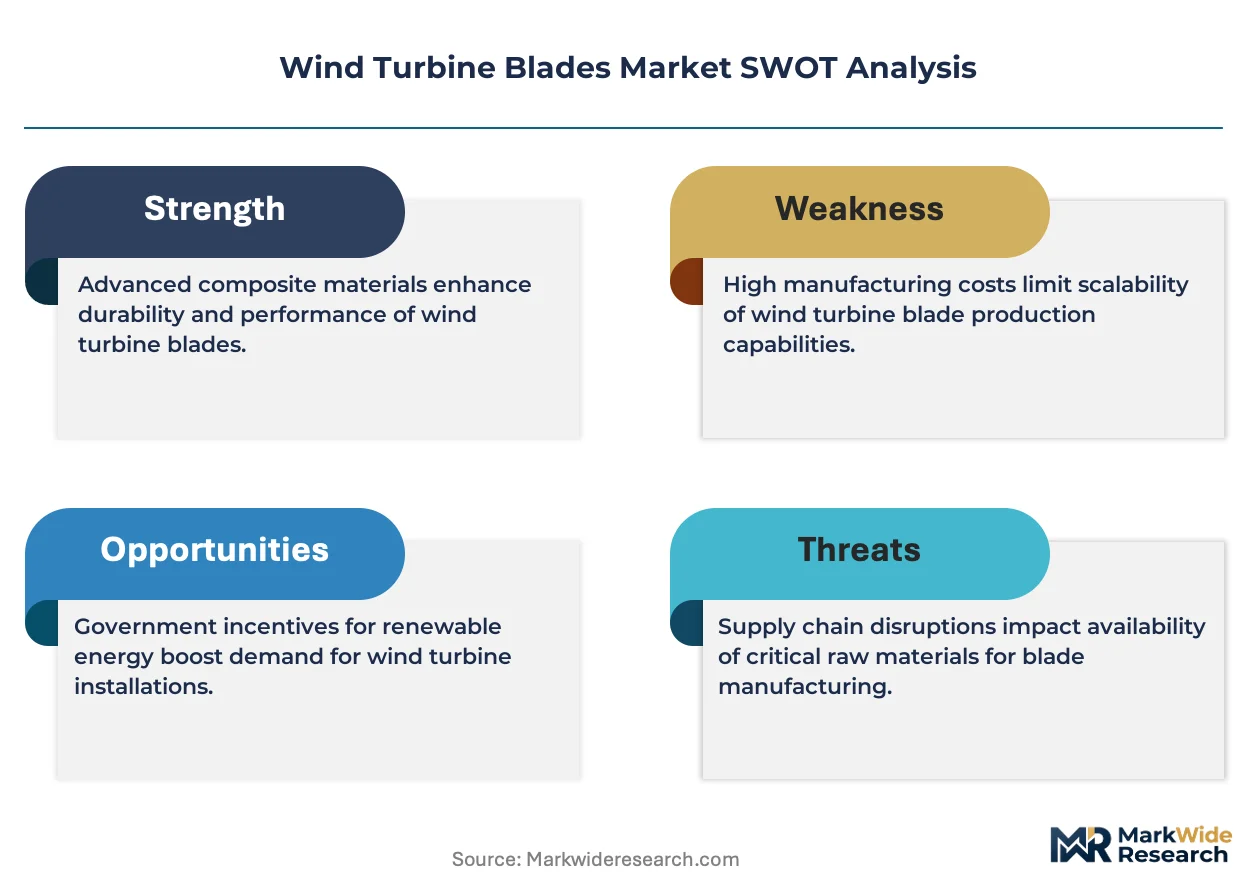
- Epoxy resin price volatility:Petrochemical feedstock fluctuations transmit directly into blade laminate costs, compressing OEM margin pools on fixed-price supply contracts.
- Specialized mold fabrication bottlenecks:Only Danish and Spanish tooling suppliers currently produce mandrels for 115-meter blade platforms, creating single-source vulnerability.
- Onshore FAA height clearances:US aviation restrictions indirectly cap maximum blade lengths for terrestrial installations below offshore-optimized designs.
Strategic Opportunities
- Blade recycling infrastructure gaps:First-generation wind farms in Germany and Denmark reach end-of-life without scaled thermoset composite recovery, opening decommissioning service contracts.
- Modular segmented blade platforms:Bolted joint designs enable road-transportable sections that unlock inland wind sites previously unreachable with single-piece logistics.
- India's CEA renewable purchase obligations:State distribution company mandates for wind procurement create blade demand outside established Chinese and European supply orbits.
Industry Challenges
- Composite technician training deficits:Vacuum infusion and preform layup skills concentrate in legacy aerospace regions, constraining manufacturing expansion into emerging wind markets.
- Type certification timeline compression:IEC 61400-23 full-scale blade testing protocols require 12-18 month validation cycles that misalign with developer construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Blades Market |
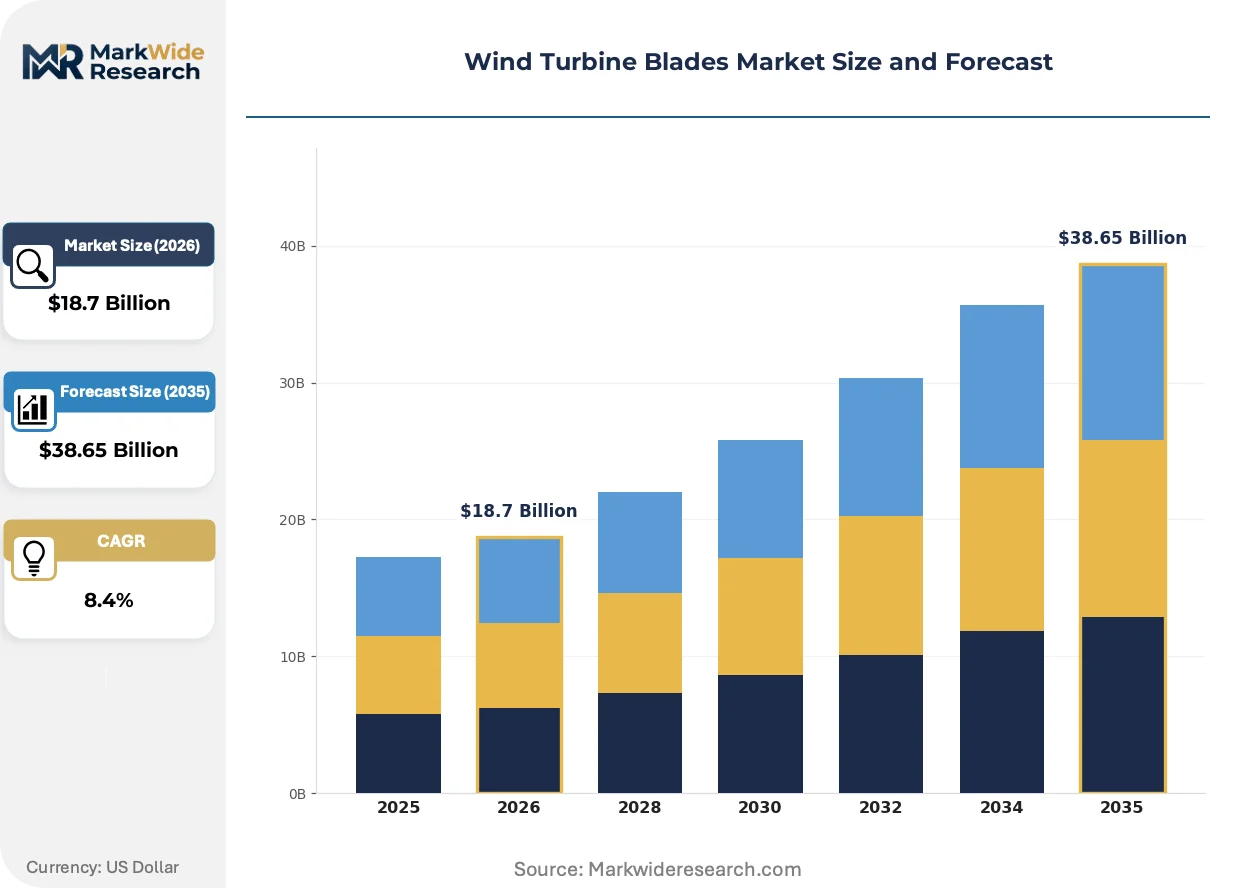
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Fiberglass, Carbon Fiber, Wood, Metal Blade Length: Small, Medium, Large, Extra Large Manufacturing Process: Injection Molding, Hand Layup, Prepreg, Automation End User: Utilities, Independent Power Producers, OEMs, Research Institutions |
| Companies Covered | Siemens Gamesa Renewable Energy, Nordex, TPI Composites, Sinoma Wind Power Blade, MFG Wind, LM Wind Power, Lianyungang Zhongfu Lianzhong Composites Group, Aeris Energy, Vestas Wind Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Blades Market Strategic Shifts & Innovations
Digital thread integration across blade design, manufacturing, and operational monitoring is collapsing traditional handoffs between engineering and field performance, creating continuous feedback loops that accelerate material and geometric iteration cycles.
Automated fiber placement systems are converging with robotic grinding and finishing cells to reduce labor content in carbon fiber spar cap production. Offshore OEMs in Denmark and the Netherlands deploy these lines for 110-meter-plus blade platforms. The technology is converging with real-time thermography inspection to compress cycle times while maintaining structural integrity standards.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in blade core materials, forcing suppliers to qualify CO2-based or hydrocarbon alternatives in sandwich panel construction. This transition adds qualification costs but aligns blade manufacturing with embodied carbon accounting under the EU Green Deal. Nordic and North Sea offshore projects face the tightest compliance timelines.
Developer procurement teams are unbundling blade supply from turbine nacelle packages, negotiating direct contracts with independent manufacturers for specific rotor configurations. This disintermediation fragments traditional OEM turnkey offerings and exposes blade specialists to direct warranty and performance risk. The pattern is most pronounced in Chinese state wind bases and US merchant wind portfolios seeking component-level cost transparency.
Wind Turbine Blades Market Segmentation
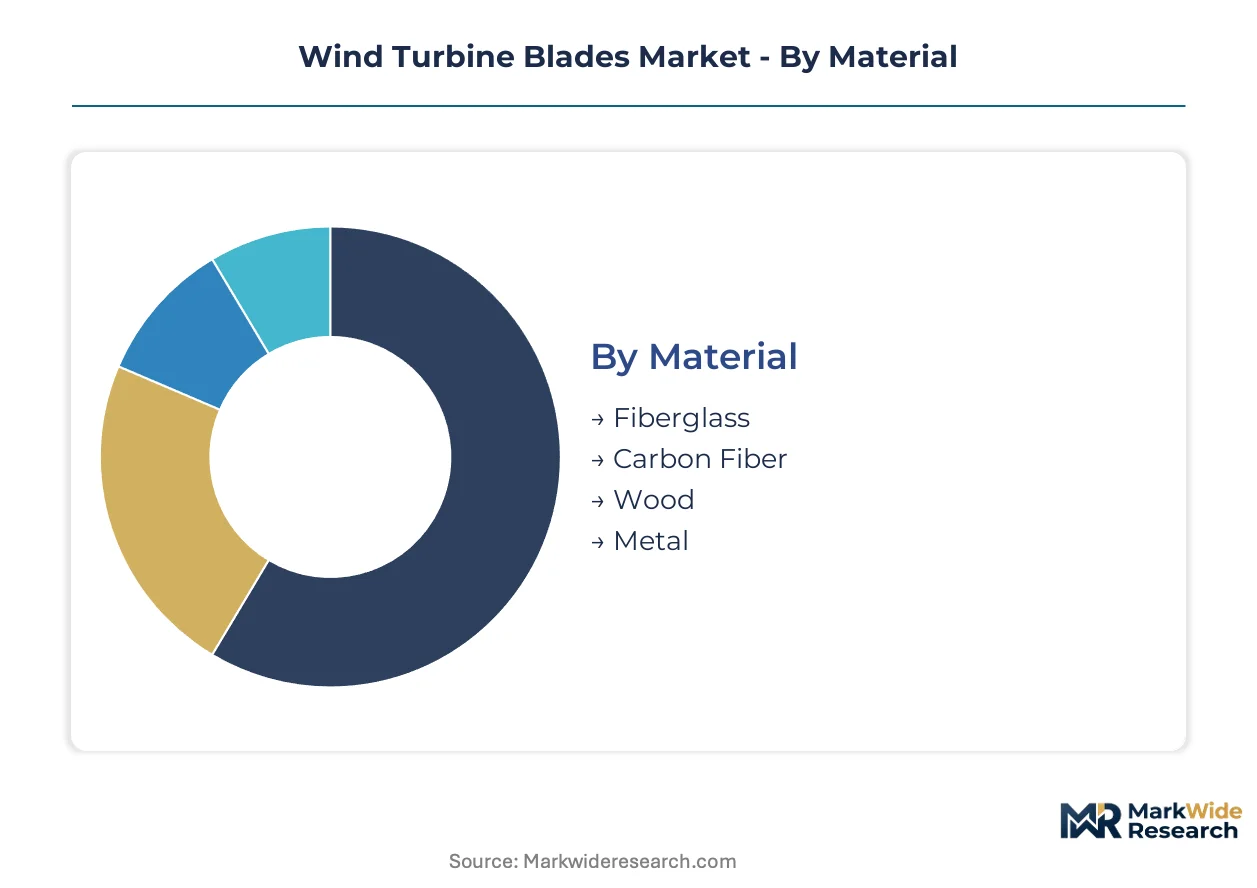
Blade segmentation determines manufacturing footprint, logistics architecture, and margin structure across the value chain. Material selection and dimensional class lock in composite processing requirements and factory location decisions.
Material:
Supply concentration in fiberglass manufacturing clusters shapes regional blade production economics.
- Fiberglass:Glass-fiber reinforced epoxy dominates current production volumes due to cost efficiency at scale. Demand concentrates in Chinese state wind bases where procurement teams prioritize unit economics over stiffness optimization for onshore installations below 100 meters.
- Carbon Fiber:Advanced polymer composites deliver superior stiffness-to-weight ratios critical for 110-meter-plus offshore platforms. European and North Sea developers specify carbon spar caps to reduce rotor mass while maintaining fatigue resistance under cyclic loading.
- Wood:Laminated timber cores serve niche small-turbine applications and heritage restoration projects.
- Metal:Aluminum alloys persist in experimental vertical-axis and micro-turbine prototypes.
Today's leader: Fiberglass. Tomorrow's challenger: Carbon Fiber.
Blade Length:
Dimensional class directly dictates mold capital requirements and transport modality selection.
- Small:Sub-40-meter blades serve distributed generation and retrofitted legacy turbines.
- Medium:40-70 meter platforms anchor repowering programs across German and Danish onshore fleets.
- Large:70-100 meter single-piece structures require specialized flatbed convoys and route surveys.
- Extra Large:115-meter-plus designs exceed road transport limits, forcing developers toward port-adjacent manufacturing or segmented bolted joints for inland sites.
Extra Large blades are gaining share fastest as rotor diameters scale beyond 220 meters.
Manufacturing Process:
Process selection reflects labor cost arbitrage and quality consistency requirements.
- Injection Molding:High-pressure resin transfer suits high-volume small-blade production with minimal porosity variance.
- Hand Layup:Manual fiber placement persists in prototype shops and emerging market greenfields where technician density remains low.
- Prepreg:Pre-impregnated carbon fiber sheets enable precise thickness control for spar cap laminates in Denmark-based technology centers.
- Automation:Robotic fiber placement and automated grinding compress cycle times for 110-meter-plus carbon fiber platforms.
Automation commands premium positioning. Hand Layup retains cost-floor defense.
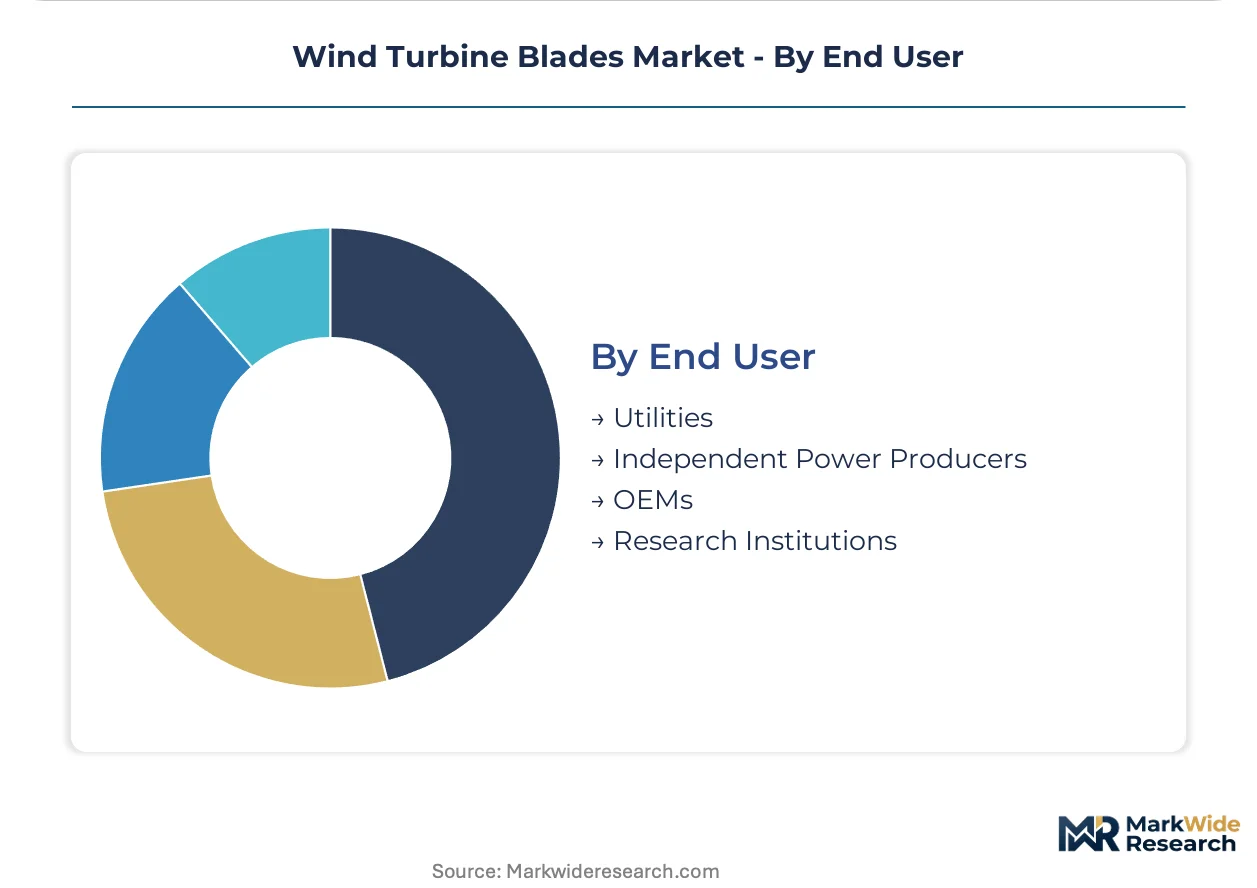
End User:
Procurement authority determines warranty structure and performance risk allocation.
- Utilities:Vertically integrated European and Chinese utilities negotiate direct blade contracts to unbundle component costs from turbine packages.
- Independent Power Producers:Merchant wind developers in US and Indian markets concentrate procurement in medium and large blade classes for PPA-backed projects.
- OEMs:Turbine manufacturers maintain captive blade production or sole-source partnerships to protect integrated margin pools.
- Research Institutions:National laboratories and university programs acquire small-batch prototypes for aerodynamic validation and materials testing.
Utilities drive volume scale. Independent Power Producers are expanding most quickly as merchant wind accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark pioneered modern wind turbine blade manufacturing through LM Wind Power's composite innovations in the 1980s, establishing the technical foundation that now spans manufacturing clusters across four continents.
China
State-backed wind bases in Inner Mongolia and coastal provinces generate concentrated demand for 90-meter-plus blade classes. MIIT enforces GB standards on composite material recycling and blade decommissioning protocols. Lianyungang Zhongfu Lianzhong Composites Group anchors production in Jiangsu province alongside multiple blade fabrication parks serving domestic OEMs.
United States
Merchant wind developers concentrate procurement in medium and large blade classes for PPA-backed projects across Texas and Great Plains wind corridors. The EPA coordinates with FAA on turbine height clearances that indirectly constrain maximum blade lengths for onshore installations. TPI Composites sustains manufacturing scale across multiple OEM programs from its Rhode Island and Iowa facilities.
Germany
Repowering programs across onshore fleets drive demand for 40-70 meter replacement blades. The EU F-Gas Regulation phases down hydrofluorocarbon blowing agents in blade core materials, forcing qualification of CO2-based alternatives. Nordex maintains blade engineering capabilities near Rostock while serving domestic auction requirements under EU Green Deal domestic content mandates.
Denmark
North Sea offshore projects face the tightest compliance timelines for embodied carbon accounting under EU Green Deal frameworks. LM Wind Power anchors European blade engineering through its Denmark-based technology center specializing in carbon fiber spar cap design. Siemens Gamesa Renewable Energy leverages integrated blade-turbine engineering from its Danish headquarters to capture offshore contracts.
Spain
Iberian manufacturing greenfields attract capital redirected by European renewable auction local content requirements. Spanish tooling suppliers currently produce mandrels for 115-meter blade platforms alongside Danish competitors. Aeris Energy occupies a position among fabricators serving southern European offshore development pipelines.
Wind Turbine Blades Market Key Industry Players
The competitive structure tilts toward vertically integrated turbine OEMs controlling captive blade production alongside independent specialists serving multiple manufacturer programs. Two strategic archetypes dominate: integrated engineering houses that synchronize blade design with nacelle aerodynamics, and third-party fabricators that achieve scale through multi-OEM contract manufacturing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with port-adjacent manufacturing investments targeting offshore logistics constraints.
Within the integrated engineering tier, Siemens Gamesa Renewable Energy and Vestas Wind Systems exemplify archetypes that control in-house blade production to protect turbine margin pools. Among independent specialists, TPI Composites occupies a position representing third-party manufacturing scale across multiple OEM programs, while LM Wind Power anchors European blade engineering through Denmark-based technology centers. Sinoma Wind Power Blade and MFG Wind represent scale-driven fabricators positioned within Chinese and North American supply orbits respectively.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Nordex |
| TPI Composites |
| Sinoma Wind Power Blade |
| MFG Wind |
| LM Wind Power |
| Lianyungang Zhongfu Lianzhong Composites Group |
| Aeris Energy |
| Vestas Wind Systems |
| Others |
Cost & Logistics Intelligence
Epoxy resin price indices transmit petrochemical volatility directly into blade laminate cost structures, compressing OEM margin pools and forcing procurement teams toward long-term offtake contracts with Chinese fiberglass suppliers.
Pricing Analysis
Contract-based long-term offtake agreements dominate blade procurement, with pricing stratifying across premium carbon fiber spar caps, standard fiberglass platforms, and economy-grade repowering replacements. Price differentiation hinges on IEC 61400-23 certification tier and volume scale commitments from state wind base developers. Cost compression in standard fiberglass tiers is intensifying because Chinese state-backed procurement teams prioritize unit economics over stiffness optimization. Merchant wind developers in US Great Plains corridors exhibit highest price sensitivity, while North Sea offshore developers accept premium positioning for carbon fiber fatigue resistance.
Supply Chain Analysis
Reverse-logistics flows for end-of-life blade decommissioning remain underdeveloped, with first-generation German and Danish wind farms accumulating thermoset composite waste without scaled recovery infrastructure. Manufacturing gravity centers on China, Denmark, and Spain, with mold fabrication capabilities concentrated in Danish and Spanish tooling suppliers. Raw material supply draws from petrochemical feedstocks for epoxy resins, glass fiber rovings from Chinese state-owned enterprises, and carbon fiber precursors from Japanese and South Korean suppliers. Single-source vulnerability in 115-meter mandrel production creates supply chain risk. Distribution runs through port-adjacent manufacturing clusters for extra-large offshore platforms and specialized flatbed convoys for inland onshore sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind turbine blade procurement has shifted toward premium carbon fiber specifications for offshore platforms, transforming competitive positioning around stiffness-to-weight engineering rather than pure manufacturing scale.
For Market Incumbents: Lock in carbon fiber spar cap supply agreements with Japanese and South Korean precursor suppliers before merchant developers consolidate procurement. Defend margin pools by accelerating in-house production of extra-large blade molds to reduce dependency on Danish and Spanish tooling suppliers. Monitor emerging Chinese blade fabricators targeting European domestic content mandates as a direct threat to established market share. For New Entrants and Emerging Players: Independent power producers in India's CEA-mandated renewable purchase obligations represent the most penetrable buyer archetype outside established Chinese and European supply orbits. Target blade recycling and decommissioning service contracts in Germany and Denmark where first-generation wind farms reach end-of-life without scaled thermoset composite recovery. Pursue joint venture structures with port-adjacent manufacturing greenfields in Spain to satisfy EU Green Deal local content requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where carbon fiber spar cap engineering capabilities concentrate in Denmark-based technology centers and Chinese state-owned fabricators. Long-term viability favors specialists with backward integration into mold fabrication and segmented blade platform intellectual property. Acquisition targets should demonstrate port-adjacent manufacturing footprints and IEC certification track records. Monitor EU F-Gas Regulation compliance timelines and MIIT recycling mandate enforcement as inflection indicators for manufacturing cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Spar Cap Scale-Up | Captures North Sea offshore contracts requiring 110-meter-plus stiffness-to-weight performance. |
| Port-Adjacent Manufacturing Buildout | Resolves logistics constraints for extra-large blade platforms exceeding road transport limits. |
| Blade Recycling Infrastructure Investment | Positions for decommissioning service contracts as German and Danish first-generation fleets retire. |
| Segmented Blade Platform Development | Unlocks inland wind sites previously unreachable with single-piece 115-meter logistics. |
| EU Green Deal Compliance Certification | Secures auction eligibility under tightening domestic content and embodied carbon mandates. |
Research Approach
Multiple input streams — composite manufacturing plant managers, utility procurement officers, wind farm EPC contractors, and blade recycling specialists — were reconciled against secondary validation from IEC certification databases, EU ETS emissions registries, and Chinese MIIT industrial policy filings. Bottom-up project pipeline analysis across Inner Mongolia and coastal state wind bases was triangulated with top-down OEM capacity announcements from Denmark and Spain. Primary fieldwork captured vacuum infusion process economics and mold fabrication lead times from Iberian and Baltic manufacturing greenfields.
Data-stream reconciliation across material segmentation, blade length classes, and end-user procurement authority generated volume and value outputs across the projection horizon. The analytical framework modeled fiberglass versus carbon fiber material splits, small-to-extra-large dimensional tier migrations, and utility versus independent power producer demand patterns. CAGRs were derived from installed capacity trajectories and rotor diameter scaling curves. Forecast inputs incorporated epoxy resin price elasticity, FAA height clearance constraints, and EU F-Gas Regulation phase-down timelines.
Inputs from OEM engineering directors and Chinese state wind base procurement leads were available through the study window; gaps in segmented blade platform commercial deployment introduce uncertainty bands around inland site accessibility assumptions. Forecasts reflect documented assumptions regarding carbon fiber cost curves and recycling infrastructure buildout rates. Practitioners should monitor EU Green Deal domestic content mandate enforcement and MIIT decommissioning protocol implementation for early signals of manufacturing location decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Thailand Wind Energy Market