
 New Zealand Wind Energy Market | 2026-2036
New Zealand Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Wind Energy Market Foresight
Project finance with long-term offtake agreements is reconfiguring competitive entry in New Zealand wind development, enabling independent generators to secure capital without utility balance sheets. Meridian Energy Limited leverages its vertically integrated generation and retail position to control development timelines. Contact Energy Limited anchors its portfolio with grid-scale onshore projects in premium wind corridors. Mercury Energy sustains growth through distributed renewable strategies that complement centralized wind farms.
New Zealand wind energy encompasses turbine systems converting kinetic atmospheric energy into electrical power through horizontal-axis rotors typically rated between 2 MW and 4 MW, feeding into the national grid or embedded networks for commercial and industrial supply. Onshore horizontal-axis technology dominates installed capacity given mature supply chains and proven capacity factors across the country's exposed ridgelines. The utility end-user segment captures the majority of offtake volume through long-term power purchase agreements that underpin project finance structures. Component specialization concentrates in turbine assembly and blade manufacturing where imported nacelles meet locally fabricated towers.
The Electricity Authority governs market dispatch and transmission pricing that directly shapes wind farm location economics, while the Ministry for the Environment administers consenting under the Resource Management Act that determines project timelines. Standards New Zealand adopts IEC turbine design standards that equipment suppliers must meet for grid connection approval. Stakeholders must monitor proposed reforms to national grid transmission investment plans that will determine which wind-rich regions gain competitive dispatch access.
Market Dynamics
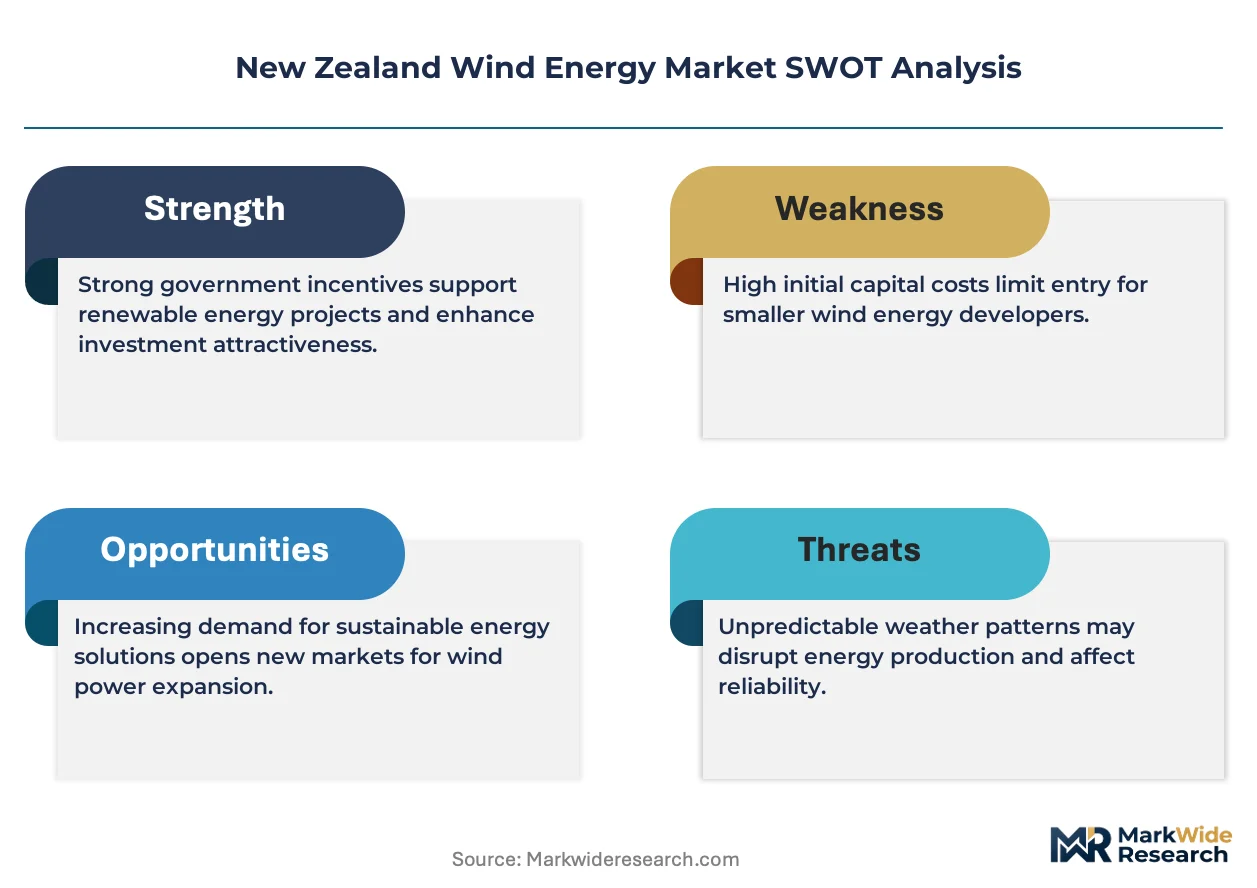
The Electricity Authority's transmission pricing methodology is restructuring locational economics for wind developers, forcing recalculation of project returns across the South Island's high-resource zones.
Growth Catalysts
- Grid-scale storage co-location:Battery energy storage systems paired with wind farms are flattening output volatility and improving dispatch rankings in the wholesale electricity market.
- Resource Management Act streamlining:Proposed fast-track consenting pathways for renewable energy projects are compressing development timelines in premium wind corridors.
- Corporate renewable procurement:Large commercial and industrial buyers are executing direct power purchase agreements that bypass traditional utility intermediaries.
Market Restraints
- Specialized transport logistics:Blade lengths exceeding 70 meters require route modifications and police escorts through New Zealand's narrow mountain passes.
- Grid connection queue congestion:Transpower's connection assessment process faces backlogs in Otago and Southland where multiple projects compete for limited substation capacity.
- Steel and rare earth price volatility:Tower fabrication costs fluctuate with global commodity markets, compressing developer margins on fixed-price construction contracts.
Strategic Opportunities
- Manawatū-Whanganui expansion:The region's proven capacity factors above 45% and existing transmission infrastructure create brownfield development potential.
- Green hydrogen offtake integration:Proposed electrolyzer projects in Taranaki could anchor long-term demand contracts for curtailed wind generation.
- Repowering early installations:Turbines installed during the 1990s and 2000s in the Tararua Range offer retrofit potential with modern 4 MW-plus units.
Industry Challenges
- Geotechnical assessment capacity:The limited pool of New Zealand-based engineers qualified for complex ridgeline foundation design extends pre-construction phases.
- Blade end-of-life processing:The absence of domestic fiberglass recycling infrastructure creates disposal cost uncertainty under proposed extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Wind Energy Market |
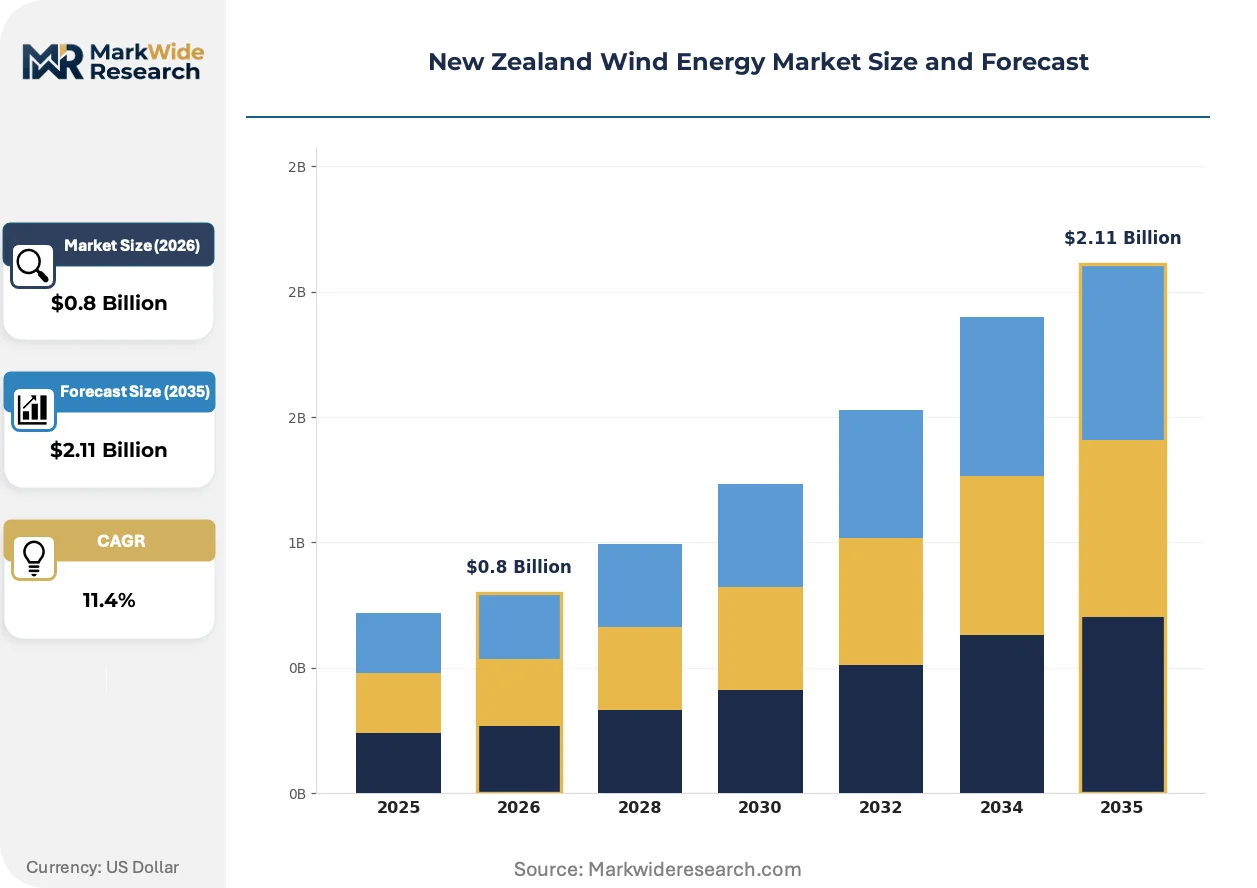
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Industrial Users, Commercial Users, Residential Users Component: Turbine, Blade, Gearbox, Generator Installation Type: New Installation, Retrofit, Expansion, Maintenance |
| Companies Covered | Meridian Energy Limited, Mercury Energy, Vestas Wind Systems, General Electric Company, Contact Energy Limited, Genesis Energy, Siemens Gamesa Renewable Energy, Tilt Renewables Ltd, Manawa Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Wind Energy Market Shifts & Advancements
Digital twin technology and predictive maintenance systems are compressing operational expenditure curves for New Zealand wind assets, while regulatory pressure on embodied carbon reshapes equipment sourcing decisions.
Advanced turbine control software is virtualizing traditional mechanical yaw and pitch systems through sensor-driven algorithms that optimize rotor orientation in real-time. Meridian Energy and Contact Energy are deploying these systems across their South Island fleets to extract incremental capacity factors from turbulent wind regimes. This virtualization is compressing the performance gap between established and greenfield sites, reducing the premium commanded by premium wind corridors.
The Electricity Authority's 2024 consultation on locational marginal pricing represents the most significant market design shift since the 2009 Electricity Industry Act. Industrial load centers in Auckland and Taranaki would face higher effective prices, accelerating demand-side response investments. Wind developers in distant high-resource zones must now model basis risk between generation location and load settlement points.
Aggregated virtual power plant models are emerging as the dominant procurement channel for commercial and industrial offtake. These platforms pool distributed generation assets—including behind-the-meter wind—to offer firm capacity contracts that individual projects cannot match. The shift is most visible in Canterbury, where irrigation-dependent agricultural processors seek price stability through multi-asset portfolios rather than single-source PPAs.
New Zealand Wind Energy Market Segmentation
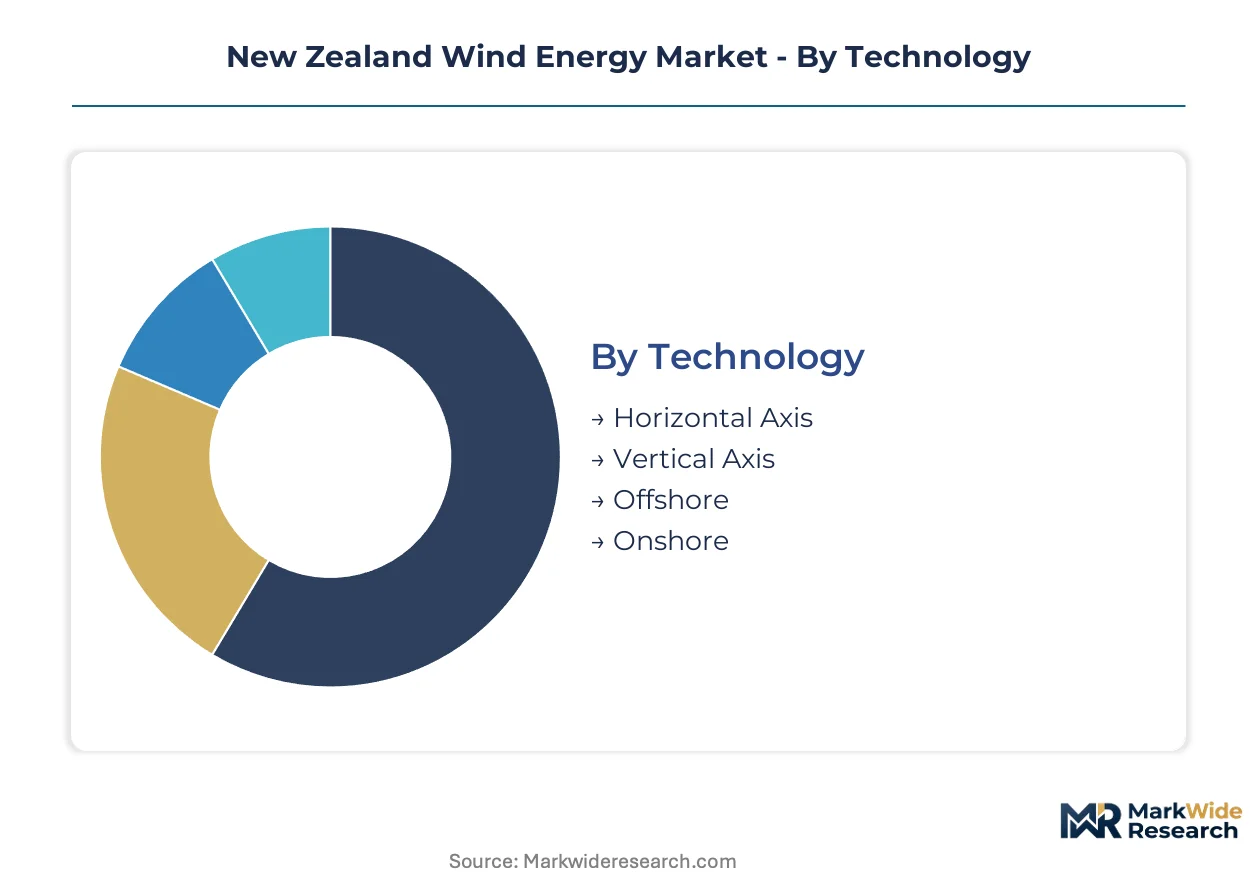
New Zealand's wind energy market segments across technology platforms, end-use applications, and component supply chains that determine project economics. Understanding these divisions reveals where capital concentrates and which configurations respond to regulatory shifts in consenting and transmission pricing.
Technology:
The use-case spectrum spans established onshore horizontal-axis systems through emerging offshore concepts suited to deeper waters.
- Horizontal Axis:Rotor systems with two or three blades mounted on upwind or downwind configurations dominate ridgeline installations. Demand concentrates in Manawatū-Whanganui and Southland where proven capacity factors above 45% attract utility-scale development capital.
- Onshore:Land-based turbine arrays feeding into Transpower's national grid or embedded distribution networks anchor current capacity additions. The Electricity Authority's transmission pricing methodology is restructuring locational returns for developers targeting South Island high-resource zones.
- Vertical Axis:Darrieus and Savonius designs occupy niche applications in distributed generation contexts where omni-directional wind capture offsets lower efficiency.
- Offshore:Floating and fixed-bottom concepts remain pre-commercial in New Zealand waters, with seabed depth and consenting complexity delaying deployment relative to onshore maturation.
Established volume favors Horizontal Axis; emerging adoption favors Offshore.
End User:
Customer type determines offtake contract structures and financing mechanisms across the project pipeline.
- Utilities:Meridian Energy, Contact Energy, and Mercury Energy execute long-term power purchase agreements that underpin project finance for grid-scale developments. Their vertically integrated generation-retail positions control development timelines and dispatch scheduling.
- Industrial Users:Agricultural processors and manufacturing facilities in Canterbury and Taranaki seek price stability through direct procurement or virtual power plant aggregation.
- Commercial Users:Mid-sized enterprises bypass traditional utility intermediaries through corporate renewable procurement channels.
- Residential Users:Behind-the-meter small-scale turbines serve rural properties with adequate wind exposure, though solar PV dominates household renewable investment.
Contract scale favors Utilities; procurement innovation favors Industrial Users.
Component:
Supply chain specialization concentrates in segments where local fabrication meets imported precision engineering.
- Turbine:Complete rotor-nacelle-assembly systems rated 2-4 MW form the capital core of project expenditure. Nacelles arrive from international suppliers while towers are fabricated domestically to reduce transport complexity through mountain corridors.
- Blade:Fiberglass composite structures exceeding 70 meters require specialized logistics and face end-of-life disposal uncertainty under proposed extended producer responsibility frameworks.
- Gearbox:Speed-increasing transmissions between rotor and generator represent high-wear components with established refurbishment supply chains.
- Generator:Electrical conversion systems must meet Standards New Zealand's adopted IEC design standards for grid connection approval.
Local value capture favors Blade; import dependency favors Turbine.
Installation Type:
Project lifecycle phases reflect market maturity from greenfield construction through operational optimization.
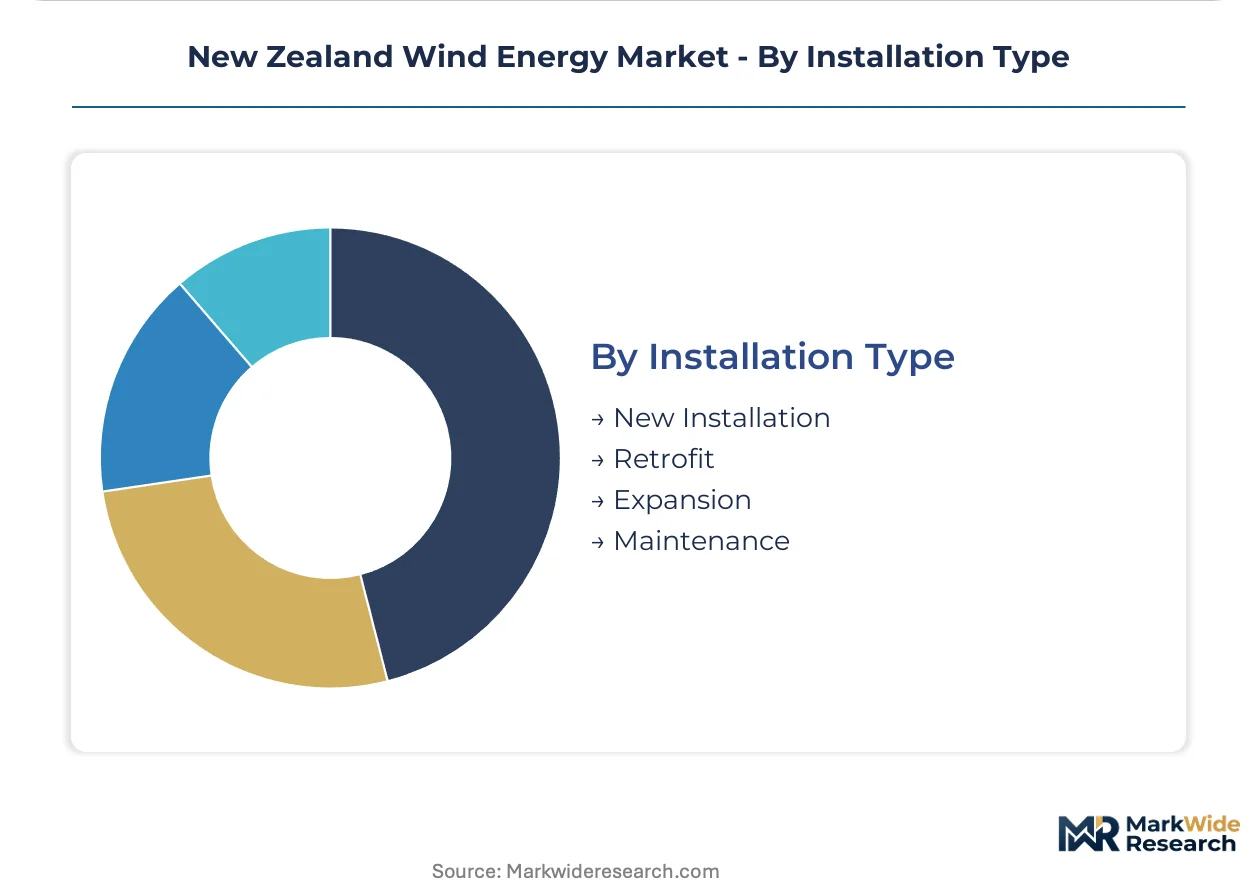
- New Installation:Greenfield turbine deployment in premium wind corridors drives capacity expansion, constrained by Transpower connection queue congestion in Otago and Southland.
- Retrofit:Repowering 1990s and 2000s Tararua Range installations with modern 4 MW-plus units offers capacity uplift without new consenting pathways.
- Expansion:Brownfield site extensions leverage existing transmission infrastructure and operational expertise for incremental capacity.
- Maintenance:Predictive systems and digital twin technology are compressing operational expenditure curves for established fleets.
Capital deployment favors New Installation; margin expansion favors Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Electricity Authority's transmission pricing methodology and fast-track consenting reforms are redistributing development capital across New Zealand's wind corridors, concentrating investment where grid access and resource quality align.
Manawatū-Whanganui
Tararua Range wind farms with capacity factors exceeding 45% anchor brownfield expansion. The Resource Management Act consenting pathways determine project timelines. Palmerston North serves as the regional logistics hub where turbine component assembly meets existing transmission infrastructure.
Southland
High-resource ridgelines attract utility-scale procurement from vertically integrated generators. Transpower's connection queue congestion creates development bottlenecks around Invercargill substations. The region's exposed coastal topography supports larger rotor configurations.
Otago
Central Otago wind corridors face grid connection backlogs as multiple projects compete for limited substation capacity. The Electricity Authority's locational marginal pricing consultation reshapes project return calculations. Dunedin-based engineering firms specialize in geotechnical ridgeline assessments.
Canterbury
Agricultural processors drive corporate renewable procurement through virtual power plant aggregation. Irrigation-dependent food manufacturers seek price stability via multi-asset portfolios. Christchurch anchors demand-side response investments that complement intermittent wind generation.
Taranaki
Proposed electrolyzer projects could anchor long-term offtake contracts for curtailed wind generation. The region's existing petrochemical infrastructure offers brownfield hydrogen production sites. New Plymouth clusters engineering expertise from legacy energy operations.
New Zealand Wind Energy Market Competitive Landscape
Channel-controlling players compete with product-specialist players for capital allocation in New Zealand wind development. The market structure concentrates around vertically integrated utilities with generation-retail positions and independent developers securing project finance through long-term offtake agreements. Strategic archetypes span balance-sheet-backed incumbents, independent power producers, and equipment suppliers with service arms. Dominant competitive moves include transmission queue positioning and turbine supply chain partnerships.
Among New Zealand-based utilities, Meridian Energy Limited and Contact Energy Limited exemplify the vertically integrated archetype controlling development timelines and dispatch scheduling. Mercury Energy occupies a position within the distributed renewable strategy tier, complementing centralized wind farms with smaller-scale assets. Tilt Renewables Ltd represents the independent developer model securing capital without utility balance sheets.
| Leading Market Players |
|---|
| Meridian Energy Limited |
| Mercury Energy |
| Vestas Wind Systems |
| General Electric Company |
| Contact Energy Limited |
| Genesis Energy |
| Siemens Gamesa Renewable Energy |
| Tilt Renewables Ltd |
| Manawa Energy |
| Others |
Supply & Pricing Matrix
Palmerston North anchors New Zealand's wind component assembly cluster, where turbine tower fabrication capacity and grid interconnection infrastructure concentrate development capital. This geographic concentration grants established developers procurement leverage over new entrants bidding for limited domestic steel fabrication slots.
Pricing Analysis
Project scale and grid connection tier create the primary spread in New Zealand wind development economics. Large utility-scale installations secure long-term power purchase agreements that lock in revenue certainty, while smaller distributed projects face merchant price exposure. Pricing pressure intensifies in Otago and Southland as Transpower connection queue congestion forces developers to absorb extended holding costs. Industrial offtakers demonstrate highest price sensitivity through virtual power plant aggregation, whereas vertically integrated utilities exhibit lowest sensitivity due to captive retail demand.
Supply Chain Analysis
Domestic tower fabricators in Palmerston North and Auckland hold contracted capacity for nacelle integration, while blade and generator imports draw from Denmark, Germany, and China. Tower steel and rare earth magnet dependencies expose developers to commodity volatility and shipping route constraints. Single-source vulnerability concentrates in specialized blade logistics exceeding 70 meters through mountain corridors. Distribution runs through Transpower's national grid with embedded network alternatives for industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand wind energy sits as a high-growth disruption driven by the Electricity Authority's locational marginal pricing consultation, which will restructure dispatch economics across South Island high-resource zones.
For Market Incumbents: Insulate project returns by securing priority positions in Transpower's connection queue ahead of regulatory implementation. Meridian Energy and Contact Energy should deepen backward integration into tower fabrication to offset steel price volatility. Control of Palmerston North assembly capacity represents the critical defensive lever against independent developer encroachment.
For New Entrants and Emerging Players: Mid-scale commercial and industrial offtakers in Canterbury represent the most penetrable entry point for aggregated virtual power plant offerings. Taranaki green hydrogen offtake contracts offer anchor demand for curtailed generation. Direct corporate procurement channels bypass utility intermediaries and unlock faster development timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure yield play because transmission-connected assets generate contracted revenue streams underpinned by resource management act consenting scarcity. Acquisition targets should display secured grid connection agreements and brownfield expansion rights in Manawatū-Whanganui. Monitor Electricity Authority final determinations on locational marginal pricing as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Transmission Queue Positioning | Secures dispatch priority ahead of Electricity Authority pricing reforms in South Island zones. |
| Power Purchase Agreement Execution | Locks in long-term offtake with corporate buyers bypassing traditional utility channels. |
| Backward Integration into Tower Fabrication | Captures steel fabrication margin and reduces transport complexity through domestic supply. |
| Battery Co-location Deployment | Flattens output volatility and improves wholesale market dispatch rankings for wind assets. |
| Green Certification Program | Aligns with corporate renewable procurement standards and streamlines consenting pathways. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with utility planning officers, independent power producer project developers, EPC contractors, and grid operators; and secondary validation against Electricity Authority market reports, Transpower transmission investment disclosures, Resource Management Act consenting databases, and Standards New Zealand IEC adoption records. Bottom-up project pipeline enumeration triangulated against top-down market sizing from generation capacity forecasts.
Forecast inputs span technology platform maturation, transmission pricing methodology evolution, and corporate procurement channel growth across the projection horizon. Segmentation modeling incorporates turbine scale tier, end-user contract structure, component supply chain origin, and regional grid access type. CAGRs derive from capacity addition trajectories and revenue per megawatt-hour assumptions tied to wholesale market design shifts.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and steel commodity prices would shift project finance viability and construction cost assumptions. Forecasts reflect documented assumptions on consenting timeline compression and transmission investment sequencing. Quarterly review of Electricity Authority regulatory determinations and Transpower connection queue status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Wind Energy Market