
 Norway Offshore Oil and Gas Decommissioning Market | 2026-2036
Norway Offshore Oil and Gas Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Offshore Oil and Gas Decommissioning Market Analytics
Modular contracting for integrated platform removal and site clearance is hardening as the preferred procurement model among North Sea operators. Aker Solutions ASA leverages its heavy-lift vessel fleet to dominate full-field decommissioning packages. Subsea 7 sustains competitive positioning through specialized pipeline abandonment engineering. AF Gruppen ASA anchors its market presence with onshore waste management and recycling capabilities tied to offshore contracts.
Norway offshore oil and gas decommissioning encompasses the engineered dismantlement, removal, and environmental restoration of subsea production systems, fixed platforms, and pipelines at water depths from 70 to 500 meters, employing heavy-lift vessels, cutting tools, and remotely operated seabed equipment. The primary purpose is to eliminate physical infrastructure, remediate hydrocarbon-contaminated sediments, and restore seabed conditions to regulatory baseline states after production cessation. Platform removal commands the largest revenue share due to structural mass and marine operation complexity, while robotic systems and remote operated vehicles represent the fastest-expanding technology category as operators substitute mechanized seabed intervention for diver-dependent methods. Performance-based contracting models are gaining traction as oil companies transfer operational risk to service providers with demonstrated removal efficiency metrics.
Petroleum Safety Authority Norway enforces removal depth requirements and seabed clearance standards that dictate engineering scope and cost structure for every decommissioning project. The Norwegian Environment Agency coordinates waste stream permitting and discharge limits that shape onshore processing investments by contractors. Equinor Energy AS, as both operator and stakeholder, navigates internal portfolio obligations alongside external regulatory timelines that compress project windows. Stakeholders must monitor how upcoming field cessation decisions and regulatory interpretation shifts around partial removal alternatives will redistribute contract value across the supplier chain.
Market Dynamics
Platform removal complexity at 70-500 meter water depths is compressing project timelines and forcing operators toward integrated service bundling. The Petroleum Safety Authority Norway's mandate for comprehensive seabed clearance eliminates partial abandonment options, reshaping contractor capability requirements.
Growth Catalysts
- Regulatory Mandate Stringency:The Petroleum Safety Authority Norway enforces full removal standards that eliminate cost-cutting alternatives. Operators must contract comprehensive dismantlement services.
- Asset Age Concentration:North Sea infrastructure installed during the 1970s-1980s buildout is reaching end-of-life simultaneously. Field cessation decisions cluster in narrow windows.
- Heavy-Lift Vessel Specialization:Purpose-built decommissioning vessels with 10,000+ ton crane capacity enable single-lift platform topside removal. Marine contractors are absorbing these assets into fleet rotations.
Market Restraints
- Steel Price Volatility:Scrap steel revenue uncertainty destabilizes project economics. Recycling value fluctuations directly impact contractor risk pricing.
- Specialized Labor Scarcity:Subsea cutting technicians and remotely operated vehicle pilots concentrate in Aberdeen and Stavanger clusters. Geographic concentration creates wage pressure.
- Legacy Well Integrity:Plugging and abandonment of pre-1990s wells requires non-standard cement formulations. Technical limitations extend timelines for early-generation installations.
Strategic Opportunities
- Arctic Infrastructure Pre-positioning:Barents Sea field developments will eventually require decommissioning capabilities. Contractors establishing presence in Hammerfest gain first-mover positioning.
- Robotic Seabed Intervention:Autonomous underwater vehicles converging with machine vision systems enable diverless pipeline cutting. Technology convergence reduces personnel exposure costs.
- Onshore Circular Processing:The Norwegian Environment Agency's waste hierarchy incentives favor material recovery over landfill. Contractors with in-house recycling infrastructure capture margin expansion.
Industry Challenges
- Subsea Metallurgical Assessment:Corrosion evaluation of decades-submerged structures requires specialized non-destructive testing protocols. Certification timelines extend front-end engineering phases.
- Cross-Contractor Coordination:Platform removal, pipeline abandonment, and site clearance often involve three separate specialist firms. Integration complexity multiplies interface risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Offshore Oil and Gas Decommissioning Market |
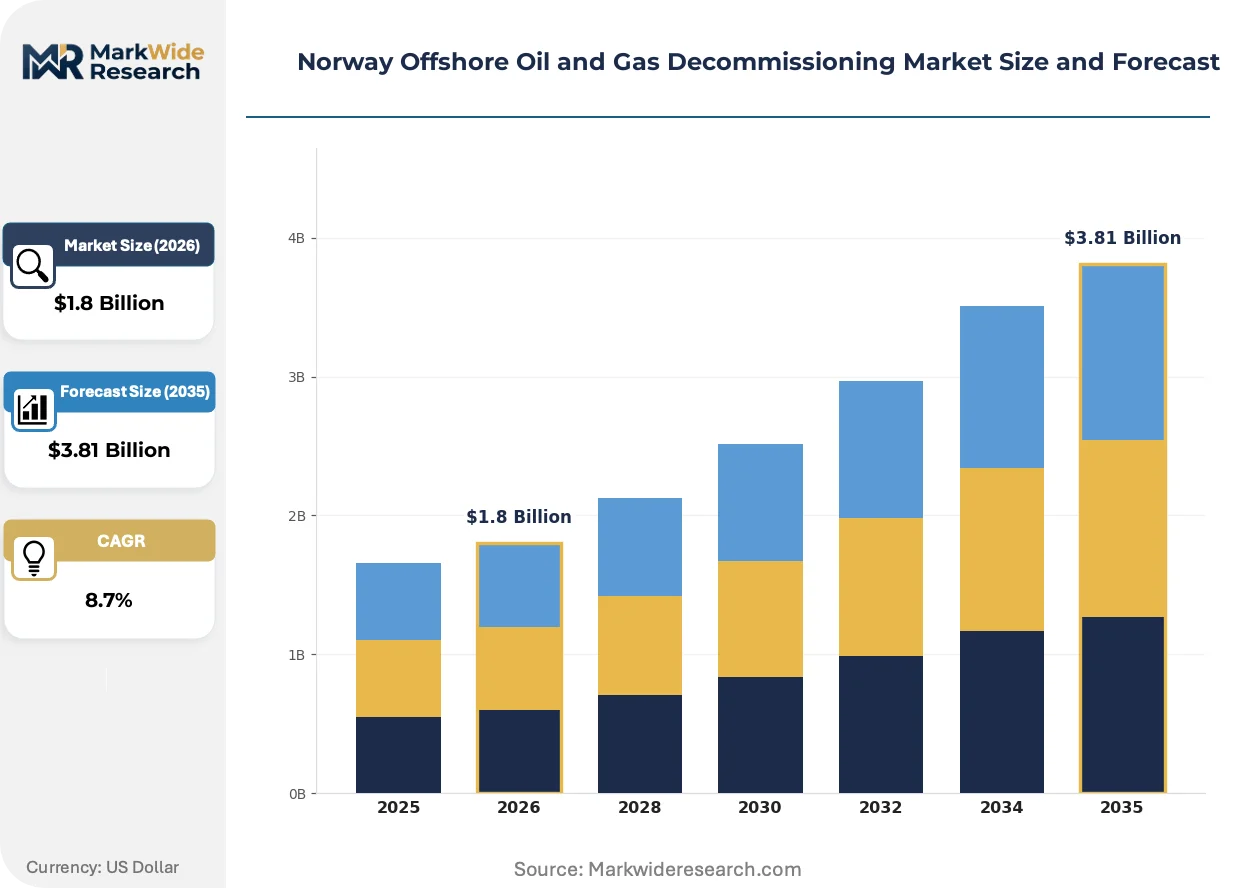
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Platform Removal, Pipeline Abandonment, Site Clearance, Waste Management Technology: Robotic Systems, Remote Operated Vehicles, Conventional Dismantling, Environmental Monitoring End User: Oil Companies, Service Providers, Regulatory Authorities, Environmental Agencies Contracting Model: Fixed Price, Cost Plus, Time and Materials, Performance-Based |
| Companies Covered | DNV GL, Petroleum Geo-Services ASA, AF Gruppen ASA, Subsea 7, Oceaneering International, Aker Solutions ASA, Spirit Energy Limited, TechnipFMC, Equinor Energy AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Offshore Oil and Gas Decommissioning Market Evolving Landscape
Mechanized seabed intervention is displacing human diving operations across the Norwegian Continental Shelf. Three interconnected developments are compressing project execution models and redistributing value toward technology-integrated service providers.
Remotely operated vehicles equipped with diamond wire cutting systems are absorbing tasks previously requiring saturation diving teams. Equinor and Aker BP are specifying ROV-only intervention for pipeline severance at depths below 120 meters. This absorption is eliminating dive-spread mobilization costs and compressing weather-window constraints.
The Petroleum Safety Authority Norway's 2023 clarification on seabed clearance verification requirements is mandating acoustic and visual survey redundancy. Contractors must deploy multibeam echosounders combined with synthetic aperture sonar for post-removal site certification. Subsea 7 and Ocean Installer are reconfiguring survey spreads to meet dual-sensor mandates.
Performance-based contracting is displacing unit-rate pricing for integrated removal packages. Operators transfer cost-overrun risk to contractors with demonstrated heavy-lift efficiency metrics. This shift concentrates contract awards among vessel owners with documented North Sea removal track records.
Norway Offshore Oil and Gas Decommissioning Market Segmentation
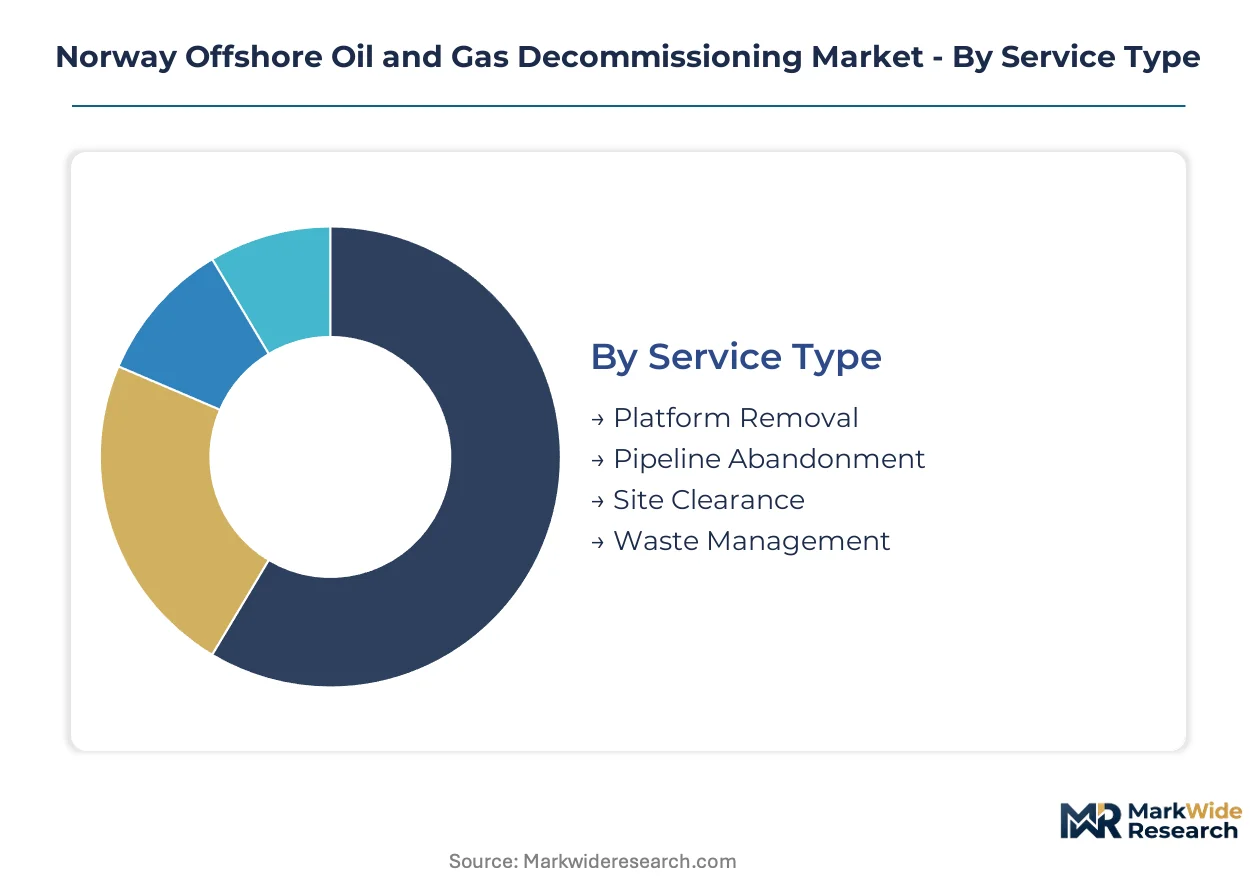
Decommissioning procurement in the Norwegian Continental Shelf segments across service complexity, intervention technology, stakeholder role, and risk allocation structure. Each dimension shapes contractor capability requirements and contract value distribution differently.
Service Type:
Operator procurement patterns diverge based on whether they seek single-source accountability or specialist fragmentation for discrete work scopes.
- Platform Removal:Heavy-lift marine operations encompassing topside module extraction, jacket severance, and offshore-to-onshore transport. Demand concentrates around mature fields in the North Sea's Norwegian sector, driven by the Petroleum Safety Authority Norway's mandate for complete structural removal rather than reefing alternatives.
- Pipeline Abandonment:Subsea infrastructure decommissioning through trenching, cutting, and burial or removal operations. Activity clusters around the Ekofisk and Statfjord field complexes where 1970s-era trunk lines reach end-of-life simultaneously, constrained by seabed clearance verification requirements.
- Site Clearance:Post-removal seabed survey and debris recovery to regulatory baseline conditions. Norwegian operators bundle this with platform contracts to transfer certification liability.
- Waste Management:Onshore processing of hydrocarbon-contaminated materials and structural steel recycling. The Norwegian Environment Agency's waste hierarchy enforcement drives contracting toward integrated recyclers.
Platform removal leads volumes today; site clearance is gaining share fastest as verification standards tighten.
Technology:
Contractor selection increasingly hinges on demonstrated capability in mechanized seabed intervention versus legacy diving-dependent methods.
- Robotic Systems:Autonomous and semi-autonomous platforms executing cutting, inspection, and manipulation tasks without surface-tethered umbilicals. Emerging demand centers on Barents Sea pre-positioning where weather windows compress operational availability.
- Remote Operated Vehicles:Tethered submersibles with manipulator arms and diamond wire cutting tools. Equinor and Aker BP now specify ROV-only intervention below 120-meter depths, eliminating saturation diving spreads from project economics.
- Conventional Dismantling:Surface-based cutting, lifting, and module segregation using crane vessels and manual fabrication techniques. Remains prevalent for topside processing where structural geometry favors established methods.
- Environmental Monitoring:Sensor arrays and sampling protocols for hydrocarbon release detection and sediment contamination assessment. Mandated by the Norwegian Environment Agency for all removal operations.
Remote operated vehicles lead volumes today; robotic systems are expanding most quickly as autonomy converges with machine vision.
End User:
Stakeholder influence over project scope and timeline varies sharply across the Norwegian decommissioning value chain.
- Oil Companies:Field operators holding cessation and removal obligations under petroleum licenses. Internal portfolio prioritization at Equinor Energy AS compresses external contractor procurement windows.
- Service Providers:Marine contractors, engineering houses, and waste processors executing removal operations. Heavy-lift vessel owners with North Sea track records capture integrated package awards.
- Regulatory Authorities:The Petroleum Safety Authority Norway and Norwegian Environment Agency setting removal depth, seabed clearance, and discharge standards. Regulatory interpretation shifts redistribute contract value across supplier tiers.
- Environmental Agencies:Coordination bodies overseeing waste stream permitting and circular economy compliance. Incentives for material recovery over landfill shape onshore processing investments.
Oil companies lead volumes today; service providers are gaining share fastest as performance-based contracting transfers operational risk.
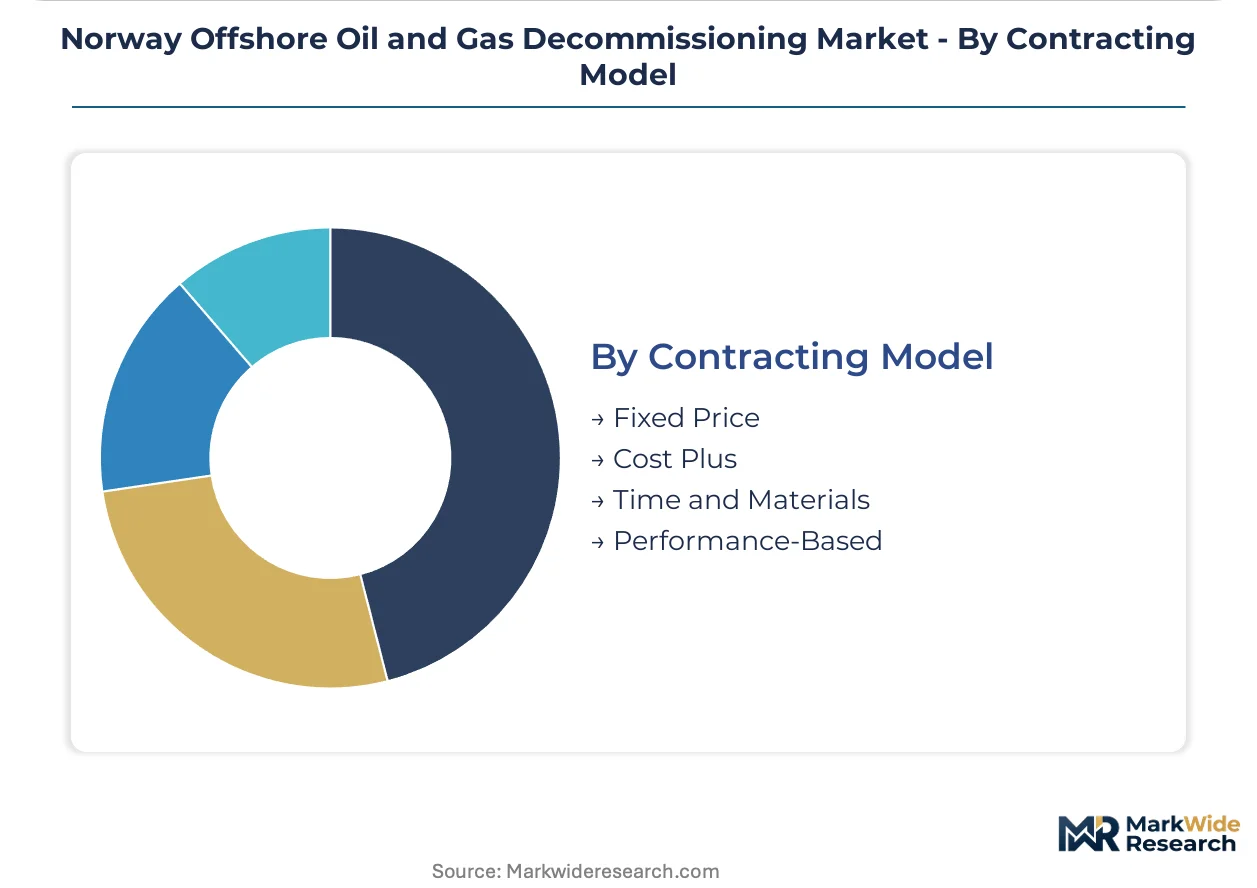
Contracting Model:
Risk allocation preferences are shifting from unit-rate transparency toward outcome-based accountability.
- Fixed Price:Lump-sum agreements with defined scope and schedule parameters. Contractors with documented removal efficiency metrics absorb cost-overrun exposure.
- Cost Plus:Reimbursement of actual costs plus agreed fee percentage. Persists for early-phase engineering where subsurface uncertainty defies accurate estimation.
- Time and Materials:Billing based on resource deployment duration and consumption. Declining share as operators seek budget predictability.
- Performance-Based:Payment tied to demonstrable outcomes including schedule adherence, safety metrics, and seabed clearance certification. The Norwegian Continental Shelf is accelerating adoption of this structure.
Fixed price leads volumes today; performance-based models are climbing the fastest as operators transfer project risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea offshore decommissioning originated in Norwegian waters during the late 1990s, establishing Stavanger as the industry's foundational cluster. This heritage shapes how contractors organize capabilities across the Norwegian Continental Shelf today.
Stavanger Region
Stavanger anchors Norway's decommissioning supply chain through heavy-lift vessel operators and subsea engineering houses. The Petroleum Safety Authority Norway maintains its headquarters here, enabling direct regulatory interface for project permitting. Contractors cluster around Dusavik harbor, where marine bases support North Sea campaign mobilizations.
Bergen Area
Bergen hosts specialized pipeline abandonment engineering and remotely operated vehicle operators serving western North Sea fields. The Norwegian Environment Agency coordinates waste stream permitting from regional offices, shaping onshore processing logistics. Subsea technology providers concentrate in Ågotnes and Åsane industrial zones.
Hammerfest
Hammerfest positions contractors for eventual Barents Sea decommissioning as Snøhvit and Goliat fields mature. Arctic infrastructure requirements differ fundamentally from North Sea standards. Local marine bases offer year-round access despite seasonal ice constraints.
Oslo
Oslo concentrates corporate headquarters and financial structuring functions for decommissioning project portfolios. The Norwegian Ministry of Petroleum and Energy oversees license obligation frameworks from the capital. Engineering consultancies and legal advisors cluster in Fornebu and Bjørvika developments.
Norway Offshore Oil and Gas Decommissioning Market Competitive Landscape
Premium-margin players sit above commodity-margin players across vessel specialization and integrated service bundling. Heavy-lift marine contractors with purpose-built decommissioning fleets capture integrated package awards, while specialist engineering houses compete for discrete work scopes. Three archetypes dominate: full-field integrators with vessel ownership, subsea specialists with robotic intervention capabilities, and onshore processors with circular material recovery infrastructure. Competitive dynamics center on fleet expansion through newbuild heavy-lift vessels and backward integration into waste processing assets.
Among Norwegian-based contractors, Aker Solutions ASA occupies a position within the full-field integrator tier, while AF Gruppen ASA exemplifies the onshore processing archetype with waste management capabilities. Subsea 7 represents the subsea specialist category through pipeline abandonment engineering. These three anchors illustrate how capability bundling determines contract access across the Norwegian Continental Shelf.
| Leading Market Players |
|---|
| DNV GL |
| Petroleum Geo-Services ASA |
| AF Gruppen ASA |
| Subsea 7 |
| Oceaneering International |
| Aker Solutions ASA |
| Spirit Energy Limited |
| TechnipFMC |
| Equinor Energy AS |
| Others |
Value Network & Pricing Analysis
Heavy-lift vessel scarcity against platform removal demand bifurcates contractor margins sharply, with integrated package providers capturing premium pricing while fragmented specialists absorb commodity-rate pressure. This divergence feeds directly into fleet investment decisions, as vessel ownership concentration in Stavanger and Bergen shapes regional pricing power and forces non-asset owners toward subcontracting relationships that erode margin retention.
Pricing Analysis
Performance-based lump-sum contracting dominates the Norwegian Continental Shelf, transferring cost-overrun risk from Equinor and Aker BP to contractors with documented removal efficiency metrics. Price differentiation hinges on heavy-lift crane capacity certification and seabed clearance guarantee provisions, with 10,000-ton-plus vessel operators commanding substantial premiums over smaller operators. Pricing pressure intensifies in pipeline abandonment segments where ROV saturation erodes specialist margins. International oil companies exhibit lowest price sensitivity due to license obligation timelines, while independent operators facing field cessation clusters negotiate most aggressively on bundled scopes.
Supply Chain Analysis
Direct-to-operator contracting handles integrated platform removal demand, with marine contractors maintaining Stavanger marine bases for North Sea campaign mobilizations. Geographic supply concentration centers on Norway, the United Kingdom, and the Netherlands, where heavy-lift vessel construction and subsea engineering capabilities cluster. Raw material dependencies span high-strength steel for jacket fabrication, diamond wire for subsea cutting systems, and specialized cement formulations for well plugging. Supply chain risk concentrates in single-source saturation diving technician pools concentrated in Aberdeen and Stavanger, creating wage inflation vulnerability. Distribution runs through long-term framework agreements rather than spot procurement, locking in vessel allocation years ahead of field cessation dates.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norway offshore decommissioning market compounds value through regulatory obligation intensity, with Petroleum Safety Authority Norway's full removal mandate eliminating cost-cutting alternatives and guaranteeing demand visibility for compliant service providers.
For Market Incumbents: Anchor market position through backward integration into onshore waste processing assets, capturing Norwegian Environment Agency circular economy incentives that favor material recovery over landfill disposal. Expand heavy-lift vessel fleet with Arctic-capable specifications to pre-position for Barents Sea decommissioning cycles. Defend against robotic intervention specialists by acquiring autonomous underwater vehicle capabilities or forming exclusive technology partnerships with machine vision developers. For New Entrants and Emerging Players: Capture white-space opportunity in site clearance verification services, where dual-sensor acoustic and visual survey mandates create specialist demand unmet by generalist contractors. Target Hammerfest marine base establishment for Arctic infrastructure positioning before Snøhvit and Goliat field maturation accelerates. Enter through performance-based contracting partnerships with established vessel owners, leveraging survey technology differentiation rather than capital-intensive fleet competition. For Investors and Strategic Acquirers: Consolidation pressure builds where ROV-only intervention specifications eliminate diving-dependent contractors from contract eligibility, creating distressed asset opportunities among legacy service providers. Frame long-term viability around 5-10 year regulatory obligation windows with limited substitution risk. Prioritize acquisition targets with in-place Norwegian Environment Agency waste permits and documented seabed clearance certification track records. Monitor Petroleum Safety Authority Norway regulatory interpretation shifts around partial removal alternatives as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Lift Vessel Fleet Expansion | 10,000-ton crane capacity enables single-lift platform topside removal for Equinor field obligations. |
| ROV-Only Intervention Certification | Diamond wire cutting capabilities below 120-meter depths eliminate saturation diving spread costs. |
| Onshore Circular Processing Investment | In-house steel recycling infrastructure captures Norwegian Environment Agency waste hierarchy incentives. |
| Arctic Marine Base Pre-positioning | Hammerfest infrastructure establishes first-mover positioning for Barents Sea decommissioning cycles. |
| Performance-Based Contracting Capability | Outcome accountability transfers cost-overrun risk and concentrates awards among proven operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with decommissioning project managers, marine contracting executives, regulatory affairs specialists at the Petroleum Safety Authority Norway, and waste processing facility operators with secondary validation. Secondary sources encompassed Norwegian Environment Agency discharge permits, Petroleum Safety Authority Norway removal compliance filings, offshore vessel tracking databases, and North Sea field cessation announcements. Bottom-up project pipeline enumeration triangulated against top-down regulatory obligation modeling to establish market sizing.
Segment-weighting approaches distributed value across service type, technology category, and contracting model dimensions, with platform removal, pipeline abandonment, site clearance, and waste management tracked separately. Deployment depth tiers, vessel specification classes, and regional clusters within the Norwegian Continental Shelf provided additional analytical granularity. CAGRs were derived from project announcement velocity and regulatory timeline compression. Forecast inputs incorporated heavy-lift vessel supply constraints, well integrity assessment backlogs, and seabed clearance verification standard evolution.
Underlying measurement precision varies by segment; platform removal carries tighter precision due to visible project announcements, while robotic systems adoption trajectories carry wider uncertainty bands. Forecasts reflect assumptions around regulatory mandate continuity, field cessation schedule adherence, and vessel delivery timelines. Periodic stress-testing of base assumptions is recommended against Petroleum Safety Authority Norway policy shifts, steel price volatility, and Arctic infrastructure development acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
South Sudan Oil and Gas Market