
 Spain Wind Energy Market | 2026-2036
Spain Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Wind Energy Market Outlook
Aftermarket service revenue is rewriting margin distribution across the Spain wind energy value chain. Siemens Gamesa Renewable Energy leverages its blade refurbishment network to capture recurring revenue streams. Iberdrola anchors its competitive position through integrated project development and grid connection capabilities. Vestas Wind Systems dominates the onshore turbine servicing segment with predictive maintenance platforms.
Wind energy encompasses the kinetic-to-electrical conversion of atmospheric air currents through aerodynamic rotor blades driving synchronous or doubly-fed induction generators, with modern onshore turbines reaching hub heights exceeding 130 meters and rotor diameters surpassing 160 meters to maximize capacity factors across variable terrain. The technology serves as Spain's primary renewable electricity source, supplying baseload-compatible generation that balances intermittency through geographic dispersion and hybrid storage pairing. Onshore horizontal-axis turbines occupy the mature volume position with established supply chains, while offshore installations represent the fastest-expanding technology segment as floating foundation designs unlock deeper Mediterranean waters. The component dimension concentrates margin pools in blades and nacelles, where advanced composite materials and direct-drive generator architectures differentiate performance.
Spain's Ministry for the Ecological Transition enforces renewable deployment schedules through the National Integrated Energy and Climate Plan, while grid operator Red Eléctrica de España mandates connection standards that shape turbine certification requirements. The EU Green Deal and REPowerEU framework accelerate permitting streamlining and cross-border renewable financing mechanisms that expand developer access to capital. Stakeholders must monitor seabed leasing rounds and port infrastructure investments to time offshore entry decisions against onshore site saturation.
Market Dynamics
Spain's wind energy sector is experiencing a structural inflection as floating offshore technology unlocks deeper Mediterranean waters previously inaccessible to fixed-bottom foundations, triggering a geographic expansion of developable seabed and reshaping capital allocation across the value chain.
Growth Catalysts
- EU Green Deal framework:The EU Green Deal and REPowerEU mechanism accelerate permitting streamlining and unlock cross-border renewable financing pools that expand developer access to institutional capital.
- Castilla y León onshore cluster:Concentrated wind resources and extensive land availability in Castilla y León sustain high-capacity-factor project economics that attract utility-scale procurement commitments.
- Hybrid storage pairing:Co-located battery systems are mitigating intermittency constraints and enabling wind farms to capture premium capacity market revenues through firm dispatchable output.
Market Restraints
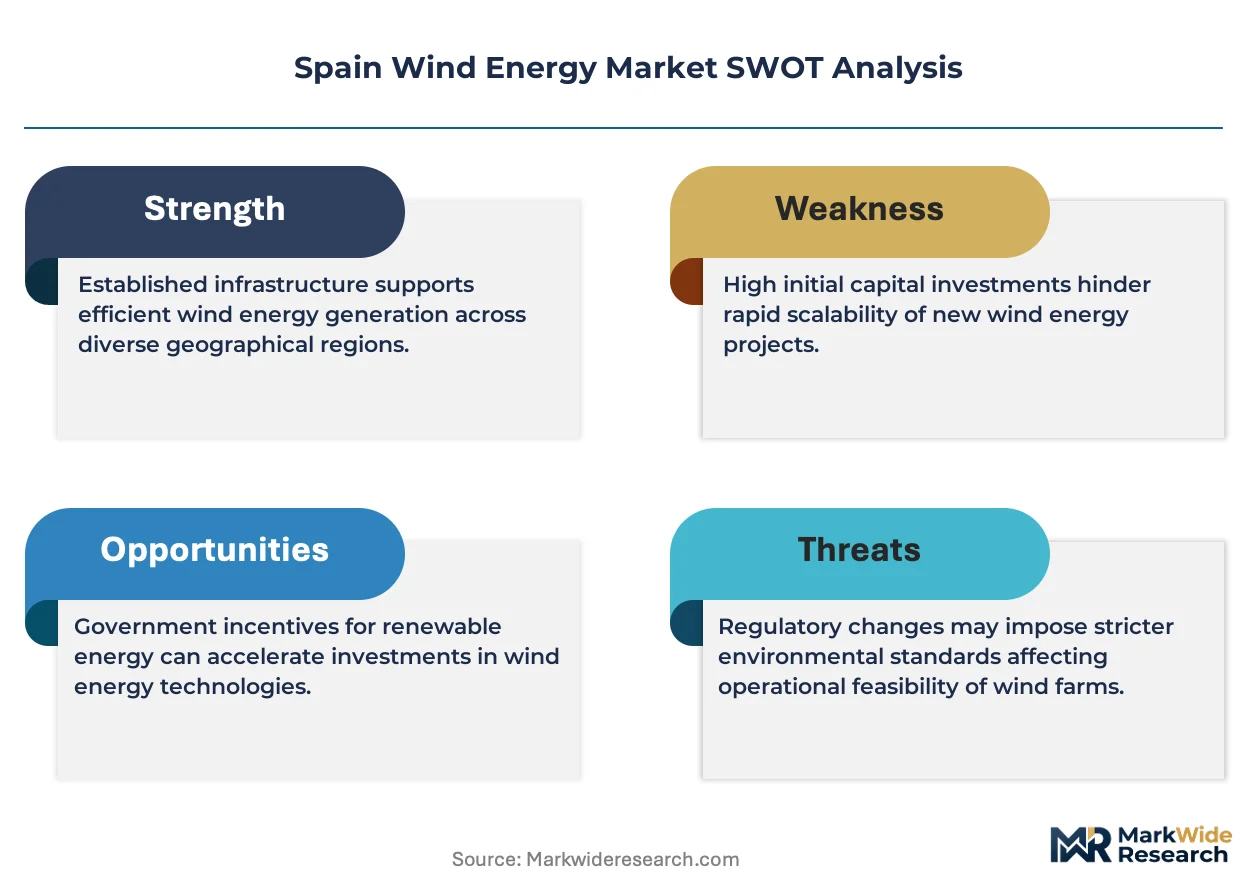
- Grid connection queues:Red Eléctrica de España interconnection backlogs extend project commissioning timelines by 18-36 months, compressing developer returns and elevating offtake pricing requirements.
- Specialized vessel scarcity:Heavy-lift installation ships capable of handling 15MW+ turbine components remain concentrated among Northern European operators, constraining Spanish offshore deployment velocity.
- Copper and rare earth volatility:Direct-drive generator architectures depend on neodymium and dysprosium supply chains concentrated in Chinese processing facilities, exposing nacelle manufacturers to input cost swings.
Strategic Opportunities
- Aragón green hydrogen hub:The region's wind-to-hydrogen pipeline projects create offtake certainty for new capacity while positioning Spain as a European electrolyzer export base.
- Blade refurbishment networks:Circular economy mandates under EU waste directives are creating aftermarket revenue streams through blade decommissioning and composite recycling services.
- Canary Islands floating pilot zone:Deep-water demonstration projects off Gran Canaria and Tenerife offer first-mover learning curves for Mediterranean floating foundation deployment.
Industry Challenges
- Marine construction expertise deficit:Spanish port infrastructure and specialized offshore engineering talent pools lag North Sea capabilities, requiring imported contracting capacity that elevates project execution risk.
- Type certification timelines:IEC 61400-22 turbine certification processes for novel floating platforms extend 12-18 months beyond conventional onshore equivalents, compressing construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Wind Energy Market |
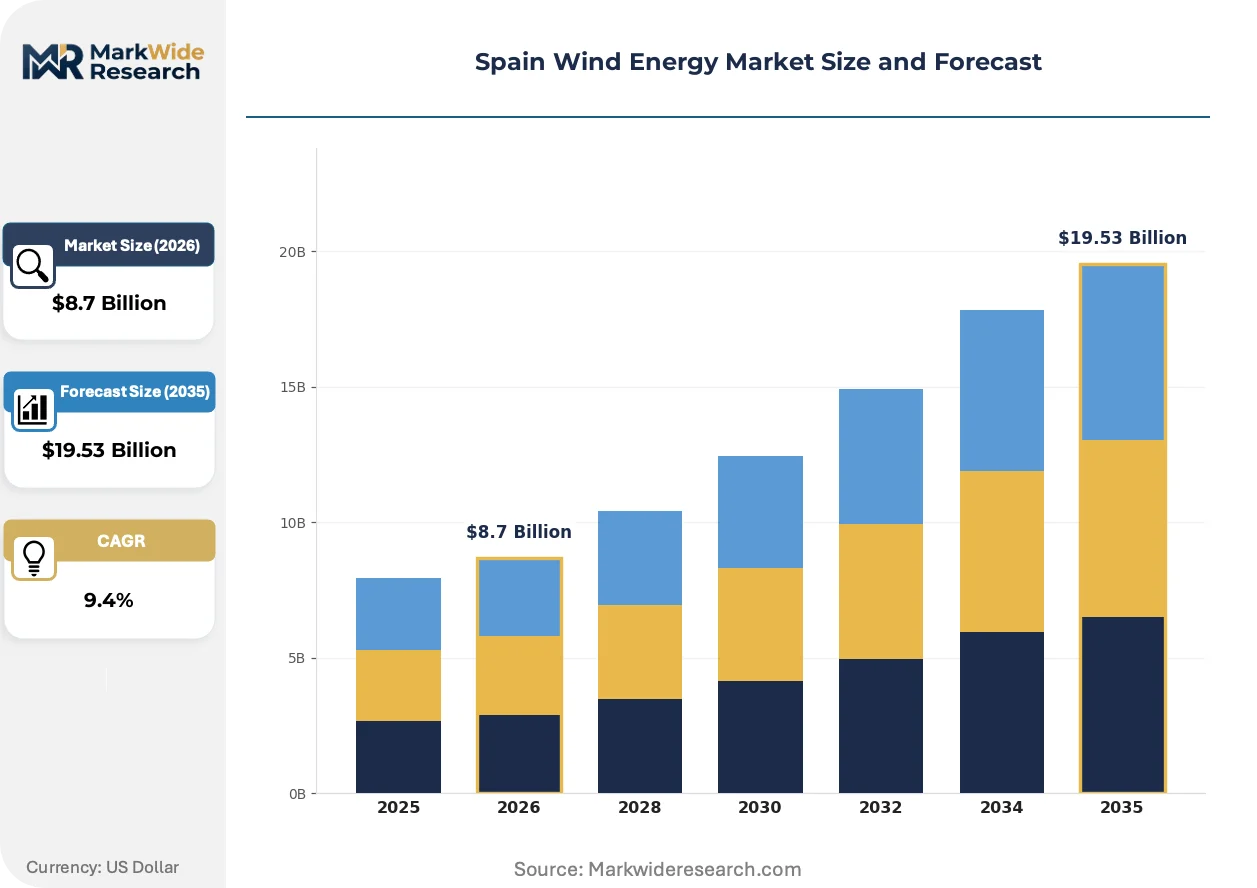
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Component: Turbines, Nacelles, Blades, Generators Application: Power Generation, Grid Integration, Remote Power, Hybrid Systems End User: Utilities, Independent Power Producers, Industrial, Government |
| Companies Covered | Acciona, General Electric, Siemens Gamesa Renewable Energy, EDP Renovables, Naturgy Energy Group, Vestas Wind Systems, Capital Energy, Masdar, Iberdrola, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Wind Energy Market Strategic Shifts
Technology trajectories in Spanish wind energy are converging on larger rotor architectures, deeper water access, and predictive maintenance platforms that reshape competitive differentiation across original equipment and service segments.
Direct-drive permanent magnet generators are eliminating gearbox failure modes and reducing nacelle maintenance requirements. Spanish developers deploying 5MW+ onshore units are specifying these architectures for 25-year design lifecycles. The technology is migrating from offshore niche applications to mainstream onshore procurement specifications as gearbox reliability premiums compress.
Spain's Ministry for the Ecological Transition is enforcing renewable deployment schedules through the National Integrated Energy and Climate Plan that mandate specific annual capacity additions. Industrial consequence includes accelerated environmental impact assessment reforms and consolidated permitting windows. Grid-scale utilities are responding by front-loading project pipelines to secure connection agreements before regulatory deadlines tighten.
Utility offtakers are unbundling turbine supply agreements from long-term service contracts, reversing previous integrated procurement models. Independent service providers are capturing blade inspection and gearbox overhaul work previously captive to OEM networks. This pattern concentrates in Castilla y León and Galicia where mature installed bases exceed 10GW and aftermarket competition intensifies.
Spain Wind Energy Market Segmentation
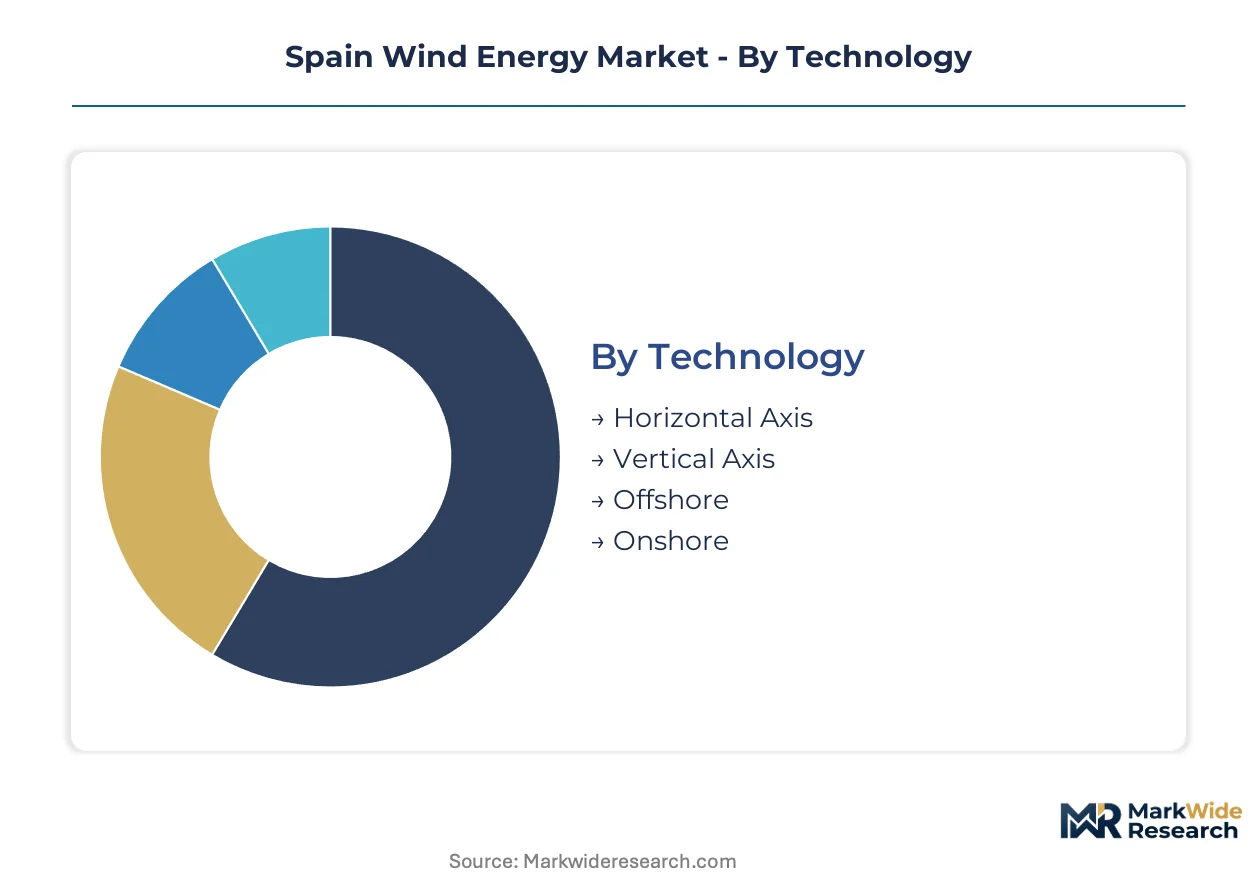
Wind energy market segmentation reveals how technology maturity, component economics, and customer procurement patterns allocate revenue pools across the Spanish value chain. Distinct competitive dynamics govern each dimension, from turbine architecture choices to offtake contracting structures.
Technology:
Maturity spectra separate established onshore deployments from emerging offshore platforms that require fundamentally different foundation engineering.
- Horizontal Axis:Aerodynamic rotor blades mounted on tall towers capture prevailing wind currents through pitch-controlled blade angles. Castilla y León and Galicia concentrate installed capacity where hub heights exceeding 130 meters maximize capacity factors across rolling terrain.
- Onshore:Ground-based installations dominate procurement volumes through standardized civil works and established grid connection protocols. Aragón's expanding project pipeline attracts utility-scale investments seeking lower levelized cost of energy than southern European alternatives.
- Vertical Axis:Omnidirectional rotor designs eliminate yaw mechanisms and reduce mechanical complexity for distributed applications. Limited Spanish deployment concentrates in remote agricultural settings where maintenance access constraints favor simpler architectures.
- Offshore:Floating foundation designs unlock Mediterranean depths beyond 60 meters where fixed-bottom construction proves uneconomical. Canary Islands demonstration zones provide first-mover learning curves before commercial scale-up.
Onshore horizontal configurations retain volume leadership; offshore floating platforms hold the steepest expansion curve as seabed leasing accelerates.
Component:
Cost tier differentiation concentrates margin capture in composite-intensive subsystems versus commoditized electromechanical elements.
- Blades:Advanced carbon fiber and glass-reinforced polymer constructions exceeding 80 meters in length determine aerodynamic efficiency and noise profiles. Siemens Gamesa's blade refurbishment network in northern Spain captures recurring aftermarket revenue through composite repair services.
- Turbines:Integrated rotor-nacelle-tower systems above 5MW rated capacity define project economics through availability guarantees and power curve warranties. Procurement specifications increasingly unbundle supply agreements from long-term service contracts.
- Nacelles:Housing assemblies integrate drivetrain, generator, and power electronics in weather-sealed enclosures. Direct-drive permanent magnet architectures eliminate gearbox failure modes but concentrate rare earth supply risk.
- Generators:Doubly-fed induction and synchronous designs convert mechanical rotation to grid-synchronous electricity. Copper winding specifications and permanent magnet configurations differentiate efficiency ratings across manufacturer portfolios.
Blade systems command premium pricing tiers; turbine integrated packages generate the highest absolute revenue per project.
Application:
Customer type segmentation separates utility-scale procurement from distributed generation models with diverging interconnection requirements.
- Power Generation:Bulk electricity production for wholesale market participation or bilateral offtake agreements. Grid-scale utilities in Castilla y León front-load development pipelines to secure connection agreements before regulatory deadlines tighten.
- Grid Integration:Synchronous generation with voltage regulation and frequency response capabilities for transmission system stability. Red Eléctrica de España mandates grid code compliance that shapes turbine converter specifications and fault-ride-through requirements.
- Hybrid Systems:Co-located battery storage paired with wind generation to firm output profiles and capture capacity market premiums. Aragón green hydrogen hub projects create dedicated offtake streams for electrolyzer-fed industrial demand.
- Remote Power:Off-grid or weak-grid installations supplying isolated industrial facilities or island communities. Canary Islands microgrids demonstrate technical feasibility before mainland regulatory adaptation.
Grid-connected power generation dominates procurement volumes; hybrid storage configurations are gaining share fastest as battery costs decline.
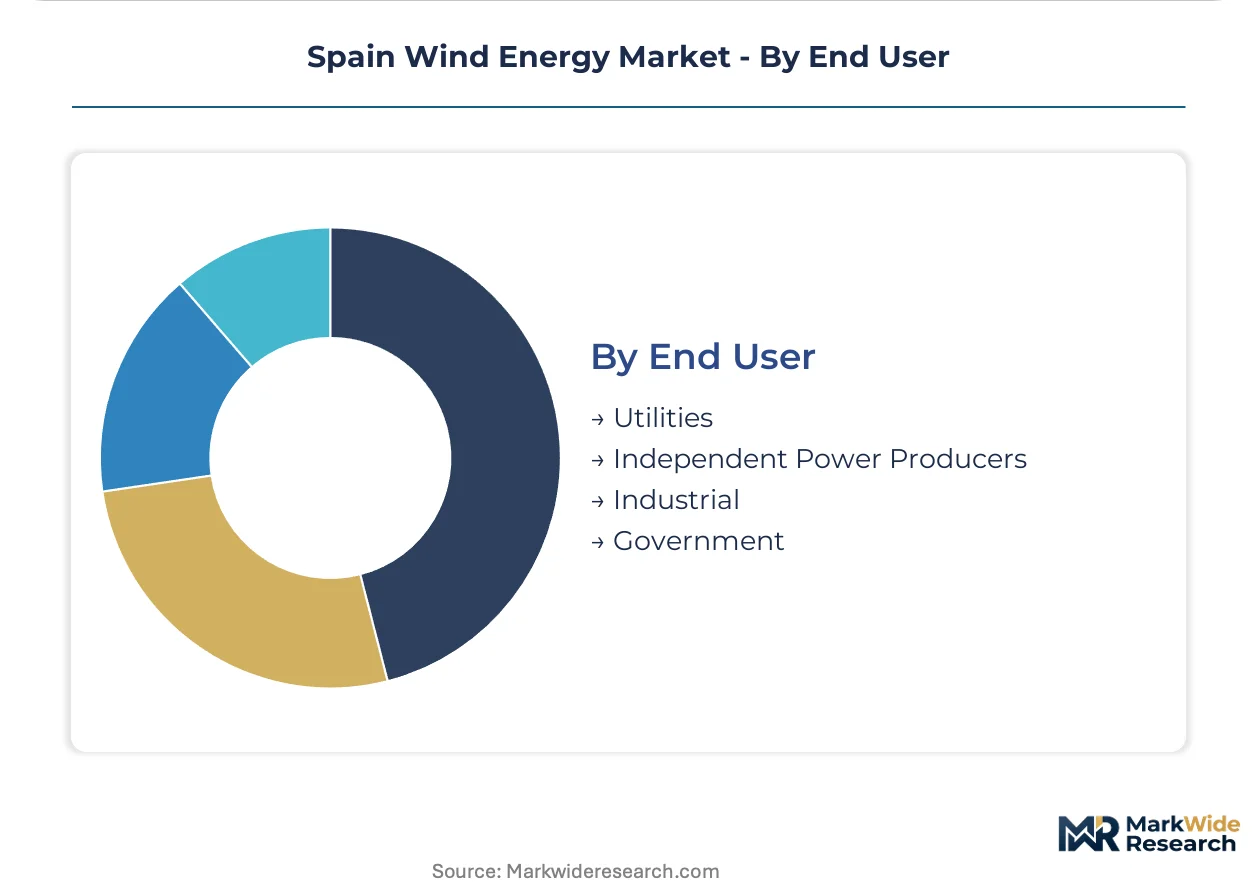
End User:
Volume concentration among integrated utilities contrasts with emerging procurement patterns from industrial self-consumption and public sector tenders.
- Utilities:Vertically integrated electricity suppliers deploying proprietary generation assets for retail portfolio balancing. Iberdrola anchors competitive position through integrated project development and grid connection capabilities across Spanish territories.
- Independent Power Producers:Non-utility developers securing power purchase agreements with corporate offtakers or merchant market exposure. Merchant risk tolerance varies with wholesale price hedging instruments and renewable certificate value capture.
- Industrial:Energy-intensive manufacturers contracting direct renewable supply to meet emissions targets and price stability objectives. Chemical and steel sector procurement concentrates in regions with transmission capacity surplus.
- Government:Public administration tenders for municipal supply, defense installations, and research demonstration projects. Ministry for the Ecological Transition funding mechanisms support early-stage floating offshore pilots.
Utility procurement retains volume leadership; industrial direct contracting shows the steepest expansion trajectory as corporate renewable targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish wind energy capacity concentrates in interior plateau regions and Atlantic coastal zones where terrain and maritime exposure maximize turbine yield. Grid infrastructure investments and seabed leasing frameworks are redrawing competitive positioning across autonomous communities.
Castilla y León
Extensive land availability and consistent wind shear sustain utility-scale project economics across the Meseta Central. The Junta de Castilla y León streamlined environmental impact procedures under regional renewable acceleration decrees. Burgos and Palencia provinces host dense turbine corridors where Iberdrola and EDP Renovables operate multi-gigawatt portfolios.
Aragón
Green hydrogen offtake agreements from chemical and steel sectors are anchoring new wind-to-electrolyzer investments in the Ebro Valley. The regional government Zaragoza administers simplified permitting for renewable-industrial hybrid complexes. Teruel and Zaragoza provinces attract capital seeking lower land costs than northern European alternatives.
Galicia
Atlantic exposure and rugged coastal topography deliver capacity factors exceeding national averages for onshore installations. The Xunta de Galicia enforces landscape integration standards that shape turbine siting and visual impact mitigation. A Coruña and Lugo provinces concentrate operational assets where Vestas Wind Systems maintains blade service networks.
Andalusia
Southern wind corridors and port infrastructure position the region for Mediterranean offshore component staging. The Junta de Andalucía coordinates with Red Eléctrica de España on transmission reinforcement for renewable export capacity. Cádiz and Huelva provinces host emerging floating foundation assembly facilities serving Canary Islands demonstration zones.
Canary Islands
Deep-water bathymetry and isolated grid architecture make the archipelago a testbed for floating offshore technology at commercial scale. The Ministry for the Ecological Transition designates Gran Canaria and Tenerife waters for pilot zone licensing with streamlined marine consenting. Santa Cruz de Tenerife port investments target heavy-lift vessel accommodation for future deployment phases.
Spain Wind Energy Market Competitive Environment
Integrated utilities and specialized turbine suppliers split the market between proprietary development pipelines and equipment-plus-service contracting models. The vendor base concentrates around three strategic archetypes: vertically integrated European energy majors with captive project pipelines, Danish-Spanish turbine OEMs with dominant servicing networks, and Gulf-backed infrastructure investors deploying capital through development partnerships. Competitive intensity is accelerating through unbundled procurement patterns and aftermarket service disintermediation.
Among the integrated utility tier, Iberdrola and Naturgy Energy Group exemplify project development and grid connection capabilities that span multiple Spanish territories. Siemens Gamesa Renewable Energy occupies a distinctive position as a turbine manufacturer with blade refurbishment infrastructure capturing recurring aftermarket revenue. Vestas Wind Systems represents the servicing-specialist archetype through predictive maintenance platforms deployed across mature installed bases in Castilla y León and Galicia.
| Leading Market Players |
|---|
| Acciona |
| General Electric |
| Siemens Gamesa Renewable Energy |
| EDP Renovables |
| Naturgy Energy Group |
| Vestas Wind Systems |
| Capital Energy |
| Masdar |
| Iberdrola |
| Others |
Value Chain & Pricing Dynamics
Rare earth supply concentration in Chinese processing facilities determines both nacelle pricing tier spreads and supply chain configuration for Spanish wind energy. Neodymium and dysprosium dependency creates input cost volatility that compresses margins on direct-drive generator architectures while forcing procurement diversification into doubly-fed induction alternatives.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure through accelerated permitting premiums and cross-border financing access. Three-tier pricing structure across premium, standard, and economy levels separates integrated service bundles from unbundled turbine supply agreements. Cost compression in the standard tier is intensifying because independent service providers are capturing blade refurbishment work previously captive to OEM networks. Industrial offtakers show highest price sensitivity due to merchant risk exposure, while utilities demonstrate lowest sensitivity through captive portfolio balancing.
Supply Chain Analysis
Siemens Gamesa and Vestas manufacturing facilities in Spain and Denmark hold dominant nacelle and blade production capacity for the Iberian market. Component sourcing draws from China for rare earth magnets, Germany for precision bearings, and domestic Spanish facilities for tower steel fabrication. Single-source vulnerability concentrates in heavy-lift installation vessels operated by Northern European marine contractors. Distribution runs through Red Eléctrica de España grid connection queues that extend project commissioning timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's wind energy market functions as a defensive-moat story anchored in regulatory entrenchment. The National Integrated Energy and Climate Plan creates switching costs for developers through mandated deployment schedules and consolidated permitting windows.
For Market Incumbents: Insulate service revenue streams by expanding blade refurbishment networks in Castilla y León and Galicia where mature installed bases exceed critical mass. Deepen backward integration into nacelle assembly to offset rare earth cost volatility. Capture grid connection queue priority through front-loaded project pipelines before regulatory deadlines tighten.
For New Entrants and Emerging Players: Establish a beachhead in the Aragón green hydrogen hub where wind-to-electrolyzer offtake agreements create dedicated demand streams. Target the Canary Islands floating pilot zone for first-mover learning curves before Mediterranean commercial scale-up. Pursue independent service provider positioning to unbundle blade inspection from OEM captive networks.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors integrated project developers with grid connection capabilities. Long-term viability rests on hybrid storage pairing penetration and floating offshore technology maturation. Target acquisition archetypes include regional IPPs with secured interconnection agreements. Quarterly review of Red Eléctrica de España queue clearance rates and seabed leasing round timing is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Offshore Pilot Deployment | Canary Islands demonstration zones unlock Mediterranean deep-water access for commercial scale-up. |
| Hybrid Storage Integration | Co-located battery systems firm output profiles and capture capacity market premiums through Red Eléctrica de España grid services. |
| Blade Refurbishment Network Expansion | EU waste directive compliance creates recurring aftermarket revenue through composite recycling services. |
| Green Hydrogen Offtake Partnerships | Aragón electrolyzer projects anchor industrial demand for new wind capacity with long-term contract certainty. |
| Direct-Drive Generator Architecture Migration | Permanent magnet designs eliminate gearbox failure modes but require rare earth supply chain hedging strategies. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through IEA reports, FERC-style filings with Red Eléctrica de España, project development databases, and customs records. Bottom-up capacity addition modeling triangulated against top-down renewable target allocations from the National Integrated Energy and Climate Plan.
Forecast inputs span technology segmentation by foundation type and turbine rating, application segmentation by grid connection configuration, and end-user segmentation by offtaker risk profile across the projection horizon. CAGRs were derived from capacity deployment schedules, interconnection queue clearance assumptions, and technology cost trajectories. Industry-specific inputs include seabed leasing round timing and hybrid storage pairing adoption curves.
Sensitivities concentrate around permitting reform velocity, rare earth price volatility, and floating platform certification timelines. Forecasts reflect documented assumptions on grid reinforcement investment pacing and EU financing mechanism access. Quarterly review of Red Eléctrica de España interconnection backlogs and Ministry for the Ecological Transition pilot zone licensing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Wind Power Forgings Market