
 Wind Energy Market | 2026-2036
Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Energy Market Analysis
The wind energy sector is pivoting sharply between premium offshore installations with 15+ MW turbines and commoditized onshore units where blade length standardization squeezes margins. Vestas Wind Systems dominates European offshore servicing through backward integration into blade manufacturing. Siemens Gamesa Renewable Energy anchors its position in the Americas via specialized direct-drive generator platforms. Goldwind Science & Technology leverages vertical supply control over rare-earth permanent magnet sourcing to sustain cost leadership in Asian markets.
Wind energy harnesses kinetic airflow through aerodynamic rotor blades—typically 80–120 meters in diameter for utility-scale units—to drive generators producing grid-synchronized electricity at 50 or 60 Hz. The technology displaces fossil thermal generation by delivering zero-combustion power with capacity factors now exceeding 35% for modern onshore installations. Onshore turbines occupy the mature volume tier where OEMs compete on logistics optimization and installation speed. Offshore turbines command premium pricing due to foundation complexity and salt-corrosion engineering requirements. Utility-scale application segments lead absolute megawatt additions while distributed generation segments attract novel financing structures from commercial and industrial off-takers seeking direct power purchase agreements.
FERC interconnection queue reforms in the United States, EU Green Deal auction mechanisms under REPowerEU, and China's dual carbon targets enforced by MEE collectively reshape demand trajectories and equipment certification requirements across major markets. IEC 61400 design standards and ISO 19045 wind measurement protocols govern type certification and bankability assessments that determine project finance access. Stakeholders must monitor evolving floating foundation installation codes and emerging blade recycling mandates as regulatory baselines tighten without grandfathering existing assets.
Market Dynamics
Floating platform engineering is compressing foundation costs for deep-water installations while auction mechanisms in Germany, China, and the United States compress developer margins and accelerate equipment standardization timelines.
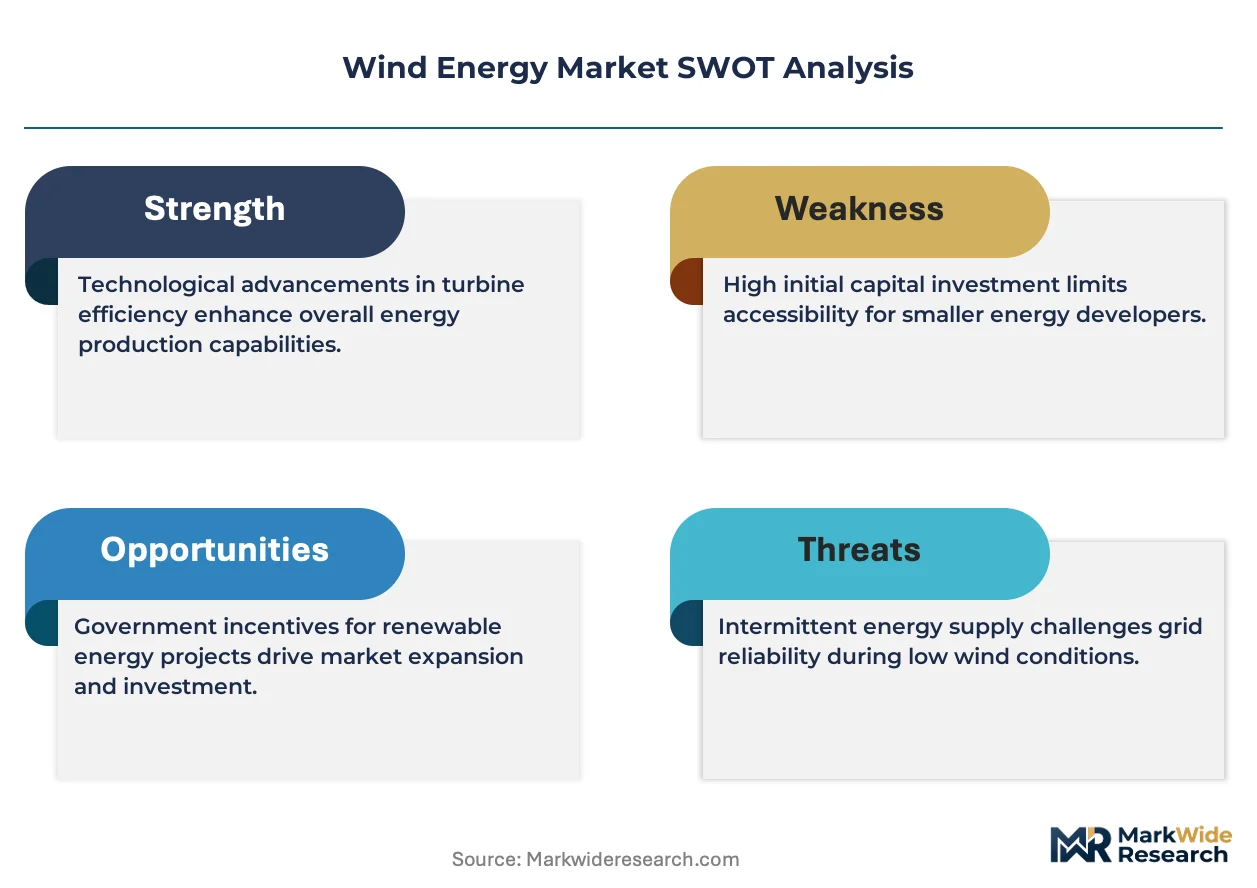
Growth Catalysts
- REPowerEU Auction Mechanisms:The EU Green Deal's competitive bidding frameworks in Germany and Denmark are accelerating offshore project pipelines by compressing permitting timelines and mandating technology-neutral cost benchmarks.
- China's Dual Carbon Targets:MEE enforcement of carbon intensity caps is forcing provincial grid operators to prioritize wind procurement over coal thermal, creating guaranteed offtake channels for utility-scale developers.
- Floating Foundation Technology:Semi-submersible and tension-leg platform designs are unlocking water depths beyond 60 meters, expanding addressable seabed area for developers in Portugal and Japan.
Market Restraints
- Rare-Earth Magnet Concentration:Neodymium and dysprosium supply chains concentrate in Chinese processing facilities, exposing direct-drive generator OEMs to input cost volatility and export quota uncertainty.
- IEC 61400 Certification Friction:Type certification timelines for 15+ MW offshore units now exceed 18 months, delaying project financial close and compressing developer working capital cycles.
- Grid Interconnection Queues:FERC queue reform implementation lags in Texas and California ISO territories, stranding permitted capacity and inflating carrying costs for pre-construction assets.
Strategic Opportunities
- Brazil's Underpenetrated Northeast Corridor:Ceará and Rio Grande do Norte states offer 8+ meter-per-second wind regimes with nascent offshore regulatory frameworks and limited incumbent supplier presence.
- Blade Recycling Mandates:Emerging EU end-of-life regulations for thermoset composites are creating first-mover advantages for OEMs with in-house pyrolysis or mechanical recycling capabilities.
- Direct Power Purchase Agreements:C&I off-takers in Germany and the United States are bypassing utility intermediaries, creating new financing structures for distributed generation portfolios under 50 MW.
Industry Challenges
- Installation Vessel Scarcity:Heavy-lift jack-up vessel availability for 12+ MW turbine components constrains annual offshore deployment capacity in the North Sea and Baltic markets.
- Grid Synchronization Complexity:Inverter-based resource integration with legacy synchronous generation requires advanced grid-forming controls, stretching utility engineering capabilities and certification timelines.
- Composite Repair Technician Shortage:Blade damage assessment and structural repair expertise concentrates in Vestas and Siemens Gamesa service networks, limiting third-party maintenance market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Energy Market |
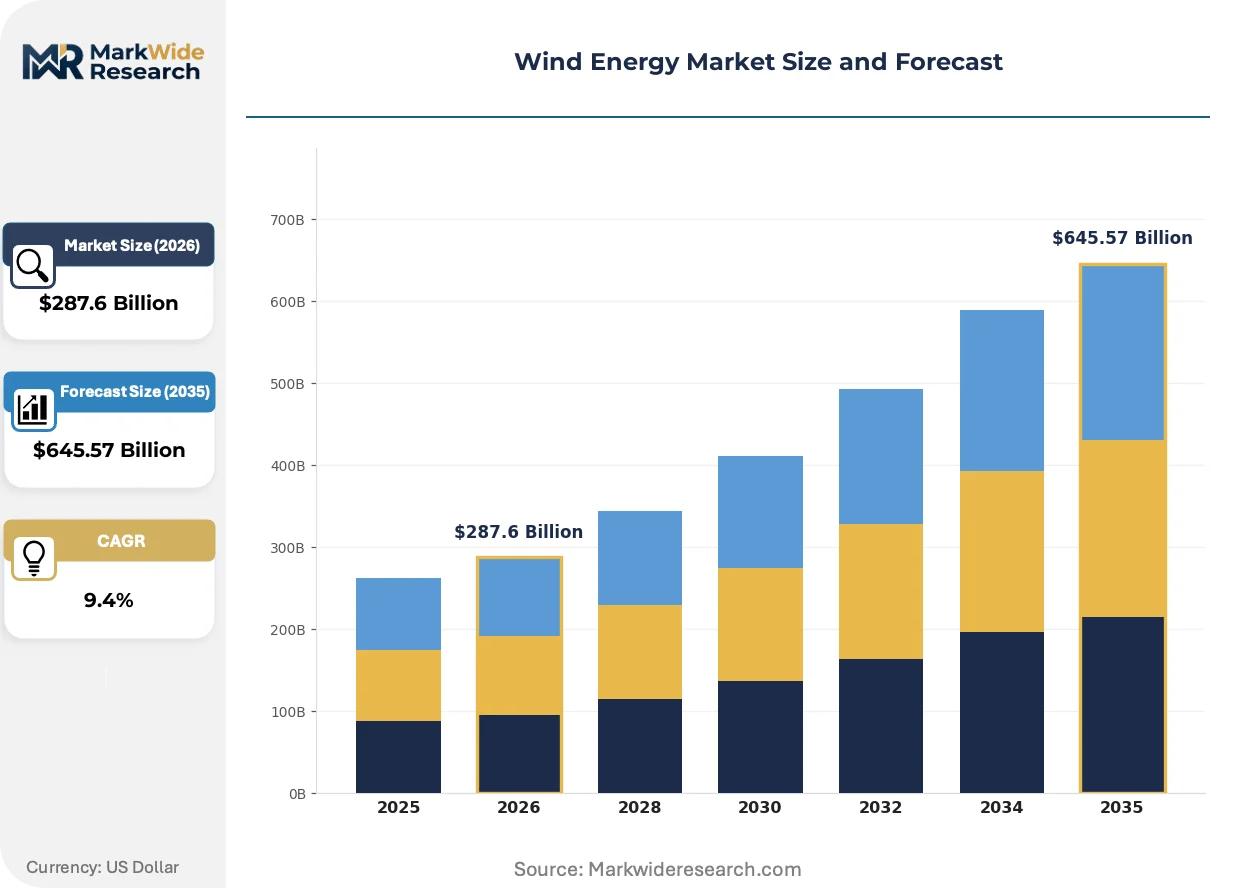
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $645.57 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore Turbines, Offshore Turbines, Horizontal Axis, Vertical Axis Application: Utility Scale, Distributed Generation, Hybrid Systems, Offshore Farms End User: Industrial Sector, Residential Sector, Government, Energy Providers Installation: Ground Mounted, Floating, Fixed Foundation, Integrated Systems |
| Companies Covered | Vestas Wind Systems, Siemens Gamesa Renewable Energy, GE Renewable Energy, Goldwind Science & Technology, Envision Energy, NextEra Energy, Suzlon Energy, Nordex SE, Mingyang Smart Energy Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Energy Market Emerging Trajectories
Aerodynamic control systems and modular drivetrain architectures are compressing levelized cost trajectories while regulatory mandates force circularity investments and procurement models fragment across utility and corporate channels.
Segmented blade designs using carbon fiber spar caps are electrifying logistics economics for 100+ meter rotors. Vestas and Goldwind are deploying split-blade configurations that enable standard truck transport without specialized escort vehicles. This technology is electrifying remote site accessibility and reducing port-side assembly bottlenecks for onshore projects in mountainous terrain.
The EU Green Deal's REPowerEU acceleration framework is tightening auction price ceilings and mandating supply-chain disclosure requirements. Developers in Germany and Denmark must now document embodied carbon and circularity plans to qualify for contract-for-difference awards. Offshore segments face compressed bidding timelines while onshore projects absorb additional compliance overhead.
Corporate offtakers are unbundling energy attribute certificates from physical power delivery, creating synthetic PPA structures that separate price hedging from renewable energy claims. This model disrupts traditional utility intermediation in Texas ERCOT and PJM territories. Data center operators in Virginia and hyperscale cloud providers in Frankfurt drive this behavioral shift.
Wind Energy Market Segmentation
Wind energy market segmentation reveals distinct certification pathways and capital intensity profiles that shape equipment procurement strategies. Technology and installation type determine whether projects face IEC 61400 type certification or maritime foundation codes, directly impacting development timelines and financing structures.
Technology:
IEC 61400 governs type certification for all turbine classes, though offshore units above 12 MW now face extended 18-month certification cycles that delay financial close. Horizontal axis designs dominate bankability assessments, while vertical axis configurations encounter limited certification precedent.
- Onshore Turbines:Horizontal-axis units with 80–120 meter rotors and geared drivetrains deliver capacity factors exceeding 35% in high-resource corridors. Demand concentrates in China's Inner Mongolia and Texas ERCOT territories where grid interconnection reforms accelerate deployment. OEMs compete on blade logistics optimization and installation speed.
- Offshore Turbines:15+ MW direct-drive units with permanent magnet generators require salt-corrosion engineering and advanced grid-forming controls. Procurement clusters in Germany's North Sea lease areas and China's Jiangsu province where floating foundation trials expand addressable water depths. Extended certification timelines compress developer working capital cycles.
- Horizontal Axis:Aerodynamic rotor designs with three blades dominate utility-scale installations across all geographies.
- Vertical Axis:Darrieus and Savonius configurations serve niche distributed applications with limited type certification precedent.
Onshore Turbines sits at the top of the volume ranking, with Offshore Turbines climbing the fastest.
Application:
Cost tier differentiation separates utility-scale projects with billion-dollar capital stacks from distributed generation portfolios under 50 MW that attract corporate PPA structures. Auction mechanisms in Germany and contract-for-difference frameworks in the UK reshape procurement economics across tiers.
- Utility Scale:Grid-connected installations exceeding 100 MW require transmission-level interconnection and synchronous generation integration. Deployment concentrates in China's Gansu and Xinjiang provinces where MEE carbon intensity enforcement guarantees offtake. FERC queue reforms in Texas and California ISO territories determine project viability.
- Distributed Generation:Sub-50 MW installations serving C&I off-takers bypass utility intermediaries through synthetic PPA structures. Demand clusters in Virginia data center corridors and Frankfurt hyperscale cloud facilities where energy attribute certificates unbundle from physical delivery.
- Hybrid Systems:Wind-plus-storage or wind-plus-solar configurations co-optimize capacity value in ERCOT and PJM markets.
- Offshore Farms:Dedicated maritime installations in Denmark's Kriegers Flak and US Atlantic lease areas command premium foundation costs.
Utility Scale maintains absolute megawatt leadership, though Distributed Generation gains share fastest through corporate procurement restructuring.
End User:
Customer type determines financing channel access and offtake security, with energy providers leveraging regulated rate bases while industrial off-takers negotiate direct contracts.
- Industrial Sector:Manufacturing and data center operators in Germany's Rhine-Ruhr corridor and Virginia's Loudoun County procure renewable energy through synthetic PPAs that separate price hedging from REC claims.
- Residential Sector:Small-scale distributed installations face interconnection queue bottlenecks in California and Hawaii territories.
- Government:Federal and state procurement mandates in the US and EU Green Deal auction participation drive public sector demand.
- Energy Providers:Regulated utilities in China's State Grid service areas and Germany's RWE/EnBW portfolios deploy capital through guaranteed return mechanisms.
Energy Providers dominate installed capacity, with Industrial Sector expanding most quickly through corporate sustainability commitments.
Installation:
Foundation type dictates supply chain configuration and vessel requirements, with floating platforms unlocking deep-water frontiers while fixed foundations mature in shallower territories.
- Ground Mounted:Concrete pad and anchor bolt installations for onshore turbines dominate volume deployment across China's northern provinces and the US Great Plains. Standardized civil works and crane logistics compress construction schedules in flat terrain corridors.
- Floating:Semi-submersible and tension-leg platform designs enable 60+ meter water depths in Portugal's WindFloat Atlantic and Japan's Fukushima forward area. Heavy-lift vessel scarcity constrains annual deployment capacity in emerging markets.
- Fixed Foundation:Monopile and jacket structures anchor offshore turbines in Germany's North Sea and China's Jiangsu intertidal zones.
- Integrated Systems:Pre-assembled turbine-and-foundation packages reduce port-side assembly bottlenecks for remote onshore projects.
Ground Mounted commands the largest installed base, with Floating platforms showing the steepest expansion trajectory as deep-water regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Denmark's offshore wind corridor anchor European project development, while Chinese manufacturing workforces dominate turbine component fabrication across coastal provinces.
United States
Texas ERCOT and PJM grid operators drive utility-scale procurement through corporate PPA demand from Virginia data centers. FERC interconnection queue reforms in California ISO territories accelerate pre-construction timelines. The Atlantic coast from Massachusetts to Virginia hosts offshore lease areas where floating foundation trials expand addressable depths.
China
Provincial grid operators in Gansu and Xinjiang prioritize wind procurement over coal thermal under MEE carbon intensity enforcement. Jiangsu province anchors offshore deployment with intertidal fixed foundations and deep-water floating trials. Inner Mongolia corridors concentrate onshore manufacturing and installation activity.
Germany
REPowerEU auction mechanisms in the North Sea and Baltic lease areas compress developer margins while mandating supply-chain disclosure. RWE and EnBW portfolios deploy capital through regulated return mechanisms. The Kriegers Flak cluster exemplifies multi-gigawatt offshore coordination across Danish waters.
Brazil
Ceará and Rio Grande do Norte states offer 8+ meter-per-second wind regimes with nascent offshore regulatory frameworks. Limited incumbent supplier presence creates entry opportunities for foreign OEMs. The Northeast corridor attracts distributed generation investment from commercial and industrial off-takers.
Japan
METI floating foundation codes enable 60+ meter water depths in the Fukushima forward area and Goto Islands. Heavy-lift vessel scarcity constrains annual deployment capacity. Domestic consortiums partner with European technology providers to localize semi-submersible platform fabrication.
Wind Energy Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across turbine supply chains. Vestas Wind Systems and Siemens Gamesa Renewable Energy anchor European offshore servicing through captive blade manufacturing, while Goldwind Science & Technology leverages upstream control over rare-earth magnet sourcing. The market structures around three archetypes: integrated OEMs with full drivetrain capabilities, component specialists focused on generators or blades, and project developers with in-house EPC functions. Consolidation pressure favors M&A between turbine manufacturers and foundation engineering firms, while geographic expansion into Brazil and Japan accelerates through licensing partnerships.
Among Danish and Spanish integrated OEMs, Vestas Wind Systems and Siemens Gamesa Renewable Energy exemplify the full-service archetype spanning onshore and offshore segments. Goldwind Science & Technology anchors the Chinese tier with vertical supply control. GE Renewable Energy occupies a position bridging American utility relationships with European offshore technology licensing. These three represent distinct competitive vectors: European servicing integration, Asian cost leadership through material control, and transatlantic project finance access.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| GE Renewable Energy |
| Goldwind Science & Technology |
| Envision Energy |
| NextEra Energy |
| Suzlon Energy |
| Nordex SE |
| Mingyang Smart Energy Group |
| Others |
Supply Flow & Price Mechanics
Utility-scale developers in Germany and China's provincial grid systems anchor procurement volume, forcing OEMs toward contract-for-difference structures that bundle turbine supply with long-term service agreements. This buyer concentration compresses upfront equipment margins while shifting value capture to aftermarket servicing and availability guarantees.
Pricing Analysis
Bundled full-service agreements dominate offshore procurement, while unbundled equipment-only sales persist in commoditized onshore segments. Price differentiation rests on IEC 61400 certification tier and geographic delivery complexity, with salt-corrosion engineering premiums attaching to North Sea deployments. Cost compression in onshore units intensifies as blade length standardization erodes manufacturer leverage. Distributed generation portfolios under 50 MW exhibit highest price sensitivity due to limited balance-sheet capacity.
Supply Chain Analysis
Freight economics for 80+ meter blades dominate landed cost calculations, driving segmented designs that enable standard truck transport. Rare-earth magnet processing concentrates in China, while nacelle assembly clusters in Denmark and Spain. Supply chains draw from German gearbox specialists and Japanese bearing manufacturers. Single-source vulnerability in neodymium refining exposes direct-drive generator OEMs to export quota disruptions. Distribution runs through captive service networks controlled by Vestas and Siemens Gamesa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FERC interconnection reforms and REPowerEU auction mechanisms continuously reset demand trajectories and equipment certification requirements.
For Market Incumbents: Hedge against rare-earth magnet volatility through backward integration into permanent magnet recycling or alternative drivetrain architectures. Secure heavy-lift vessel access via joint ventures with marine contractors to defend offshore installation schedules against capacity constraints. Prioritize blade pyrolysis capabilities ahead of EU end-of-life mandates. For New Entrants and Emerging Players: Capture share in Brazil's Northeast corridor where Ceará and Rio Grande do Norte wind regimes exceed 8 meters per second with limited incumbent service infrastructure. Target floating foundation engineering partnerships in Japan's Fukushima forward area where METI codes enable 60+ meter depths. Lead with integrated EPC offerings that compress development timelines for first-mover utility relationships. For Investors and Strategic Acquirers: European utilities with regulated return mechanisms are the most active acquirer in this space, consolidating project pipelines to secure offtake visibility. Five-to-ten-year viability hinges on grid interconnection queue resolution velocity. Monitor FERC implementation progress in Texas and California ISO territories as the signal for stranded capacity release and developer working capital recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Technology Licensing | Unlocks 60+ meter water depths in Portugal's WindFloat Atlantic and Japan's Goto Islands. |
| Blade Recycling Infrastructure Buildout | Positions OEMs ahead of EU thermoset composite end-of-life regulations. |
| Direct Power Purchase Agreement Structuring | Bypasses utility intermediaries for Virginia data center and Frankfurt hyperscale demand. |
| Grid-Forming Control Certification Investment | Addresses inverter-based resource integration complexity in ERCOT and PJM territories. |
| Heavy-Lift Vessel Joint Venture | Secures installation capacity for 15+ MW offshore turbines in North Sea lease areas. |
Methodological Framework
Bottom-up utility procurement modeling reconciled against top-down turbine manufacturing tracking forms the analytical core. Primary interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators combine with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Cross-referencing OEM order backlogs against interconnection queue data ensures demand-side triangulation.
Historical trendline analysis across installed capacity trajectories informs projection frameworks. Segmentation models incorporate technology type, installation foundation, project scale tier, and regional regulatory framework. CAGRs derive from equipment cost curve analysis and auction price ceiling trends. Forecast inputs include floating platform deployment schedules and blade recycling mandate implementation timelines.
Policy reversals, rare-earth export quota shocks, and grid interconnection reform delays are the dominant revision risks. Forecasts reflect assumptions regarding MEE carbon intensity enforcement continuity and REPowerEU funding allocation stability. A model refresh is warranted upon material change in FERC queue processing velocity or IEC 61400 certification timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Global Wind Turbine Operations Market