
 Airborne Wind Turbines Market | 2026-2036
Airborne Wind Turbines Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Wind Turbines Market Outlook
European aerostat manufacturers is expanding production capacity for tethered lifting platforms rated above 200 kW. Altaeros Energies leverages its buoyant airborne turbine architecture to anchor utility-scale deployments in remote grid locations. SkySails Power competes through its ship-kite heritage, while Makani Power sustains R&D intensity on rigid-wing autonomous systems despite Google's parent company winding down commercial operations.
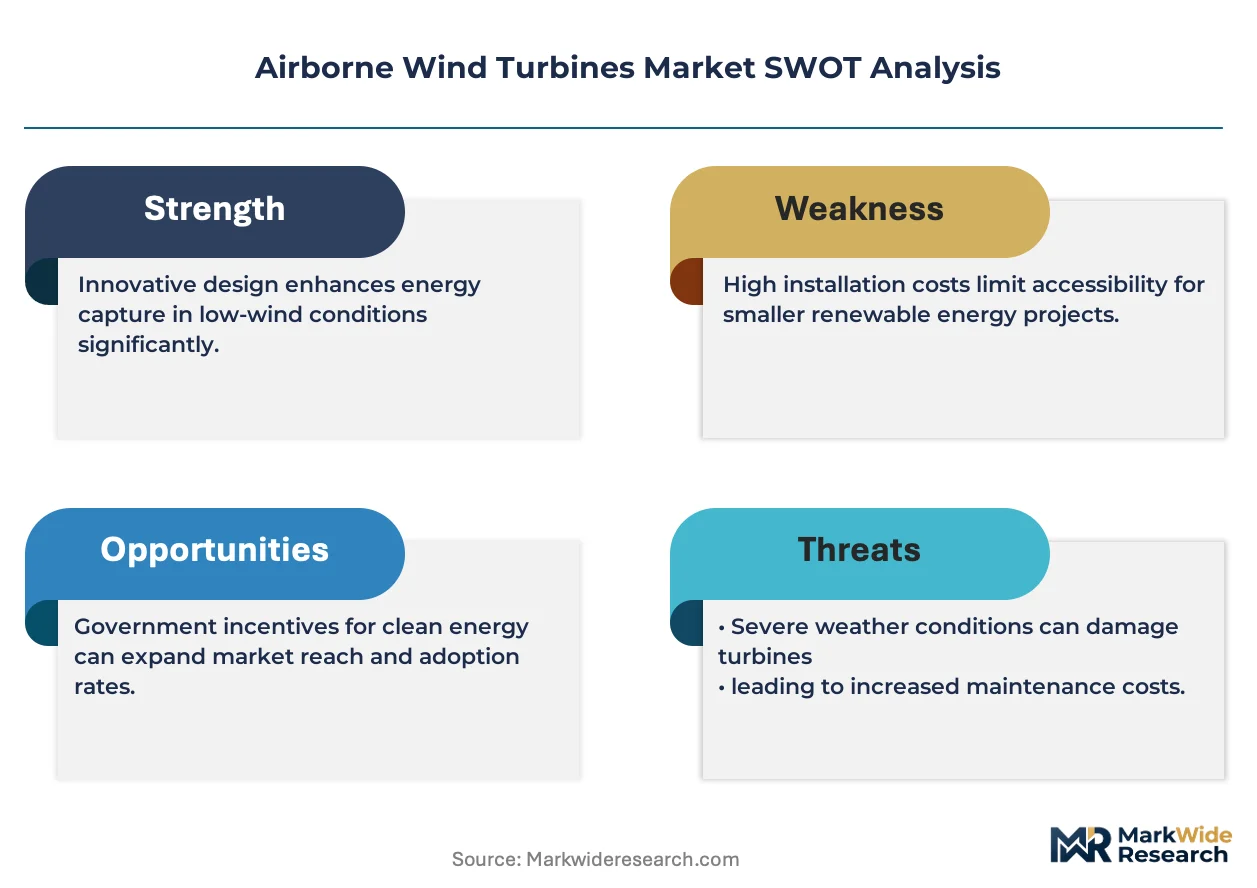
Airborne wind turbines harvest wind energy using tethered flying structures—kites, rigid wings, or aerostats—operating at altitudes of 200 to 800 meters where wind speeds exceed surface-level resources by 30 to 100 percent. These systems convert aerodynamic lift into mechanical or electrical power transmitted through conductive tethers to ground stations, serving off-grid industrial sites and coastal utilities seeking capacity without tower foundations. Autonomous systems lead technology development due to reduced crew requirements and 24-hour operational windows, while offshore deployment commands premium project economics despite higher tether maintenance complexity. Small and medium scale capacity segments dominate current installations, though mega-scale prototypes from European developers signal a structural shift toward utility-class output.
The Federal Aviation Administration in the United States imposes altitude and airspace coordination rules that constrain operational windows for tethered systems above 150 meters. EASA in Europe and the UK's Civil Aviation Authority enforce analogous frameworks, with the EU AI Act adding algorithmic transparency requirements for autonomous flight control systems. Stakeholders must monitor evolving aviation authority positions on beyond-visual-line-of-sight operations, as these determinations will dictate where commercial fleets achieve sustained deployment without restrictive waivers.
Market Dynamics
Autonomous flight control systems are compressing operational costs for airborne wind turbine operators while EU Green Deal implementation accelerates permitting harmonization across member states. This dual pressure is restructuring competitive positioning toward technology-integrated solution providers.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating demand for buoyant lifting platforms using alternative lift gases in German and Norwegian demonstration zones.
- Offshore energy platforms:Oil and gas decommissioning budgets are redirecting toward hybrid renewable microgrids where tethered systems provide baseload without seabed foundations.
- Conductive tether materials:High-strength carbon fiber composites with embedded power transmission are extending operational altitude ceilings and reducing conductor weight penalties.
Market Restraints
- Helium supply concentration:Qatar and the United States control over 80 percent of global helium extraction, creating input cost volatility for aerostat-dependent architectures.
- FAA altitude waivers:Case-by-case approvals for beyond-visual-line-of-sight operations above 150 meters impose timeline uncertainty and geographic deployment restrictions.
- Fixed-bottom offshore wind:Mature turbine technology with established supply chains and financing mechanisms competes directly for coastal utility procurement budgets.
Strategic Opportunities
- United Kingdom island communities:Orkney and Shetland grid isolation creates premium pricing environments for autonomous airborne systems displacing diesel generation.
- EU AI Act compliance services:Algorithmic transparency requirements for autonomous flight control are opening advisory and certification revenue streams for engineering consultancies.
- Ship-kite retrofit integration:Maritime freight operators are evaluating airborne wind assist for existing vessel fleets, extending technology heritage into parallel mobility applications.
Industry Challenges
- Aviation authority coordination:Multi-jurisdictional airspace classification disputes between civil and military controllers delay operational certificate issuance.
- Tether fatigue certification:Cyclic loading standards for conductive cables operating across 200 to 800 meter altitude ranges remain underdeveloped, extending prototype validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Wind Turbines Market |
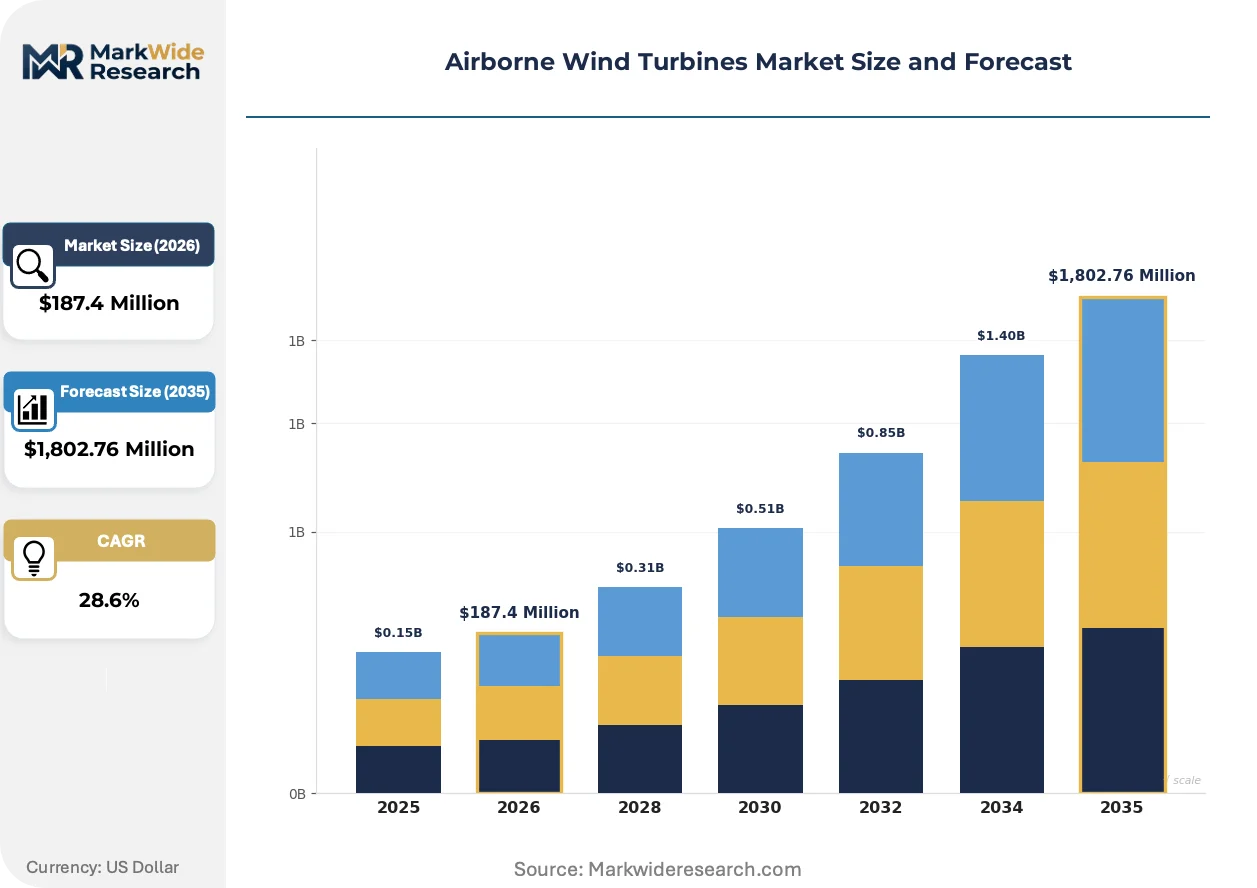
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: HAWT, VAWT, Hybrid Systems, Autonomous Systems Deployment: Onshore, Offshore, Urban Areas, Rural Areas End User: Utilities, Oil & Gas, Telecommunications, Research Institutions Capacity: Small Scale, Medium Scale, Large Scale, Mega Scale |
| Companies Covered | Kite X, KitGen, Altaeros Energies, SkySails Power, Makani Power, Kitepower, Brainwhere, AMPYX Power, E-kite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Wind Turbines Market Strategic Shifts
Distributed sensing and predictive maintenance architectures are reshaping how airborne wind turbine operators manage asset uptime across remote deployment locations. This shift is compressing the traditional reactive service model.
Rigid-wing autonomous systems are absorbing ground station complexity through onboard power generation and stabilized flight control algorithms. Remote mining camps in Australia and Canada are piloting these configurations to reduce crew transport costs. The technology is absorbing capital that previously flowed to conventional tower-mounted microgrids.
The EU AI Act's algorithmic transparency mandates are forcing airborne wind turbine developers to document decision pathways for autonomous flight control systems. EASA implementation guidance requires explainable AI architectures for beyond-visual-line-of-sight certifications. Developers in Germany and Norway are restructuring software stacks to meet documentation burdens before 2026 enforcement deadlines.
Industrial offtakers are consolidating procurement decisions through integrated energy service contracts rather than equipment purchase agreements. Mining and remote processing facilities in Scandinavia now specify guaranteed availability metrics over capital expenditure minimization. This preference shift favors vendors with captive maintenance networks over pure technology licensors.
Airborne Wind Turbines Market Segmentation
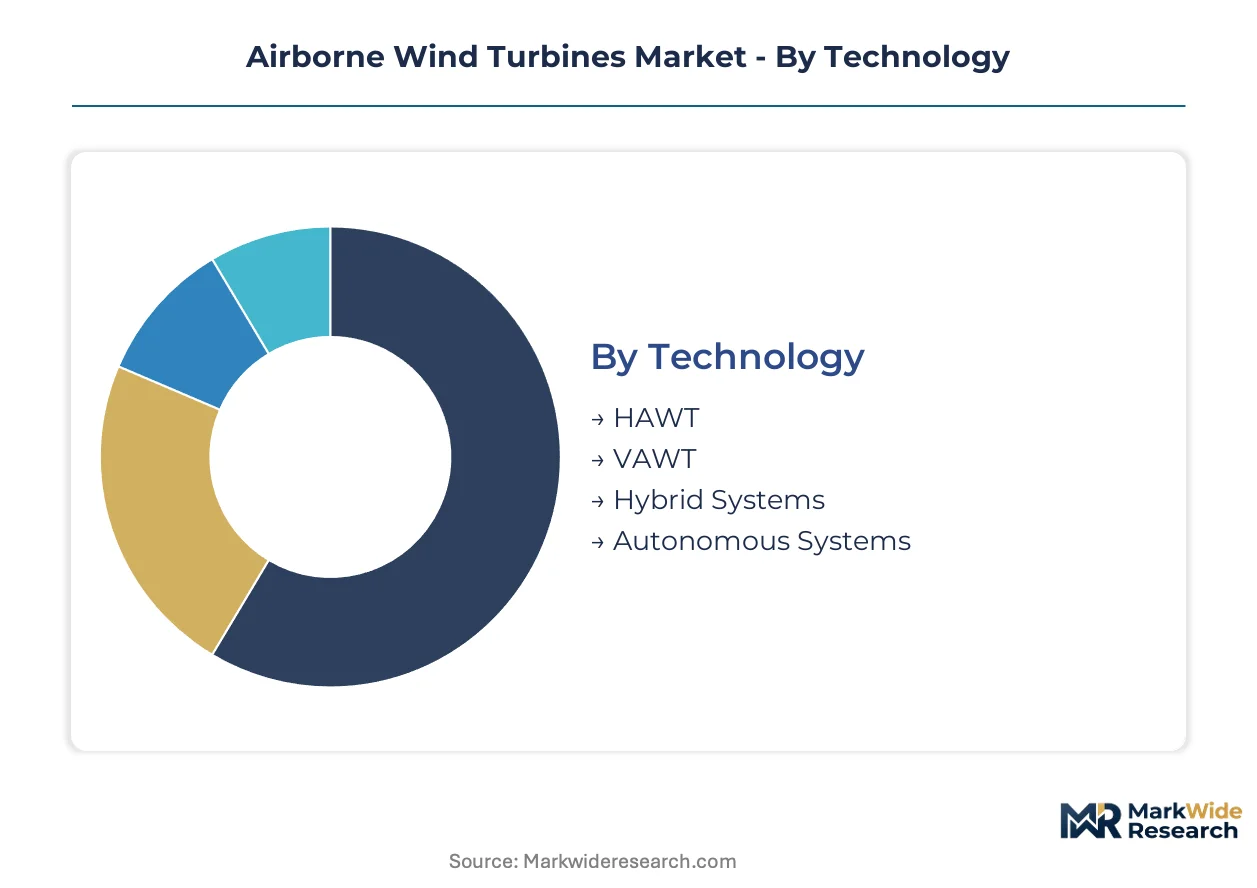
Segmentation in airborne wind turbines distinguishes between tethered aerostats, rigid-wing kites, and autonomous flight architectures. Each technology pathway carries distinct altitude ceilings, power conversion mechanisms, and regulatory compliance burdens that reshape procurement economics across deployment environments.
Technology:
Integration depth separates standalone ground-generation systems from airborne platforms with onboard power conversion and conductive tether transmission.
- Autonomous Systems:Rigid-wing or soft-kite platforms with algorithmic flight control eliminate crew requirements for launch and retrieval. Mining camps in Australia and remote grid installations in Canada prioritize these configurations for 24-hour operational windows without on-site technicians.
- Hybrid Systems:Architectures combining buoyant lift with aerodynamic surfaces reduce helium dependence while maintaining altitude stability. Norwegian and German demonstration zones under EU F-Gas Regulation phasedown are accelerating procurement of these lift-gas alternatives.
- HAWT:Horizontal-axis designs adapted from conventional tower-mounted turbines for tethered airborne deployment.
- VAWT:Vertical-axis configurations offering omnidirectional wind capture without yaw mechanisms.
Volume placements concentrate in Autonomous Systems; the faster expansion belongs to Hybrid Systems.
Deployment:
Cost tier stratification separates premium offshore installations from standardized onshore and distributed rural configurations.
- Offshore:Deployments above coastal waters or decommissioned oil platforms command premium project economics due to higher wind shear and absence of land-use constraints. Oil and gas operators redirecting decommissioning budgets toward hybrid renewable microgrids in the North Sea drive specialized demand.
- Onshore:Ground-based installations in open terrain offer the lowest barrier to entry for early commercial deployments. FAA altitude waivers above 150 meters constrain operational windows in the United States, while EASA frameworks in Europe permit more flexible corridor arrangements.
- Rural Areas:Agricultural and remote industrial sites with limited grid interconnection.
- Urban Areas:Restricted airspace and population density limit applicability to specialized demonstration projects.
Revenue concentration sits with Offshore deployments; Onshore configurations are climbing the fastest as waiver frameworks mature.
End User:
Customer type segmentation distinguishes procurement sophistication between integrated energy service contracts and direct equipment acquisition.
- Oil & Gas:Offshore platform operators and remote production facilities specify guaranteed availability metrics over capital expenditure minimization. Decommissioning budget redirection in the North Sea and Gulf of Mexico creates immediate addressable demand for baseload displacement without seabed foundations.
- Utilities:Coastal and island grid operators in the United Kingdom evaluate airborne systems for capacity augmentation where conventional offshore fixed-bottom wind faces supply chain bottlenecks.
- Telecommunications:Remote tower powering and backup generation for off-grid communication infrastructure.
- Research Institutions:Demonstration project hosts and technology validation partners.
Contract value concentrates in Oil & Gas; Utilities represent the steepest expansion trajectory as grid interconnection trials advance.
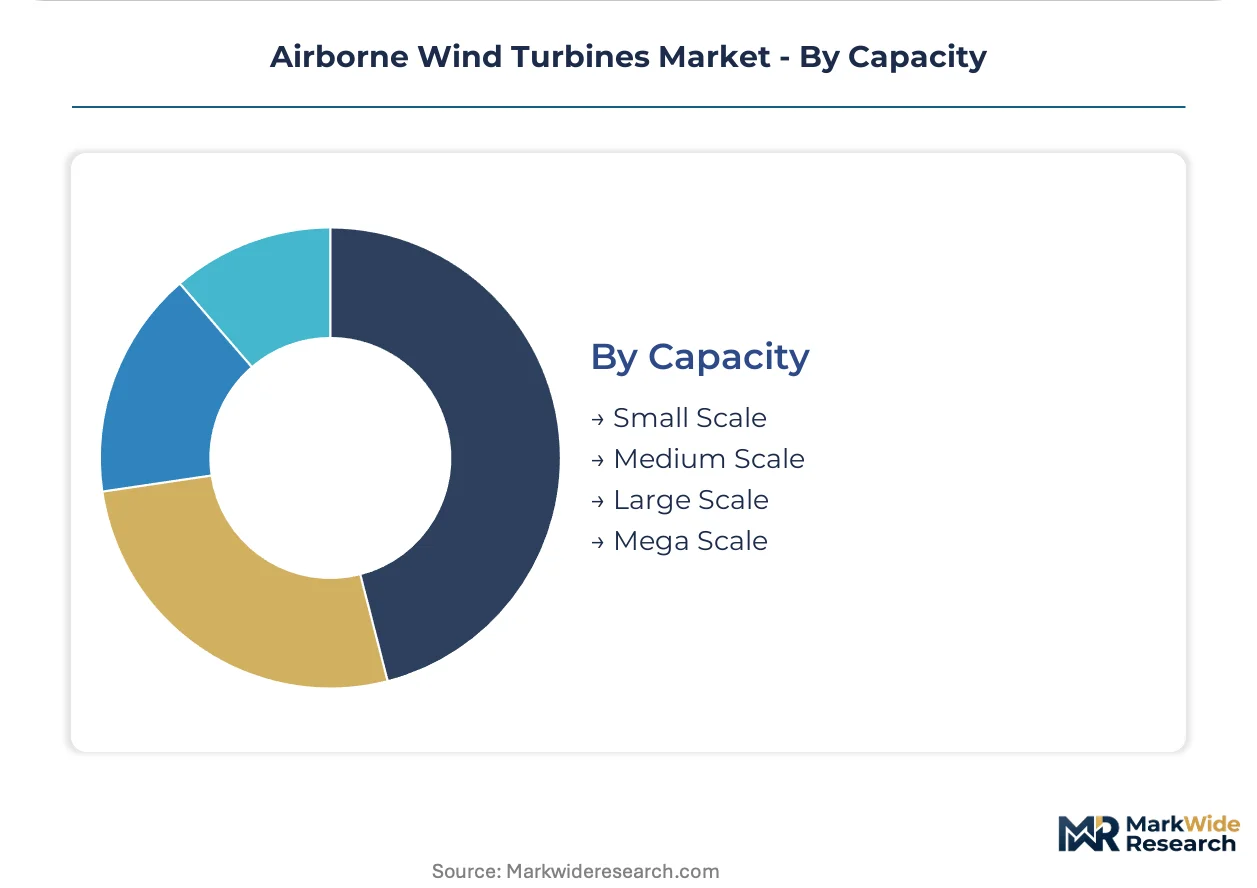
Capacity:
Maturity segmentation tracks the technology transition from pilot-scale validation toward utility-class output certification.
- Small Scale:Systems below 100 kW dominate current operational installations, serving remote telecommunications towers and isolated mining equipment. These configurations absorb capital that previously flowed to diesel microgrids in Australian and Canadian resource extraction zones.
- Medium Scale:100-500 kW platforms bridge demonstration and early commercial deployment, with European developers expanding production capacity for tethered lifting platforms rated above 200 kW.
- Large Scale:500 kW-2 MW systems approaching conventional distributed generation output thresholds.
- Mega Scale:Prototypes exceeding 2 MW signal structural shift toward utility-class output, with European developers leading hardware validation.
Installed base concentrates in Small Scale; Mega Scale prototypes are gaining share fastest as tether fatigue certification standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction concentration in Qatar and the United States shapes deployment economics for aerostat-dependent architectures across key demonstration zones. Germany, Norway, and the United Kingdom anchor European adoption through coordinated aviation authority frameworks and decommissioning budget redirection.
United States
Remote mining camps in Nevada and Arizona drive autonomous system demand for diesel displacement. FAA altitude waivers above 150 meters constrain operational windows, though case-by-case approvals advance in Alaska for isolated grid applications. Greater Boston hosts tether fatigue research partnerships between composite manufacturers and federal laboratories.
Germany
EU F-Gas Regulation phasedown accelerates procurement of hybrid lift-gas alternatives in North Rhine-Westphalia demonstration corridors. EASA implementation guidance on algorithmic transparency reshapes software documentation requirements for autonomous flight control. Hamburg engineering consultancies expand EU AI Act compliance advisory services ahead of 2026 deadlines.
Norway
North Sea oil and gas decommissioning budgets redirect toward hybrid renewable microgrids without seabed foundations. Norwegian aviation authorities coordinate with military controllers on multi-jurisdictional airspace classification for offshore corridors. Stavanger energy service clusters integrate airborne wind into integrated availability contracts.
United Kingdom
Orkney and Shetland grid isolation creates premium pricing environments for autonomous systems displacing diesel generation. The Civil Aviation Authority enforces frameworks analogous to EASA for beyond-visual-line-of-sight operations. Scottish Highlands host conductive tether validation trials for 200-800 meter altitude ranges.
Canada
Remote resource extraction zones in British Columbia and Alberta absorb capital previously flowing to diesel microgrids. Transport Canada aviation regulations govern tethered system deployments above 150 meters with coordination requirements for northern territories. Toronto-Waterloo engineering clusters advance predictive maintenance architectures for distributed sensing applications.
Airborne Wind Turbines Market Competitive Environment
Global majors compete with regional champions across aviation authority coordination capabilities and integrated service contract execution. The vendor base stratifies between technology-integrated solution providers and pure equipment licensors. Three archetypes dominate: buoyant aerostat specialists, rigid-wing autonomous developers, and ship-kite heritage operators. Capacity expansion in European production facilities and strategic partnerships for conductive tether supply represent the dominant competitive moves.
Within the autonomous flight control tier, Altaeros Energies and Makani Power exemplify divergent architectural approaches to utility-scale deployment. SkySails Power occupies a position bridging maritime heritage with airborne wind applications. Kitepower and AMPYX Power sit within the European specialist cluster advancing rigid-wing validation. KitGen represents the emerging engineering consultancy archetype targeting EU AI Act compliance documentation.
| Leading Market Players |
|---|
| Kite X |
| KitGen |
| Altaeros Energies |
| SkySails Power |
| Makani Power |
| Kitepower |
| Brainwhere |
| AMPYX Power |
| E-kite |
| Others |
Value Chain & Pricing Dynamics
Conductive tether manufacturing scale-up in European composite facilities is simultaneously compressing unit economics and consolidating supplier power around carbon fiber specialists with embedded power transmission capabilities. This dual restructuring favors vendors with captive tether production over pure technology licensors seeking third-party supply.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium autonomous system vendors from unbundled equipment suppliers in procurement negotiations. Project-based contracting dominates, with price differentiation driven by certification tier for beyond-visual-line-of-sight operations and geographic delivery cost to remote deployment zones. Pricing pressure stems from fixed-bottom offshore wind competition for coastal utility budgets. Oil and gas operators show least price sensitivity due to decommissioning fund availability, while rural telecommunications buyers face capital constraints.
Supply Chain Analysis
Composite engineering talent shortages in Germany, Norway, and the United Kingdom constrain conductive tether production expansion despite demand acceleration. Raw material dependencies center on high-strength carbon fiber, helium for aerostat architectures, and rare-earth magnets for onboard generation systems. Supply chain risk concentrates in Qatar and United States helium supply concentration creating input cost volatility. Distribution runs through integrated energy service contracts rather than equipment-only channels, with vendors embedding maintenance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into conductive tether production represents the decisive vertical-integration lever as carbon fiber supply tightens and proprietary cable designs become differentiation anchors.
For Market Incumbents: To counter fixed-bottom offshore wind competition for coastal utility procurement, Altaeros Energies and SkySails Power should deepen captive maintenance network coverage in North Sea corridors and secure EASA algorithmic transparency pre-certification for autonomous flight stacks. These moves defend pricing power against emerging hybrid-system challengers. For New Entrants and Emerging Players: Launch via integrated availability contracts targeting United Kingdom island communities in Orkney and Shetland, where diesel displacement premiums and grid isolation create penetrable white-space. EU AI Act compliance advisory services offer parallel entry path for engineering consultancies lacking hardware heritage. For Investors and Strategic Acquirers: Re-rating potential sits with rigid-wing autonomous developers possessing EASA pre-certification given EU AI Act enforcement deadlines. Five-to-ten year viability favors vendors with demonstrated beyond-visual-line-of-sight operational hours and captive conductive tether supply. Watch FAA altitude waiver streamlining as inflection signal for United States addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Conductive Tether Backward Integration | Captive carbon fiber composite production secures supply and protects proprietary designs from replication. |
| EASA Algorithmic Transparency Pre-Certification | Early EU AI Act compliance documentation accelerates beyond-visual-line-of-sight operational approvals. |
| North Sea Maintenance Network Expansion | Embedded service presence captures oil and gas decommissioning budget redirection toward hybrid microgrids. |
| United Kingdom Island Community Pilot Programs | Orkney and Shetland deployments establish reference installations for premium-priced diesel displacement. |
| Predictive Maintenance Platform Development | Distributed sensing architectures compress downtime costs and differentiate integrated service contracts. |
Study Parameters
Multi-period observation of aviation authority waiver issuance, demonstration project commissioning, and tether fatigue certification milestones anchored the trend analysis, supplemented by interviews with autonomous system developers, EASA certification specialists, oil and gas decommissioning planners, and conductive tether composite engineers. Secondary validation drew from FAA airspace coordination filings, EASA implementation guidance on algorithmic transparency, EU F-Gas Regulation phasedown schedules, and North Sea decommissioning budget disclosures. Bottom-up project pipeline enumeration triangulated against top-down addressable market sizing across technology and deployment segments.
Input-output matrices modeled capacity installations, revenue flows, and cost structures across autonomous, hybrid, HAWT, and VAWT technology pathways; offshore, onshore, rural, and urban deployment environments; oil and gas, utility, telecommunications, and research institution end users; and small through mega scale capacity tiers. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated aviation authority coordination timelines, helium supply elasticity, and conductive tether certification standard maturation.
Aviation authority position shifts on beyond-visual-line-of-sight operations, helium supply disruption events, and tether fatigue certification standard finalization are the dominant revision risks to modeled projections. Forecasts embed assumptions on regulatory harmonization progress and composite manufacturing scale-up feasibility. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Floating Wind Turbine Market