
 Flare Gas Recovery System Market | 2026-2036
Flare Gas Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Flare Gas Recovery System Market Analysis
Aftermarket service revenue is reconfiguring margin pools across the competitive landscape. Honeywell UOP leverages its catalyst and process licensing heritage to anchor long-term service contracts. John Zink Hamworthy Combustion dominates combustion and flare system integration, extending its position into recovery retrofits. Wärtsilä competes through marine and offshore power expertise, positioning its gas handling systems for floating production platforms.
A flare gas recovery system captures hydrocarbon gases that would otherwise be combusted at flare stacks, using compression, condensation, or membrane separation to return them to processing units or fuel systems. Compression systems achieve discharge pressures from 50 to 1,500 psig depending on reinjection or pipeline specifications. Vapor recovery units lead the product type segment due to established deployment at storage terminals and loading facilities. Offshore deployment shows the fastest structural growth as floating production facilities face stricter venting limits and fuel gas optimization requirements.
The US EPA enforces methane performance standards under New Source Performance Standards for the oil and gas sector, directly mandating flare gas minimization at new and modified facilities. The EU methane strategy and F-Gas Regulation impose measurement, reporting, and reduction obligations that drive capital allocation toward recovery infrastructure. The International Maritime Organization's carbon intensity indicators shape offshore vessel and platform fuel strategies. Stakeholders must monitor how jurisdictional methane pricing mechanisms alter project economics for greenfield versus retrofit installations.
Market Dynamics
Upstream operators face mounting pressure from methane pricing mechanisms and carbon border adjustments, forcing capital reallocation from flaring infrastructure toward recovery and reinjection systems that transform waste streams into revenue.
Growth Catalysts
- US EPA methane performance standards:New Source Performance Standards mandate flare gas minimization at modified facilities, compelling operators to install vapor recovery units.
- Floating production platform expansion:Offshore developments in the North Sea and Gulf of Mexico deploy integrated gas handling systems to meet stricter venting limits.
- Membrane separation advances:Polymeric membrane modules now achieve hydrocarbon recovery rates exceeding conventional condensation at lower energy intensity.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel for high-pressure compressors concentrates among Nordic and Japanese metallurgical suppliers.
- Retrofit integration complexity:Legacy flare systems at mature Permian Basin facilities require extensive piping modifications that extend commissioning timelines.
- Electrification cost volatility:Variable frequency drive and motor assemblies for large compression trains face copper and rare earth magnet price swings.
Strategic Opportunities
- EU methane strategy implementation:Measurement, reporting, and verification mandates create retrofit demand across Dutch and Danish offshore corridors.
- Associated gas-to-power integration:Captured flare gas feeds combined-cycle turbines at remote Saudi and Iraqi upstream facilities.
- Modular skid-mounted systems:Standardized compression packages reduce field assembly labor and accelerate deployment in Nigerian and Angolan developments.
Industry Challenges
- Rotating equipment specialist scarcity:Reciprocating compressor technicians and high-pressure sealing engineers command premium wages across Texas and Alberta.
- API 618 certification timelines:Reciprocating compressor design validation for sour service applications extends vendor qualification periods.
- Legacy SCADA integration:Digital control retrofits for pneumatic flare monitoring systems require protocol translation layers that complicate automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flare Gas Recovery System Market |
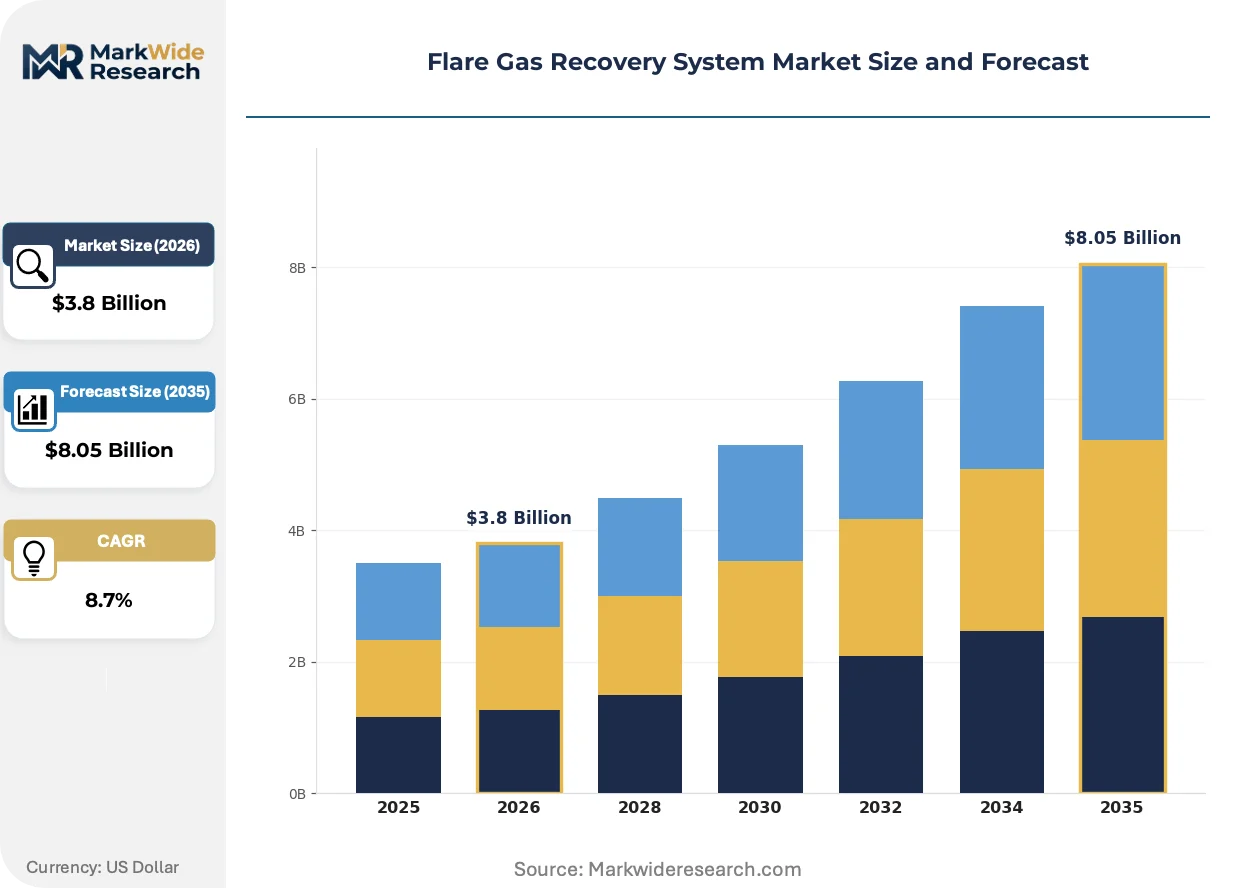
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Systems, Vapor Recovery Units, Gas Processing Equipment, Detonation Systems End User: Oil & Gas Industry, Chemical Manufacturing, Power Generation, Landfills Deployment: Onshore, Offshore, Industrial Sites, Municipal Facilities Service Type: Installation, Maintenance, Consultation, Training |
| Companies Covered | Zeeco Inc., Honeywell UOP, John Zink Hamworthy Combustion, Gardner Denver, Wärtsilä, Transvac Systems Ltd, Aerzen, Cimarron Energy, SoEnergy International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flare Gas Recovery System Market Emerging Trajectories
Digital instrumentation and predictive analytics are penetrating flare gas recovery infrastructure, converting passive mechanical systems into data-generating assets that optimize compression scheduling and reduce unplanned outages.
Machine learning algorithms applied to compressor vibration and discharge temperature patterns is digitizing maintenance planning across Permian Basin and North Sea installations. Operators at supermajor and independent producers now deploy edge computing nodes on skid packages. Real-time performance modeling reduces emergency flaring events and extends mean time between overhauls.
The EU F-Gas Regulation and its phasedown of hydrofluorocarbon refrigerants in condensation units is accelerating hydrocarbon refrigerant adoption. European engineering contractors redesign chiller circuits to use propane or mixed refrigerant blends. Offshore platform projects in Norwegian and UK waters specify these systems to preempt compliance deadlines.
Integrated service contracts are displacing equipment-only procurement at major upstream operators. Engineering-procurement-construction firms bundle compression hardware with decade-long maintenance and spare parts agreements. This shift concentrates vendor relationships and locks in aftermarket revenue streams across Middle Eastern national oil companies.
Flare Gas Recovery System Market Segmentation
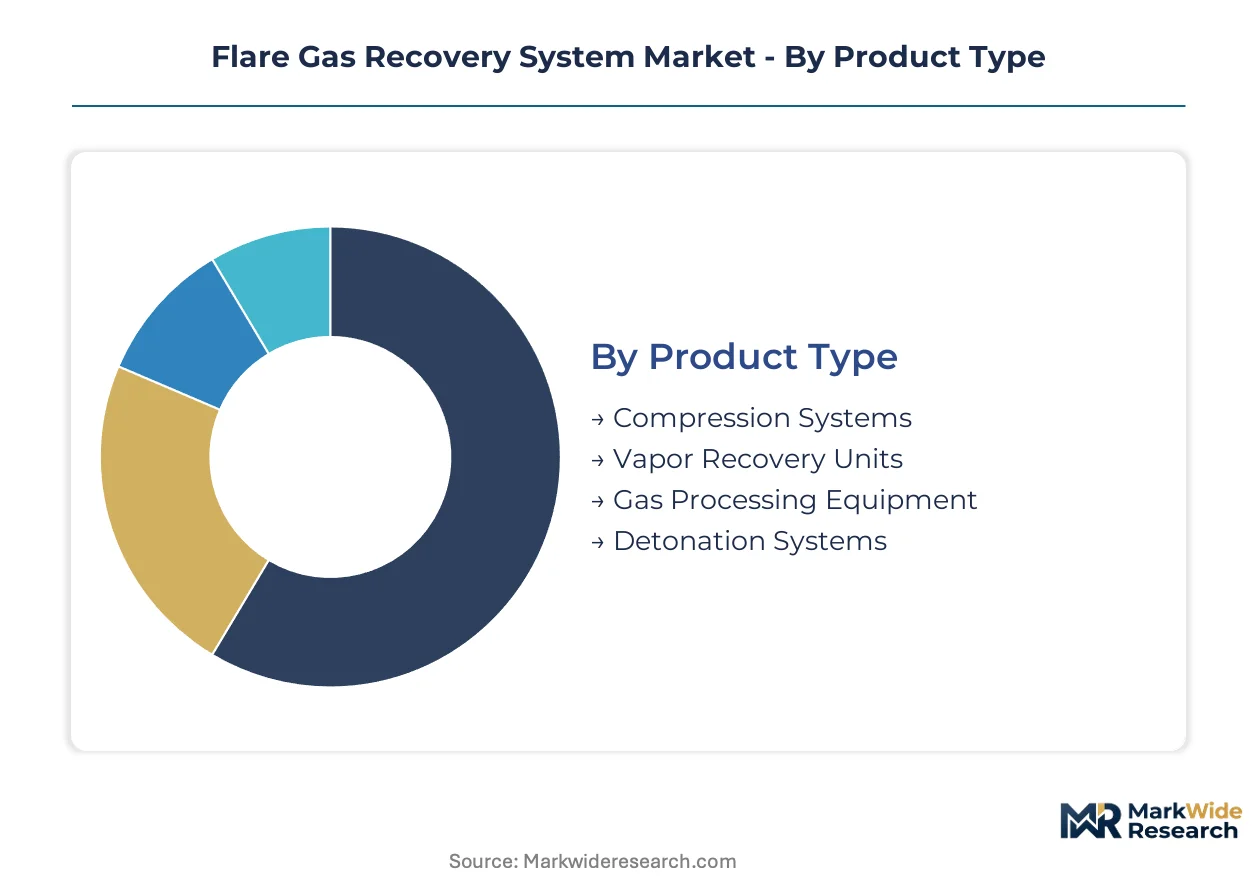
Segmentation in the flare gas recovery system market reflects distinct technical requirements across pressure regimes, facility types, and service intensity. Equipment specifications diverge sharply between reinjection-grade compression and atmospheric vapor capture, while deployment location dictates material selection and regulatory compliance pathways.
Product Type:
Cost tier differentiation separates high-pressure reinjection infrastructure from lower-pressure fuel gas conditioning equipment.
- Compression Systems:Reciprocating and centrifugal compressors achieve discharge pressures from 50 to 1,500 psig for pipeline injection or reservoir reinjection. Permian Basin operators deploy these for associated gas capture where gathering infrastructure remains underdeveloped.
- Vapor Recovery Units:Vacuum-assisted vapor collection systems handle hydrocarbon vapors from storage tanks and loading racks at atmospheric to low-pressure conditions. Terminal operators across Texas and Louisiana favor these for benzene and VOC compliance under EPA standards.
- Gas Processing Equipment:Dehydration and contaminant removal skids condition recovered gas for fuel use.
- Detonation Systems:Specialized combustion controls manage emergency flare scenarios where recovery capacity saturates.
Vapor recovery units command the established base. The steepest expansion runs through compression systems.
End User:
Application context determines recovery system scale, from wellhead aggregation to centralized processing.
- Oil & Gas Industry:Upstream producers deploy modular compression at well pads and centralized facilities to meet methane performance standards. Saudi Aramco and Iraqi state operators integrate recovered gas into power generation at remote fields.
- Chemical Manufacturing:Petrochemical complexes capture vent streams from reactors and storage to feed process heaters and boilers.
- Power Generation:Combined-cycle plants utilize conditioned flare gas as supplementary fuel.
- Landfills:Biogas upgrading equipment extracts methane from decomposition gases for pipeline injection or vehicle fuel.
Oil and gas applications anchor current deployment. Landfill gas recovery is climbing the fastest as waste-to-energy regulations tighten.
Deployment:
Volume concentration and logistics constraints reshape system architecture between fixed and floating installations.
- Onshore:Permian Basin and Middle Eastern desert developments favor skid-mounted compression packages with rapid redeployment capability.
- Offshore:Floating production platforms in the North Sea and Gulf of Mexico require compact, weight-optimized gas handling with marine-grade corrosion protection.
- Industrial Sites:Refinery and chemical complex retrofits integrate recovery into existing flare header networks.
- Municipal Facilities:Wastewater treatment and landfill operations deploy smaller-scale vapor collection.
Onshore infrastructure holds the dominant share. Offshore deployment is gaining share fastest under stricter platform venting limits.
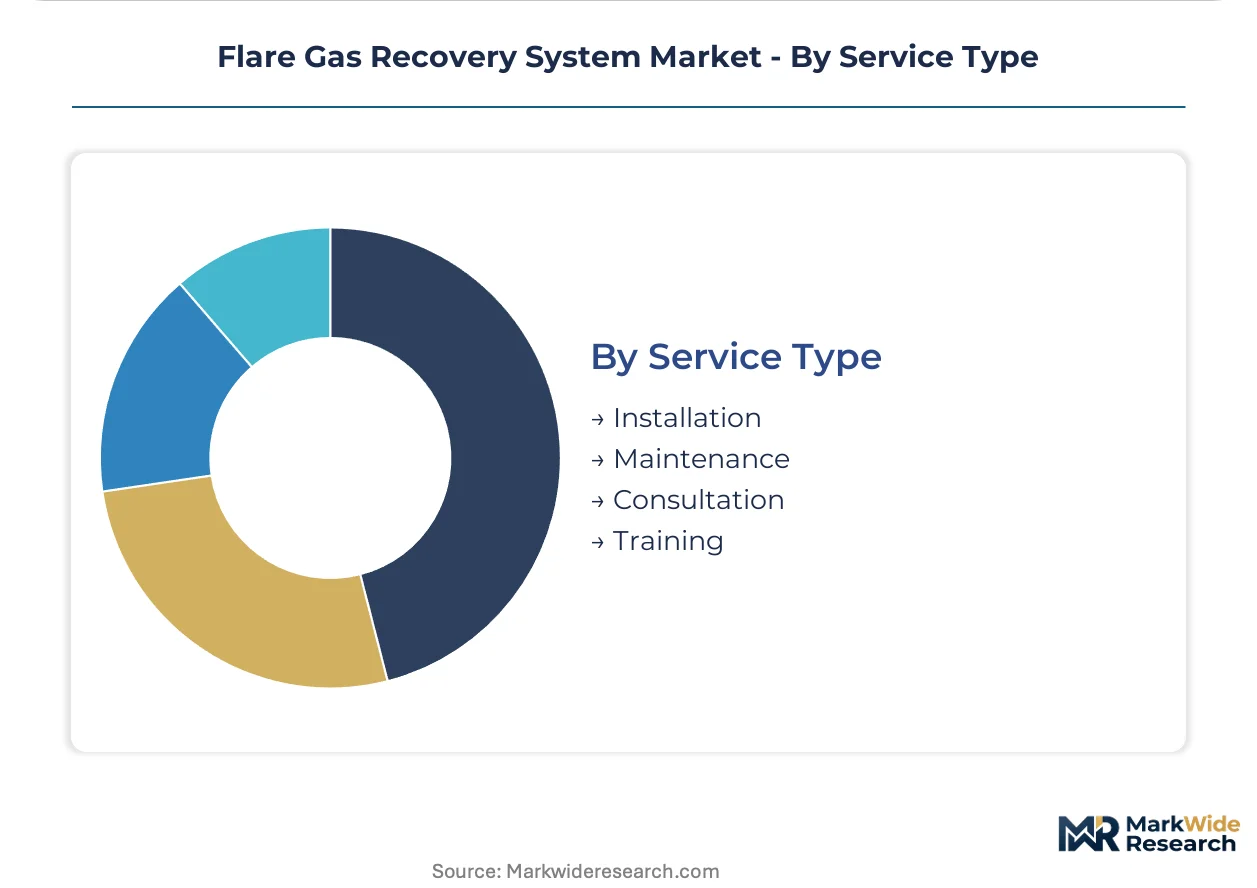
Service Type:
Customer type and asset maturity drive revenue mix between capital installation and recurring aftermarket.
- Installation:Engineering-procurement-construction contractors deliver turnkey compression and processing packages with commissioning support.
- Maintenance:Long-term service agreements cover reciprocating compressor overhauls, seal replacements, and predictive monitoring.
- Consultation:Process licensors optimize recovery system integration with existing flare networks and regulatory reporting.
- Training:Operator certification programs address high-pressure equipment safety and EPA compliance documentation.
Installation revenue dominates project economics. Maintenance contracts are expanding most quickly as installed base matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies: mature regulatory environments absorb premium recovery systems while emerging producers prioritize modular, redeployable units. Buyers in North American shale corridors demand rapid payback periods; Middle Eastern national oil companies optimize for decades-long operational life.
United States
Permian Basin operators deploy skid-mounted compression packages to capture associated gas where gathering infrastructure lags. The US EPA New Source Performance Standards mandate flare gas minimization at modified facilities, compelling vapor recovery retrofits. Midland-Odessa clusters concentrate deployment of high-pressure reinjection systems as operators face methane pricing mechanisms.
Norway
North Sea floating production platforms drive demand for weight-optimized gas handling with marine-grade corrosion protection. The country's petroleum regulator enforces strict venting limits through carbon intensity benchmarks on offshore installations. Stavanger and Bergen engineering corridors specialize in compact membrane separation modules for subsea tiebacks.
Saudi Arabia
Remote upstream facilities integrate recovered flare gas into combined-cycle power generation to displace liquid fuel imports. The national hydrocarbon regulator mandates gas conservation targets across all new field developments. Eastern Province industrial cities anchor associated gas-to-power projects at supergiant oil fields.
Netherlands
Dutch offshore corridors face retrofit demand from EU methane strategy measurement and verification mandates. The national environmental agency enforces reporting obligations that drive capital allocation toward recovery infrastructure. Rotterdam and Groningen clusters concentrate engineering-procurement-construction contracts for North Sea platform upgrades.
China
Western shale basins and coastal refining complexes deploy vapor recovery for benzene compliance and fuel gas optimization. The Ministry of Ecology and Environment tightens fugitive emission standards for petrochemical storage terminals. Sichuan-Chongqing shale plays anchor domestic compressor manufacturing scale as local suppliers capture mid-pressure segments.
Flare Gas Recovery System Market Vendor Landscape
Capability concentration sits with process licensing specialists; scale advantage sits with diversified industrial conglomerates. The vendor base stratifies across three tiers: integrated technology licensors anchoring long-term service relationships, combustion-focused system integrators extending into recovery retrofits, and regional fabricators capturing modular skid orders. Dominant competitive moves include strategic partnerships between compressor OEMs and engineering contractors, plus portfolio diversification into predictive maintenance services.
Within the technology licensor tier, Honeywell UOP leverages catalyst and process heritage to anchor aftermarket revenue streams. John Zink Hamworthy Combustion occupies a position spanning combustion integration and recovery retrofits. Wärtsilä exemplifies marine-to-offshore diversification, representing the floating production specialization vector. These three companies sit within distinct archetypes that collectively cover the value chain from process design through platform deployment.
| Leading Market Players |
|---|
| Zeeco Inc. |
| Honeywell UOP |
| John Zink Hamworthy Combustion |
| Gardner Denver |
| Wärtsilä |
| Transvac Systems Ltd |
| Aerzen |
| Cimarron Energy |
| SoEnergy International |
| Others |
Supply Flow & Price Mechanics
Stavanger and Bergen engineering corridors anchor European supply capacity for high-pressure compression systems, with their specialized fabrication yards translating limited metallurgical supply into sustained pricing leverage over downstream operators. Duplex stainless steel procurement from Nordic and Japanese mills feeds directly into project cost structures, amplifying margin pressure when alloy availability tightens.
Pricing Analysis
Long-term service contracts dominate procurement structures, with engineering-procurement-construction firms bundling compression hardware with decade-long maintenance agreements. Three-tier pricing structure across premium, standard, and economy levels separates API 618-certified sour service systems from mid-pressure fuel gas conditioning units and basic vapor recovery skids. Cost compression in standard-tier equipment is intensifying because Chinese compressor OEMs are capturing mid-pressure segments through localized manufacturing. National oil companies exhibit lowest price sensitivity due to operational life optimization priorities, while independent Permian Basin operators demand rapid payback periods.
Supply Chain Analysis
Extended payment terms from Middle Eastern national oil companies strain working capital for European and American engineering contractors, forcing supply-chain finance facilities at Nordic metallurgical suppliers. Manufacturing concentrates in Norway, Germany, and Japan for high-pressure rotating equipment, with China capturing mid-pressure compressor assembly. Raw material dependencies center on duplex stainless steel forgings, rare earth magnets for variable frequency drives, and polymeric membrane modules. Single-source vulnerability runs through Japanese metallurgical suppliers for sour service alloys. Distribution runs through EPC-led turnkey contracting with integrated commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
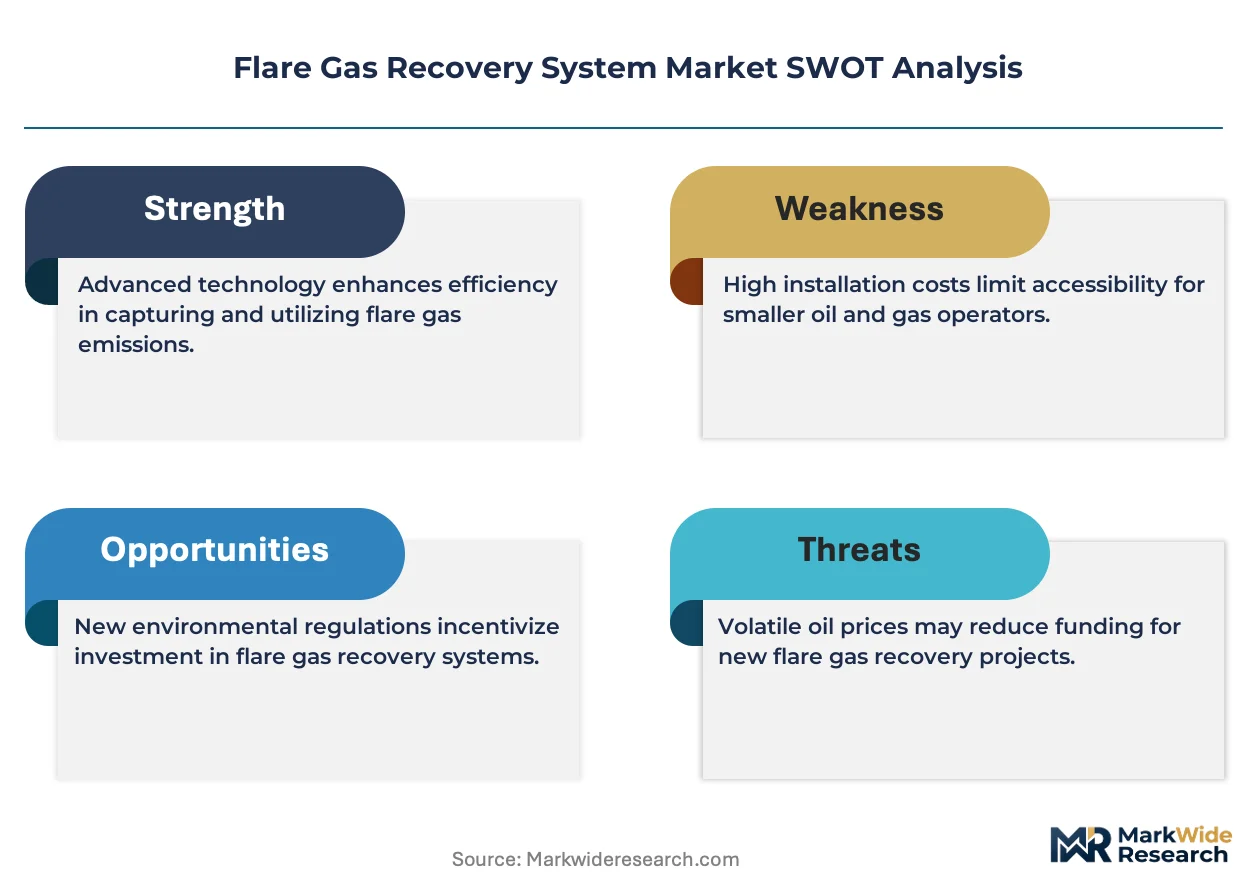
The flare gas recovery system market sits in early-cycle expansion as methane pricing mechanisms and carbon border adjustments force capital reallocation from flaring infrastructure toward capture systems. Regulatory tailwinds across the US, EU, and Middle East are accelerating penetration beyond early-adopter upstream operators.
For Market Incumbents: Pre-empt modular skid manufacturers from capturing African and Southeast Asian greenfield developments by accelerating standardized package certification for rapid deployment scenarios. Anchor long-term service contracts through predictive maintenance platform integration, countering emerging threats from independent digital service providers. Deepen backward integration into high-pressure sealing and reciprocating compressor component manufacturing to defend margin position against alloy cost volatility.
For New Entrants and Emerging Players: Nigerian and Angolan offshore developments offer underpenetrated demand for redeployable compression systems where established vendors lack localized service presence. Target landfill gas upgrading and biogas conditioning segments where technical specifications are less stringent than upstream oil and gas applications. Pursue joint venture structures with regional engineering contractors to bypass incumbent EPC relationships and accelerate reference plant accumulation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core combustion and gas handling divisions. Position for five-to-ten year holding periods as methane regulations tighten globally and aftermarket service revenue pools expand. Monitor API 618 certification backlog durations at reciprocating compressor OEMs as inflection indicator for supply-constrained pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Expansion | Locks in recurring revenue streams across Saudi Aramco and Iraqi state operator portfolios. |
| Predictive Maintenance Platform Deployment | Converts passive mechanical systems into data-generating assets at Permian Basin installations. |
| Modular Skid Standardization | Reduces field assembly labor and accelerates deployment in Nigerian and Angolan developments. |
| Hydrocarbon Refrigerant Circuit Redesign | Preempts EU F-Gas Regulation compliance deadlines for Norwegian and UK offshore platforms. |
| Membrane Separation Technology Licensing | Captures offshore platform demand for compact, weight-optimized gas handling systems. |
Methodological Framework
Initial hypotheses were tested against primary input from EPC contract managers, upstream facility engineers, rotating equipment maintenance directors, and flare system procurement leads at national oil companies and independents, and refined through secondary validation against EPA enforcement data, EU methane strategy implementation reports, SEC filings from compressor OEMs, and offshore project development databases. Bottom-up unit economics from individual facility retrofits were triangulated against top-down capital expenditure tracking across major shale basins and offshore corridors.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, deployment location, end-use application, and service intensity dimensions. CAGRs were derived through regression analysis of historical installation data and forward projection of regulatory mandate timelines. Forecast inputs incorporated methane pricing mechanism adoption curves, floating production platform order books, and membrane separation technology cost reduction trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese compressor OEMs or accelerated electrification mandates by the International Maritime Organization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Well Cementing Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Desalter Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Oilfield Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Subsea Flowlines Market