
 Wind Turbine Gearbox and Direct Drive Systems Market | 2026-2036
Wind Turbine Gearbox and Direct Drive Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Gearbox and Direct Drive Systems Market Analytics
Project finance structures with long-term power purchase agreements is fragmenting competitive access across the wind turbine gearbox and direct drive systems supply chain. Goldwind Science & Technology leverages captive manufacturing of permanent magnet direct drive generators to anchor cost positions in utility-scale tenders. Siemens Gamesa Renewable Energy sustains dual technology portfolios across gearbox and gearless architectures, competing across both onshore and offshore segments. Vestas Wind Systems specializes in modular drivetrain platforms that extend serviceability and reduce lifetime maintenance exposure.
Wind turbine gearbox and direct drive systems comprise mechanical power transmission assemblies that convert rotor torque into generator-speed electrical output, with gearboxes typically achieving 1:100 speed ratios through planetary or spur stages while direct drive systems eliminate intermediate gearing via low-speed multi-pole permanent magnet generators. These systems must withstand 20-year operational lives under cyclic loading, salt corrosion, and temperature extremes exceeding standard industrial equipment ratings. Gearbox systems dominate installed base across onshore applications where成熟 supply chains and refurbishment networks support lifecycle economics. Direct drive configurations represent the fastest-growing product category, particularly in offshore applications where eliminating gearbox failure modes reduces inaccessible maintenance events. Hybrid systems are capturing margin pools in repowering projects where existing tower structures constrain full direct drive retrofits but demand reliability upgrades.
The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in manufacturing processes and mandate circularity disclosures for drivetrain materials entering European supply chains. China's MIIT enforces GB standards on gearbox efficiency and permanent magnet material traceability, shaping export qualification requirements for domestic producers. The US FAA coordinates with offshore wind developers on aviation lighting and radar mitigation standards that influence turbine height and drivetrain mass specifications. Stakeholders must monitor how diverging carbon border mechanisms and rare earth supply security policies reshape sourcing economics for permanent magnet direct drive architectures.
Market Dynamics
Offshore wind farm developers are forcing a technology pivot away from conventional geared drivetrains toward direct drive and hybrid architectures as turbine ratings climb past 15 MW and maintenance access becomes prohibitively expensive.
Growth Catalysts
- EU F-Gas Regulation:The regulation's phase-down of fluorinated gases in manufacturing processes is accelerating investment in dry lubrication systems and sealed permanent magnet generators that eliminate gearbox oil dependency.
- China's offshore installation pipeline:Provincial energy bureaus in Jiangsu and Guangdong are tendering 8 GW annually of offshore capacity, creating concentrated demand for 10+ MW direct drive units with domestic supply chain localization requirements.
- Permanent magnet material efficiency gains:Grain boundary diffusion techniques are reducing dysprosium and terbium content in direct drive generators by 30-40% while maintaining coercivity, improving rare earth security economics.
Market Restraints
- Neodymium supply concentration:Rare earth oxide processing remains concentrated in China's Ganzhou and Baotou regions, exposing direct drive manufacturers to export quota volatility and carbon border adjustment exposure.
- Planetary gearbox fatigue limitations:Current bearing and gear surface technologies face diminishing returns in scaling beyond 5 MW for onshore applications, constraining repowering economics for aging fleets.
- US FAA aviation coordination:Radar mitigation and lighting standards for offshore arrays are capping turbine hub heights below optimal wind resource capture, forcing heavier nacelle designs that stress drivetrain mass budgets.
Strategic Opportunities
- US Gulf of Mexico lease rounds:Bureau of Ocean Energy Management auctions are opening 30 GW of seabed with hurricane resilience requirements favoring direct drive architectures with fewer rotating failure modes.
- Hybrid drivetrain retrofits:Existing 2-3 MW geared towers in Germany and Denmark are candidates for partial direct drive upgrades that preserve infrastructure while eliminating high-speed stage failures.
- India's National Offshore Wind Policy:The 37 GW target by 2030 includes domestic content requirements that incentivize joint ventures for permanent magnet generator manufacturing in Tamil Nadu and Gujarat.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled electromagnetic-structural-thermal modeling for direct drive generators requires expertise spanning magnetostatics, gear contact mechanics, and thermal management that crosses traditional mechanical and electrical engineering boundaries.
- Generator-to-grid compliance certification:IEC 61400-21 power quality testing and grid code compliance for weak grid connections in emerging markets extend product validation cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Gearbox and Direct Drive Systems Market |
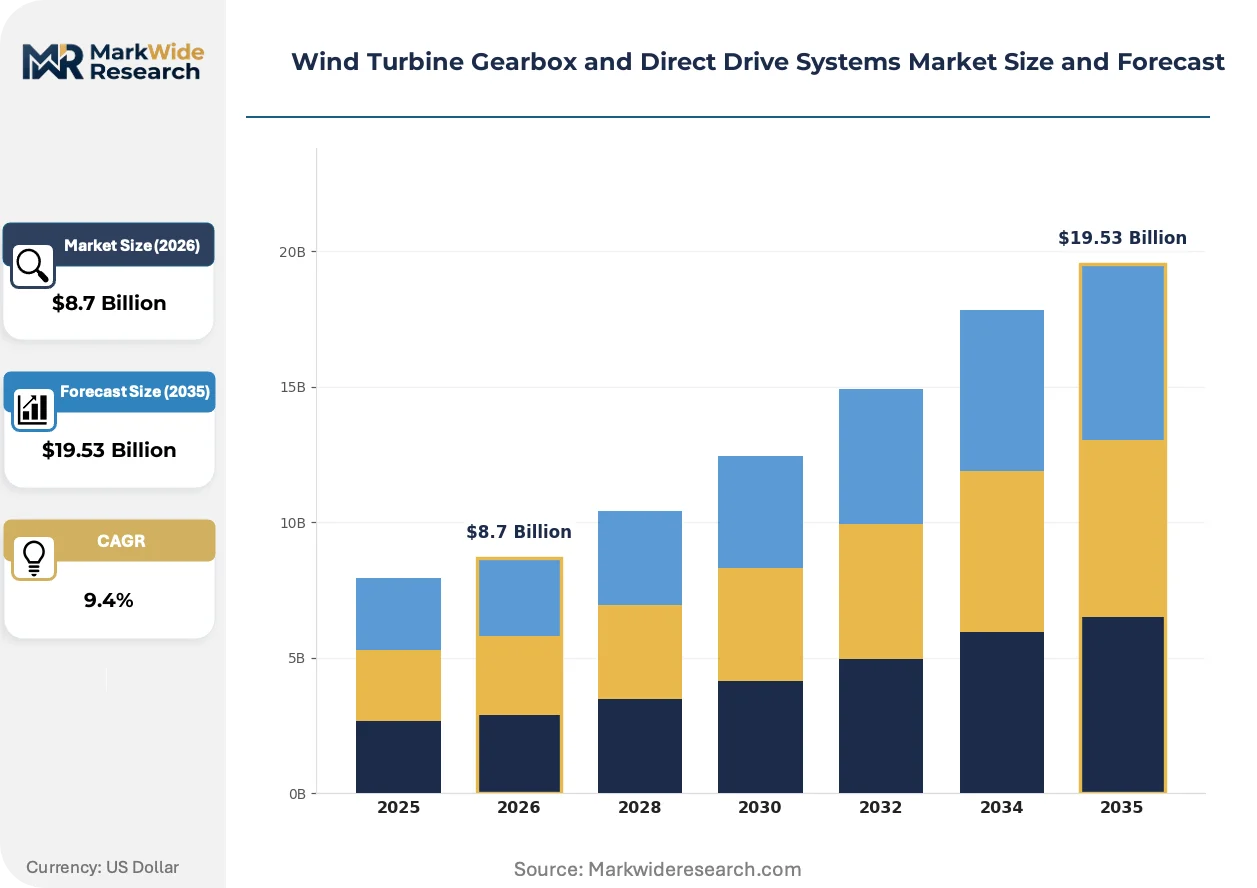
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gearbox, Direct Drive, Hybrid Systems, Pitch Control Application: Onshore, Offshore, Utility Scale, Distributed Generation End User: Energy Providers, OEMs, Project Developers, Maintenance Services Technology: Planetary Gear, Spur Gear, Permanent Magnet, Gearless |
| Companies Covered | Goldwind Science & Technology, Ming Yang Smart Energy, Siemens Gamesa Renewable Energy, ABB Ltd, Nordex SE, Vestas Wind Systems, ENERCON GmbH, Voith GmbH & Co. KGaA, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Gearbox and Direct Drive Systems Market Evolving Landscape
Permanent magnet direct drive technology is migrating from offshore niche to mainstream onshore deployment as generator mass-to-power ratios improve and rare earth recycling infrastructure matures.
Grain boundary diffusion and hot-deformed magnet architectures are migrating from laboratory demonstration to serial production at Goldwind and Siemens Gamesa facilities. Onshore developers in the US Great Plains and Brazilian Northeast are accepting 15-20% nacelle mass premiums to eliminate gearbox scheduled maintenance. This technology shift is compressing the addressable market for conventional planetary gearboxes to sub-4 MW applications and repowering retrofits.
The EU F-Gas Regulation's 2050 phase-out timeline is forcing lubricant and cooling system redesigns across drivetrain manufacturing. Sealed-for-life bearing cartridges and air-cooled generator topologies are displacing oil bath systems in new platform development. Offshore turbine platforms above 12 MW rating are most affected, with developers specifying 25-year maintenance-free intervals for inaccessible nacelle components.
Utility procurement committees are unbundling drivetrain supply from full turbine OEM contracts, creating direct commercial relationships with gearbox and generator specialists. Independent power producers in Spain and Australia are issuing separate RFPs for drivetrain packages with extended warranty terms decoupled from turbine availability guarantees. This pattern is most visible in markets with mature service infrastructure where owners self-perform maintenance.
Wind Turbine Gearbox and Direct Drive Systems Market Segmentation
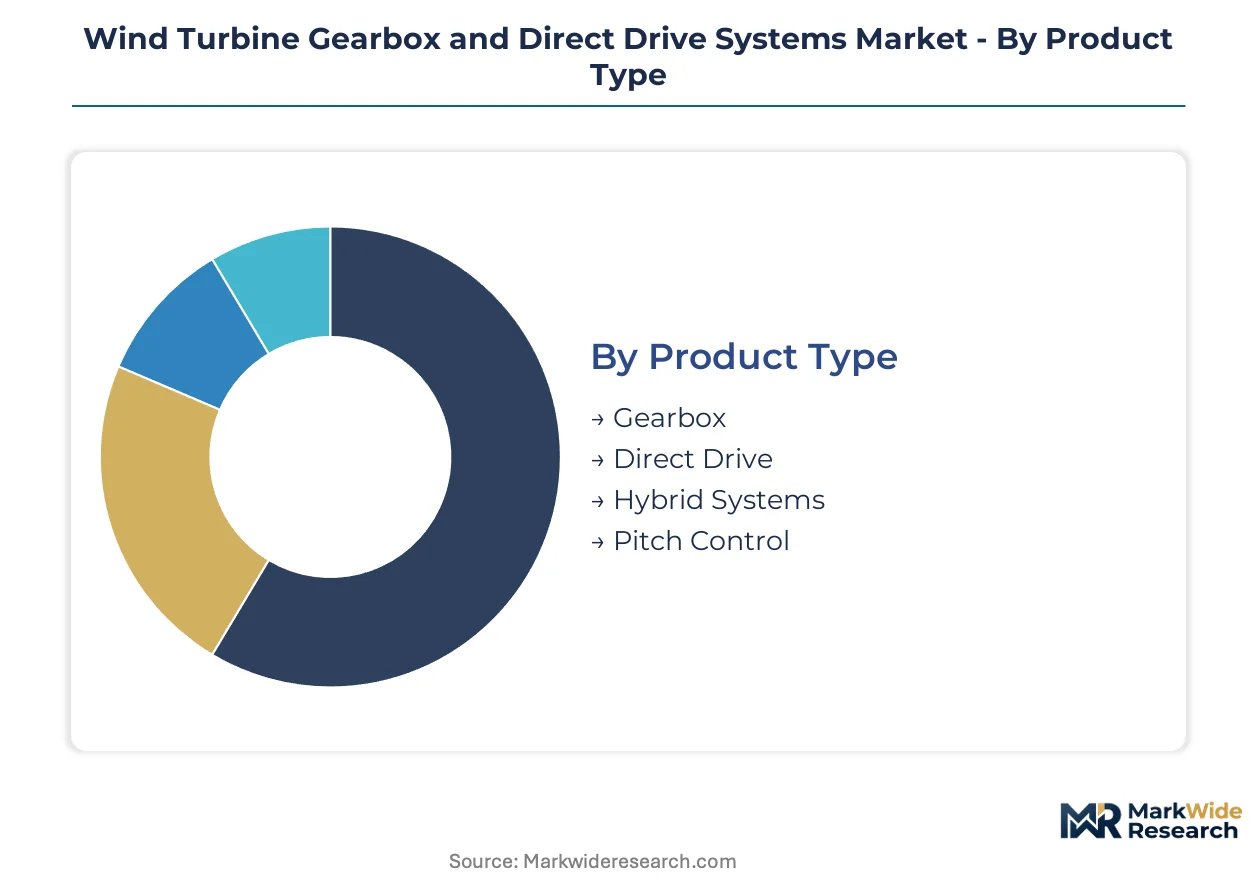
Drivetrain architecture selection determines capital intensity, maintenance schedules, and grid compliance trajectories across wind installations. Segmentation reveals how technology choices bifurcate between mature gearbox supply chains and emerging direct drive platforms.
Product Type:
Use cases span from established onshore refurbishment programs to next-generation offshore platforms requiring 25-year maintenance-free intervals.
- Gearbox:Planetary and helical stage assemblies achieving 1:100 speed ratios through hardened steel gearing. Demand concentrates in German and US onshore repowering projects where existing tower infrastructure constrains direct drive retrofits.
- Direct Drive:Low-speed multi-pole permanent magnet generators eliminating intermediate gearing entirely. Procurement from Jiangsu and Guangdong offshore tenders is accelerating as turbine ratings exceed 10 MW and helicopter access costs render gearbox maintenance uneconomical.
- Hybrid Systems:Partial direct drive architectures preserving low-speed planetary stages while eliminating high-speed failure modes.
- Pitch Control:Electromechanical and hydraulic blade angle adjustment systems integrated with drivetrain control loops.
The dominant share belongs to Gearbox systems, while Direct Drive is closing the gap fastest.
Application:
Deployment environments impose distinct mass, corrosion, and accessibility constraints on drivetrain design.
- Onshore:Land-based installations leveraging established gearbox refurbishment networks and crane access for scheduled maintenance. Procurement patterns in the US Great Plains and Brazilian Northeast favor proven planetary architectures with 20-year service histories.
- Offshore:Marine environments demanding sealed permanent magnet generators and salt-resistant bearing cartridges. China's provincial energy bureaus are tendering 8 GW annually, specifying direct drive units with domestic supply chain localization requirements.
- Utility Scale:Centralized generation assets above 5 MW capacity with grid-forming inverter requirements.
- Distributed Generation:Sub-5 MW installations serving industrial offtakers and rural electrification programs.
Offshore applications command the steepest expansion trajectory, though Onshore retains volume leadership through repowering cycles.
End User:
Procurement authority varies across asset ownership models and vertical integration strategies.
- Energy Providers:Utility and independent power producer fleets with captive O&M capabilities. Spanish and Australian IPPs are unbundling drivetrain supply from full turbine contracts, issuing separate RFPs with decoupled warranty terms.
- OEMs:Turbine manufacturers with in-house or captive drivetrain production. Goldwind leverages captive permanent magnet generator manufacturing to anchor cost positions in utility-scale tenders.
- Project Developers:Greenfield development entities structuring project finance around long-term power purchase agreements.
- Maintenance Services:Third-party service providers performing gearbox refurbishment and generator rewinding.
Energy Providers control the largest procurement volume, while OEMs are consolidating design authority fastest through platform standardization.
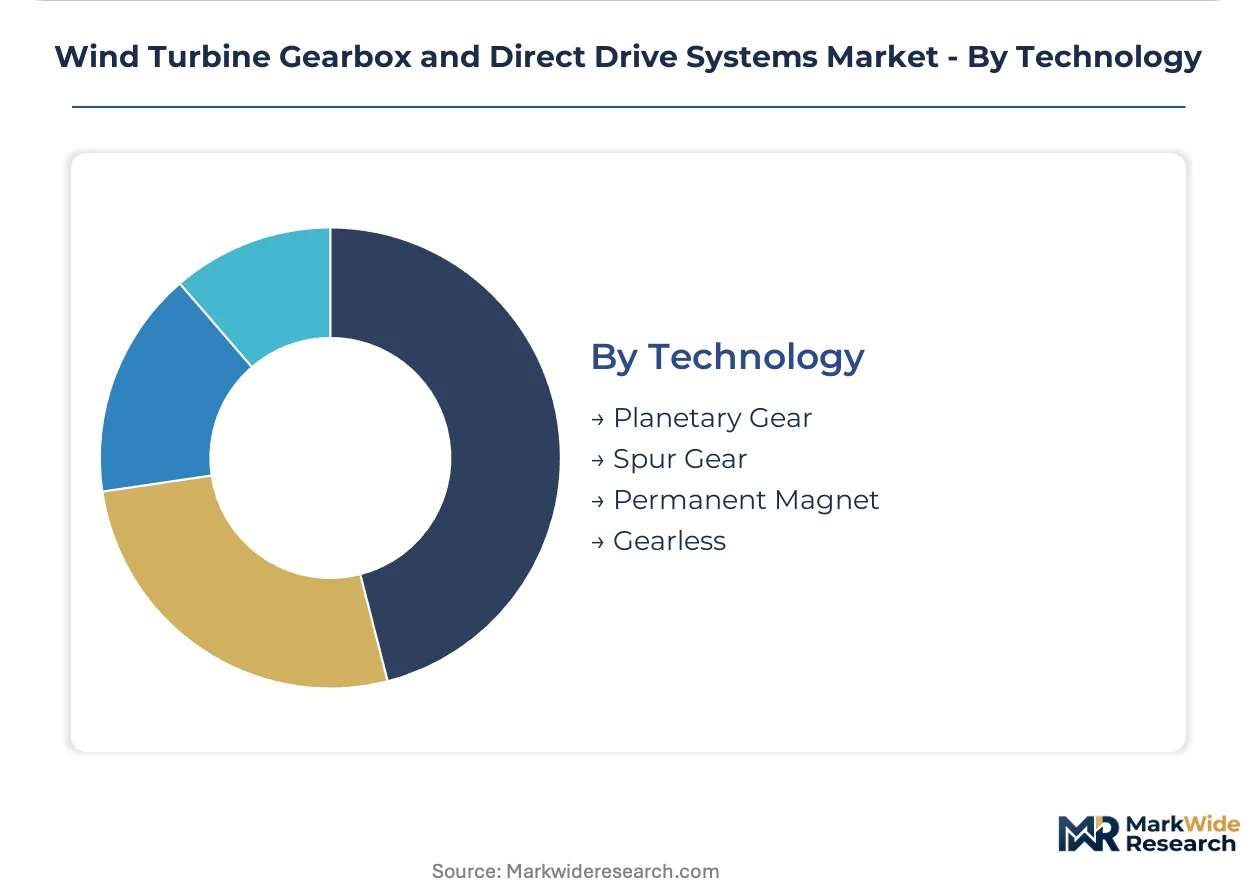
Technology:
Mechanical and electromagnetic architectures compete on efficiency, reliability, and rare earth supply security.
- Planetary Gear:Compact torque multiplication through nested epicyclic gear trains. Fatigue limitations in bearings and gear surfaces constrain scaling beyond 5 MW for onshore applications.
- Spur Gear:Parallel shaft configurations with simpler maintenance access but higher nacelle mass.
- Permanent Magnet:Neodymium-iron-boron rotor excitation eliminating field winding losses. Grain boundary diffusion techniques are reducing dysprosium and terbium content by 30-40% while maintaining coercivity.
- Gearless:Direct electromagnetic torque conversion without mechanical speed multiplication.
Planetary Gear retains installed base dominance, while Permanent Magnet technology is gaining share fastest through offshore specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for drivetrain components favor manufacturing clusters with integrated rare earth processing and deepwater port access. China maintains surplus positions in permanent magnet generators while Germany and the United States import specialized bearing assemblies and high-grade electrical steel.
China
Provincial energy bureaus in Jiangsu and Guangdong tender 8 GW annually of offshore capacity, concentrating procurement of 10+ MW direct drive units. MIIT enforces GB standards on gearbox efficiency and permanent magnet material traceability, shaping export qualification requirements. Manufacturing clusters in Changzhou and Xiangtan produce planetary gearboxes and low-speed generators for domestic installation and Southeast Asian export.
Germany
Repowering projects across Lower Saxony and Schleswig-Holstein drive demand for hybrid drivetrain retrofits preserving existing tower infrastructure. The EU F-Gas Regulation accelerates investment in dry lubrication systems and sealed generator architectures eliminating gearbox oil dependency. Industrial concentrations in Bremen and Hamburg specialize in bearing surface treatments and condition monitoring systems for offshore applications.
United States
Bureau of Ocean Energy Management lease rounds in the Gulf of Mexico open 30 GW of seabed with hurricane resilience requirements favoring direct drive architectures. FAA coordination on radar mitigation and lighting standards caps turbine hub heights, forcing heavier nacelle designs that stress drivetrain mass budgets. Manufacturing footprints in Colorado and South Carolina assemble gearboxes and generators for Great Plains and Atlantic Coast projects.
India
The National Offshore Wind Policy targets 37 GW by 2030 with domestic content requirements incentivizing joint ventures for permanent magnet generator manufacturing. CEA grid code compliance for weak grid connections in Gujarat and Tamil Nadu extends product validation cycles. Port infrastructure at Mundra and Kattupalli supports component import for assembly facilities in Pune and Chennai industrial corridors.
United Kingdom
Round 4 and Round 5 offshore leasing allocates 8 GW with turbine ratings exceeding 14 MW specifying direct drive or hybrid configurations. The Contracts for Difference scheme stabilizes revenue streams for projects procuring advanced drivetrain packages. Manufacturing and service operations in Hull and Isle of Wight support North Sea installation and maintenance activity.
Wind Turbine Gearbox and Direct Drive Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying gearboxes, generators, and bearing assemblies to multiple OEMs. The vendor structure concentrates around turbine manufacturers with captive drivetrain production and independent suppliers serving refurbishment markets. Three archetypes dominate: vertically integrated OEMs controlling full drivetrain design, independent gearbox specialists focused on planetary and helical architectures, and generator manufacturers supplying permanent magnet and electrically excited machines. Competitive moves center on technology licensing agreements for direct drive platforms and strategic partnerships securing rare earth supply chains.
Within the integrated OEM tier, Goldwind Science & Technology and Siemens Gamesa Renewable Energy occupy positions spanning both gearbox and gearless architectures, while Vestas Wind Systems anchors the modular drivetrain platform segment. Independent specialists include Voith GmbH & Co. KGaA representing the precision gearbox manufacturing archetype and ENERCON GmbH exemplifying the gearless direct drive specialist model. These entities collectively illustrate the competitive tension between full-system control and component supply flexibility.
| Leading Market Players |
|---|
| Goldwind Science & Technology |
| Ming Yang Smart Energy |
| Siemens Gamesa Renewable Energy |
| ABB Ltd |
| Nordex SE |
| Vestas Wind Systems |
| ENERCON GmbH |
| Voith GmbH & Co. KGaA |
| GE Vernova |
| Others |
Value Network & Pricing Analysis
Changzhou and Xiangtan manufacturing clusters in China concentrate planetary gearbox and permanent magnet generator capacity, translating upstream scale economies into pricing leverage for domestic OEMs bidding utility-scale tenders. This geographic concentration feeds downstream cost compression pressures as European and North American developers demand localized supply chain compliance under carbon border mechanisms.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure where volume scale and certification tier create stratification between premium IEC 61400-21 compliant units and standard domestic-grade equipment. Price differentiation hinges on rare earth traceability documentation and 25-year warranty bundling. Margins are tightening due to dysprosium price volatility and F-Gas Regulation compliance costs. Independent power producers exhibit highest price sensitivity, while offshore developers with project finance structures accept premium positioning for maintenance-free architectures.
Supply Chain Analysis
Contract manufacturing for bearing assemblies and high-grade electrical steel concentrates in Germany, Japan, and South Korea, with Changzhou and Baotou anchoring rare earth processing and magnet fabrication. The supply chain draws from neodymium-iron-boron alloys, specialized bearing steels, and copper windings as critical inputs. Single-source vulnerability in China's Ganzhou rare earth oxide processing exposes direct drive manufacturers to export quota disruptions. Distribution runs through turbine OEM captive integration and independent component specialists serving refurbishment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
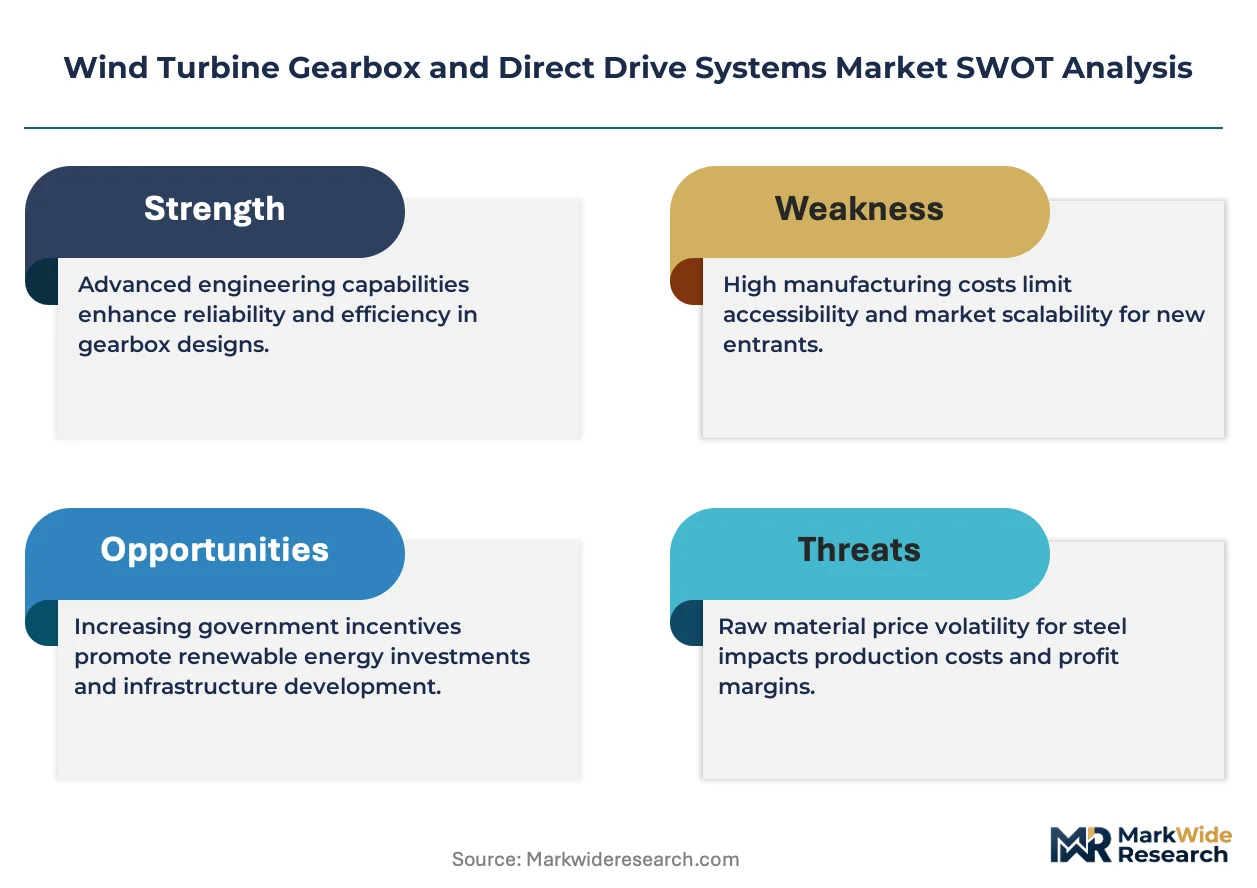
The wind turbine drivetrain market sits in a cyclical recovery phase as offshore installation pipelines in China, the United Kingdom, and the United States absorb capacity built during the previous onshore repowering wave. Capital expenditure cycles for 10+ MW turbine platforms drive this recovery trajectory.
For Market Incumbents: Harden rare earth supply security through backward integration into permanent magnet recycling or long-term offtake agreements with Ganzhou processors. Expand condition monitoring service contracts to capture recurring revenue streams as gearbox refurbishment demand peaks in German and Danish repowering markets. The threat of grain boundary diffusion technology commoditization demands accelerated R&D lock-in with generator OEMs.
For New Entrants and Emerging Players: Pursue hybrid drivetrain retrofit opportunities in Germany's 2-3 MW installed base where tower infrastructure constraints prevent full direct drive conversions. India's National Offshore Wind Policy offers the most penetrable geography given domestic content requirements forcing joint venture structures. A go-to-market angle through EPC contractor partnerships bypasses incumbent OEM procurement lock-in.
For Investors and Strategic Acquirers: Long-term, this sits as a materials technology play because permanent magnet efficiency gains and rare earth recycling infrastructure determine competitive moats more than mechanical engineering scale. Acquisition targets should display captive magnet processing or grain boundary diffusion IP. The signal to watch is dysprosium spot price divergence from neodymium, indicating supply security stress that would accelerate technology substitution toward electrically excited generators.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Locks in dysprosium and terbium access for direct drive generator production under MIIT traceability requirements. |
| Hybrid Drivetrain Platform Launch | Captures repowering demand from German and Danish operators constrained by existing tower specifications. |
| Grain Boundary Diffusion Licensing | Reduces heavy rare earth content by 30-40% while maintaining coercivity against permanent magnet cost volatility. |
| Offshore Service Infrastructure Buildout | Enables 25-year maintenance-free interval guarantees for Jiangsu and Guangdong provincial tenders. |
| Carbon Border Compliance Certification | Qualifies supply chains for EU Green Deal circularity disclosures and F-Gas Regulation lubricant phase-out timelines. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from EIA project databases, IEA renewable energy reports, FERC interconnection filings, and MIIT GB standard documentation. Bottom-up installation pipeline tracking and top-down manufacturing capacity assessment provided triangulation across the analysis window.
Scenario-bracketing framed the forecast framework across the modeling period, with segmentation dimensions spanning drivetrain architecture, application environment, end-user procurement authority, and electromagnetic technology type. CAGRs derived from unit installation trajectories and average selling price evolution through the projection horizon. Forecast inputs incorporated turbine rating escalation curves and rare earth oxide price sensitivity bands.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting project finance structures or rare earth export policy shifts would shift the trajectory. Forecasts reflect documented assumptions on technology substitution rates and regulatory compliance timelines. Quarterly review of provincial tender awards in Jiangsu and Guangdong, alongside dysprosium spot price movements, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Turbine Scrap Market