
 Global Small Wind Power Market | 2026-2036
Global Small Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Wind Power Market Outlook
Commercial microgrid developers are reorganizing procurement priorities around small wind assets for remote industrial sites. Primus Windpower leverages its vertical integration into blade manufacturing to sustain cost advantages across marine and telecom tower applications. Northern Power Systems Inc. anchors its position through permanent magnet direct-drive technology that eliminates gearbox maintenance in harsh climates. Bergey Windpower Co. specializes in residential-scale horizontal axis systems that have dominated the North American farm and ranch segment for decades.
Small wind power encompasses turbines rated below 100 kW that convert kinetic wind energy into electrical output through rotor blades, generators, and power conditioning electronics, typically achieving cut-in speeds of 3-4 meters per second. These systems serve distributed generation needs where grid extension proves uneconomical or where behind-the-meter offset reduces commercial electricity charges. Horizontal axis turbines occupy the dominant revenue position due to higher aerodynamic efficiency and established certification pathways, while vertical axis designs attract maritime and urban building-integrated applications where omnidirectional wind capture and reduced noise signatures matter. Hybrid systems pairing small wind with photovoltaic panels represent the fastest-expanding installation category, as developers exploit complementary generation profiles to improve capacity factors and reduce battery storage sizing.
The US Federal Aviation Administration reviews turbine height proposals near airports, while the EPA's Renewable Fuel Standard program indirectly supports distributed wind through broader clean energy incentives. IEC 61400-2 standards govern turbine safety and performance certification, creating market access barriers for uncertified manufacturers. Stakeholders must monitor evolving grid interconnection protocols and net metering policy reversals that could abruptly alter project economics in key state markets.
Market Dynamics
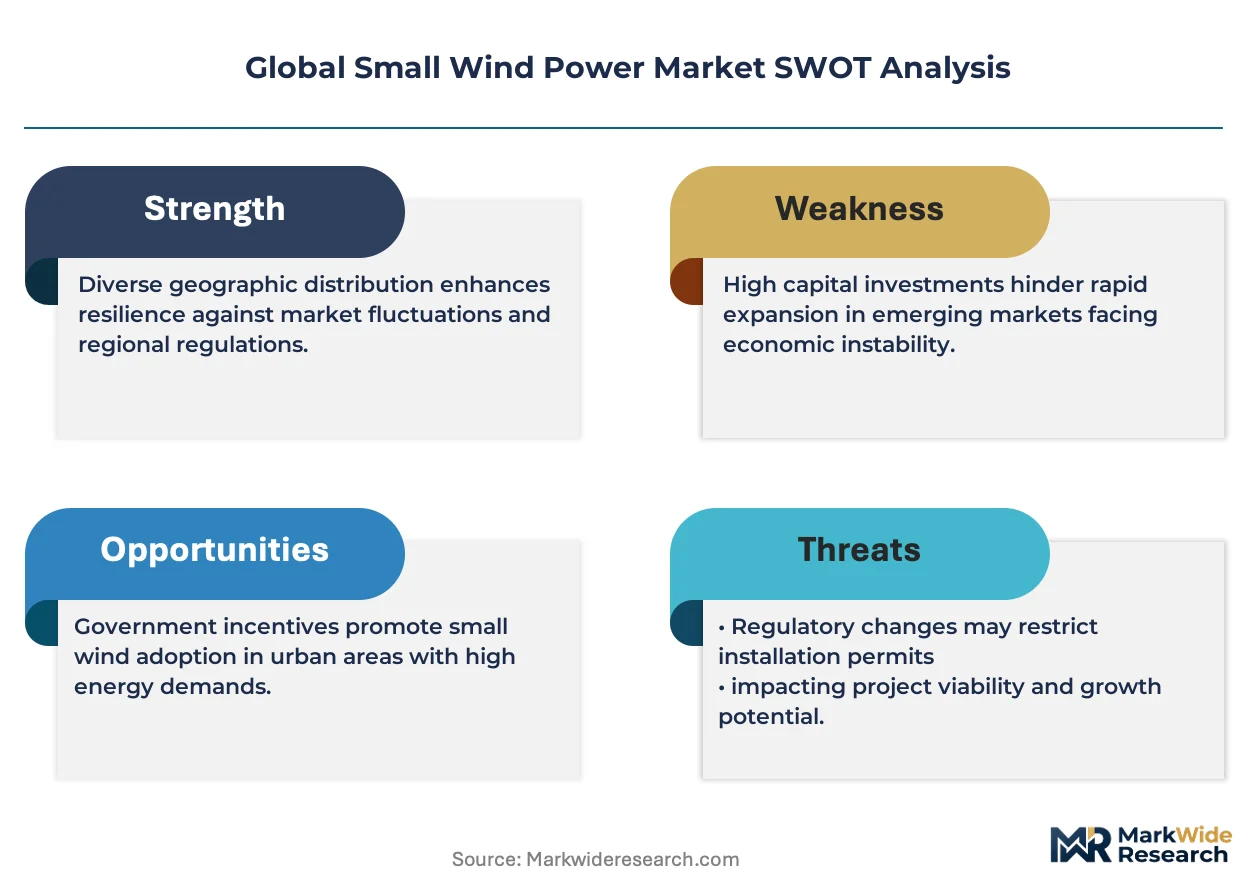
Hybrid wind-solar architectures are restructuring project economics by compressing battery storage requirements and extending capacity factors beyond standalone renewable configurations.
Growth Catalysts
- Rural electrification mandates:Sub-Saharan African governments are accelerating microgrid procurement through national universal access programs that prioritize distributed wind for off-grid settlements.
- Feed-in tariff revisions:Germany's Bundesnetzagentur has improved remuneration frameworks for sub-100 kW installations, restoring bankability for small-scale agricultural projects.
- Blade manufacturing automation:Advanced composite fabrication techniques are reducing turbine production costs and shortening delivery timelines for distributed generation developers.
Market Restraints
- Rare earth supply concentration:Permanent magnet dependency creates vulnerability to Chinese export controls on neodymium and dysprosium for direct-drive generators.
- Interconnection protocol fragmentation:Inconsistent grid codes across jurisdictions inflate engineering costs and delay commissioning for cross-border equipment suppliers.
- Photovoltaic cost compression:Solar module price declines continue to narrow the competitive window for small wind in hybrid configurations.
Strategic Opportunities
- Marine and coastal applications:Offshore aquaculture operations and island microgrids represent underpenetrated demand pockets for corrosion-resistant vertical axis designs.
- Building-integrated urban deployment:Omnidirectional turbines are capturing rooftop and façade mounting opportunities where noise restrictions and spatial constraints exclude horizontal alternatives.
- Agricultural irrigation electrification:Indian state-level subsidies for farm mechanization are expanding the addressable market for wind-powered pumping systems.
Industry Challenges
- IEC 61400-2 certification timelines:Third-party testing protocols for safety and performance validation extend product development cycles by months.
- Grid integration engineering capacity:Shortages of power electronics specialists familiar with distributed generation interconnection standards constrain project execution velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Wind Power Market |
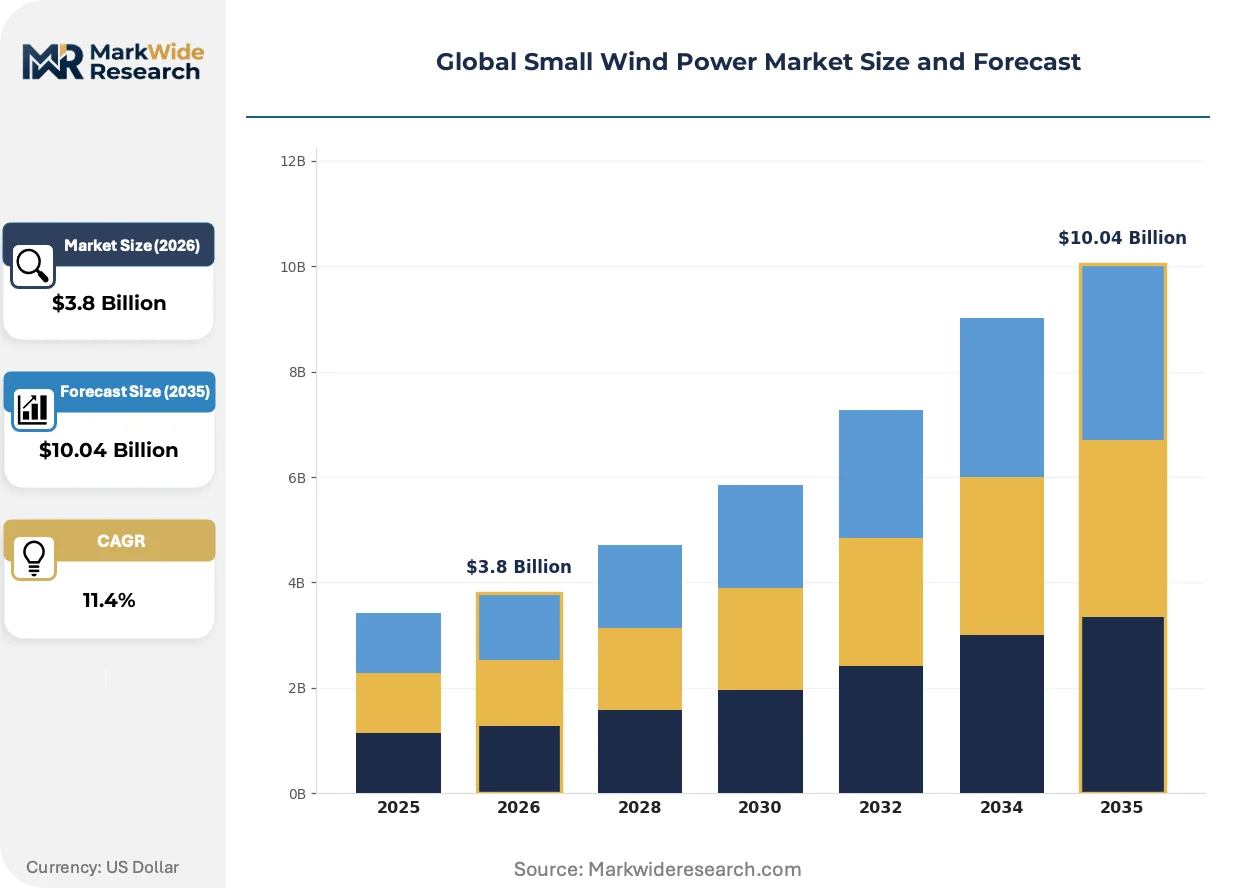
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis Turbines, Vertical Axis Turbines, Micro Wind Turbines, Hybrid Systems Installation Type: Roof-mounted, Ground-mounted, Portable, Off-grid End User: Residential, Commercial, Industrial, Agricultural Power Rating: Below 1 kW, 1-10 kW, 11-100 kW, Others |
| Companies Covered | Primus Windpower, Northern Power Systems Inc., Bergey Windpower Co., Kliux Energies, Ryse Energy, Aeolos Wind Energy Ltd., New World Wind, LuvSide GmbH, BORNAY AEROGENERADORES, SL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Wind Power Market Strategic Shifts
Modular turbine architectures and digital power conditioning are converging to reduce balance-of-system costs and enable plug-and-play deployment models for non-specialist installers.
Airborne wind energy systems using tethered drones or aerostats are decomposing traditional tower-and-blade economics by accessing higher-altitude wind resources without structural steel requirements. Remote mining operators and disaster relief agencies are piloting these systems for rapid deployment scenarios. The technology is decomposing conventional site preparation and foundation costs that previously dominated small wind project budgets.
The EU Green Deal's renewable energy targets are tightening building code requirements for on-site generation across member states. National implementation of nearly zero-energy building standards is mandating renewable integration in new commercial construction. Nordic countries are responding fastest, with Denmark and Sweden incorporating small wind into district heating facility retrofits.
Commercial buyers are consolidating vendor relationships around full-service providers offering predictive maintenance and remote monitoring subscriptions. Equipment-only transactions are losing share to performance-guaranteed contracts that transfer operational risk to manufacturers. This pattern is most pronounced in German and Dutch agricultural cooperatives deploying hybrid wind-solar irrigation systems.
Global Small Wind Power Market Segmentation
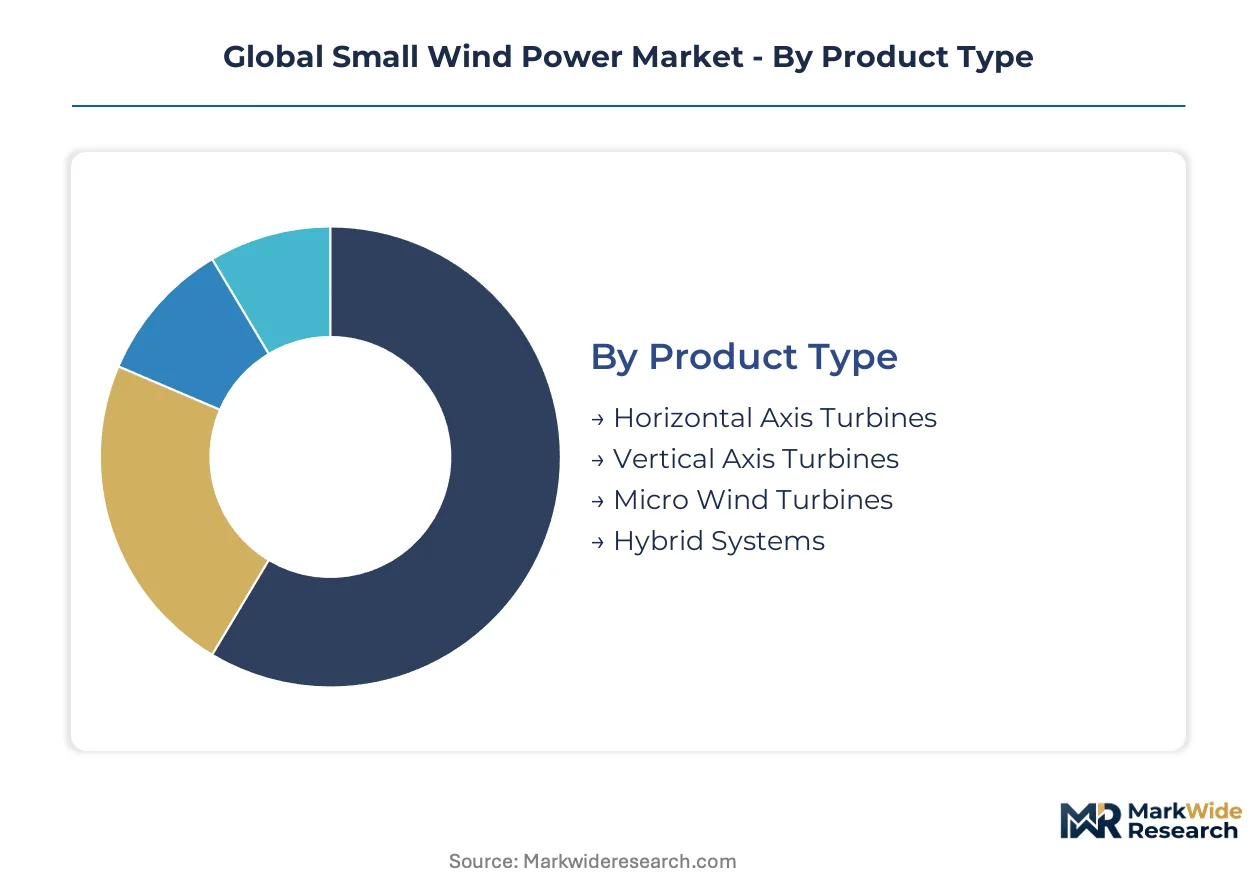
Segmentation in small wind power reveals how turbine architecture, mounting configuration, and scale interact with site constraints and energy economics. Procurement patterns diverge sharply across these dimensions, with hybrid architectures and off-grid installations commanding premium positioning against standalone grid-tied alternatives.
Product Type:
Photovoltaic cost compression exerts the most severe substitution pressure on standalone horizontal axis configurations, while hybrid wind-solar bundles resist displacement through capacity factor advantages.
- Horizontal Axis Turbines:Aerodynamic designs with rotor blades perpendicular to wind flow achieve higher efficiency coefficients and dominate certification pathways under IEC 61400-2 standards. Farm and ranch applications across the United States concentrate procurement in this category, though interconnection delays in state markets constrain deployment velocity.
- Vertical Axis Turbines:Omnidirectional capture geometry eliminates yaw mechanisms and reduces acoustic signatures for urban building integration. Maritime and coastal applications in Denmark and Sweden favor corrosion-resistant variants for aquaculture microgrids and island electrification.
- Micro Wind Turbines:Sub-1 kW units target residential balconies and telecom tower backup power in sub-Saharan African rural electrification programs.
- Hybrid Systems:Wind-solar pairings exploit complementary generation profiles to compress battery storage requirements and extend duty cycles beyond standalone configurations.
Horizontal axis turbines anchor the volume base while hybrid systems gain share at the steepest rate.
Installation Type:
Site preparation cost tiers separate ground-mounted foundations from rooftop alternatives, with portable configurations commanding logistics premiums for rapid deployment scenarios.
- Roof-mounted:Building-integrated deployment eliminates land acquisition costs but imposes structural load constraints and height restrictions under FAA regulations near US airports.
- Ground-mounted:Tower foundations on agricultural land across India support irrigation pumping applications with state-level farm mechanization subsidies.
- Portable:Containerized turbine units serve disaster relief agencies and remote mining operators requiring rapid redeployment without permanent civil works.
- Off-grid:Standalone microgrid configurations bypass interconnection protocol fragmentation but require oversized storage and redundant generation capacity.
Ground-mounted installations anchor the volume base while portable configurations expand most quickly in emergency response and frontier extraction markets.
End User:
Customer procurement sophistication separates industrial buyers seeking performance guarantees from residential purchasers sensitive to upfront capital requirements.
- Residential:Single-family installations concentrate in North American farm and ranch segments where net metering policies improve project economics.
- Commercial:Microgrid developers reorganize procurement priorities around small wind assets for remote industrial sites with unreliable grid supply.
- Industrial:Mining and manufacturing operations in Australia deploy hybrid systems to offset behind-the-meter electricity charges and hedge against tariff volatility.
- Agricultural:Indian state subsidies for irrigation electrification accelerate wind-powered pumping system deployment across Maharashtra and Gujarat.
Agricultural end users anchor the volume base while industrial deployments climb the fastest as energy security concerns override capital cost sensitivity.
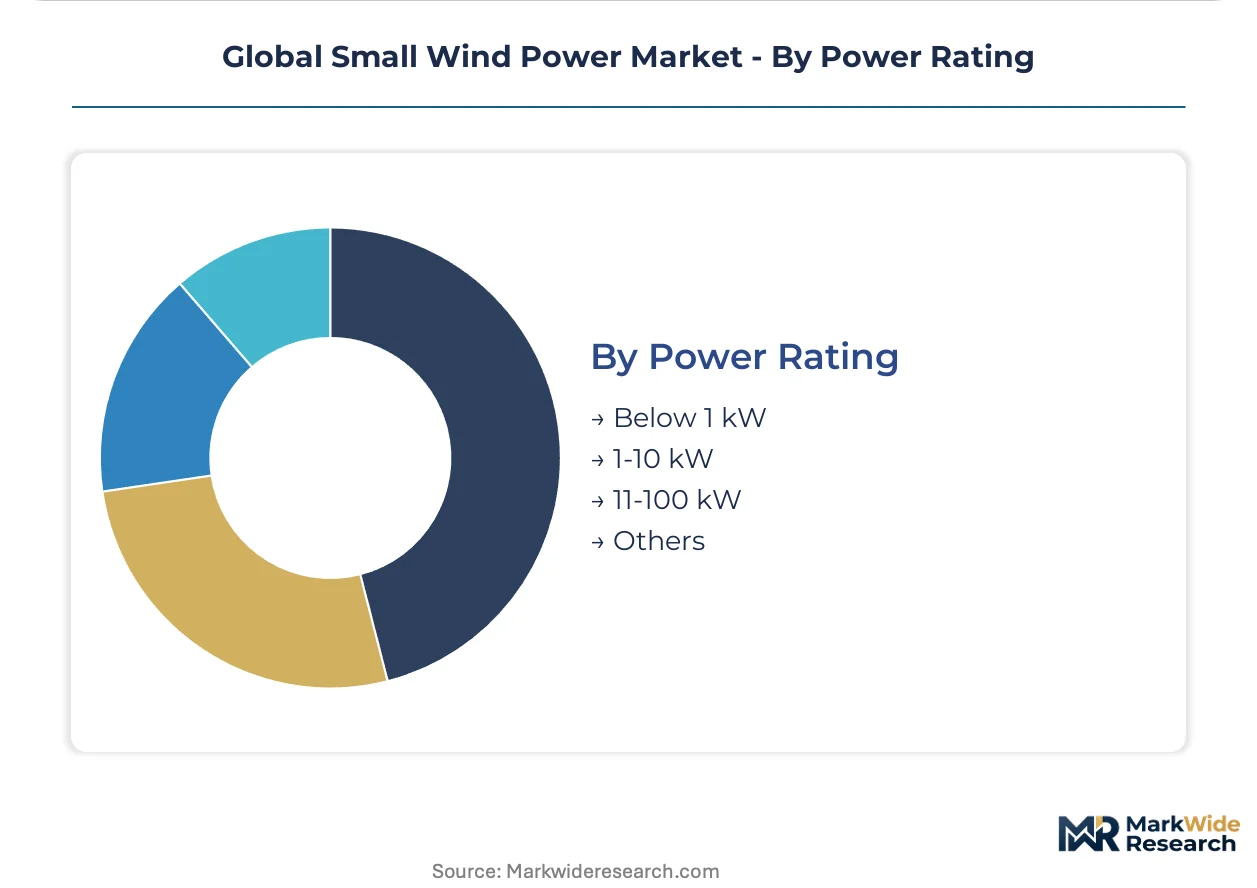
Power Rating:
Scale thresholds determine interconnection complexity and regulatory jurisdiction, with sub-100 kW units accessing streamlined approval pathways in Germany's revised feed-in tariff framework.
- Below 1 kW:Micro-scale units target telecom tower backup and residential balcony applications with minimal permitting requirements.
- 1-10 kW:Distributed agricultural pumping and small commercial loads dominate this bracket, particularly in Indian state electrification programs.
- 11-100 kW:Direct-drive permanent magnet generators eliminate gearbox maintenance for harsh climate operations in Nordic district heating retrofits.
- Others:Custom and emerging scale categories capture airborne wind energy pilots and tethered drone configurations for rapid deployment scenarios.
The 1-10 kW bracket anchors the volume base while the 11-100 kW segment shows the steepest expansion trajectory as commercial microgrid developers consolidate vendor relationships around full-service maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnect underwrites Northern Europe's concentration of small wind innovation, while India's rural electrification corridors and the US Great Plains transmission backbone anchor volume deployment across three distinct regulatory environments.
Germany
Revised feed-in tariffs from the Bundesnetzagentur have restored bankability for sub-100 kW agricultural installations. The EU Green Deal's building efficiency mandates accelerate district heating retrofits in Denmark-bordering Schleswig-Holstein. Hamburg's port logistics cluster hosts blade manufacturing automation trials for Baltic Sea marine applications.
United States
FAA height review protocols near commercial airports constrain rooftop deployment in dense corridors, yet net metering policies in Great Plains states sustain farm and ranch procurement. The EPA's broader clean energy incentive frameworks indirectly support distributed wind through renewable portfolio standards. Iowa's agricultural cooperatives consolidate vendor relationships around full-service maintenance contracts for irrigation pumping systems.
India
Maharashtra and Gujarat state subsidies for farm mechanization expand wind-powered irrigation electrification across the Western Ghats foothills. Central Electricity Authority interconnection guidelines streamline approval pathways for sub-10 kW rural microgrids. Tamil Nadu's coastal manufacturing belt produces composite blade components for export to sub-Saharan African electrification programs.
Denmark
Nearly zero-energy building standards mandate on-site renewable generation in new commercial construction across Copenhagen and Aarhus. Nordic district heating facility retrofits incorporate permanent magnet direct-drive turbines for harsh climate reliability. Odense's maritime engineering cluster develops corrosion-resistant vertical axis designs for aquaculture microgrids.
Sweden
National implementation of EU Green Deal targets tightens building code requirements for distributed generation in Stockholm and Gothenburg commercial developments. Island microgrid operators in the Stockholm archipelago pilot hybrid wind-solar configurations to reduce diesel dependency. Västra Götaland's industrial automation sector supplies power conditioning electronics to German agricultural cooperatives.
Global Small Wind Power Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and geographic reach, producing a tiered structure where scale-driven incumbents anchor premium segments and regional fabricators capture price-sensitive agricultural demand. Three archetypes dominate: permanent magnet direct-drive specialists eliminating gearbox maintenance, vertical axis innovators targeting building-integrated urban niches, and hybrid system integrators bundling wind-solar-storage configurations. Consolidation pressure intensifies through strategic partnerships for blade manufacturing automation and cross-border equipment certification.
Within the direct-drive technology tier, Northern Power Systems Inc. and Primus Windpower exemplify engineering-intensive positioning, while Bergey Windpower Co. anchors the North American farm and ranch segment through decades of horizontal axis specialization. Denmark-based vertical axis specialists and Spanish fabricators occupy building-integrated and maritime application niches where omnidirectional capture geometries reduce noise signatures. German agricultural cooperatives increasingly consolidate procurement around full-service providers offering predictive maintenance subscriptions rather than equipment-only transactions.
| Leading Market Players |
|---|
| Primus Windpower |
| Northern Power Systems Inc. |
| Bergey Windpower Co. |
| Kliux Energies |
| Ryse Energy |
| Aeolos Wind Energy Ltd. |
| New World Wind |
| LuvSide GmbH |
| BORNAY AEROGENERADORES, SL |
| Others |
Value Chain & Pricing Dynamics
Permanent magnet substitution for gearbox-driven generators simultaneously relocates supply gravity toward Chinese rare earth processing clusters and compresses margin structures for European direct-drive specialists. This input transition rewards turbine OEMs with captive magnet sourcing while exposing price-takers to export control volatility.
Pricing Analysis
Volume-discount tiering separates IEC 61400-2 certified units from uncertified alternatives, with German agricultural cooperatives commanding 15-20 point spreads through bundled predictive maintenance subscriptions. Price differentiation hinges on certification grade and after-sales service depth. Cost compression in sub-10 kW brackets intensifies as Indian state subsidies consolidate procurement around lowest-qualified bidders. Residential purchasers in North American farm segments exhibit highest price sensitivity, while Australian mining operators prioritize energy security over capital outlay.
Supply Chain Analysis
China anchors rare earth magnet production, Germany hosts precision blade manufacturing automation, and India supplies composite tower components for sub-Saharan African electrification programs. Permanent magnet generators draw from neodymium-dysprosium supply chains concentrated in Chinese export licensing regimes. Single-source vulnerability in magnet feedstock creates tariff exposure for direct-drive specialists. Distribution runs through EPC contractors and agricultural cooperative procurement committees rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions are expanding faster than hardware transactions as German and Dutch agricultural cooperatives consolidate vendor relationships around performance-guaranteed contracts. This service-attach dynamic restructures competitive economics toward recurring revenue capture.
For Market Incumbents: Consolidate blade manufacturing automation capabilities through backward integration into composite fabrication, neutralizing cost pressure from Chinese component imports. Deepen certification investment under IEC 61400-2 to maintain premium positioning against uncertified Asian competitors expanding through price-aggressive channels.
For New Entrants and Emerging Players: Remote monitoring service gaps in sub-Saharan African rural electrification programs offer white-space entry where incumbents under-serve through equipment-only models. Target portable turbine configurations for disaster relief agencies and frontier mining operators requiring rapid redeployment without permanent civil works. Pursue performance-guaranteed contracting to differentiate from transaction-focused competitors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-service providers with predictive maintenance platforms over pure-play hardware manufacturers. Long-term viability rests on recurring revenue attachment rates exceeding 40% of contract value. Monitor feed-in tariff revision patterns in Germany and subsidy continuity in Indian state programs as inflection indicators for hardware demand cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| Blade Manufacturing Automation | Advanced composite fabrication in Hamburg and Odense clusters reduces production timelines for Baltic marine applications. |
| Hybrid System Integration | Wind-solar-storage bundling compresses battery requirements and extends duty cycles beyond standalone configurations. |
| Permanent Magnet Direct-Drive Adoption | Elimination of gearbox maintenance addresses harsh climate reliability requirements in Nordic district heating retrofits. |
| Predictive Maintenance Platform Development | Remote monitoring subscriptions transfer operational risk to manufacturers and secure recurring revenue streams. |
| Vertical Axis Corrosion Resistance Engineering | Omnidirectional designs capture aquaculture microgrid demand in Danish and Swedish coastal zones. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EIA capacity databases, IEA renewable energy reports, FERC interconnection filings, and Bundesnetzagentur tariff documentation. Primary inputs drew from utility planning officers, IPP project developers, EPC contractors, agricultural cooperative procurement managers, and aftermarket service heads. Bottom-up unit economics triangulated against top-down national electrification program targets.
Segmentation dimensions modeled include turbine architecture, installation configuration, end-user category, and power rating tier across the projection horizon. CAGRs derived from regression analysis against historical deployment velocities, subsidy continuity assumptions, and interconnection queue clearance rates. Forecast inputs incorporated rare earth price volatility indices and composite material cost trajectories.
Forecasts assume regulatory continuity in German feed-in tariff frameworks and Indian state subsidy regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in national electrification program announcements and IEC certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Netherlands Wind Energy Market