
 Lubricants for Wind Turbine Market | 2026-2036
Lubricants for Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricants for Wind Turbine Market Outlook
ISO 4406 cleanliness code certification for wind turbine lubricants is collapsing the supplier field to firms with advanced filtration and blending capabilities. Shell plc leverages its synthetic gear oil portfolio to dominate North Sea offshore installations. ExxonMobil Corporation anchors its position through backward integration into Group III+ base oil production. Klüber Lubrication specializes in high-performance greases for pitch and yaw bearings, competing on formulation precision rather than volume.
Lubricants for wind turbines comprise synthetic and mineral-based fluids engineered for extreme-pressure protection, oxidation stability, and water separation in multi-megawatt drivetrains operating across temperature ranges from -40°C to 150°C. These formulations prevent micropitting in planetary gear stages and extend drain intervals beyond standard industrial lubricants. Gear oils command the largest value pool due to sump volumes exceeding 600 liters per main gearbox, while condition monitoring oils represent the fastest-expanding segment as predictive maintenance protocols spread across energy company fleets. Hydraulic fluids for pitch control systems occupy a mature, price-sensitive niche where OEM specifications limit supplier switching.
REACH registration requirements in Europe and China's GB standards for lubricant biodegradability are forcing reformulation investments that favor integrated compounders over blenders. The EPA's Vessel General Permit in the United States adds compliance layers for offshore lubricant handling and discharge protocols. Stakeholders must monitor how evolving carbon border adjustment mechanisms affect base oil sourcing economics and whether asset managers will consolidate lubricant procurement across multi-site portfolios.
Market Dynamics
ISO 4406 cleanliness code certification is collapsing the supplier field to firms with advanced filtration and blending capabilities, concentrating procurement power among energy companies operating multi-gigawatt fleets across Germany, China, and the United States.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-containing formulations is forcing reformulation toward lower-toxicity polyalphaolefin base stocks, expanding addressable demand for synthetic lubricant specialists.
- Offshore wind farm operators:Turbine sizes exceeding 15 MW are driving sump volume expansion beyond 600 liters per main gearbox, multiplying per-unit lubricant consumption in North Sea installations.
- Predictive maintenance protocols:Condition monitoring oil adoption is accelerating across energy company fleets, creating pull-through demand for sensor-compatible formulations with extended drain intervals.
Market Restraints
- Group III+ base oil supply concentration:Backward integration by major compounders limits independent blender access to high-viscosity index feedstocks, squeezing margin structures for mid-tier suppliers.
- REACH registration timelines:ECHA compliance requirements for novel additive packages extend commercialization cycles by 18-24 months, delaying product launches for reformulated biodegradable grades.
- Mineral oil substitution ceiling:Price-sensitive onshore operators in mature markets continue specifying mineral-based hydraulic fluids for pitch systems, capping synthetic penetration in the largest volume segment.
Strategic Opportunities
- Floating offshore wind:Dynamic cable and platform motion systems in pre-commercial arrays off Scotland and Portugal require specialized grease formulations for pitch bearing reliability in salt-spray environments.
- China's dual carbon goals:MIIT mandates for renewable energy equipment localization are creating procurement preferences for domestic lubricant compounders with GB-standard biodegradable certifications.
- Used oil reclamation services:Asset managers are unbundling drain-and-fill contracts from OEM service agreements, opening direct supplier relationships for reclamation logistics and re-refined base oil闭环 supply.
Industry Challenges
- ISO 4406 certification capacity:Advanced particle counting and filtration infrastructure requires capital deployment exceeding $2 million per blending facility, excluding regional blenders from offshore qualification.
- Grease formulation precision:Pitch and yaw bearing applications demand rheological specifications with tight tolerances, constraining batch-to-batch consistency for non-specialist compounders.
- EPA Vessel General Permit compliance:Offshore lubricant handling and discharge protocols add documentation burdens for service vessels operating in US federal waters, extending logistics cycle times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricants for Wind Turbine Market |
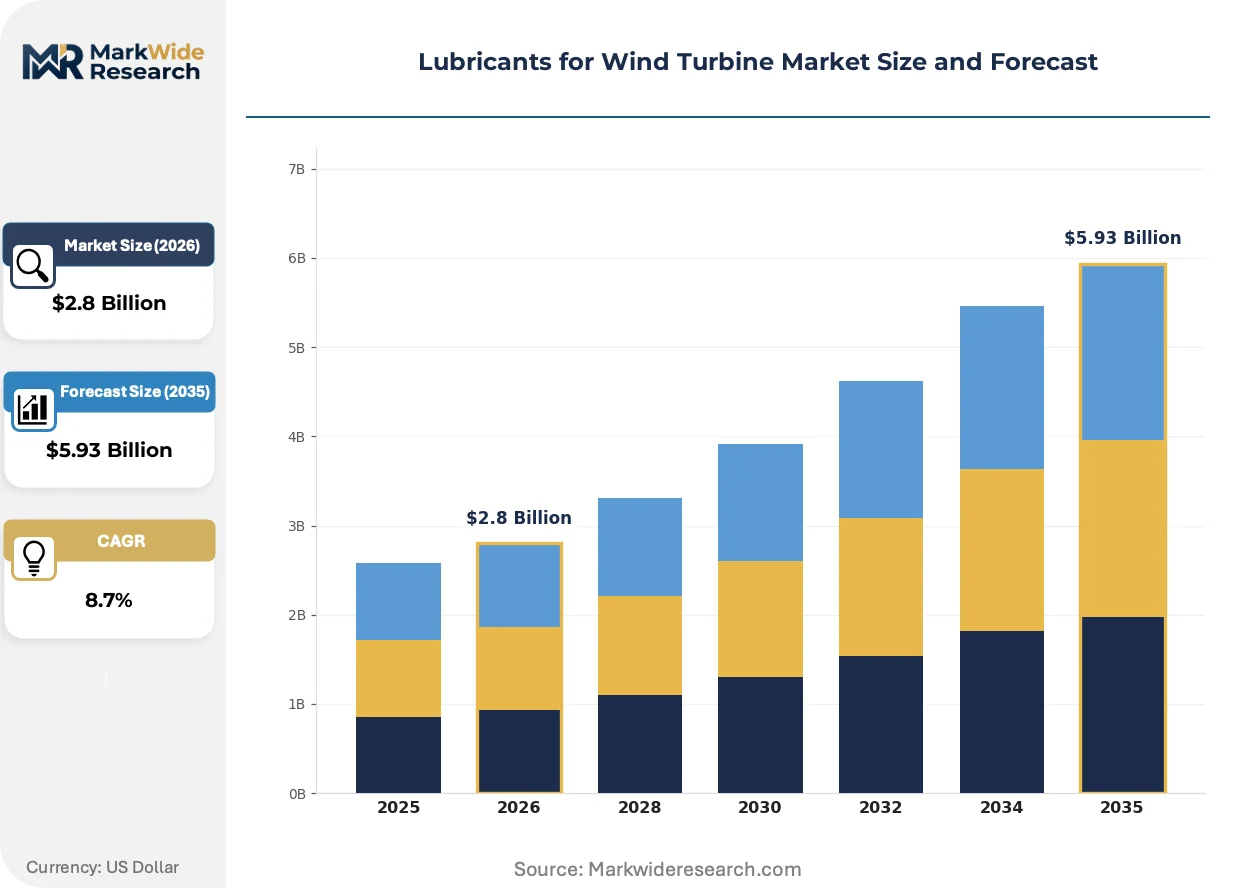
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gear Oils, Hydraulic Fluids, Greases, Condition Monitoring Oils Application: Main Gearbox, Pitch Control, Yaw System, Generator End User: OEMs, Maintenance Providers, Energy Companies, Asset Managers Deployment: Onshore, Offshore, Coastal, Remote |
| Companies Covered | Shell plc, ExxonMobil Corporation, TotalEnergies SE, Chevron Corporation, BP plc, FUCHS Petrolub SE, Klüber Lubrication, Castrol Limited, Phillips 66 Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricants for Wind Turbine Market Strategic Shifts
Synthetic formulation architectures and predictive maintenance integration are restructuring how lubricant value is captured, shifting competition from product specifications to service-embedded performance guarantees.
Polyalphaolefin-based gear oils with optimized additive packages for micropitting resistance are fragmenting the traditional mineral-synthetic segmentation. Offshore operators in the North Sea and Baltic markets are specifying these formulations for 7-year drain intervals, compressing the addressable market for standard mineral products to onshore retrofit applications with shorter maintenance windows.
REACH authorization requirements for zinc-based antiwear additives are compelling reformulation toward ashless phosphorus chemistry. ECHA's sunset date enforcement for legacy hydraulic fluid additives is accelerating R&D spending among European compounders, with Germany's turbine fleet operators demanding compliant stocks ahead of regulatory deadlines to avoid supply disruption.
Energy company procurement departments are consolidating lubricant contracts across multi-site portfolios, displacing turbine OEM-specified supply agreements. This concentration is most visible in the United States, where independent power producers operating assets across Texas, Iowa, and Oklahoma are negotiating enterprise pricing for condition monitoring oil and grease programs directly with compounders, bypassing Vestas and Siemens Gamesa service channels.
Lubricants for Wind Turbine Market Segmentation
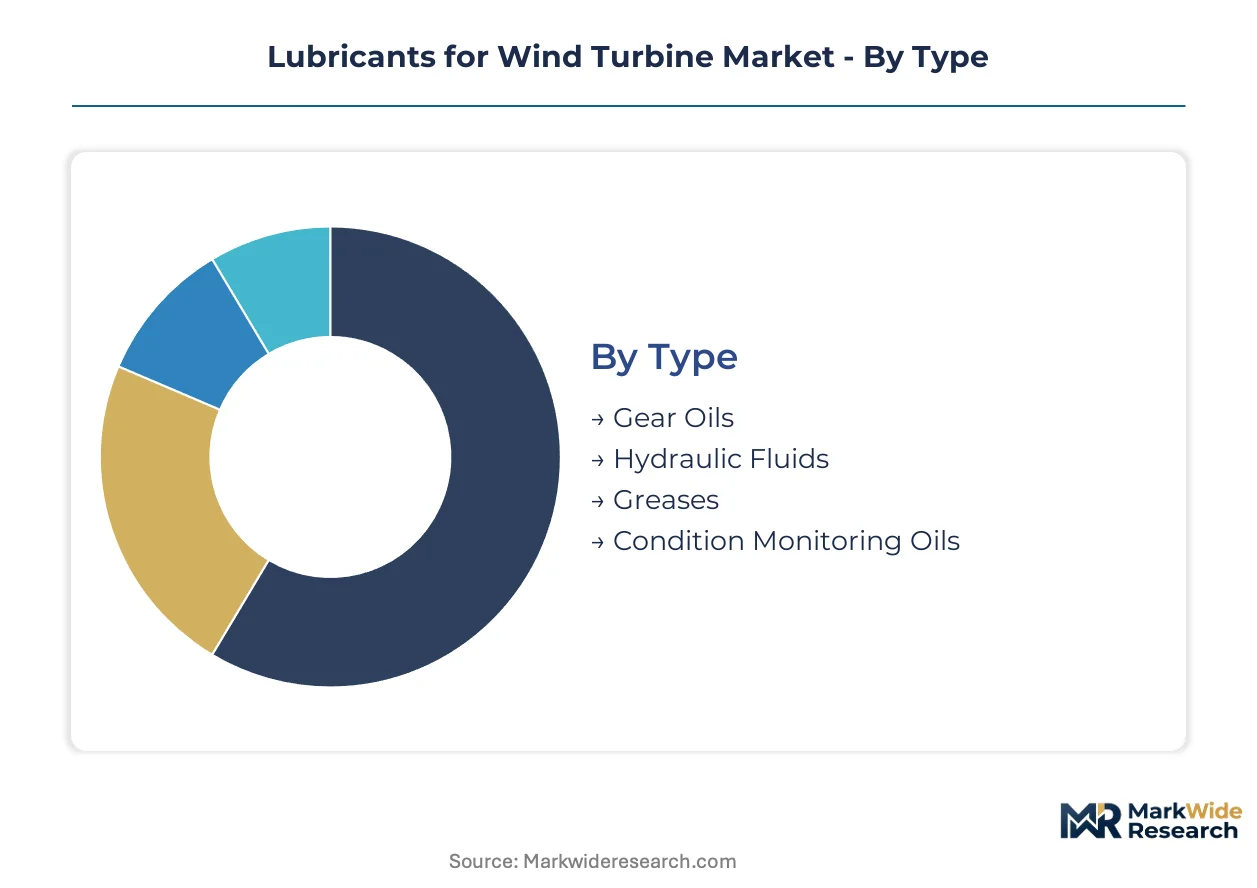
Segmentation in wind turbine lubricants reveals how formulation requirements diverge across drivetrain components and deployment environments. Procurement patterns vary sharply between OEM specification-driven sales and aftermarket service contracts, creating distinct margin profiles for suppliers.
Type:
Gear oils face intensifying substitution pressure from extended-drain synthetic formulations that compress replacement frequency, while mineral-based hydraulic fluids retain incumbent status in cost-sensitive pitch systems.
- Gear Oils:Polyalphaolefin-based formulations dominate multi-megawatt main gearboxes with sump volumes exceeding 600 liters. North Sea offshore operators specify 7-year drain intervals, displacing mineral alternatives in high-reliability applications.
- Condition Monitoring Oils:Sensor-compatible synthetic fluids enable predictive maintenance protocols across energy company fleets. Germany's turbine operators are consolidating enterprise contracts for these formulations ahead of predictive maintenance rollouts.
- Hydraulic Fluids:Mineral-based stocks retain specification in pitch control systems where OEM documentation limits supplier switching.
- Greases:Rheologically precise formulations for pitch and yaw bearings compete on batch consistency rather than volume scale.
Gear oils retain volume leadership; condition monitoring oils hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-specified main gearbox lubricants from commodity-grade hydraulic fluids in auxiliary systems.
- Main Gearbox:Extreme-pressure synthetic formulations prevent micropitting in planetary gear stages operating across -40°C to 150°C temperature ranges. China's MIIT localization mandates are steering procurement toward domestic compounders with GB-standard biodegradable certifications.
- Pitch Control:Hydraulic fluid specifications remain locked by Vestas and Siemens Gamesa OEM service agreements, constraining direct supplier relationships.
- Yaw System:Grease formulations demand tight rheological tolerances for bearing reliability in nacelle rotation mechanisms.
- Generator:Dielectric and bearing lubricants occupy a specialized niche with limited supplier field.
Main gearbox applications command the highest per-unit value; pitch control represents the most volume-constrained segment due to OEM specification lock-in.
End User:
Customer type determines contract structure, with asset managers unbundling services while OEMs retain specification authority.
- Energy Companies:Multi-gigawatt fleet operators in the United States are negotiating enterprise pricing directly with compounders, bypassing turbine OEM service channels. Texas and Iowa independent power producers lead this procurement consolidation.
- Asset Managers:Infrastructure funds operating multi-site portfolios are separating drain-and-fill contracts from OEM agreements, opening direct reclamation logistics relationships.
- OEMs:Vestas and Siemens Gamesa maintain specification control for new turbine lubricant fills and warranty-period service.
- Maintenance Providers:Regional service contractors face margin pressure from ISO 4406 certification requirements exceeding $2 million per blending facility.
Energy companies are gaining procurement leverage fastest; maintenance providers face the steepest capability barriers.
Deployment:
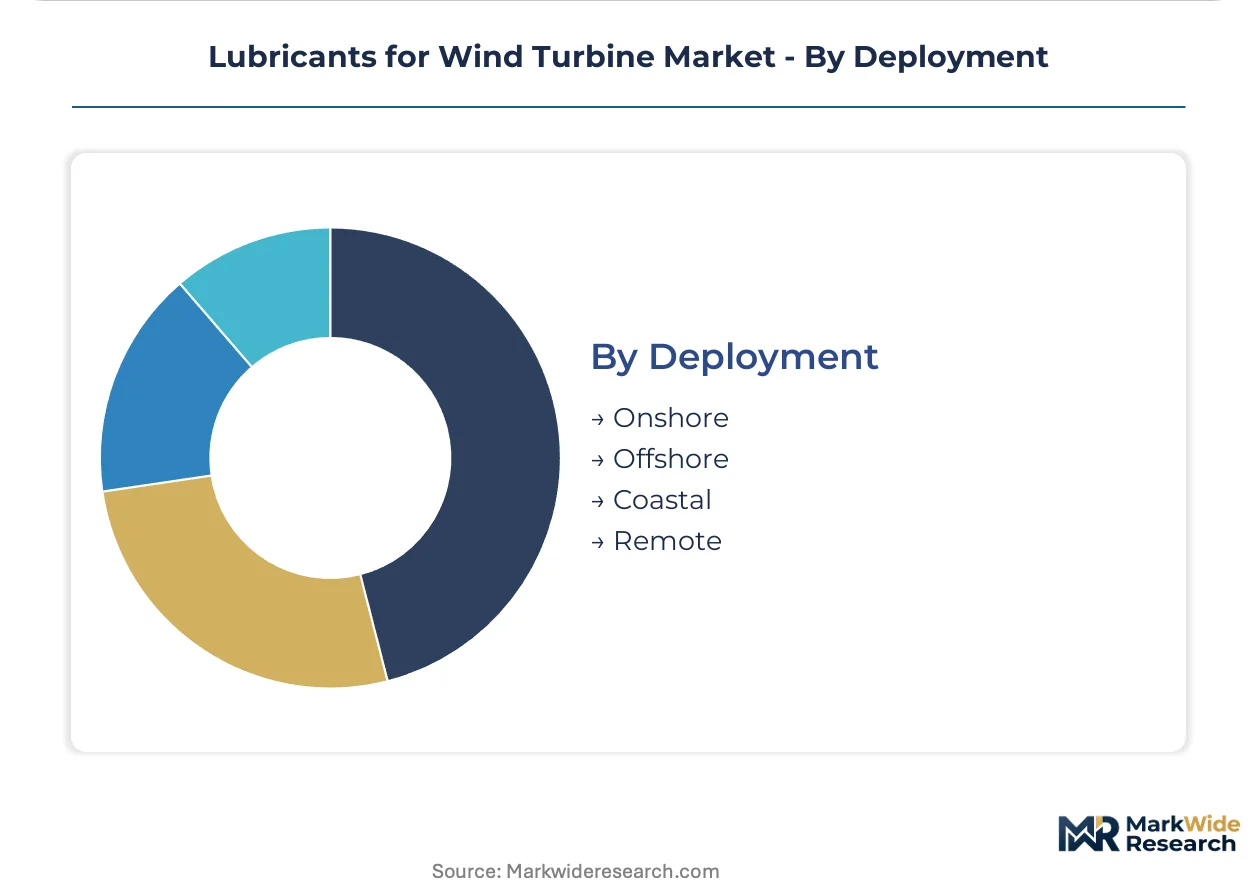
Geography drives formulation severity, with offshore salt-spray exposure demanding specialized grease architectures unavailable to onshore-specified products.
- Offshore:Dynamic platform motion systems in Scotland and Portugal pre-commercial arrays require salt-spray-resistant grease formulations. EPA Vessel General Permit compliance adds documentation burdens for US federal waters operations.
- Onshore:Mature markets in Germany and the United States specify mineral-based hydraulic fluids for pitch systems, capping synthetic penetration in the largest volume segment.
- Coastal:Moderate corrosion protection requirements bridge onshore and offshore specification tiers.
- Remote:Extended drain interval specifications prioritize logistics efficiency over unit cost in Arctic and desert installations.
Offshore commands the highest formulation premium; onshore retains absolute volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Esbjerg in Denmark anchors North Sea offshore wind logistics, while China's Jiangsu coastal grid interconnection underwrites the world's largest turbine installation base. These infrastructure assets concentrate lubricant procurement decisions among multi-gigawatt fleet operators.
United States
Independent power producers in Texas and Iowa operate multi-site wind portfolios exceeding 20 GW combined. The EPA's Vessel General Permit governs offshore lubricant handling in federal waters, extending documentation cycles for service logistics. The Gulf Coast corridor hosts blending facilities supplying synthetic gear oils for Great Plains installations.
Germany
ECHA's REACH authorization timelines for zinc-based antiwear additives compel 18-24 month reformulation cycles among domestic compounders. The country's national chemical regulator enforces sunset dates for legacy hydraulic fluid additives. Industrial clusters in Hamburg and Bremen concentrate blending capacity serving North Sea offshore arrays.
China
MIIT mandates for renewable energy equipment localization steer procurement toward domestic compounders with GB-standard biodegradable certifications. The Yangtze River Delta hosts manufacturing bases for 15+ MW turbines requiring sump volumes exceeding 600 liters. Jiangsu province leads installed capacity additions driving synthetic lubricant consumption.
United Kingdom
Scotland's pre-commercial floating offshore arrays demand salt-spray-resistant grease formulations for dynamic platform motion systems. The country's national environmental regulator enforces discharge protocols for service vessels operating in territorial waters. Aberdeen's energy supply chain cluster supports North Sea lubricant logistics infrastructure.
Lubricants for Wind Turbine Market Competitive Environment
Listed leaders compete with private specialists across formulation certification tiers, concentrating procurement leverage among energy companies with multi-gigawatt fleets. The supplier field collapses around ISO 4406 cleanliness code requirements exceeding $2 million per blending facility. Three archetypes dominate: integrated oil majors with backward integration into base oil production, synthetic specialists competing on extended drain intervals, and regional blenders serving price-sensitive onshore retrofit markets. Capacity expansion and strategic partnerships represent the primary competitive vectors as compounders seek REACH-compliant additive supply.
Within the integrated major tier, Shell plc and ExxonMobil Corporation exemplify divergent strategic positions. Shell anchors its presence through synthetic gear oil portfolios specified for North Sea offshore installations. ExxonMobil occupies a position defined by captive supply of Group III+ base oil feedstocks. Klüber Lubrication represents the specialist archetype, competing on formulation precision for pitch and yaw bearing applications rather than volume scale.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Chevron Corporation |
| BP plc |
| FUCHS Petrolub SE |
| Klüber Lubrication |
| Castrol Limited |
| Phillips 66 Company |
| Others |
Value Chain & Pricing Dynamics
Blending facility scale economies exceeding $2 million per ISO 4406 certification site concentrate supply among integrated compounders while compressing price floors for regional blenders serving onshore retrofit markets. This capacity barrier fragments procurement leverage across energy company fleets, OEM specification channels, and independent service contractors.
Pricing Analysis
Volume-discount tiering structures separate enterprise contracts for multi-gigawatt fleet operators from spot purchases by regional maintenance providers. Price differentiation rests on ISO 4406 cleanliness certification grade and REACH-compliant additive package specifications. Pricing pressure stems from Group III+ base oil supply concentration among backward-integrated majors, squeezing mid-tier blender margins. Energy companies with consolidated procurement across Texas and Iowa portfolios exhibit lowest price sensitivity; independent service contractors face highest cost compression.
Supply Chain Analysis
Inventory lead times for specialized additive packages extend commercialization cycles by 18-24 months under ECHA registration timelines. Supply concentrates in Germany, China, and the United States, where Hamburg industrial clusters, Jiangsu manufacturing bases, and Gulf Coast blending facilities anchor production. Raw material dependencies include polyalphaolefin base stocks, ashless phosphorus antiwear chemistry, and high-viscosity index Group III+ feedstocks. Single-source vulnerability runs through REACH-authorized additive suppliers. Distribution feeds from compounder blending facilities through OEM service channels and direct asset manager contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as predictive maintenance protocol adoption unbundles lubricant procurement from OEM service agreements, creating specialist niches in condition monitoring oil formulations and reclamation logistics.
For Market Incumbents: Secure ISO 4406 certification capacity expansion in Germany and China to defend against domestic compounder localization mandates. Anchor backward integration into Group III+ base oil production to preserve margin structures against feedstock supply concentration. Prioritize sensor-compatible formulation R&D to capture predictive maintenance pull-through demand.
For New Entrants and Emerging Players: Lead with used oil reclamation services targeting asset managers unbundling drain-and-fill contracts from Vestas and Siemens Gamesa agreements. Target floating offshore wind pre-commercial arrays off Scotland and Portugal with salt-spray-resistant grease formulations. Pursue direct procurement relationships with infrastructure funds operating multi-site portfolios.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic formulation specialists with extended-drain interval portfolios serving North Sea offshore operators. Long-term viability centers on REACH-compliant additive supply security and biodegradable certification positioning. Monitor ECHA sunset date enforcement for legacy hydraulic fluid additives as inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group III+ feedstock supply secures margin structure against supply concentration in Germany and China. |
| ISO 4406 Certification Investment | Advanced particle counting infrastructure qualifies suppliers for North Sea offshore procurement specifications. |
| REACH-Compliant Additive Reformulation | Ashless phosphorus chemistry transition ahead of ECHA sunset dates avoids supply disruption for European turbine fleets. |
| Used Oil Reclamation Service Launch | Direct asset manager relationships bypass OEM service channels and capture circular supply economics. |
| Sensor-Compatible Formulation Development | Predictive maintenance protocol integration enables enterprise pricing with energy company fleet operators. |
Study Parameters
Initial hypotheses were tested against primary input from lubricant procurement managers at energy companies, blending facility technical directors, and aftermarket service contractors, then refined through secondary validation against customs trade data, ECHA registration databases, and SEC filings from integrated oil majors. Bottom-up triangulation across turbine installation databases and top-down verification through base oil production capacity estimates anchored volume and value outputs.
Variance decomposition across formulation type, deployment environment, and end-user procurement channel structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against installed capacity addition forecasts and drain interval extension trends. Modeled inputs included polyalphaolefin substitution rates for mineral gear oils and predictive maintenance protocol adoption curves across German and US turbine fleets.
Forecasts assume regulatory continuity in EU REACH authorization timelines and China's GB standards for lubricant biodegradability; material policy shifts would require re-modeling. Commodity price volatility in base oil feedstocks and floating offshore wind commercialization delays represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market