
 Wind Turbine Forged Tower Flange Market | 2026-2036
Wind Turbine Forged Tower Flange Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Forged Tower Flange Market Insights
High-strength alloy steel is decoupling from traditional carbon steel specifications in tower flange production, enabling thinner wall sections without sacrificing fatigue resistance. Bharat Forge leverages integrated forging and machining operations to serve both onshore and offshore tower programs. Iraeta Energy Equipment anchors its position through dedicated heat treatment lines for large-diameter rings up to eight meters. Thyssenkrupp differentiates via metallurgical R&D on offshore-grade alloys with enhanced corrosion performance.
A wind turbine forged tower flange is a rolled or pressed ring component, typically manufactured from normalized or quenched-and-tempered carbon or alloy steel, that connects tubular tower sections and transmits rotor-nacelle assembly loads to the foundation. These flanges require Charpy V-notch impact values exceeding 27 joules at minus 20 degrees Celsius and ultrasonic testing per EN 10228-3 to ensure structural integrity across 25-year design lives. Flange Rings dominate product type value pools due to their irreplaceable role in every tower joint, while Custom Components represent the fastest-growing segment as OEMs specify proprietary bolt circle geometries for next-generation offshore machines. Alloy Steel commands premium positioning over Carbon Steel as turbine hub heights climb and dynamic loading cycles intensify.
The EU F-Gas Regulation and CE marking under the Machinery Directive govern material traceability and welding compatibility for flanges installed in European waters. China's GB standards and NMPA-equivalent pressure vessel oversight shape domestic procurement protocols for tower fabricators. India's BIS certification requirements for structural steel imports influence sourcing decisions for developers under the PLI scheme for renewable energy equipment. Stakeholders must monitor evolving nacelle mass trajectories and corresponding flange load ratings as turbine OEMs push beyond 15 megawatt offshore platforms.
Market Dynamics
The central structural force reshaping wind turbine forged tower flange supply is the divergence between onshore and offshore load specifications, with offshore developers demanding progressively larger ring diameters that strain existing forge press capacities.
Growth Catalysts
- Offshore hub height escalation:Turbine OEMs are specifying flanges above six meters diameter for 15 MW-plus nacelles, pulling capacity investments toward heavy-ring forging lines.
- F-Gas Regulation traceability mandates:The EU framework now requires full material certification chains for tower components, locking qualified European forges into long-term supply relationships.
- China dual carbon goals:Domestic wind installation targets under the 14th Five-Year Plan are absorbing forge output that previously served export markets.
Market Restraints
- Scrap alloy steel price volatility:Nickel and molybdenum input costs swing 15-40 percent annually, compressing margin visibility on multi-year tower supply contracts.
- Press capacity concentration:Rings above eight meters diameter rely on a handful of Chinese and European forges, creating single-source vulnerability for offshore developers.
- EN 10228-3 ultrasonic testing:The European standard's defect rejection thresholds force higher scrap rates in large-diameter quenched-and-tempered rings.
Strategic Opportunities
- Floating foundation flange architectures:Tension-leg and semi-submersible platforms require specialized load distribution geometries not yet standardized, opening design partnerships.
- India PLI scheme localization:The production-linked incentive framework for renewable energy equipment creates captive demand for domestic flange forging investments.
- Digital thread integration:Blockchain-enabled material traceability from melt to installation is integrating with GB standards compliance in China, differentiating premium suppliers.
Industry Challenges
- Heat treatment technician scarcity:Normalizing and quenching operations for 100-ton-plus rings require specialized furnace control expertise concentrated at retiring European workforces.
- Offshore certification timelines:DNV-ST-0126 type approval for new flange geometries extends 18-24 months, misaligning with compressed turbine development cycles.
- Machining-fixture capital intensity:Bolt circle finishing for proprietary OEM patterns demands dedicated CNC ring mills with 30-million-dollar entry costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Forged Tower Flange Market |
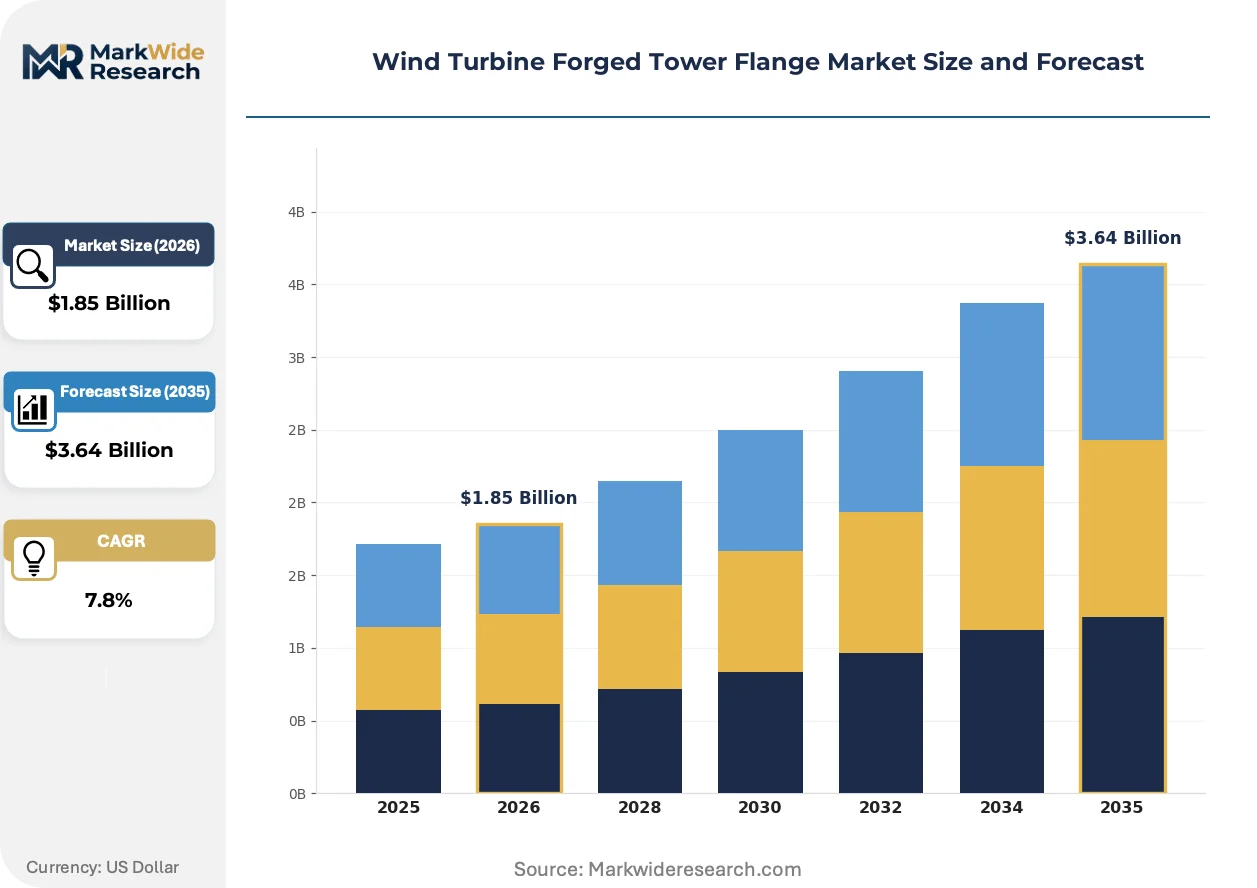
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flange Rings, Blanks, Fittings, Custom Components Material: Carbon Steel, Alloy Steel, Stainless Steel, Others Manufacturing Stage: Forging, Machining, Heat Treatment, Finishing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Assembly Plants |
| Companies Covered | Bharat Forge, China First Heavy Industries, Scot Forge, Thyssenkrupp, Iraeta Energy Equipment, Ellwood Group, CHW Forge, US Forged Rings Inc., CS Wind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Forged Tower Flange Market Trends and Innovations
Active innovation in tower flange manufacturing centers on metallurgical performance optimization, digital quality assurance, and supply chain proximity realignment. These shifts are compressing traditional specifications while expanding performance envelopes.
Quenched-and-tempered high-strength low-alloy steel is integrating into offshore tower specifications, replacing normalized carbon grades in load-critical joints. Developers in the North Sea and Baltic markets are mandating the upgrade for 20-year fatigue life guarantees. The transition is compressing acceptable supplier pools to forges with dedicated heat treatment infrastructure.
The EU F-Gas Regulation's material traceability extensions are forcing documentation system overhauls across European tower supply chains. Weld compatibility certification now requires batch-level chemical analysis submission to classification societies. Offshore project developers in German and Danish waters are responding by consolidating procurement around vertically integrated forge-to-tower fabricators.
Buyer consolidation among turbine OEMs is compressing flange supplier negotiation leverage, with three manufacturers controlling 80 percent of offshore nacelle orders. Long-term supply agreements now bundle machining, surface treatment, and logistics under fixed-price escalators. The pattern is most pronounced in China, where domestic tower fabricators are absorbing forge capacity through equity stakes.
Wind Turbine Forged Tower Flange Market Segmentation
Tower flange procurement decisions split across technical specifications, manufacturing capabilities, and supply chain positioning. Each segmentation dimension reveals distinct margin structures and buyer power dynamics that reshape competitive strategy.
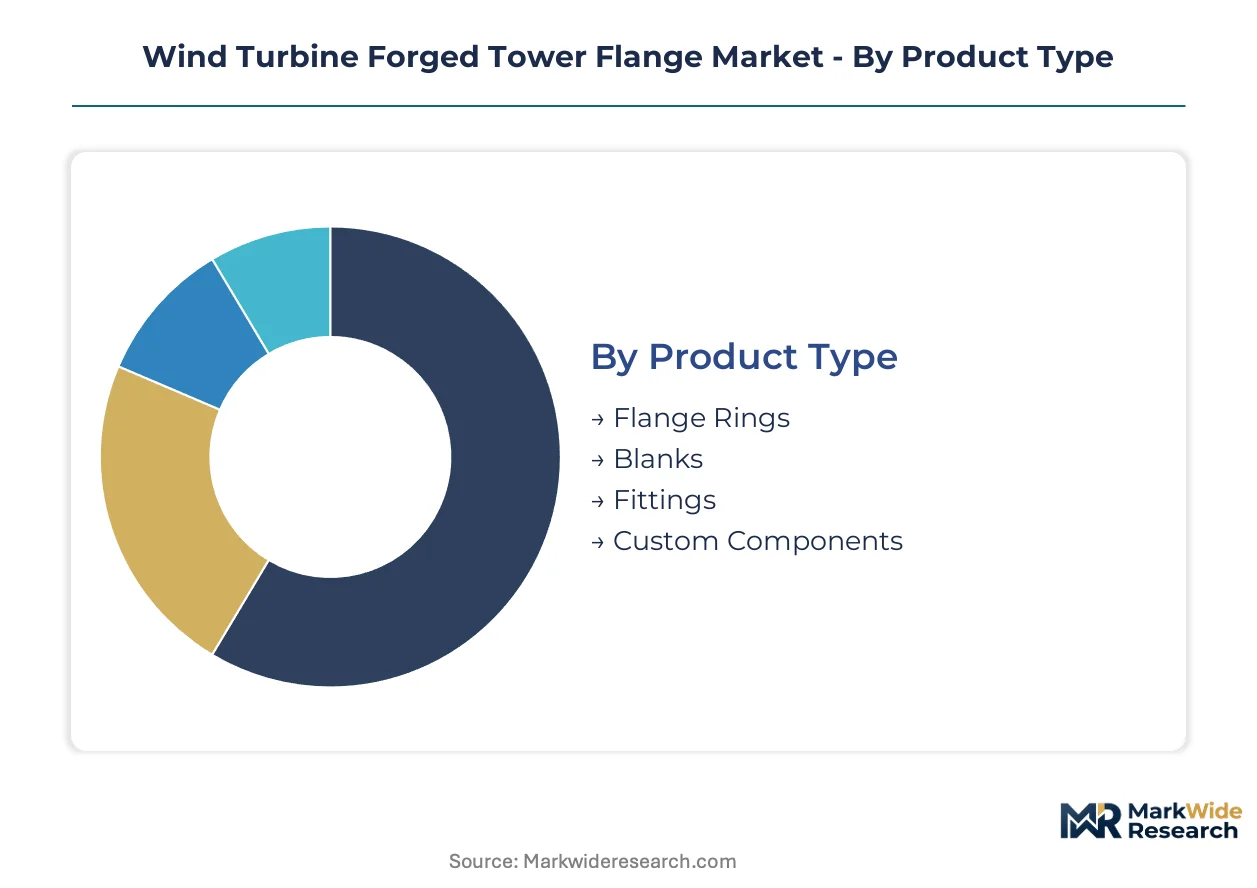
Product Type:
Buyers prioritize load-bearing integrity and bolt circle precision when selecting flange formats for tower joint configurations.
- Flange Rings:Rolled or pressed circular steel components form the structural backbone of every tower section joint, requiring normalized or quenched-and-tempered processing to meet Charpy V-notch impact thresholds. Demand concentrates with offshore developers in the North Sea and Baltic waters where 15 MW-plus nacelles mandate six-meter-plus diameters that strain forge press availability.
- Custom Components:Proprietary bolt circle geometries and load distribution patterns specified by turbine OEMs for next-generation floating platforms. These configurations gain share fastest as Vestas, Siemens Gamesa, and Goldwind differentiate tower architectures.
- Blanks:Unmachined forged ring preforms supplied to tower fabricators with in-house finishing capability.
- Fittings:Secondary connection elements including adapter rings and transition pieces for hybrid tower designs.
Volume sits with Flange Rings; growth tilts toward Custom Components.
Material:
Material selection trades off unit cost against fatigue life requirements as hub heights climb and dynamic loading cycles intensify.
- Alloy Steel:High-strength low-alloy grades with nickel and molybdenum additions enable thinner wall sections without sacrificing 25-year fatigue resistance. Procurement concentrates among offshore developers under DNV-ST-0126 certification paths where 20-year performance guarantees are mandatory.
- Carbon Steel:Normalized grades dominate onshore tower specifications where load ratings remain moderate and cost sensitivity runs higher. Chinese tower fabricators under GB standards absorb the majority of global carbon steel flange output.
- Stainless Steel:Corrosion-resistant grades for coastal onshore installations with aggressive atmospheric exposure.
- Others:Experimental clad materials and hybrid metal matrix composites under evaluation for floating foundation applications.
Alloy Steel commands premium positioning; Carbon Steel retains volume dominance.
Manufacturing Stage:
Outsourcing depth varies by buyer scale, with integrated tower fabricators capturing value through captive forging and machining operations.
- Forging:Ring rolling and press forming of raw steel into rough cylindrical preforms. Capacity concentrates at Bharat Forge, Iraeta Energy Equipment, and a limited cohort of Chinese and European forges capable of eight-meter-plus diameters.
- Heat Treatment:Normalizing and quenching-and-tempering operations that determine final mechanical properties. Dedicated furnace lines for 100-ton-plus rings represent the primary bottleneck in offshore-grade supply chains.
- Machining:CNC finishing of bolt circles and sealing surfaces to OEM-specific tolerances.
- Finishing:Surface preparation, coating application, and protective packaging for maritime transport.
Forging captures the value pool; Heat Treatment constrains expansion.
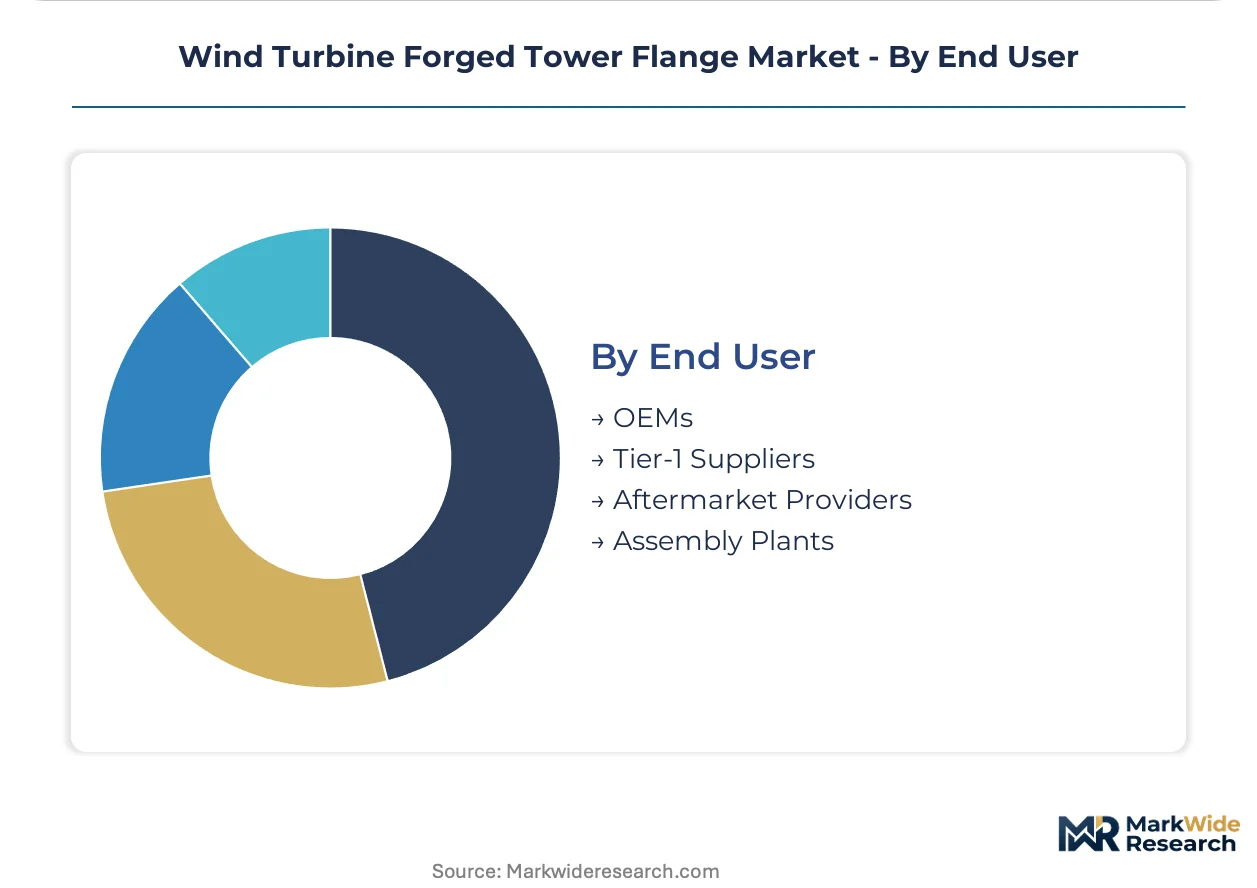
End User:
Procurement authority is consolidating as turbine OEMs absorb tower supply chain tiers through equity stakes and long-term agreements.
- OEMs:Vestas, Siemens Gamesa, Goldwind, and Envision specify flange geometries directly and increasingly source through captive forge relationships. Their technical teams mandate EN 10228-3 ultrasonic testing and full material traceability under EU F-Gas Regulation extensions.
- Tier-1 Suppliers:Specialized tower fabricators including CS Wind, Windar Renovables, and Qingdao Pingcheng purchase flanges for machining and assembly into finished tower sections.
- Aftermarket Providers:Replacement flange suppliers serving repowering projects and structural repair programs.
- Assembly Plants:Regional tower construction facilities with limited in-house forging capability.
OEMs concentrate procurement leverage; Tier-1 Suppliers face margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along China's coastal provinces concentrate forging capacity for both domestic turbine OEMs and export markets. The EU F-Gas Regulation and Renewable Energy Directive are tightening material traceability requirements across European waters. India's PLI scheme for renewable energy equipment is redirecting investment toward domestic flange production.
China
Domestic forge capacity under the 14th Five-Year Plan dual carbon goals is absorbing output that previously served export markets. GB standards and NMPA-equivalent pressure vessel oversight shape procurement protocols for tower fabricators in Shandong and Jiangsu provinces. Qingdao and Yantai host concentrated ring-rolling operations serving Goldwind and Envision nacelle programs.
Germany
North Sea offshore developers are mandating six-meter-plus diameter flanges for 15 MW turbine platforms under DNV-ST-0126 certification paths. The EU F-Gas Regulation requires full material certification chains, locking qualified forges into long-term supply relationships. Rostock and Bremerhaven anchor fabrication clusters where vertically integrated tower suppliers consolidate procurement.
United States
Gulf Coast and Great Lakes offshore lease rounds are pulling demand for heavy-ring forging lines capable of handling higher load ratings. FERC interconnection queues and IRA production tax credits are accelerating project timelines. Texas and Ohio manufacturing corridors are absorbing carbon steel flange volumes for onshore repowering programs.
India
The PLI scheme for renewable energy equipment is creating captive demand for domestic flange forging investments under CEA grid integration mandates. BIS certification requirements for structural steel imports influence sourcing decisions for developers. Gujarat and Tamil Nadu industrial zones are emerging as fabrication hubs for captive tower supply.
Denmark
Baltic Sea floating foundation pilots are specifying proprietary bolt circle geometries not yet standardized, opening design partnerships with specialized forges. CE marking under the Machinery Directive governs welding compatibility for components installed in Danish waters. Esbjerg maintains its position as North European logistics hub for offshore tower assembly.
Wind Turbine Forged Tower Flange Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated forge-to-tower fabricators capturing premium positioning in offshore markets. The supplier base concentrates around heavy-ring forging capacity above eight meters diameter, where press availability constrains entry. Three archetypes dominate: vertically integrated steel-forge conglomerates with captive heat treatment infrastructure; specialized ring-rolling operations serving multiple OEM programs; and tower fabricators with backward integration into forging operations. Capacity expansion and long-term supply agreement bundling represent the primary competitive moves, particularly in China where equity stakes are absorbing forge output.
Among the integrated steel-forge conglomerates, Bharat Forge and Thyssenkrupp occupy positions exemplifying metallurgical R&D and dedicated heat treatment capabilities for offshore-grade alloys. Iraeta Energy Equipment represents the specialized ring-rolling archetype with focused infrastructure for large-diameter rings. These three entities anchor the competitive structure without exhaustive claims about specific market positions or strategic actions.
| Leading Market Players |
|---|
| Bharat Forge |
| China First Heavy Industries |
| Scot Forge |
| Thyssenkrupp |
| Iraeta Energy Equipment |
| Ellwood Group |
| CHW Forge |
| US Forged Rings Inc. |
| CS Wind |
| Others |
Pricing and Supply Chain Analysis
Quenched-and-tempered processing for offshore-grade alloys is simultaneously elevating heat treatment costs and concentrating supplier power among forges with dedicated furnace infrastructure. The EU F-Gas Regulation's traceability mandates are amplifying this effect by locking qualified European suppliers into premium-priced long-term contracts with North Sea developers.
Pricing Analysis
Volume sits with normalized carbon steel flanges for onshore towers, while margins concentrate in quenched-and-tempered alloy grades for offshore applications. Price differentiation hinges on DNV-ST-0126 certification tier and proprietary bolt circle machining complexity specified by Vestas, Siemens Gamesa, and Goldwind. Cost compression in carbon steel tiers is intensifying as Chinese tower fabricators consolidate procurement through equity stakes in domestic forges. Tier-1 tower fabricators exhibit highest price sensitivity due to fixed-price escalator contracts with OEMs, while offshore developers under 25-year performance guarantees demonstrate lowest sensitivity.
Supply Chain Analysis
Heat treatment technician scarcity in Germany and Denmark is constraining expansion of offshore-grade flange output despite press capacity availability. Forging capacity concentrates in China, Germany, and India, with eight-meter-plus diameter rings drawing from a limited cohort of Chinese and European facilities. Raw material dependencies rest on nickel and molybdenum alloy additions, scrap steel quality grades, and specialized quenching media formulations. Single-source vulnerability pervades the eight-meter-plus segment where fewer than ten forges operate qualified lines. Distribution runs through vertically integrated tower fabricators in Rostock, Bremerhaven, and Qingdao that bundle machining, surface treatment, and maritime logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wind turbine forged tower flange market functions as a cost-of-compliance arena where the EU F-Gas Regulation and DNV-ST-0126 certification paths erect formidable barriers to entry, entrenching incumbents with established traceability systems and heat treatment infrastructure.
For Market Incumbents: Extend certification coverage into emerging floating foundation geometries before standardization locks in incumbent designs. Deepen backward integration into nickel and molybdenum supply channels to buffer scrap alloy volatility that compresses margins on multi-year contracts. Lock in long-term capacity reservations with heat treatment specialists facing retiring workforces in European manufacturing clusters. For New Entrants and Emerging Players: The premium-to-economy price gap in flange rings offers entry space through specialized heat treatment services rather than forging capacity. Target India's PLI scheme localization incentives where CEA grid integration mandates are creating captive demand for domestic flange production. Pursue design partnerships with Baltic Sea floating foundation pilots specifying proprietary load distribution geometries not yet standardized. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by turbine OEMs seeking captive forge capacity, as demonstrated by Goldwind and Envision equity stakes in Chinese suppliers. Five-to-ten year viability hinges on positioning within offshore-grade alloy supply chains rather than carbon steel commoditization. Watch nacelle mass trajectories beyond 15 MW platforms as the inflection signal for flange load rating escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Treatment Infrastructure Expansion | Dedicated quenching lines for 100-ton-plus rings differentiate offshore-grade suppliers under DNV-ST-0126. |
| Backward Integration into Alloy Supply | Captive nickel and molybdenum sourcing buffers margin compression from scrap steel price volatility. |
| Floating Foundation Design Partnerships | Early collaboration on tension-leg and semi-submersible geometries establishes proprietary specification influence. |
| Digital Thread Traceability Implementation | Blockchain-enabled material certification from melt to installation differentiates premium suppliers under EU F-Gas Regulation. |
| India PLI Scheme Localization Investment | CEA grid integration mandates under renewable equipment incentives create captive demand for domestic forging capacity. |
Research Methodology
Document review covered customs and trade data, SEC filings from listed forge operators, DNV and classification society certification registries, and EU regulatory filings under F-Gas Regulation extensions, complemented by interviews with procurement directors at tower fabricators, heat treatment operations managers, offshore project development executives, and metallurgical R&D leads. Secondary validation drew from EN 10228-3 ultrasonic testing standards documentation, GB standards compliance frameworks, and project development databases tracking nacelle mass trajectories. Bottom-up unit economics and top-down market sizing were triangulated against capacity utilization data from heavy-ring forging lines.
Segment-level outputs across product type, material grade, manufacturing stage, and end-user category were generated through the projection horizon using demand elasticity models calibrated to turbine OEM procurement patterns. CAGRs were derived from install-base growth trajectories, repowering cycle timing, and flange replacement rates across onshore and offshore applications. Forecast inputs incorporated nacelle mass escalation curves, hub height trajectories, and floating foundation deployment schedules.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time forge capacity utilization data and proprietary OEM specification timelines introduce uncertainty bands around offshore-grade volume projections. Forecasts reflect assumptions regarding certification timeline adherence, alloy input cost stabilization, and technician workforce continuity in European heat treatment operations. A small set of triggers—nacelle mass breakthroughs beyond 20 MW, F-Gas Regulation enforcement intensity shifts, and India PLI scheme allocation revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
South Korea Wind Energy Market