
 Thailand Wind Energy Market | 2026-2036
Thailand Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Wind Energy Market Analytics
A shortage of certified wind turbine technicians is unwinding project timelines across Thailand's northeastern provinces. Electricity Generating PCL leverages its integrated utility model to secure long-term power purchase agreements. Siemens Gamesa Renewable Energy SA anchors its regional service hub in Thailand to support growing Southeast Asian installations. Gunkul Engineering competes through local manufacturing partnerships that reduce import dependency for tower and foundation components.
Thailand wind energy encompasses the conversion of kinetic wind resources into grid-connected electricity through horizontal-axis turbines typically rated between 2 MW and 4.5 MW, with rotor diameters exceeding 120 meters optimized for low-to-moderate wind regimes. These installations serve primarily to displace gas-fired generation in Thailand's national power mix and to supply direct renewable energy to industrial estates under corporate power purchase structures. Horizontal axis technology dominates operational capacity given its higher efficiency and established supply chain, while offshore development remains nascent pending seabed assessment and transmission infrastructure planning. The industrial end user segment commands premium attention as factory clusters seek 24/7 renewable supply contracts independent of utility tariff fluctuations.
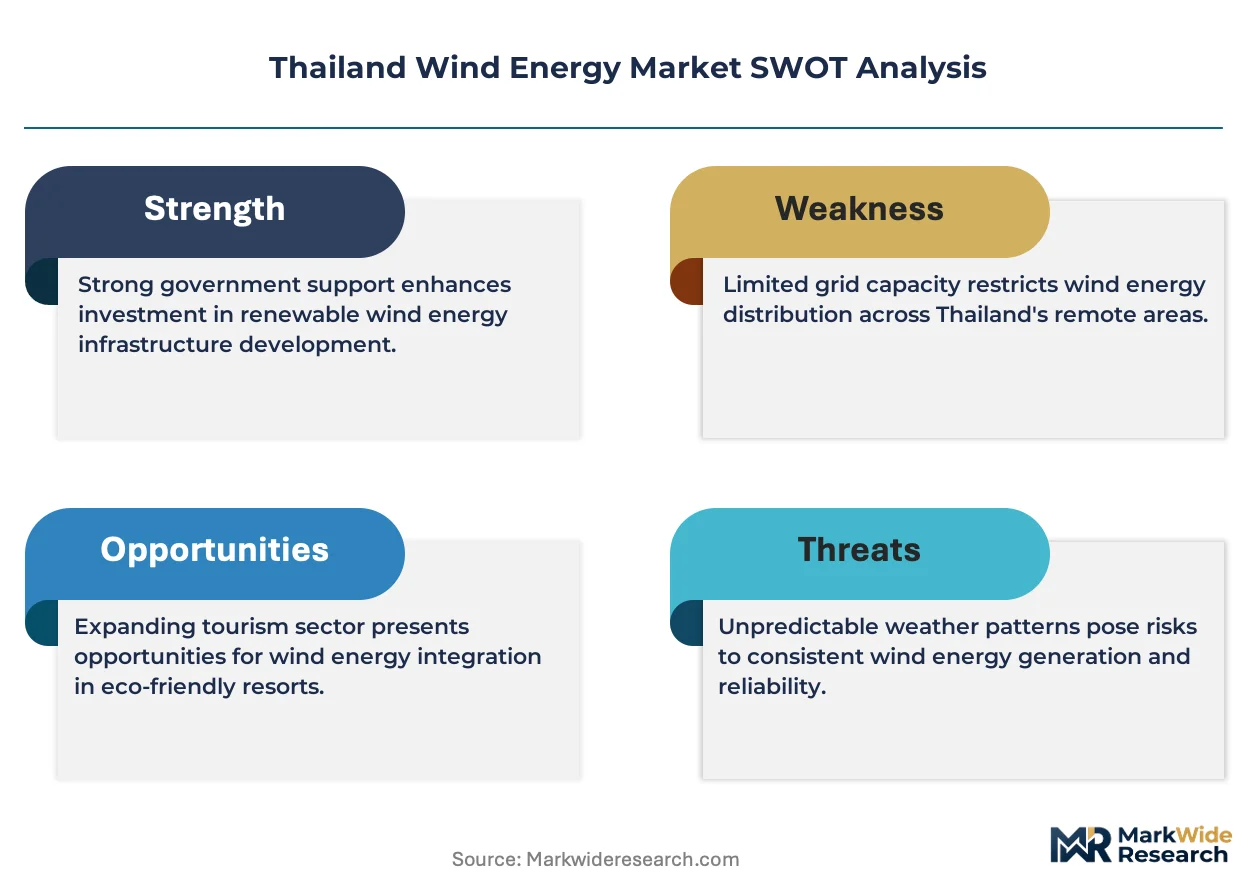
Thailand's Department of Alternative Energy Development and Efficiency administers feed-in tariff frameworks and resource zone classifications that determine project bankability, while the Energy Regulatory Commission governs grid connection standards and power purchase agreement terms. The Ministry of Energy's Power Development Plan revisions shape long-term capacity auction schedules and domestic content requirements. Stakeholders must monitor transmission queue congestion in the Northeast and evolving land-use restrictions that could redirect development toward coastal or offshore prospects.
Market Dynamics
Feed-in tariff revisions by Thailand's Department of Alternative Energy Development and Efficiency are compressing developer margins while accelerating project clustering in wind-rich northeastern provinces. This regulatory recalibration is forcing capital reallocation toward transmission-adjacent sites and integrated utility partnerships.
Growth Catalysts
- Power Development Plan capacity auctions:Scheduled procurement rounds under Thailand's PDP create predictable offtake pathways for independent power producers seeking long-term revenue visibility.
- Industrial estate carbon commitments:Factory clusters in the Eastern Economic Corridor are executing direct renewable power purchase agreements to satisfy Scope 2 emission reduction targets.
- Low-to-moderate wind regime optimization:Turbine OEMs are deploying 120-meter-plus rotor configurations specifically engineered for Thailand's wind speed profile, unlocking previously marginal sites.
Market Restraints
- Import dependency for nacelle assemblies:Thailand lacks domestic manufacturing capacity for turbine drivetrains, exposing projects to currency fluctuation and shipping queue risk.
- Transmission congestion in the Northeast:Grid interconnection queues in Nakhon Ratchasima and Chaiyaphum provinces are extending project energization timelines by 18-24 months.
- Land-use restriction tightening:Agricultural zone protections and military radar clearance requirements are eliminating viable wind farm sites faster than new areas open.
Strategic Opportunities
- Offshore seabed assessment completion:Gulf of Thailand wind resource mapping by the Department of Marine and Coastal Resources will unlock floating foundation prospects beyond shallow coastal zones.
- Corporate PPA aggregation platforms:Energy service companies are bundling SME demand to create procurement pools large enough to underwrite utility-scale project finance.
- Domestic content requirement compliance:Local manufacturing partnerships for tower and foundation components qualify projects for tariff premiums under revised feed-in frameworks.
Industry Challenges
- Certified wind technician scarcity:The Global Wind Organisation training infrastructure in Thailand supports fewer than 200 annual certifications against project pipeline needs exceeding 500 technicians.
- Grid code compliance complexity:Energy Regulatory Commission frequency ride-through and voltage support standards require costly power electronics upgrades for older turbine models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Wind Energy Market |
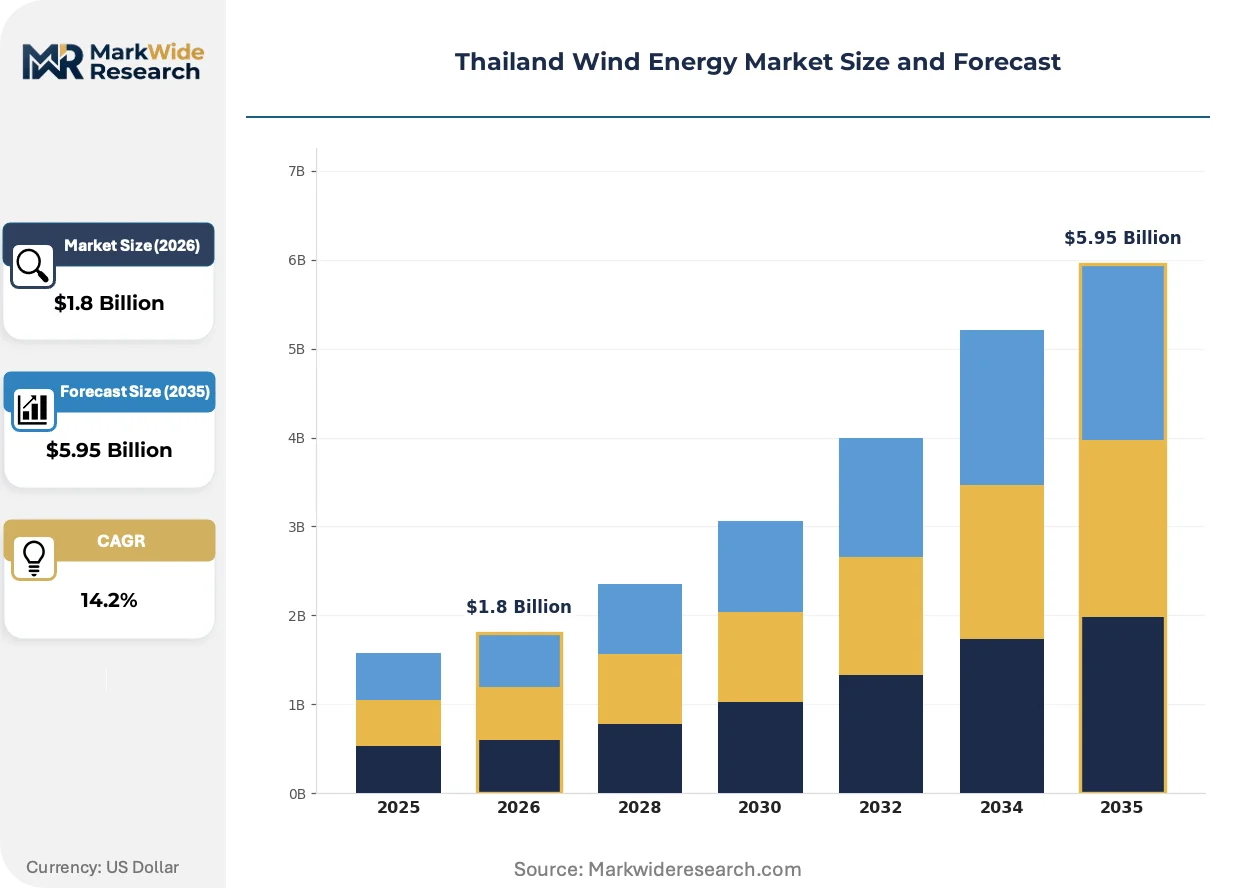
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Industrial Sector, Commercial, Residential Component: Turbine, Gearbox, Generator, Control System Installation: New Installation, Upgrades, Retrofits, Maintenance |
| Companies Covered | Electricity Generating PCL, Siemens Gamesa Renewable Energy SA, Wind Energy Holding Co Ltd, Gunkul Engineering, EGCO Group, Energy Absolute PCL, BCPG PCL, BayWa r.e., Gulf Energy Development PCL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Wind Energy Market Evolving Landscape
Technology maturation and procurement model experimentation are restructuring competitive advantage in Thailand's wind sector. Developers are prioritizing integrated service capabilities over equipment-only supply relationships.
Turbine scale-up is displacing sub-2 MW installations from the development pipeline. OEMs are promoting 4.5 MW platform configurations with 140-meter rotors for Thailand's wind regime. Industrial estate offtakers are specifying these larger units to minimize land footprint per megawatt contracted. This scale transition is displacing older turbine inventory and compressing balance-of-plant costs per installed kilowatt.
Thailand's Energy Regulatory Commission is revising grid connection standards to incorporate stricter fault ride-through requirements. These technical specifications mandate enhanced power converter capabilities for all new grid-tied capacity. Project developers are responding by specifying full converter turbine architectures in equipment tenders. The compliance burden falls heaviest on repowering candidates with doubly-fed induction generator legacy designs.
Direct corporate power purchase agreements are fragmenting traditional utility-centric procurement channels. Multinational manufacturers in Rayong and Chonburi industrial zones are negotiating 15-20 year renewable supply contracts independent of state utility tariffs. Financial institutions are developing non-recourse project finance structures tailored to these bilateral offtake arrangements. This buyer behavior shift is most pronounced among automotive and electronics exporters facing EU carbon border adjustment exposure.
Thailand Wind Energy Market Segmentation
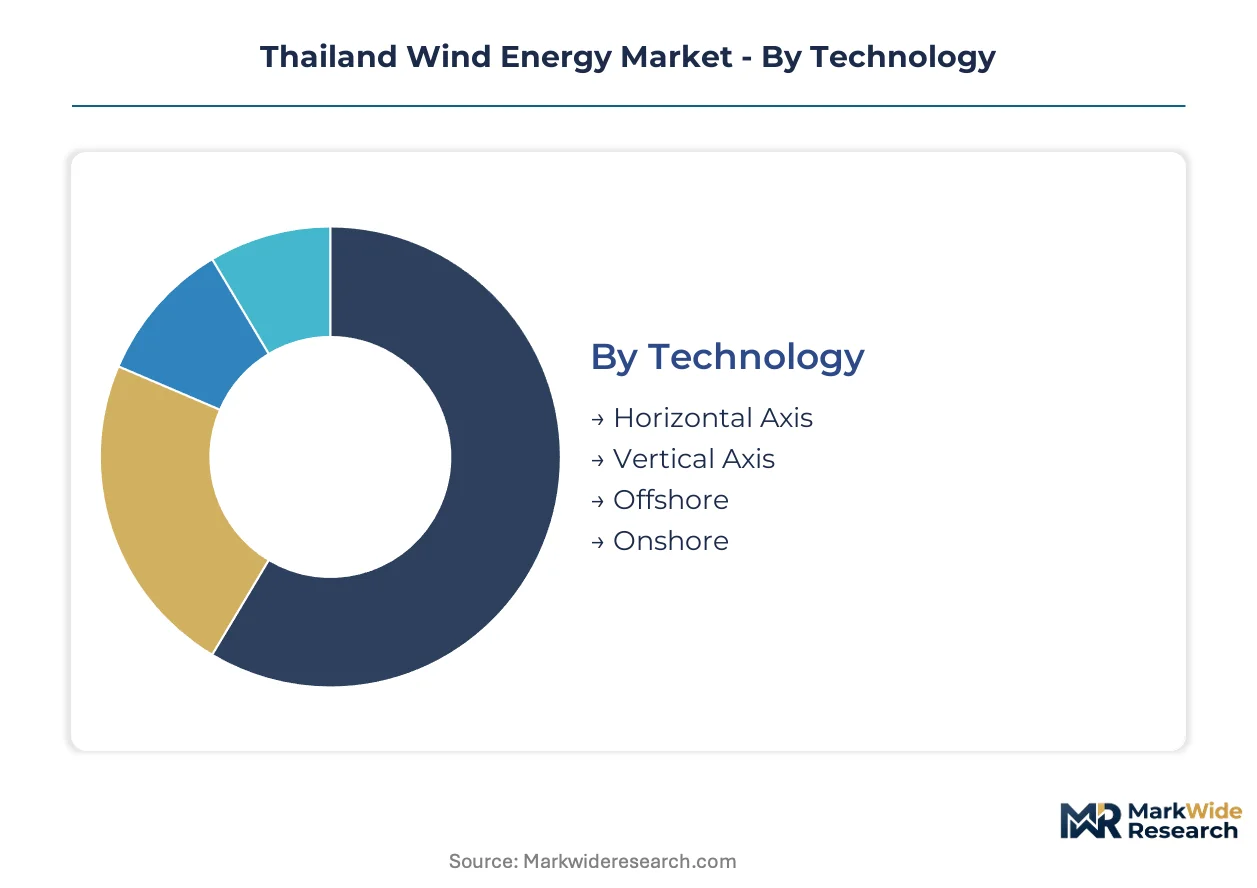
Thailand's wind energy market segments along four operational axes that determine project economics, procurement channels, and regulatory exposure. Each category reflects distinct buyer behaviors, technology maturity levels, and supply chain dependencies that shape competitive strategy.
Technology:
Domestic installations favor proven configurations with established local service networks, while export-oriented technology licensing targets regional Southeast Asian markets.
- Horizontal Axis:Rotor diameters exceeding 120 meters dominate operational capacity, with 2-4.5 MW ratings optimized for Thailand's low-to-moderate wind regime. Nakhon Ratchasima and Chaiyaphum provinces concentrate procurement of these units under revised feed-in tariff frameworks that reward higher capacity factors.
- Onshore:Land-based installations account for all current operational megawatts, with project pipelines clustering in northeastern transmission corridors. Grid interconnection queues in these provinces now extend 18-24 months, compressing developer returns and favoring integrated utility partnerships that can navigate regulatory clearance.
- Vertical Axis:Darrieus and Savonius configurations serve distributed micro-generation applications in remote agricultural zones where grid extension costs prove prohibitive.
- Offshore:Floating foundation prospects await completion of Gulf of Thailand seabed assessments by the Department of Marine and Coastal Resources.
Horizontal Axis holds the largest share; momentum sits with Onshore as transmission infrastructure expands.
End User:
Customer type determines contract structure, with bilateral corporate arrangements displacing traditional utility-tariff dependency among the largest buyers.
- Industrial Sector:Factory clusters in Rayong and Chonburi industrial zones negotiate 15-20 year direct power purchase agreements to satisfy Scope 2 emission targets and EU carbon border adjustment exposure. These buyers specify 4.5 MW turbine platforms to minimize land footprint per contracted megawatt.
- Utilities:State-affiliated offtakers procure through PDP-scheduled capacity auctions, offering long-term revenue visibility that supports non-recourse project finance. Electricity Generating PCL leverages integrated generation-transmission capabilities to secure preferential queue positions.
- Commercial:Office complexes and retail centers purchase bundled renewable energy certificates alongside physical power through energy service company intermediaries.
- Residential:Rooftop and small-scale community wind remains marginal due to distribution tariff structures that favor solar PV.
Utilities anchor current installed base; Industrial Sector climbs fastest as Eastern Economic Corridor carbon commitments harden.
Component:
Supply concentration varies sharply by subassembly, with domestic manufacturing limited to lower-technology components.
- Turbine:Nacelle assemblies remain import-dependent, exposing projects to currency fluctuation and shipping queue risk. Gunkul Engineering reduces this exposure through local tower and foundation partnerships that qualify for tariff premiums.
- Control System:Full converter architectures now dominate new tenders as Energy Regulatory Commission grid code revisions mandate enhanced fault ride-through capabilities.
- Gearbox:Drivetrain manufacturing lacks Thai domestic capacity, forcing reliance on European and Chinese OEM supply chains.
- Generator:Doubly-fed induction designs face obsolescence pressure from stricter power electronics standards.
Turbine captures dominant value share; Control System gains fastest as grid compliance burdens intensify.
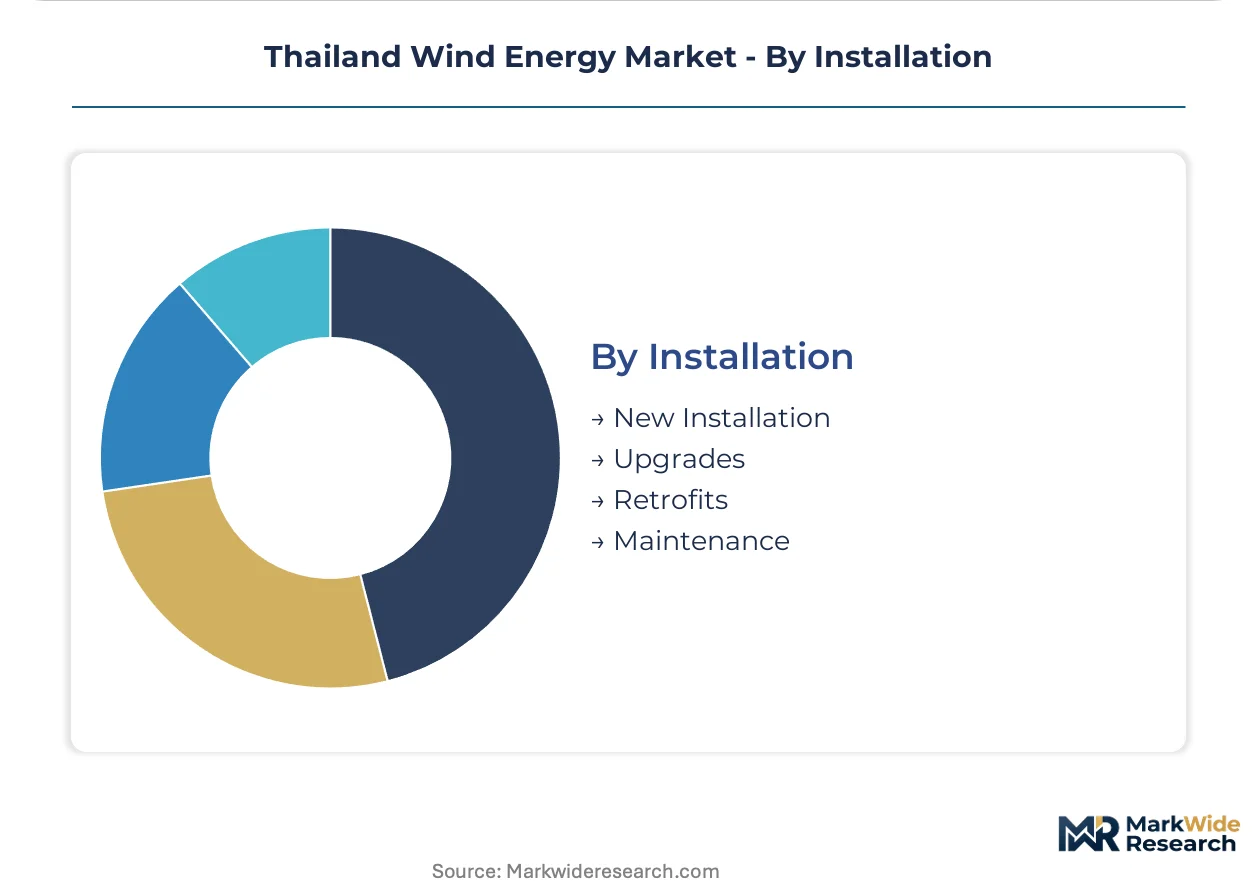
Installation:
Service revenue concentrates among OEM-affiliated technicians, though independent operators are penetrating maintenance segments.
- New Installation:Greenfield projects in Nakhon Ratchasima and Chaiyaphum face certified technician scarcity, with Global Wind Organisation training infrastructure supporting under 200 annual certifications against pipeline needs exceeding 500.
- Maintenance:Siemens Gamesa anchors its regional service hub in Thailand to capture recurring revenue from expanding Southeast Asian fleets.
- Upgrades:Power electronics retrofits address grid code compliance for operational assets with legacy converter designs.
- Retrofits:Repowering of sub-2 MW installations accelerates as larger rotor platforms unlock previously marginal sites.
New Installation commands largest revenue pool; Maintenance expands most quickly as operational fleet ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's wind consumption profile diverges sharply from neighbors: industrial estates in the Eastern Economic Corridor procure renewable electricity through bilateral corporate power purchase agreements, whereas Vietnam and the Philippines rely predominantly on utility-scheduled auctions and state-backed offtake.
Nakhon Ratchasima Province
Transmission-adjacent wind farms in this northeastern province capture the strongest pipeline of new project approvals under Thailand's revised feed-in tariff framework. The Department of Alternative Energy Development and Efficiency classifies this zone as a priority wind resource area, accelerating environmental clearance timelines. Grid interconnection queues here now extend 18-24 months, compressing developer returns and favoring integrated utility partnerships.
Chaiyaphum Province
Low-to-moderate wind regime optimization drives equipment selection in this neighboring northeastern province, with turbine OEMs deploying 140-meter rotor configurations specifically engineered for local wind speed profiles. Provincial land-use offices coordinate with military authorities on radar clearance requirements that have eliminated competing sites elsewhere. Agricultural zone protections here remain less restrictive than in central Thailand, preserving viable wind farm footprints.
Rayong Industrial Zone
Automotive and electronics exporters in this Eastern Economic Corridor hub negotiate 15-20 year direct renewable supply contracts to satisfy Scope 2 emission targets and EU carbon border adjustment exposure. Factory clusters specify 4.5 MW turbine platforms to minimize land footprint per contracted megawatt. The Energy Regulatory Commission governs grid connection standards for these bilateral arrangements.
Chonburi Industrial Zone
Multinational manufacturers in this adjacent Eastern Economic Corridor location execute corporate power purchase agreements independent of state utility tariffs. Energy service companies bundle SME demand to create procurement pools large enough to underwrite utility-scale project finance. The Ministry of Energy's Power Development Plan revisions shape long-term capacity auction schedules affecting regional supply security.
Gulf of Thailand Coastal Zone
Floating foundation prospects await completion of seabed assessments by the Department of Marine and Coastal Resources, with preliminary resource mapping indicating viable wind speeds beyond shallow coastal zones. Transmission infrastructure planning for offshore development remains nascent pending regulatory framework finalization. Coastal provinces including Phetchaburi and Prachuap Khiri Khan position for future lease rounds.
Thailand Wind Energy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-level competitive structure. Electricity Generating PCL leverages its utility affiliation to secure preferential transmission queue positions and long-term power purchase agreements. Specialist developers compete through local manufacturing partnerships that reduce import dependency and qualify for tariff premiums. Dominant competitive moves include strategic partnerships with turbine OEMs for service capabilities and backward integration into tower and foundation component production.
Within the integrated utility tier, Electricity Generating PCL and EGCO Group occupy positions that combine generation assets with transmission access advantages. Siemens Gamesa Renewable Energy SA anchors the equipment and service segment through its regional hub strategy. Among local engineering specialists, Gunkul Engineering exemplifies the domestic content compliance archetype through manufacturing partnerships that qualify projects for feed-in tariff premiums. Wind Energy Holding Co Ltd represents the independent developer model focused on greenfield project origination in northeastern transmission corridors.
| Leading Market Players |
|---|
| Electricity Generating PCL |
| Siemens Gamesa Renewable Energy SA |
| Wind Energy Holding Co Ltd |
| Gunkul Engineering |
| EGCO Group |
| Energy Absolute PCL |
| BCPG PCL |
| BayWa r.e. |
| Gulf Energy Development PCL |
| Others |
Value Network & Pricing Analysis
Capacity utilization at European and Chinese nacelle assembly plants shapes both supply concentration and price floors for Thai project developers. Feed-in tariff compression forces developers toward integrated utility partnerships that can absorb margin pressure through captive transmission access and preferential queue positioning.
Pricing Analysis
Long-term power purchase agreements dominate procurement, with bilateral corporate contracts commanding premium pricing over utility-scheduled auctions. Price differentiation stems from after-sales service bundling and domestic content certification levels that qualify projects for tariff premiums. Pricing pressure intensifies as feed-in tariff revisions compress developer margins and extend payback periods. Industrial estate offtakers exhibit lowest price sensitivity due to carbon compliance mandates, while independent power producers face acute margin pressure.
Supply Chain Analysis
China and Germany anchor nacelle and drivetrain manufacturing, with European OEMs supplying full-converter architectures for grid code compliance. Thailand sources tower and foundation components through local manufacturing partnerships, though gearbox and generator assemblies remain import-dependent. Single-source vulnerability concentrates in specialized power electronics and blade composites. Distribution runs through OEM-affiliated service hubs and EPC contractors with regional Southeast Asian project experience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as corporate PPA demand splinters procurement away from centralized utility auctions. Direct bilateral contracting enables specialist developers to bypass queue congestion through integrated industrial estate partnerships.
For Market Incumbents: Consolidate transmission queue positions through preferential grid interconnection agreements with Electricity Generating PCL and EGCO Group. Deepen backward integration into tower and foundation production to capture domestic content tariff premiums and offset nacelle import exposure. Defend against emerging corporate PPA aggregators by bundling energy service capabilities with physical generation assets.
For New Entrants and Emerging Players: Anchor in offshore wind prospecting as Gulf of Thailand seabed assessments unlock floating foundation opportunities beyond shallow coastal zones. Target SME demand aggregation through energy service company platforms that bundle procurement pools large enough to underwrite project finance. Pursue certification partnerships with Global Wind Organisation training providers to address technician scarcity constraining project timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated utility-affiliated developers with captive transmission access and long-term offtake visibility. Long-term viability centers on regulatory navigation capabilities and industrial estate relationship depth. Monitor feed-in tariff revision schedules and transmission queue clearance rates as inflection indicators for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Northeastern province expansion addresses industrial estate renewable demand under revised PDP schedules. |
| Power Purchase Agreement | Bilateral corporate contracts with Eastern Economic Corridor manufacturers secure 15-20 year revenue streams. |
| Technology Licensing | Full converter turbine architectures satisfy Energy Regulatory Commission fault ride-through mandates. |
| Backward Integration | Local tower and foundation production qualifies projects for domestic content tariff premiums. |
| Green Certification Program | Global Wind Organisation technician training addresses pipeline needs exceeding current certification capacity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators; and secondary validation through Department of Alternative Energy Development and Efficiency filings, Energy Regulatory Commission grid codes, Power Development Plan revisions, and project development databases. Bottom-up installation forecasts triangulated against top-down capacity auction schedules.
Across the analysis window, the forecasting framework modeled segmentation dimensions including technology configuration, end-user contract structure, component supply tier, and installation service type. CAGRs derived from capacity auction pipelines, interconnection queue clearance rates, and industrial estate demand aggregation trends. Inputs incorporated feed-in tariff revision schedules and domestic content requirement compliance thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained PDP auction schedules and transmission infrastructure expansion timelines; material deviation in regulatory frameworks or grid investment priorities would warrant model refresh. Recalibration cycles align with material shifts in Power Development Plan revisions and feed-in tariff framework updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Canada Wind Energy Market